
 Global Hydrophobic Coating Market | 2026-2036
Global Hydrophobic Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrophobic Coating Market Foresight
Performance-grade fluoropolymer specifications is unwinding across the Global Hydrophobic Coating Market as buyers prioritize durability over cost. BASF SE leverages its polymer science depth to sustain high-barrier formulations for automotive OEMs. PPG Industries anchors North American supply through integrated resin-to-coating production. 3M Company differentiates via proprietary nanoparticle platforms that command premium positioning in electronics applications.
Hydrophobic coatings are thin-film surface treatments engineered to achieve water contact angles exceeding 90 degrees, typically formulated with silane-modified polymers or fluorinated compounds via sol-gel or chemical vapor deposition processes. These coatings repel moisture, contaminants, and corrosive media to extend substrate life in harsh operating environments. Fluoropolymer formulations retain the largest value share due to their extreme chemical inertness and thermal stability, though nanoparticle-based systems represent the fastest-expanding category as manufacturers seek to balance performance with reduced environmental persistence. Sol-gel technology leads volume deployment for its ambient-temperature processing and substrate versatility across construction glass and consumer electronics.
REACH restrictions on long-chain perfluorinated substances are reshaping formulation roadmaps across European supply chains, while EPA oversight of fluoropolymer manufacturing emissions tightens compliance costs in the United States. China's GB standards for volatile organic compound content in industrial coatings are accelerating waterborne and low-VOC hydrophobic system development for domestic electronics and automotive sectors. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and maintain cross-border formulation compatibility.
Market Dynamics
REACH restrictions on long-chain perfluorinated substances are forcing formulators to rebuild supply chains around fluorine-free chemistries, while China's EV and electronics manufacturing concentrates demand for sol-gel nanoparticle systems in a handful of coastal provinces.
Growth Catalysts
- EU Green Deal chemical phase-outs:The F-Gas Regulation and REACH restrictions on PFAS are accelerating R&D investment in silicone and silane-modified alternatives across German and French coating clusters.
- Automotive sensor protection:LiDAR and camera module manufacturers in Japan and South Korea are specifying hydrophobic coatings to maintain optical clarity through automated vehicle wash cycles and road spray exposure.
- Sol-gel ambient processing:The technology's room-temperature curing eliminates thermal damage to temperature-sensitive substrates, expanding application into flexible electronics and polymer-based construction materials.
Market Restraints
- Fluoropolymer feedstock concentration:Virgin PTFE and PVDF resin supply concentrates among three multinational chemical producers, exposing coaters to price volatility and allocation risk during plant turnarounds.
- Durability-performance tradeoff:Fluorine-free alternatives currently achieve 60-70% of fluoropolymer service life in outdoor automotive applications, limiting specification in premium warranty programs.
- EPA emission controls:New source performance standards for fluoropolymer manufacturing add compliance capital expenditure and operating cost burdens at US production facilities.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device assembly are creating first-mover advantage for coating suppliers establishing technical service laboratories in Gujarat and Tamil Nadu.
- Photovoltaic module protection:Bifacial solar panel architectures require edge-seal and glass-surface hydrophobic treatments to prevent potential-induced degradation in humid climates.
- Waterborne formulation platforms:China's GB standards for VOC content are pushing domestic formulators toward aqueous dispersion technologies that reduce solvent handling and flash fire risk.
Industry Challenges
- Formulation chemist scarcity:Expertise in silane chemistry and nanoparticle dispersion stabilisation is concentrating among retiring specialists in European and Japanese industrial coating laboratories.
- Cross-jurisdiction compliance:Divergent substance notification requirements between EPA TSCA, REACH, and China's MEE create registration cost duplication and formulation version fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrophobic Coating Market |
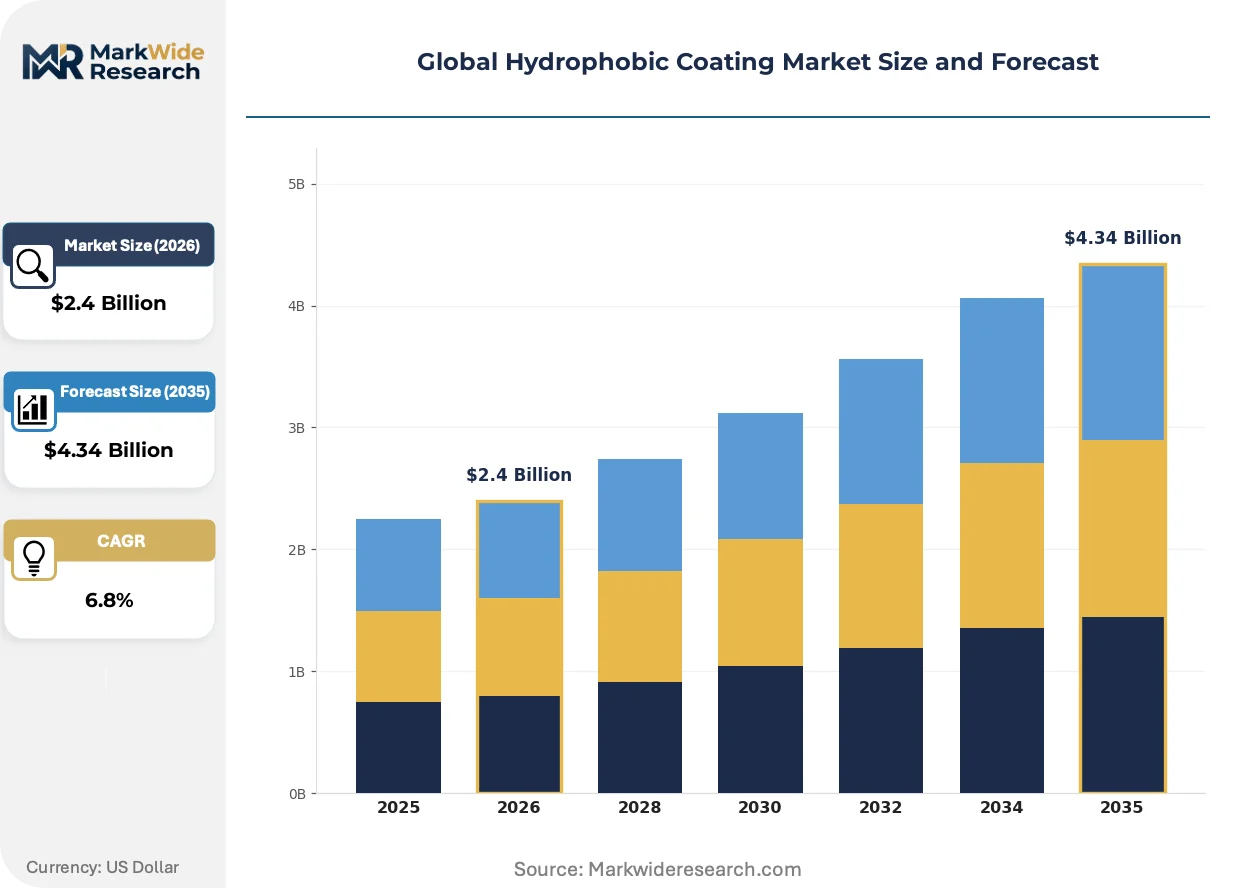
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Fluoropolymer, Nanoparticles, Acrylic, Epoxy, Polyurethane Application: Electronics, Automotive OEMs, Construction, Textile Manufacturing, Packaging, Marine Equipment Technology: Sol-Gel, Chemical Vapor Deposition, Plasma Treatment, Spray Coating, Dip Coating, Electrospinning End User Industry: Consumer Electronics, Aerospace, Oil & Gas, Food Processing, Heavy Equipment, Energy Development |
| Companies Covered | BASF SE, PPG Industries, 3M Company, AkzoNobel N.V., NEI Corporation, Nippon Paint Holdings Co., Ltd, The Sherwin-Williams Company, Dow Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrophobic Coating Market Shifts & Advancements
Formulation science is splitting along performance-versus-sustainability fault lines as regulatory pressure compounds technical tradeoffs. Three developments are restructuring competitive advantage.
Nanoparticle-reinforced sol-gel chemistry is bifurcating the mid-market segment. These systems combine silica or titania colloids with organosilane binders to achieve contact angles above 110 degrees without fluorine content. Electronics contract manufacturers in Taiwan and South Korea are qualifying these materials for smartphone and tablet display protection. The technology is compressing margins for conventional fluoropolymer suppliers in consumer-grade applications while opening volume pathways for aqueous-processable alternatives.
REACH Annex XVII restrictions on perfluorooctanoic acid and related substances are eliminating legacy fluorotelomer-based formulations from European supply chains. Industrial coaters must reformulate with short-chain fluoropolymers or abandon fluorine chemistry entirely for certain applications. German automotive OEMs are driving the tightest specifications, rejecting coatings with detectable long-chain residuals regardless of performance equivalence.
Automotive OEMs are consolidating coating specifications under centralized materials engineering functions, displacing regional purchasing autonomy. Tier-1 suppliers now face qualification requirements spanning multiple assembly plants and climate zones simultaneously. This concentration is most visible in China, where domestic EV manufacturers are adopting unified global material lists that mirror European and North American parent company standards.
Global Hydrophobic Coating Market Segmentation
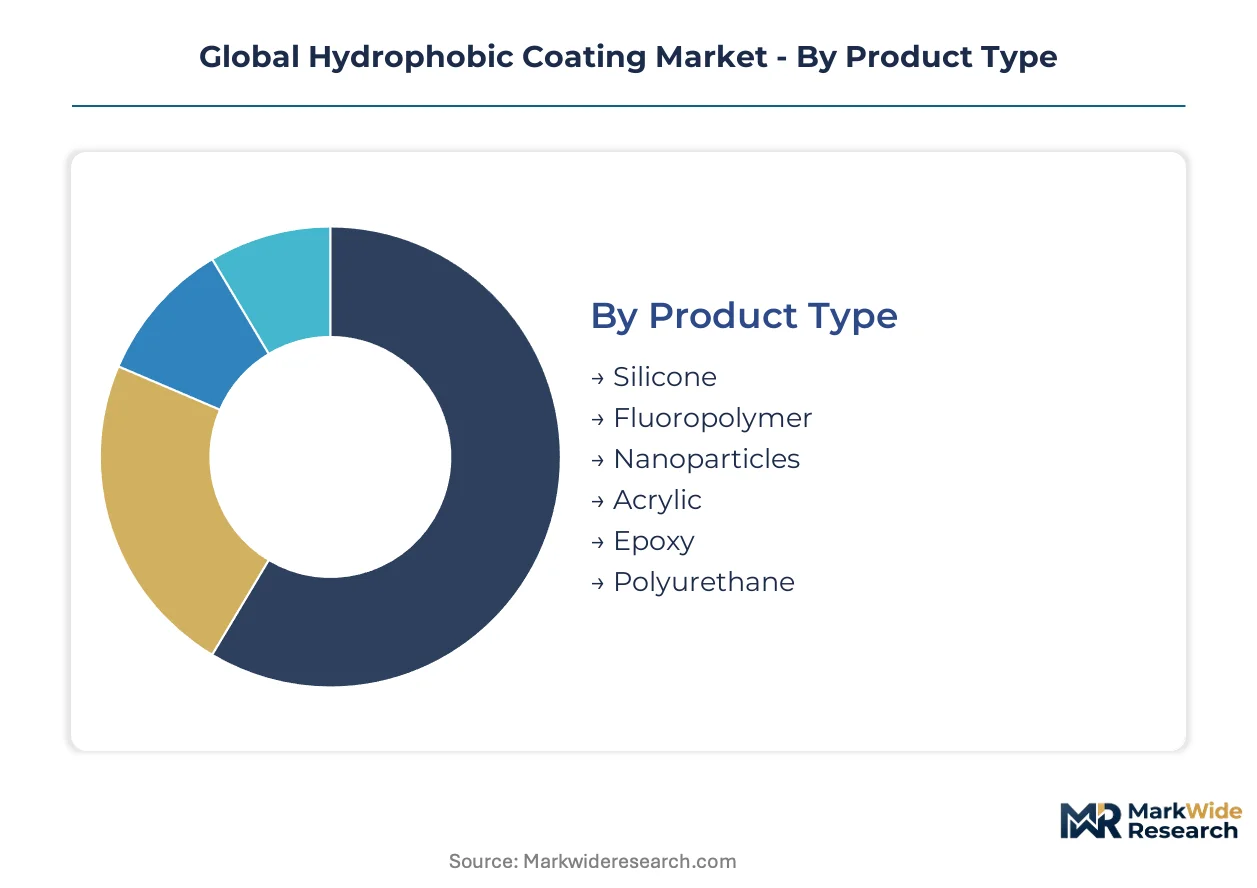
Segmentation in hydrophobic coatings reveals how formulation chemistry, application method, and end-use requirements intersect to determine procurement channels. Channel mix varies sharply by segment, with automotive OEMs and electronics contract manufacturers consolidating specifications through direct technical partnerships while construction and textile applications flow through distributor networks.
Product Type:
Channel distribution splits sharply between specification-driven direct sales for high-performance grades and distributor-mediated procurement for commodity formulations.
- Fluoropolymer:PTFE and PVDF-based systems deliver contact angles exceeding 120 degrees alongside thermal stability above 260°C. German automotive OEMs specify these coatings for underhood components and sensor housings, though REACH Annex XVII restrictions on long-chain perfluorinated substances are forcing reformulation timelines. Fluoropolymer formulations dominate installed base. Nanoparticles is where expansion concentrates.
- Nanoparticles:Silica and titania colloids dispersed in organosilane matrices achieve water repellency without fluorine content. Electronics contract manufacturers in Taiwan and South Korea are qualifying these systems for smartphone display protection to meet EU import compliance. These systems are gaining share fastest among sustainability-conscious buyers.
- Silicone:Polysiloxane-based coatings offer moderate hydrophobicity with ambient curing and lower cost structures. Construction glass processors in China specify silicone systems for building facade treatments under GB standards for VOC content.
- Acrylic:Waterborne acrylic dispersions provide entry-level moisture protection for packaging and consumer goods applications. Food processing equipment manufacturers favor these coatings for their regulatory acceptance and ease of reapplication.
- Epoxy:Two-part epoxy systems combine hydrophobicity with mechanical toughness for heavy equipment and marine applications. Oil and gas operators specify epoxy formulations for subsea connector protection.
- Polyurethane:Aliphatic polyurethane coatings balance flexibility with UV resistance for textile and flexible electronics substrates. Marine equipment fabricators in Japan specify polyurethane systems for inflatable vessel coatings.
Margin structures compress from fluoropolymer through polyurethane tiers, with nanoparticle systems commanding premium positioning despite lower raw material costs.
Application:
Cost tier segmentation separates warranty-backed automotive and aerospace specifications from price-sensitive construction and packaging procurement.
- Automotive OEMs:Exterior body panels, sensor modules, and underhood components require coatings that survive automated wash cycles and thermal cycling. LiDAR manufacturers in Japan specify hydrophobic optical clarity coatings to maintain performance through road spray exposure.
- Electronics:Smartphone displays, circuit boards, and wearable devices demand ultra-thin films that preserve touch sensitivity. South Korean contract manufacturers are consolidating specifications under parent company global material lists.
- Construction:Building glass, concrete sealers, and roofing membranes utilize sol-gel and spray-applied systems. Chinese provincial infrastructure projects drive volume procurement through state-owned contractor channels.
- Textile Manufacturing:Performance apparel and industrial fabrics require breathable hydrophobic treatments. European outdoor brands are shifting from fluorinated to silicone-based finishes under ECHA restrictions.
- Packaging:Corrugated board and flexible film treatments prevent moisture damage during cold chain distribution. Food exporters in India specify coatings meeting FSSAI contact material requirements.
- Marine Equipment:Hull coatings, deck treatments, and inflatable structures face salt spray and UV degradation. UAE shipyards specify systems certified by the country's maritime authority for superyacht construction.
Automotive OEMs and Electronics concentrate specification authority. Construction and Packaging flow through price-negotiated distributor contracts.
Technology:
Volume deployment favors ambient processing methods that eliminate thermal damage to sensitive substrates.
- Sol-Gel:Hydrolysis and condensation of metal alkoxides produce transparent ceramic-organic hybrid films at room temperature. Electronics manufacturers in China deploy sol-gel lines for high-throughput smartphone display coating.
- Chemical Vapor Deposition:Gas-phase precursor reactions create conformal nanometer-scale films on complex geometries. Aerospace component suppliers specify CVD for turbine blade and sensor protection.
- Plasma Treatment:Low-temperature plasma activation prepares surfaces and deposits functional coatings without liquid handling. German automotive tier-1 suppliers integrate plasma systems into just-in-sequence manufacturing cells.
- Spray Coating:Conventional atomized application dominates construction and marine field applications. Indian shipyards specify spray systems for on-vessel maintenance and repair.
- Dip Coating:Immersion methods provide uniform coverage for complex shapes in batch processing. Oil and gas valve manufacturers utilize dip lines for subsea component treatment.
- Electrospinning:Electric field-driven fiber formation creates superhydrophobic membranes for filtration and biomedical applications. Japanese research consortia are scaling electrospun coatings for next-generation battery separators.
Sol-Gel and Spray Coating dominate installed capacity. Chemical Vapor Deposition is where technology investment concentrates.
End User Industry:
Customer type segmentation separates consolidated specification authority in Consumer Electronics and Aerospace from fragmented procurement in Food Processing and Heavy Equipment.
- Consumer Electronics:Brand owners and contract manufacturers specify coatings for smartphones, tablets, and wearables. Apple and Samsung supplier qualification programs drive coating chemistry roadmaps across Asian supply chains.
- Aerospace:Airframe, engine, and avionics applications demand coatings surviving extreme thermal and pressure cycles. FAA certification requirements constrain formulation changes and supplier switching.
- Oil and Gas:Downhole tools, subsea infrastructure, and pipeline coatings must resist corrosive hydrocarbon environments. Saudi Aramco technical specifications influence coating selection across Middle Eastern procurement.
- Food Processing:Equipment hygiene requirements favor coatings with regulatory acceptance for incidental food contact. European processors specify systems meeting EFSA migration limits.
- Heavy Equipment:Construction and mining machinery requires abrasion-resistant hydrophobic treatments. Caterpillar and Komatsu supplier networks standardize coating specifications across global manufacturing footprints.
- Energy Development:Wind turbine blades and photovoltaic modules need edge protection and anti-soiling surfaces. Chinese solar panel manufacturers specify hydrophobic glass treatments for bifacial module architectures.
Consumer Electronics and Aerospace concentrate specification power. Food Processing and Heavy Equipment fragment across regional equipment builders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German formulators export high-barrier fluoropolymer systems to automotive OEMs in Japan and South Korea, while Chinese sol-gel producers supply contract manufacturers across Taiwan and Vietnam for consumer electronics protection.
China
Domestic EV manufacturers and electronics contract manufacturers drive concentrated procurement of nanoparticle-based sol-gel systems in Jiangsu and Guangdong provinces. The country's MEE enforces GB standards for VOC content that accelerate waterborne formulation development. Shenzhen and Suzhou industrial clusters host high-throughput coating lines serving smartphone display and automotive sensor module production.
Germany
Automotive OEMs in Stuttgart and Munich specify REACH-compliant short-chain fluoropolymer coatings for underhood components and LiDAR housings. The EU F-Gas Regulation and REACH Annex XVII restrictions eliminate legacy fluorotelomer formulations from supply chains. The Rhine-Ruhr chemical corridor anchors reformulation R&D for silicone and silane-modified alternatives.
United States
Aerospace component suppliers and oil and gas operators specify CVD-applied coatings for turbine blades and subsea infrastructure in Texas and Louisiana. EPA new source performance standards for fluoropolymer manufacturing add compliance costs at Gulf Coast production facilities. Houston hosts technical service laboratories serving Aramco-influenced Middle Eastern procurement specifications.
Japan
LiDAR and camera module manufacturers in Nagoya and Osaka specify hydrophobic optical clarity coatings for automated vehicle wash cycle survival. METI industrial standards guide coating qualification protocols for automotive tier-1 suppliers. The Kansai region concentrates plasma treatment system integration into just-in-sequence manufacturing cells.
South Korea
Samsung and LG supplier qualification programs consolidate coating specifications for smartphone and wearable device protection in Gyeonggi-do. The MFDS regulates incidental food contact applications for processing equipment coatings. The Seoul Capital Area hosts electronics contract manufacturers adopting unified global material lists mirroring European parent company standards.
Global Hydrophobic Coating Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry depth and geographic coverage. The vendor base splits between multinational chemical conglomerates with integrated resin capabilities and regional coating specialists with application-specific expertise. Three archetypes dominate: polymer science majors with captive raw material supply, application engineering specialists with plasma and CVD system integration, and aqueous formulation innovators serving electronics compliance requirements. Competitive moves concentrate on fluorine-free R&D partnerships and technical service laboratory expansion into high-growth manufacturing clusters.
Within the polymer science tier, BASF SE and Dow Inc. exemplify integrated players with backward control over silane and fluoropolymer precursor supply. PPG Industries occupies a position among North American coaters with resin-to-coating production integration. 3M Company represents the nanoparticle platform specialist archetype, anchoring premium positioning in electronics applications through proprietary colloidal dispersion technologies.
| Leading Market Players |
|---|
| BASF SE |
| PPG Industries |
| 3M Company |
| AkzoNobel N.V. |
| NEI Corporation |
| Nippon Paint Holdings Co., Ltd |
| The Sherwin-Williams Company |
| Dow Inc. |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for fluoropolymer resins lock in supply access for automotive OEMs while capping price visibility against spot volatility in virgin PTFE feedstock markets. These arrangements concentrate procurement leverage among German and Japanese coating formulators with backward integration into silane precursor production.
Pricing Analysis
Next-generation nanoparticle-reinforced sol-gel systems command 40-60% premiums over prior-generation silicone formulations, while legacy fluoropolymer grades face compression from REACH-driven substitution. Pricing stratifies across premium, standard, and economy tiers keyed to certification grade and thermal stability specifications. Cost compression in fluorine-free alternatives is intensifying as Chinese electronics contract manufacturers consolidate specifications under unified global material lists. Construction and packaging buyers exhibit highest price sensitivity, while aerospace and automotive sensor module procurement tolerates premium positioning for warranty-backed performance.
Supply Chain Analysis
China and Germany anchor hydrophobic coating production, with Chinese sol-gel specialists supplying electronics contract manufacturers across Taiwan and Vietnam while German formulators export high-barrier fluoropolymer systems to Japanese automotive OEMs. The supply chain draws from concentrated virgin PTFE and PVDF resin production, organosilane precursors, and specialized nanoparticle dispersions. Single-source vulnerability in fluoropolymer feedstock exposes coaters to allocation risk during multinational chemical producer plant turnarounds. Distribution runs through direct technical partnerships for automotive and electronics specifications, with construction and marine applications flowing through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and application engineering layers expand faster than base coating sales as automotive OEMs consolidate qualification requirements across multiple assembly plants and climate zones simultaneously.
For Market Incumbents: Fortify backward integration into silane and nanoparticle precursor supply to defend margin position against fluorine-free substitution pressure. Prioritize certification investment for REACH-compliant short-chain fluoropolymer and silicone-modified alternatives. Capacity addition in Jiangsu and Guangdong provinces captures Chinese EV and electronics manufacturing concentration. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized semiconductor and mobile device assembly clusters, where first-mover technical service laboratories in Gujarat and Tamil Nadu secure qualification pathways before incumbent laboratory expansion. Target photovoltaic module protection as the most penetrable segment, with bifacial solar panel architectures requiring edge-seal and glass-surface hydrophobic treatments. Pursue aqueous dispersion platform partnerships with domestic formulators facing China's GB standards for VOC content. For Investors and Strategic Acquirers: Capital is best deployed toward application engineering specialists with plasma and CVD system integration capabilities, as automotive OEM specification consolidation favors technical service depth over commodity formulation scale. Long-term viability hinges on fluorine-free R&D partnerships and cross-jurisdiction registration expertise. The signal to watch is German automotive OEM rejection of coatings with detectable long-chain residuals regardless of performance equivalence.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Formulation Partnership | REACH Annex XVII restrictions eliminate legacy fluorotelomer-based systems from European supply chains. |
| Technical Service Laboratory Expansion | Gujarat and Tamil Nadu PLI incentives create first-mover advantage for coating qualification in Indian electronics manufacturing. |
| Backward Integration into Precursor Supply | Captive silane and nanoparticle production defends margin compression from fluoropolymer feedstock volatility. |
| Aqueous Dispersion Platform Development | China's GB standards for VOC content accelerate waterborne system adoption in domestic electronics and automotive sectors. |
| Cross-Jurisdiction Registration Investment | Divergent EPA TSCA, REACH, and China's MEE requirements create compliance cost duplication without unified formulation strategies. |
Research Methodology
The analysis maps fluoropolymer, nanoparticle, silicone, and sol-gel formulation sub-sectors, each validated through technical R&D directors at coating formulators, procurement leads at automotive OEMs and electronics contract manufacturers, and distribution channel partners across construction and marine applications. Primary interview insights triangulate against secondary validation from SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and regulatory filings with ECHA and EPA. Bottom-up volume modeling across application segments reconciles with top-down value estimates derived from disclosed capacity and pricing benchmarks.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation across chemistry type, application method, end-use industry, and regional production hub. CAGRs derive from segment-level growth rate reconciliation with macroeconomic drivers and industry-specific demand indicators including EV production forecasts, electronics assembly volumes, and solar panel deployment trajectories.
Material uncertainties — regulatory acceleration of PFAS phase-outs, feedstock allocation disruptions, and specification consolidation by automotive OEMs — sit outside the modeled envelope. Forecasts reflect assumptions about reformulation timelines and qualification protocol durations. Recalibration cycles align with material shifts in REACH restriction schedules and Chinese GB standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Solvent Borne Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Topcoat Market
Coatings
Automotive Refinish Coatings Market
Coatings
Hard Coating Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Global Sputter Coater Market
Coatings
Epoxy Surface Coatings Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Epoxy Coating Market
Coatings
Coatings and Fillings Market