
 North America Epoxy Powder Coatings Market | 2026-2036
North America Epoxy Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Epoxy Powder Coatings Market Analytics
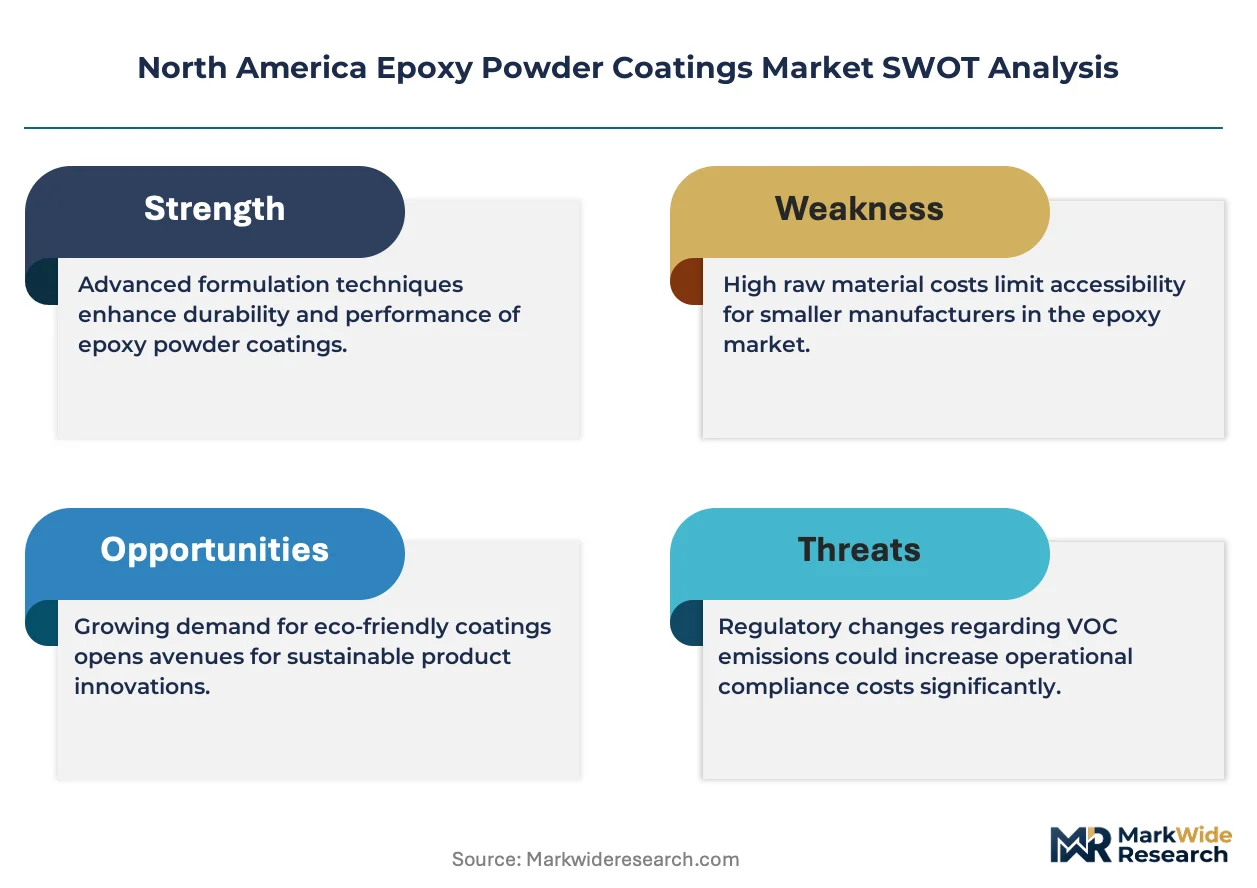
ISO 9001 certification is collapsing as a baseline qualifier, forcing suppliers to pursue IATF 16949 and AAMA 2604 credentials to retain automotive and architectural accounts. Akzo Nobel N.V. leverages its marine coatings heritage to anchor epoxy powder formulations for corrosion-intensive infrastructure. PPG Industries, Inc. sustains R&D intensity across thermosetting and low-cure portfolios. The Sherwin-Williams Company dominates distribution density through its North American branch network.
Epoxy powder coatings are thermosetting polymer systems formulated from bisphenol-A epichlorohydrin resins, cured at 150–200°C to form dense, chemically resistant films for metal substrates. They deliver dielectric insulation, corrosion barrier, and mechanical durability across industrial, automotive, and architectural metal finishing. Hybrid and pure epoxy formulations lead volume, with hybrid grades capturing margin pools in appliance and furniture segments where cost-performance balance governs procurement. Thermosetting chemistry occupies the technology core, while high-cure systems face displacement pressure from low-cure alternatives that reduce energy intensity in OEM finishing lines.
EPA NESHAP standards for hazardous air pollutants constrain conventional liquid coating operations, redirecting capital toward powder systems in metal fabrication. OSHA permissible exposure limits for isocyanates and volatile organic compounds reinforce workplace safety-driven conversion from solvent-based processes. AAMA 2604 and AAMA 2605 performance specifications set color retention and chalking thresholds that filter architectural-grade suppliers. Stakeholders must monitor how California Air Resources Board rulemaking on industrial coatings spreads to other state implementations.
Market Dynamics
Automotive OEMs are accelerating low-cure epoxy powder adoption to slash energy costs in paint lines while EPA NESHAP enforcement tightens compliance thresholds for solvent-based alternatives across metal fabrication corridors.
Growth Catalysts
- OSHA Permissible Exposure Limits:Workplace safety mandates for isocyanates and volatile organic compounds are forcing metal fabricators to convert solvent-based finishing lines to powder systems.
- US Gulf Coast Petrochemical Corridor:Concentrated industrial infrastructure investment is generating sustained demand for corrosion-resistant pipeline and tank coatings.
- Mexican Automotive Manufacturing Clusters:OEM expansion in Querétaro and Guanajuato is pulling dedicated powder coating capacity across the border.
Market Restraints
- Bisphenol-A Feedstock Volatility:Epoxy resin pricing fluctuates with benzene and propylene supply disruptions from Gulf Coast refineries.
- High-Cure System Obsolescence:Legacy 180–200°C cure schedules face displacement as OEMs prioritize 120–150°C alternatives to reduce natural gas consumption.
- Substitute Coating Technologies:UV-curable liquid coatings are capturing share in thin-film electronics and furniture applications where powder film builds exceed specification.
Strategic Opportunities
- California Air Resources Board Rulemaking:Pending industrial coating standards in California typically propagate to Northeast and Midwest state implementations within 24–36 months.
- Electric Vehicle Battery Enclosure Coatings:Dielectric epoxy formulations are penetrating new thermal management and electrical isolation applications in EV underbody assemblies.
- Direct-to-Installer Digital Platforms:Regional distributors are bypassing traditional branch networks to serve mid-size metal fabricators through e-procurement portals.
Industry Challenges
- IATF 16949 Certification Timelines:Automotive suppliers face 12–18 month qualification periods to meet OEM coating specification requirements.
- Legacy Liquid Line Conversion Capex:Metal fabricators must deploy spray booths, reclaim systems, and cure ovens totaling substantial capital outlays.
- Formulation Chemist Talent Scarcity:Thermosetting polymer expertise is concentrating among aging workforce cohorts with limited pipeline replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Epoxy Powder Coatings Market |
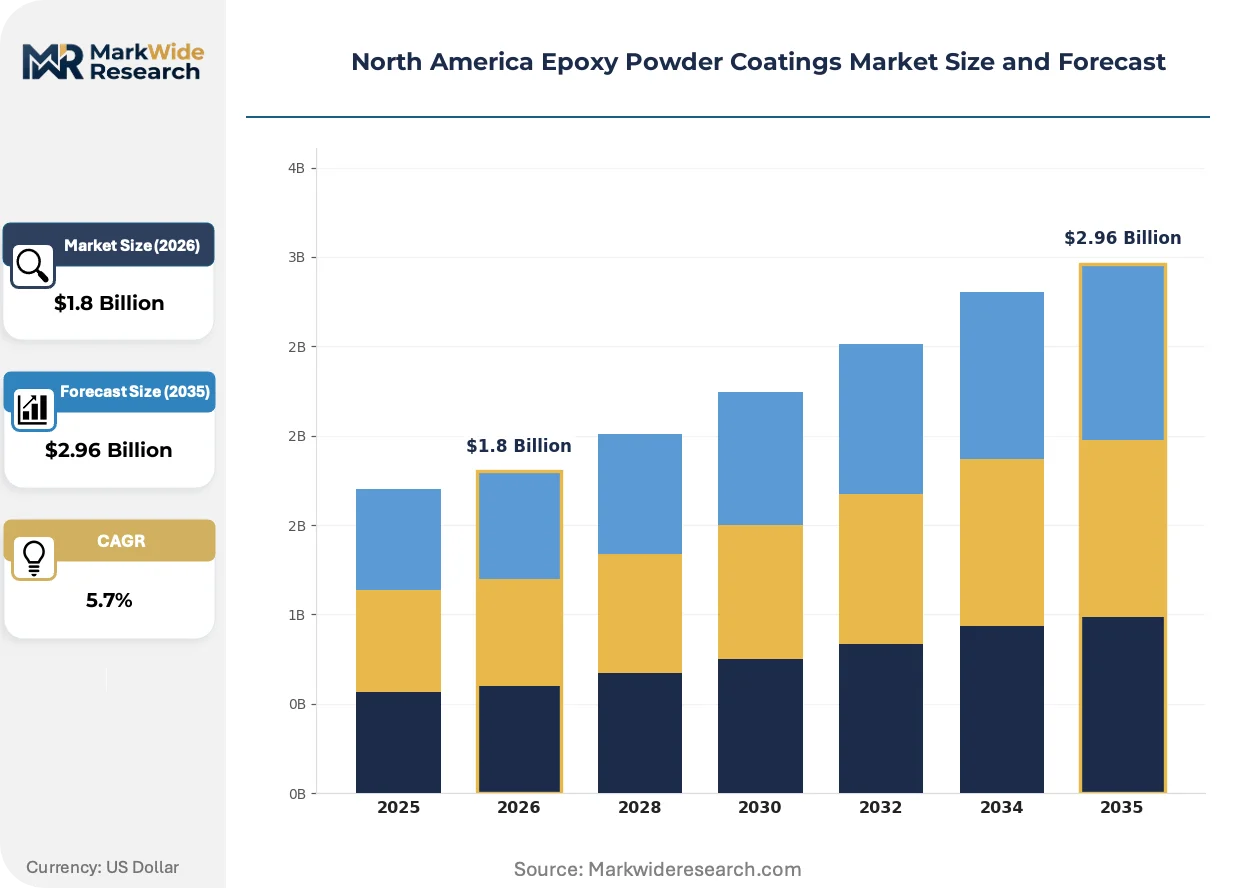
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
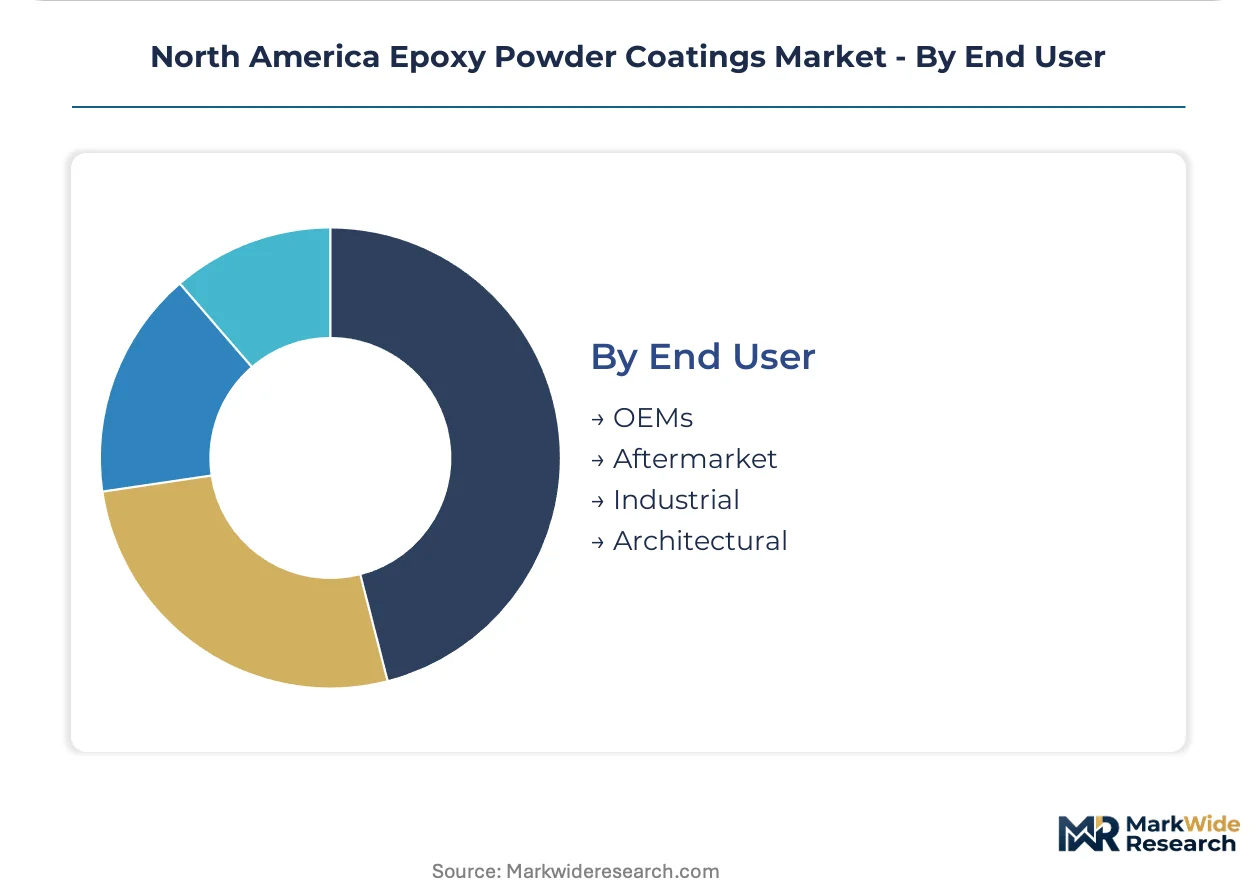
| Segmentation | Product Type: Polyester, Hybrid, Pure Epoxy, Epoxy Phenolic Application: Automotive, Appliances, Furniture, Construction Formulation Type: Thermosetting, Thermoplastic, Low Cure, High Cure End User: OEMs, Aftermarket, Industrial, Architectural |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun, 3M, Axalta Coating Systems, BASF SE, RPM International Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Epoxy Powder Coatings Market Evolving Landscape
Formulation chemistry is diverging along cure-temperature and resin-backbone axes as end-users prioritize energy efficiency and specialized performance envelopes over commodity-grade interchangeability.
Low-cure epoxy-hybrid systems are fragmenting the traditional thermosetting hierarchy by enabling 120–150°C cure schedules that slash natural gas consumption in continuous coil coating and batch finishing operations. Appliance manufacturers and automotive tier suppliers are piloting these formulations at scale. The technology is fragmenting procurement patterns as buyers bifurcate specifications between energy-optimized and legacy high-performance grades.
EPA NESHAP standards for hazardous air pollutants are compressing operational windows for conventional liquid coating operations in metal fabrication and industrial machinery sectors. Compliance deadlines are redirecting capital expenditure toward powder system conversions. Fabricators in Ohio, Michigan, and Indiana are accelerating booth installations ahead of enforcement phase-ins.
Specification-driven procurement is consolidating supplier relationships around AAMA 2604 and AAMA 2605 certified coating systems for architectural metal finishing. Architects and glazing contractors are narrowing approved vendor lists to pre-qualified sources with documented color retention and chalking performance. The shift is most pronounced in Florida and Texas commercial construction markets where warranty terms govern coating selection.
North America Epoxy Powder Coatings Market Segmentation
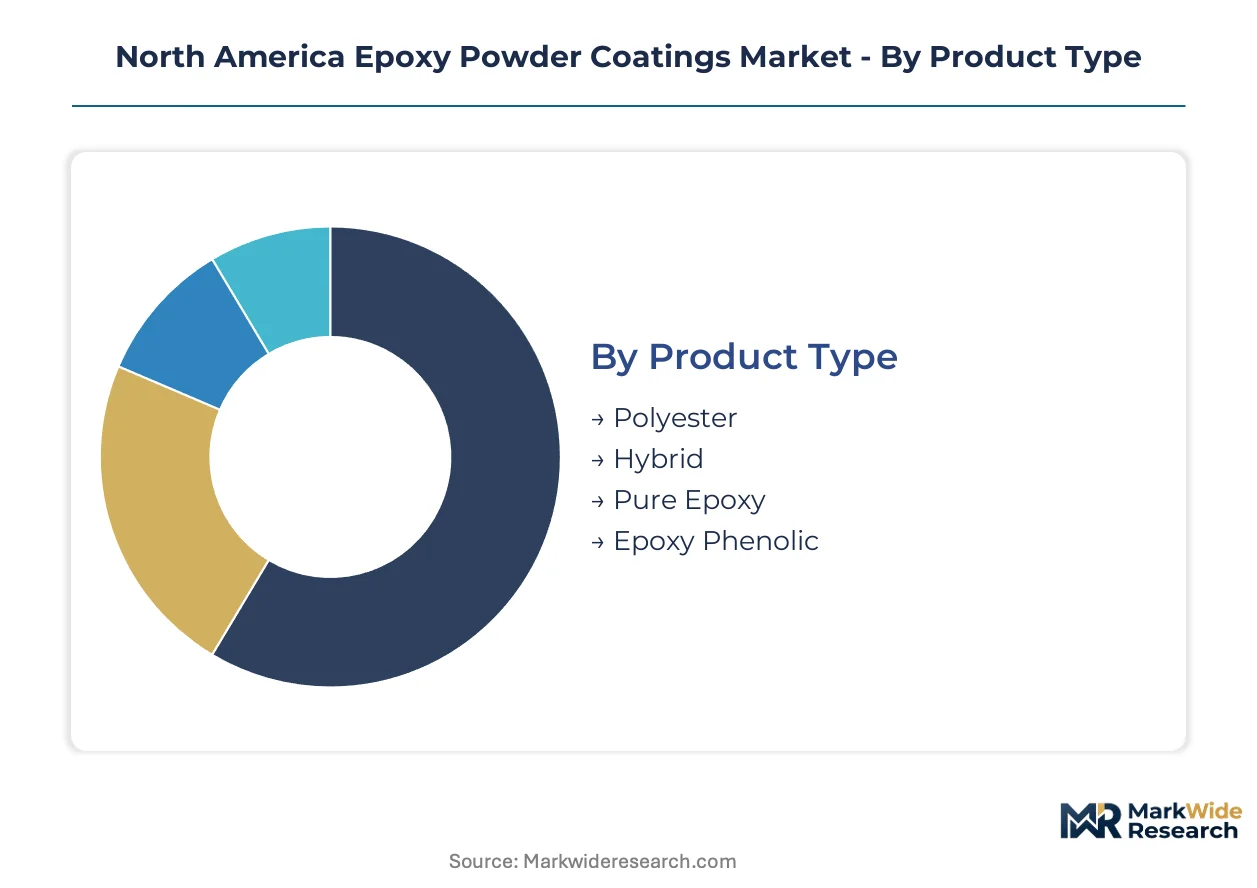
Epoxy powder coatings procurement in North America fragments across resin chemistry, cure kinetics, and end-use performance thresholds. Specification engineers weight AAMA 2604 color retention against IATF 16949 automotive qualification timelines when segmenting supplier shortlists.
Product Type:
EPA NESHAP enforcement on hazardous air pollutants has reordered formulation preferences as fabricators abandon solvent-based liquid systems for compliant powder alternatives.
- Hybrid:Epoxy-polyester hybrid systems balance chemical resistance with UV stability for outdoor architectural and appliance applications. Appliance manufacturers in the US Midwest specify hybrid grades for refrigerator and washer-dryer cabinets where cost-performance optimization governs procurement.
- Pure Epoxy:Bisphenol-A epichlorohydrin resins cure to dense, chemically resistant films delivering dielectric insulation and corrosion barrier performance. Pipeline operators across the US Gulf Coast petrochemical corridor specify pure epoxy for tank internals and subsea infrastructure where immersion resistance is non-negotiable.
- Polyester:Saturated polyester backbone formulations dominate exterior architectural metal finishing with superior gloss retention.
- Epoxy Phenolic:Modified phenolic crosslinkers extend chemical resistance for tank lining and process equipment applications.
Hybrid formulations handle the majority of throughput; pure epoxy is gaining share fastest in corrosion-intensive infrastructure.
Application:
Customer procurement patterns diverge sharply between specification-driven architectural projects and cost-optimized appliance runs.
- Automotive:Under-hood components, chassis assemblies, and EV battery enclosures demand dielectric epoxy formulations with thermal management properties. OEMs in Querétaro and Guanajuato manufacturing clusters are pulling dedicated powder coating capacity across the Mexican border to serve tier supplier networks.
- Appliances:Batch finishing operations for refrigerator cabinets, washer drums, and dryer housings prioritize low-cure hybrid systems to compress natural gas consumption. Ohio and Indiana metal fabricators are accelerating booth installations ahead of EPA NESHAP enforcement phase-ins.
- Furniture:Metal office and outdoor furniture segments specify thin-film powder systems where UV-curable liquid alternatives compete on film build.
- Construction:Curtain wall, storefront, and roofing systems require AAMA 2604 or AAMA 2605 certified coatings with documented color retention warranties.
Automotive applications carry the steepest specification burden; appliance volumes dominate unit throughput.
Formulation Type:
Energy intensity in cure ovens has become the primary axis of technology displacement across OEM finishing lines.
- Low Cure:120–150°C cure schedules slash natural gas consumption in continuous coil coating and batch operations. Automotive tier suppliers and appliance manufacturers are piloting low-cure epoxy-hybrid formulations at scale to meet corporate sustainability targets.
- Thermosetting:Crosslinked polymer networks formed at 150–200°C deliver the mechanical durability and chemical resistance baseline for industrial metal finishing. This chemistry occupies the technology core but faces displacement pressure from energy-optimized alternatives.
- High Cure:Legacy 180–200°C schedules persist in corrosion-barrier applications where film density requirements resist reformulation.
- Thermoplastic:Linear polymer systems enable remelt and repair for specialty electrical insulation and functional coating applications.
Thermosetting systems anchor current installed base; low cure alternatives are expanding most quickly on new line investment.
End User:
Qualification timelines and warranty exposure separate procurement behavior across customer categories.
- OEMs:Automotive and appliance original equipment manufacturers impose IATF 16949 or equivalent quality system mandates with 12–18 month supplier qualification periods. Coating specifications lock in resin backbone, cure schedule, and performance testing protocols.
- Industrial:Metal fabricators serving machinery, agricultural equipment, and petrochemical infrastructure prioritize corrosion resistance and turnaround speed over color matching precision.
- Architectural:Glazing contractors and metal panel fabricators narrow approved vendor lists to AAMA-certified sources with documented Florida and Texas exposure testing.
- Aftermarket:Touch-up, repair, and refurbishment operations favor small-batch flexibility and rapid color matching over volume scale.
OEMs concentrate the highest specification value; industrial end users represent the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA NESHAP enforcement timelines and state-level air quality mandates are redirecting capital expenditure toward powder coating conversions across industrial corridors. Mexican automotive expansion and US Gulf Coast petrochemical investment anchor demand concentration. Cross-border supply chains now link coating formulation in Texas and Louisiana to tier supplier networks in Querétaro and Guanajuato.
United States
Automotive OEMs in Michigan and Ohio are accelerating low-cure epoxy powder adoption to compress natural gas consumption in paint lines. EPA NESHAP standards for hazardous air pollutants constrain conventional liquid coating operations across metal fabrication corridors. Fabricators in Indiana and Ohio are installing reclaim systems and cure ovens ahead of enforcement phase-ins.
Mexico
OEM expansion in Querétaro and Guanajuato manufacturing clusters is pulling dedicated powder coating capacity across the border from US suppliers. Mexican federal environmental regulations under SEMARNAT are tightening VOC emissions thresholds for industrial finishing operations. Tier suppliers in the Bajío Region are qualifying IATF 16949 coating sources to serve Honda, Mazda, and Toyota assembly plants.
Canada
Pipeline operators in Alberta and Saskatchewan specify pure epoxy formulations for tank internals and transmission infrastructure where immersion resistance is non-negotiable. Health Canada and Environment and Climate Change Canada coordinate industrial chemical regulations that align with EPA hazardous air pollutant frameworks. Coating applicators in Ontario's manufacturing belt are converting solvent-based lines to capture provincial carbon pricing advantages.
North America Epoxy Powder Coatings Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with coatings divisions rather than pure-play powder specialists. The vendor base concentrates among multinational firms with integrated resin supply and established automotive qualification relationships. Two strategic archetypes dominate: formulation innovators pursuing low-cure chemistry patents, and distribution-heavy players leveraging branch density to capture mid-size fabricator accounts. Competitive moves center on IATF 16949 certification acceleration and direct-to-installer digital platform deployment.
Among diversified coating conglomerates, Akzo Nobel N.V., PPG Industries, Inc., and The Sherwin-Williams Company occupy positions that exemplify contrasting scale strategies. Akzo Nobel represents the marine-to-infrastructure lineage anchor. PPG exemplifies sustained R&D intensity across thermosetting portfolios. Sherwin-Williams sits within the distribution density archetype, leveraging North American branch networks to capture specification-driven procurement in architectural and industrial segments.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun |
| 3M |
| Axalta Coating Systems |
| BASF SE |
| RPM International Inc. |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Capacity utilization at US Gulf Coast epoxy resin plants shapes regional price floors while Mexican automotive demand pulls formulation supply southward. Scale economies in bisphenol-A production concentrate pricing power among integrated resin suppliers, compressing margins for independent powder compounders.
Pricing Analysis
Certification level creates the primary spread, with IATF 16949-qualified formulations commanding premium positioning over ISO 9001 baseline grades. Three-tier pricing structure across premium, standard, and economy levels reflects AAMA 2604 architectural certification, automotive OEM qualification status, and volume commitment scale. Cost compression in standard-grade hybrids is intensifying because appliance manufacturers are consolidating purchase volumes. Tier 2 automotive suppliers exhibit highest price sensitivity, while pipeline operators in corrosive infrastructure applications show least elasticity due to performance warranty exposure.
Supply Chain Analysis
The United States and Germany anchor specialty resin production, while China feeds commodity-grade epoxy intermediates. Formulation chemistry draws from benzene and propylene feedstocks, polyester crosslinkers, and specialized curing agents. Tariff exposure on Chinese epoxy intermediates creates margin volatility for non-integrated compounders. Distribution runs through Sherwin-Williams branch networks, regional chemical distributors, and direct-to-installer digital platforms serving mid-size fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA NESHAP enforcement timelines position the market in early-cycle expansion, with metal fabricators accelerating capital deployment toward powder system conversions ahead of compliance deadlines.
For Market Incumbents: Shield automotive qualification relationships by accelerating IATF 16949 certification for tier supplier networks before OEM consolidation narrows approved vendor lists. Deepen backward integration into bisphenol-A resin supply to offset feedstock volatility from Gulf Coast refinery disruptions. UV-curable liquid substitutes threaten thin-film furniture applications. For New Entrants and Emerging Players: Anchor in EV battery enclosure coatings, where dielectric epoxy specifications are still stabilizing and incumbent qualification advantages remain incomplete. California Air Resources Board rulemaking propagation creates 24–36 month windows for pre-qualified entrants in Northeast and Midwest state implementations. Direct-to-installer digital platforms bypass entrenched branch network density. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation innovators with low-cure chemistry patents over distribution-heavy players facing channel disintermediation. Five-to-ten year viability hinges on energy-transition alignment as OEMs prioritize natural gas reduction in finishing operations. Monitor IATF 16949 certification backlog as inflection signal for automotive supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Cure Formulation Patent Expansion | Energy-optimized chemistry captures OEM sustainability mandates and reduces natural gas exposure. |
| IATF 16949 Certification Acceleration | Automotive qualification timelines of 12–18 months create defensive moats against new entrants. |
| Direct-to-Installer Platform Launch | Digital procurement bypasses Sherwin-Williams branch density to serve mid-size fabricators. |
| Gulf Coast Resin Capacity Addition | Captive bisphenol-A supply insulates against benzene and propylene price volatility. |
| EV Battery Enclosure Coating Development | Dielectric formulations penetrate thermal management applications in underbody assemblies. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with coating formulators, automotive tier supplier procurement leads, appliance manufacturing engineers, and architectural metal fabricators; and secondary validation through EPA NESHAP regulatory filings, ACC industry statistics, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data on epoxy resin imports. Bottom-up volume triangulation from end-use application consumption patterns was cross-checked against top-down resin production capacity estimates.
Across the projection horizon, the analytical framework modeled demand by resin chemistry, cure kinetics, end-use performance threshold, and regional regulatory cluster. CAGRs were derived from segment-level volume buildups calibrated to OEM capital expenditure cycles and enforcement phase-in schedules. Forecast inputs incorporated natural gas price trajectories affecting low-cure adoption economics and SEMARNAT regulatory alignment timelines in Mexican manufacturing clusters.
Decision-makers should treat outputs as directional under stable EPA enforcement schedules and feedstock supply continuity; material deviation in regulatory timing or Gulf Coast refinery disruption severity would warrant model refresh. Recalibration cycles align with material shifts in NESHAP implementation pacing and low-cure formulation penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Coated Steel Market
Coatings
ASEAN Protective Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Graphene Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Global High-Performance Anti-Corrosion Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
Stain Resistant Coatings Market
Coatings
Coating Equipment Market
Coatings
Vietnam Architectural Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Diamond-Like Carbon Coatings Market