
 Polyvinylidene Fluoride (PVDF) Coatings Market | 2026-2036
Polyvinylidene Fluoride (PVDF) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinylidene Fluoride (PVDF) Coatings Market Analytics
The EU Green Deal is decoupling fluoropolymer demand from legacy high-emission chemistries across European industrial coatings procurement. PPG Industries Inc leverages its aerospace-certified PVDF systems to anchor long-term supply contracts with tier-one airframe manufacturers. AkzoNobel N.V. competes through coil coating specialization for architectural cladding across Nordic and Benelux markets. Solvay sustains captive resin-to-coating integration that controls feedstock quality for battery binder and coating dual-use applications.
Polyvinylidene fluoride coatings are fluoropolymer finishes synthesized from vinylidene fluoride monomer through suspension or emulsion polymerization, typically applied at film builds of 25–50 microns to deliver weathering resistance exceeding 3,000 hours in accelerated UV exposure testing. Their primary purpose is protecting aluminum, steel, and galvanized substrates in harsh chemical, thermal, and ultraviolet environments where conventional coatings degrade within months. Coatings formulations dominate current revenue owing to entrenched specification in AAMA 2605 architectural standards and OEM qualification cycles that lock out substitute technologies. Powder form applications are expanding fastest as electrostatic spray recovery systems cut material waste and volatile organic compound emissions below EPA Method 24 thresholds for metal finishing operations.
EPA NESHAP standards for surface coating operations mandate maximum achievable control technology for hazardous air pollutants, compelling capital upgrades at U.S. job shops serving chemical and pharmaceutical equipment. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are narrowing acceptable fluoropolymer chemistries in EU consumer-facing applications, forcing reformulation investments ahead of sunset dates. China's GB standards for building curtain wall coatings specify minimum fluoropolymer content that elevates quality floors for domestic producers while screening out low-grade imports. Stakeholders must monitor regulatory divergence between Brussels and Beijing on fluorinated compound classifications, as misaligned compliance obligations will fragment supply chain configurations and qualification documentation requirements across major demand centers.
Market Dynamics
The EU F-Gas Regulation is forcing reformulation across European PVDF coating supply chains as permissible fluorinated compound emissions tighten, while China's lithium-ion battery gigafactories concentrate demand for coated components in a single geography.
Growth Catalysts
- Semiconductor fabrication expansion:China's domestic chip foundries are multiplying coated component requirements for process equipment handling aggressive chemistries.
- REACH Annex XVII compliance deadlines:EU restrictions on per- and polyfluoroalkyl substances are accelerating qualification of next-generation fluoropolymer chemistries ahead of sunset dates.
- Electrostatic spray recovery:Powder application systems are cutting material waste and volatile organic compound emissions below EPA Method 24 thresholds for metal finishing operations.
Market Restraints
- Vinylidene fluoride monomer concentration:Captive resin production by integrated chemical majors limits independent coating formulator access to feedstock.
- Substitution by fluorinated ethylene propylene:Lower-cost FEP coatings are displacing PVDF in non-architectural applications with reduced UV exposure requirements.
- AAMA 2605 specification lock-in:Architectural standards entrenched over decades create qualification barriers for novel fluoropolymer technologies.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery production incentives are creating coated component demand outside established supply chains.
- Dual-use resin-to-binder integration:PVDF's application as both coating and lithium-ion battery electrode binder enables cross-selling to common customers.
- Waterborne dispersion technology:Solvent reduction is opening coil coating applications previously restricted by volatile organic compound regulations.
Industry Challenges
- Fluoropolymer formulation expertise scarcity:Specialized polymer science talent pools concentrate at legacy chemical majors, constraining independent formulator R&D velocity.
- OEM qualification cycle duration:Aerospace and architectural certification timelines extending 18-36 months delay revenue realization for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinylidene Fluoride (PVDF) Coatings Market |
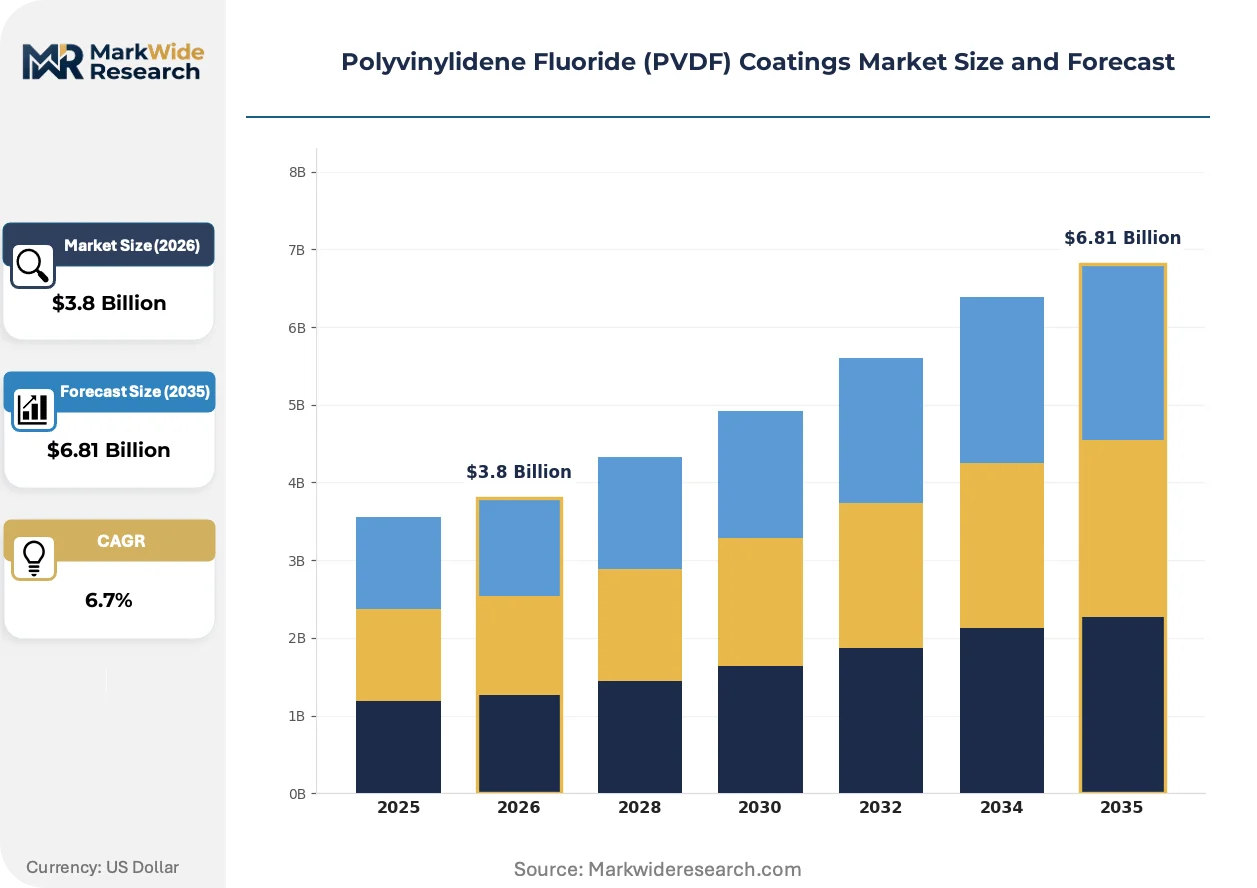
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
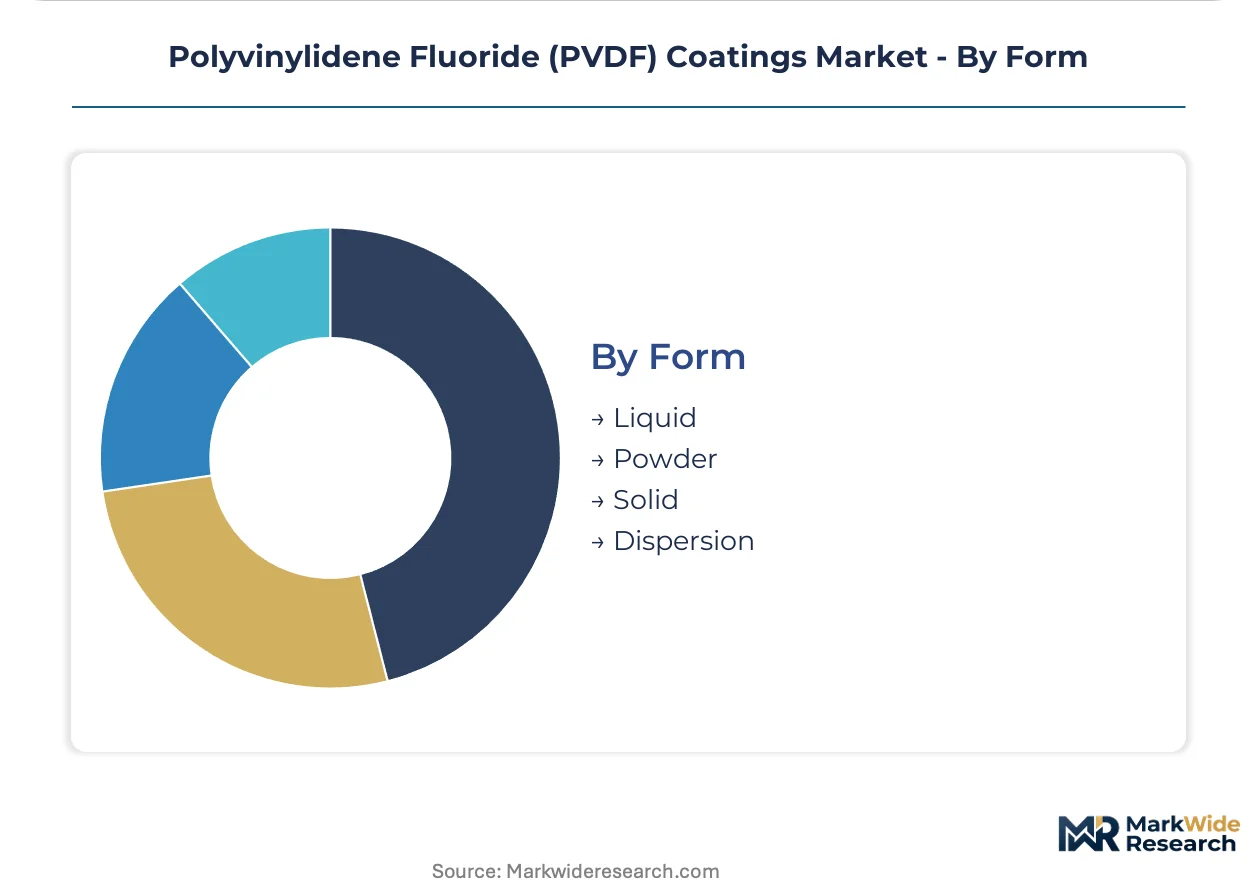
| Segmentation | Product Type: Coatings, Adhesives, Films, Lacquers End Use Industry: Aerospace, Construction, Automotive, Electronics Application: Corrosion Resistance, Chemical Resistance, Thermal Insulation, Aesthetic Finishes Form: Liquid, Powder, Solid, Dispersion |
| Companies Covered | The Sherwin-Williams Company, TIGER Coatings GmbH & Co KG, AkzoNobel N.V., Hitech Coatings, BASF SE, Solvay, KECO Coatings, Metal Coatings Corp, PPG Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinylidene Fluoride (PVDF) Coatings Market Evolving Landscape
PVDF coating technology is bifurcating between high-performance architectural specifications and mass-market industrial applications, with formulation chemistry and application method becoming the primary axes of differentiation.
Nano-structured surface modification is consolidating functional performance into thinner film builds. Coil coaters serving Nordic and Benelux architectural markets are adopting 15-25 micron systems that maintain AAMA 2605 weathering resistance. This consolidation is compressing material throughput per square meter while preserving specification compliance.
REACH restrictions on per- and polyfluoroalkyl substances are narrowing acceptable fluoropolymer chemistries in EU consumer-facing applications. Industrial coating formulators are accelerating reformulation investments ahead of 2025-2027 sunset dates. The architectural cladding segment is responding by locking in long-term supply contracts with qualified European resin producers.
Specification-driven procurement is compressing supplier lists to pre-qualified coating systems. Tier-one airframe manufacturers and curtain wall fabricators are consolidating vendor bases to reduce qualification burden. This concentration is most visible in China's domestic semiconductor and battery equipment supply chains, where GB standards for building curtain wall coatings elevate quality floors that screen out low-grade imports.
Polyvinylidene Fluoride (PVDF) Coatings Market Segmentation
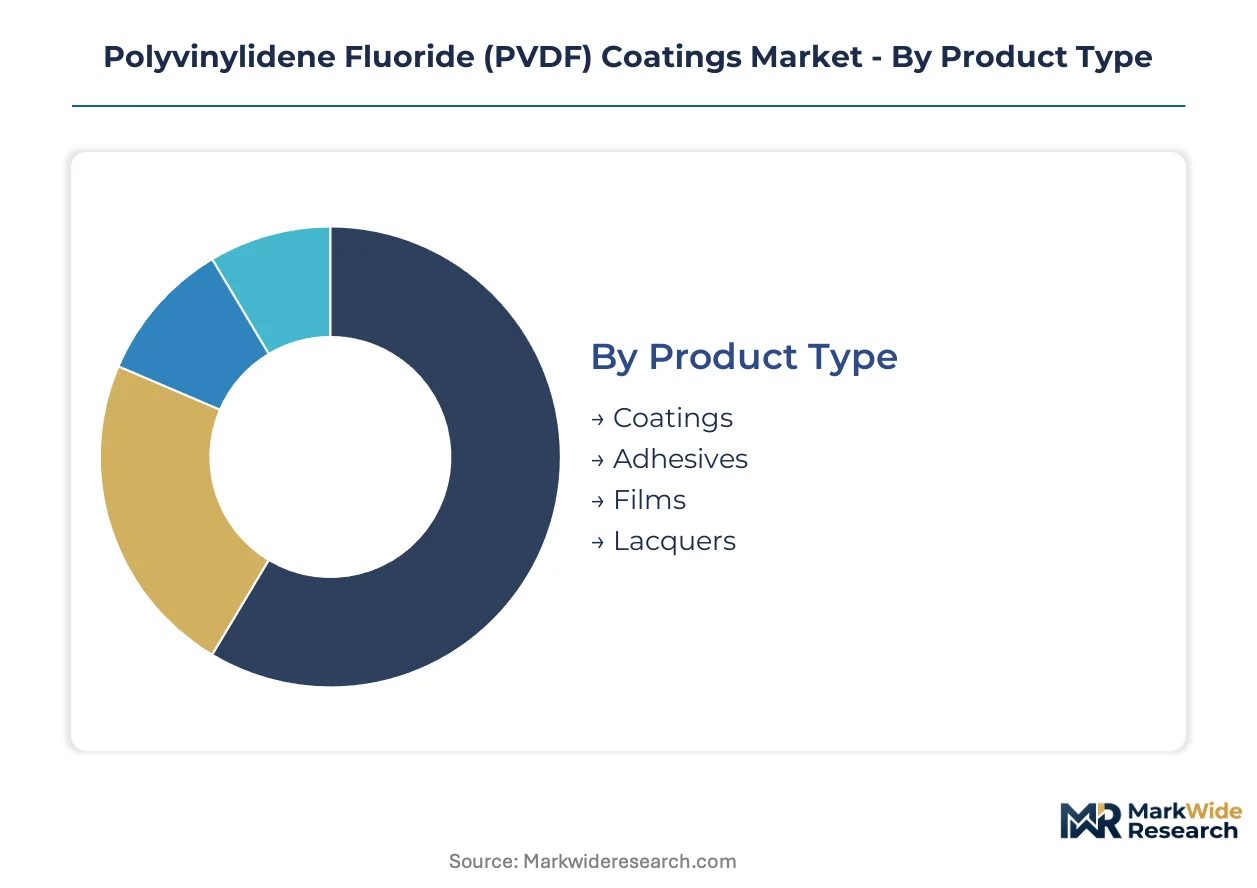
PVDF coating procurement hinges on specification compliance, application method compatibility, and end-use performance thresholds. Buyers segment supply by product chemistry, target industry qualification requirements, functional performance needs, and physical form factors that determine equipment and handling protocols.
Product Type:
Specification standards and end-use performance requirements drive buyer selection across product categories.
- Coatings:Applied at 25–50 micron film builds, these systems deliver weathering resistance exceeding 3,000 hours in accelerated UV exposure testing. Demand concentrates in architectural cladding across Nordic and Benelux markets where AAMA 2605 standards lock in fluoropolymer specifications.
- Films:Extruded or cast PVDF layers serve semiconductor fabrication equipment and lithium-ion battery component protection. China's domestic chip foundries and battery gigafactories are multiplying coated component requirements for process equipment handling aggressive chemistries.
- Adhesives:Bonding formulations for metal-to-metal and metal-to-composite joints in chemical processing equipment.
- Lacquers:Thin-film solvent-based systems for coil coating pre-finished architectural panels.
Coatings lead on scale; films lead on momentum.
End Use Industry:
Qualification cycles and regulatory exposure shape procurement concentration across verticals.
- Construction:Architectural cladding and curtain wall systems specify PVDF for weathering performance. China's GB standards for building curtain wall coatings specify minimum fluoropolymer content that elevates quality floors for domestic producers while screening out low-grade imports.
- Aerospace:Airframe exterior and interior coating systems require OEM certification extending 18–36 months. Tier-one manufacturers anchor long-term supply contracts with qualified coating formulators.
- Electronics:Semiconductor process equipment and battery manufacturing infrastructure demand chemical resistance.
- Automotive:Under-hood components and exterior trim applications with thermal and fluid exposure requirements.
Construction dominates volume; aerospace commands premium positioning.
Application:
Functional performance specifications determine formulation chemistry and film build requirements.
- Corrosion Resistance:Protects aluminum, steel, and galvanized substrates in chemical processing facilities. EPA NESHAP standards for surface coating operations mandate maximum achievable control technology for hazardous air pollutants, compelling capital upgrades at U.S. job shops serving chemical and pharmaceutical equipment.
- Chemical Resistance:Withstands aggressive media in semiconductor fabrication and battery production environments. Chemical processing facilities are expanding adoption of PVDF-coated equipment to withstand aggressive media.
- Thermal Insulation:High-temperature stability for exhaust systems and industrial ovens.
- Aesthetic Finishes:Color-stable architectural coatings with gloss retention over decades.
Corrosion resistance anchors installed base; chemical resistance is climbing the fastest.
Form:
Application equipment and environmental compliance dictate form factor selection.
- Powder:Electrostatic spray recovery systems cut material waste and volatile organic compound emissions below EPA Method 24 thresholds for metal finishing operations. Powder applications are expanding fastest as environmental regulations tighten.
- Liquid:Conventional solvent-borne and waterborne systems for field application and touch-up. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are narrowing acceptable fluoropolymer chemistries in EU consumer-facing applications, forcing reformulation investments ahead of sunset dates.
- Dispersion:Waterborne systems opening coil coating applications previously restricted by volatile organic compound regulations.
- Solid:Extrusion-grade resins for film and sheet conversion.
Liquid maintains broadest specification coverage; powder gains share fastest on compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and coating formulators concentrate in industrial clusters near fluorochemical feedstock sources and end-use manufacturing centers. Talent pools anchor in Germany's chemical corridor, China's battery manufacturing zones, and the US Gulf Coast petrochemical complex.
China
Lithium-ion battery gigafactories and domestic semiconductor foundries multiply coated component requirements for process equipment. GB standards for building curtain wall coatings specify minimum fluoropolymer content that elevates quality floors for domestic producers. The Yangtze River Delta and Pearl River Delta clusters concentrate both resin production and downstream coating application facilities.
United States
Aerospace OEMs and chemical processing equipment fabricators sustain demand for high-specification fluoropolymer systems. EPA NESHAP standards for surface coating operations mandate maximum achievable control technology for hazardous air pollutants. The Gulf Coast petrochemical corridor hosts integrated resin production alongside coating formulators serving energy and chemical sectors.
Germany
Coil coating specialists serving Nordic and Benelux architectural markets anchor specification-compliant formulation expertise. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances accelerate qualification of next-generation fluoropolymer chemistries. The North Rhine-Westphalia industrial belt concentrates both resin synthesis and architectural coating application infrastructure.
India
The PLI scheme for advanced chemistry cell manufacturing creates coated component demand outside established supply chains. BIS standards for industrial coatings are tightening quality requirements for domestic battery and chemical equipment production. Gujarat and Maharashtra industrial corridors attract coating formulators positioning for battery manufacturing infrastructure buildout.
Japan
Semiconductor process equipment manufacturers sustain premium-grade fluoropolymer coating specifications. METI industrial standards govern chemical resistance and purity requirements for electronics manufacturing applications. The Kyushu and Chubu regions concentrate precision coating applicators serving domestic chip fabrication tool builders.
Polyvinylidene Fluoride (PVDF) Coatings Market Competitive Landscape
Capital-heavy integrated resin producers compete with asset-light specialized coating formulators for specification-driven procurement decisions. The market structure concentrates around chemical majors with captive vinylidene fluoride monomer supply and independent formulators with deep OEM qualification relationships. Three archetypes dominate: integrated resin-to-coating operators, architectural specification specialists, and industrial application-focused job shops. Competitive moves center on dual-use resin-to-binder integration for battery customers and waterborne dispersion technology licensing for compliance-driven coil coating conversions.
Among European-integrated chemical majors, Solvay and BASF SE exemplify captive resin-to-coating integration strategies that control feedstock quality for battery and coating dual-use applications. AkzoNobel N.V. occupies a position within the architectural specification tier, representing coil coating specialization strategies for Nordic and Benelux markets where AAMA 2605 standards lock in fluoropolymer procurement.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| TIGER Coatings GmbH & Co KG |
| AkzoNobel N.V. |
| Hitech Coatings |
| BASF SE |
| Solvay |
| KECO Coatings |
| Metal Coatings Corp |
| PPG Industries Inc |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap coating specialists concentrated in Germany's North Rhine-Westphalia belt exercise pricing discipline through long-term resin offtake agreements with Solvay and BASF SE. Their captive relationships with architectural fabricators serving Nordic markets insulate margin structures from spot vinylidene fluoride monomer volatility. This ownership pattern concentrates supply-side bargaining power while locking in premium pricing for AAMA 2605-qualified systems.
Pricing Analysis
Bundled coating-plus-application services command 15-25% premiums over unbundled material-only transactions in architectural specification markets. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified systems from industrial maintenance grades and commodity coil coating formulations. Cost compression in standard-tier liquid coatings is intensifying because REACH Annex XVII compliance investments are raising formulation overhead without commensurate price recovery. Chemical processing OEMs exhibit lowest price sensitivity due to qualification lock-in, while job shops serving intermittent maintenance work face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements mandated by tier-one aerospace OEMs and battery manufacturers are fragmenting resin procurement across Belgium, China, and Japan. Vinylidene fluoride monomer production draws from fluorspar concentrate, hydrogen fluoride, and chloroform feedstocks concentrated in China's Inner Mongolia and Henan provinces. Single-source vulnerability in semiconductor-grade PVDF resin exposes coating formulators to allocation risk during battery sector demand surges. Distribution runs through authorized applicator networks for architectural specifications and direct mill supply for coil coating operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PVDF coatings function as a stable compounder anchored by specification inertia in architectural and aerospace procurement. Regulatory compliance obligations perpetually refresh demand for qualified formulations regardless of cyclical industrial activity.
For Market Incumbents: Hedge against fluorinated ethylene propylene substitution by deepening captive resin relationships with European majors and accelerating waterborne dispersion R&D ahead of EPA NESHAP tightening. Lock in 36-month supply contracts with China's battery equipment fabricators before India's PLI scheme matures competing demand centers. Vertical integration into lithium-ion battery binder applications offers cross-selling leverage against pure-play coating competitors. For New Entrants and Emerging Players: Waterborne dispersion technology for coil coating conversions represents the most penetrable white space, as established players prioritize powder system investments. Target India's Gujarat and Maharashtra industrial corridors before domestic qualification infrastructure matures, leveraging technology licensing from European dispersion specialists rather than building formulation capability organically. A regulatory-first go-to-market emphasizing REACH Annex XVII pre-qualification accelerates OEM approval timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among independent architectural job shops lacking battery sector exposure, where specification expertise trades at material discounts to integrated resin-to-coating operators. The 5-10 year viability window favors acquisition of qualified European coil coating specialists with established Nordic-Benelux fabricator relationships. Monitor EU F-Gas Regulation amendment timelines as the critical inflection signal for reformulation capex cycles and stranded asset risk in legacy high-GWP resin inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinylidene Fluoride Monomer | Captive resin production insulates formulators from Solvay and BASF SE allocation decisions during battery demand spikes. |
| Waterborne Dispersion Technology Licensing | REACH Annex XVII compliance opens coil coating conversions previously restricted by solvent-borne VOC thresholds. |
| Dual-Use Resin-to-Binder Integration | PVDF's application as both coating and battery electrode binder enables cross-selling to common gigafactory customers. |
| Long-Term Supply Agreement with Aerospace OEMs | AAMA 2605 and OEM certification lock-in secures 18-36 month revenue visibility against substitute fluoropolymer threats. |
| Joint Venture with Indian PLI Scheme Beneficiaries | Domestic battery manufacturing incentives in Gujarat create coated component demand outside established China-centric supply chains. |
Research Methodology
Multiple input streams — coating formulator technical directors, architectural fabricator procurement leads, chemical processing plant maintenance managers, and resin producer sales executives — were reconciled against customs trade data, SEC 10-K filings, and Cefic fluoropolymer production statistics. Bottom-up demand modeling from end-use industry consumption patterns was cross-validated with top-down resin production capacity assessments across the analysis window.
Historical volume trajectories were cross-referenced against expert panel inputs from coating application specialists and OEM qualification engineers. Segmentation dimensions modeled include product form factor, end-use industry vertical, functional performance specification, and regional regulatory compliance cluster. CAGRs were derived from slope consensus across exponential trend fitting and scenario-weighted probability distributions, with specific weighting applied to China's lithium-ion battery capacity buildout and EU F-Gas Regulation amendment schedules.
The model holds under stable regulatory phase-in timelines and continued specification inertia in architectural standards; deviation in REACH Annex XVII sunset acceleration or AAMA 2605 revision would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Cool Roof Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
BPA-Free Coatings Market
Coatings
Rail Coatings Market
Coatings
Marking Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Marine Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Global Optical Coating Market
Coatings
FBE Coatings Market
Coatings
Global Sputter Coater Market
Coatings
PU Coatings Market