
 Saudi Arabia Industrial Coatings Market | 2026-2036
Saudi Arabia Industrial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Industrial Coatings Market Analytics
Saudi Arabia is narrowing the gap between domestic formulation capacity and import dependency through expanded local manufacturing zones. PPG Industries leverages its regional blending facilities to supply high-performance epoxy systems for offshore platforms. Hempel sustains a dominant position in marine protective coatings through dedicated technical service teams in Dammam. Zamil Industrial Coating Company anchors its competitive stance with backward integration into resin supply and captive distribution across the Kingdom.
Saudi Arabia industrial coatings comprise engineered polymer films—typically 50–500 microns dry film thickness—applied to metal, concrete, or composite substrates to prevent corrosion, chemical attack, and thermal degradation in harsh operating environments. Epoxy formulations dominate petrochemical and marine applications due to superior adhesion and chemical resistance under continuous immersion. Polyurethane topcoats command premium positioning in automotive and transport end users where UV stability and gloss retention determine lifecycle value. Water-based formulations are gaining formulation share as SASO enforcement of VOC emissions intensifies across manufacturing and infrastructure projects.
SFDA oversight of chemical substance registration and SASO's mandatory product conformity assessment shape import pathways and local formulation requirements for industrial coatings. The Saudi Building Code and Gulf Standardization Organization harmonized specifications further constrain solvent-based system deployment in public infrastructure tenders. Stakeholders must monitor regulatory calibration between domestic content incentives and evolving environmental compliance thresholds to optimize supply chain positioning.
Market Dynamics
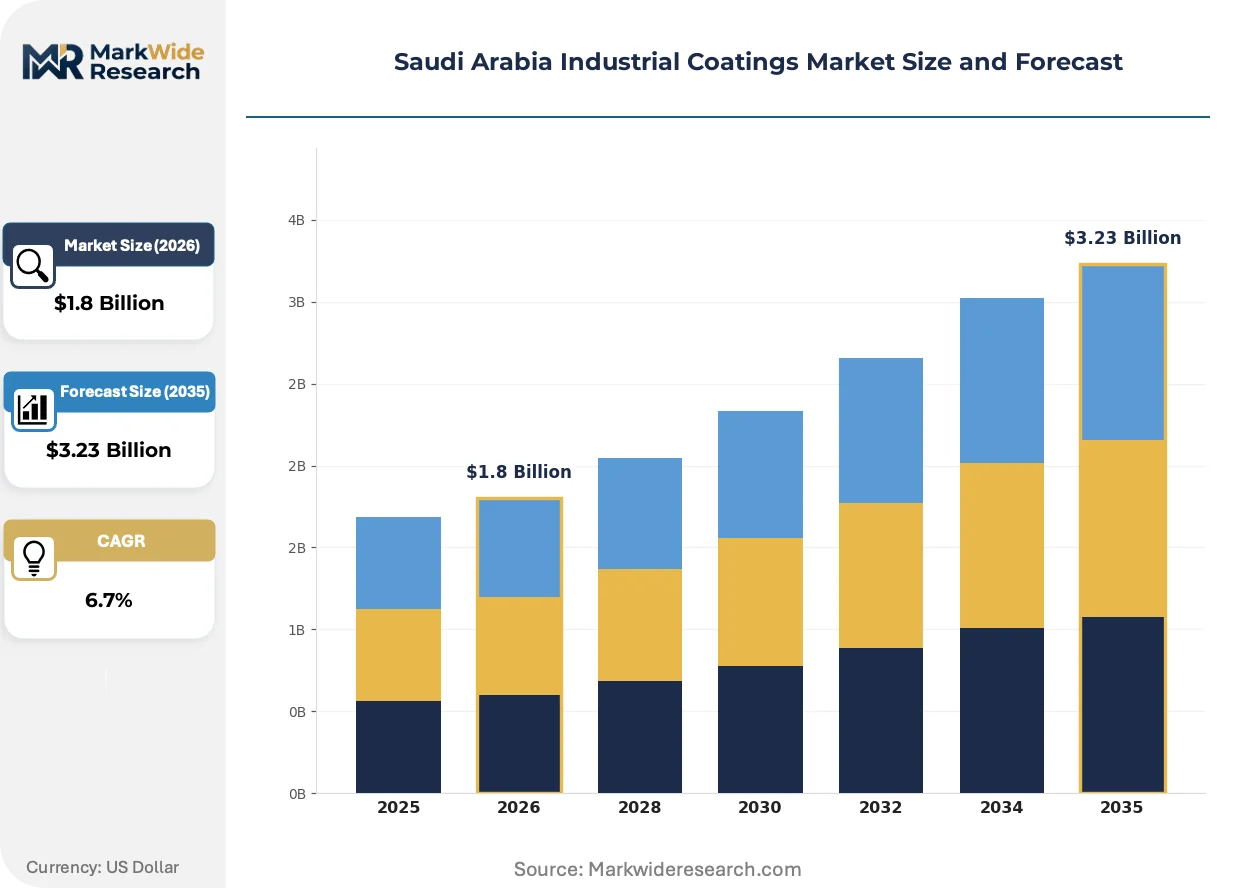
SASO's phased VOC emission reductions are forcing reformulation across solvent-based product lines while mega-project construction in Jubail and Ras Al-Khair sustains volume pull for high-performance protective systems.
Growth Catalysts
- Petrochemical capacity expansion:Downstream investments at Jubail Industrial City and Ras Al-Khair Industrial City are generating sustained demand for corrosion-resistant coating systems in processing equipment and storage infrastructure.
- SASO VOC compliance deadlines:The Saudi Standards, Metrology and Quality Organization's tightening solvent emission limits are accelerating water-based and high-solids formulation adoption across manufacturing and infrastructure tenders.
- Maritime fleet modernization:Drydock maintenance cycles at King Abdulaziz Port and King Fahd Industrial Port are expanding procurement of antifouling and ballast tank coating systems.
Market Restraints
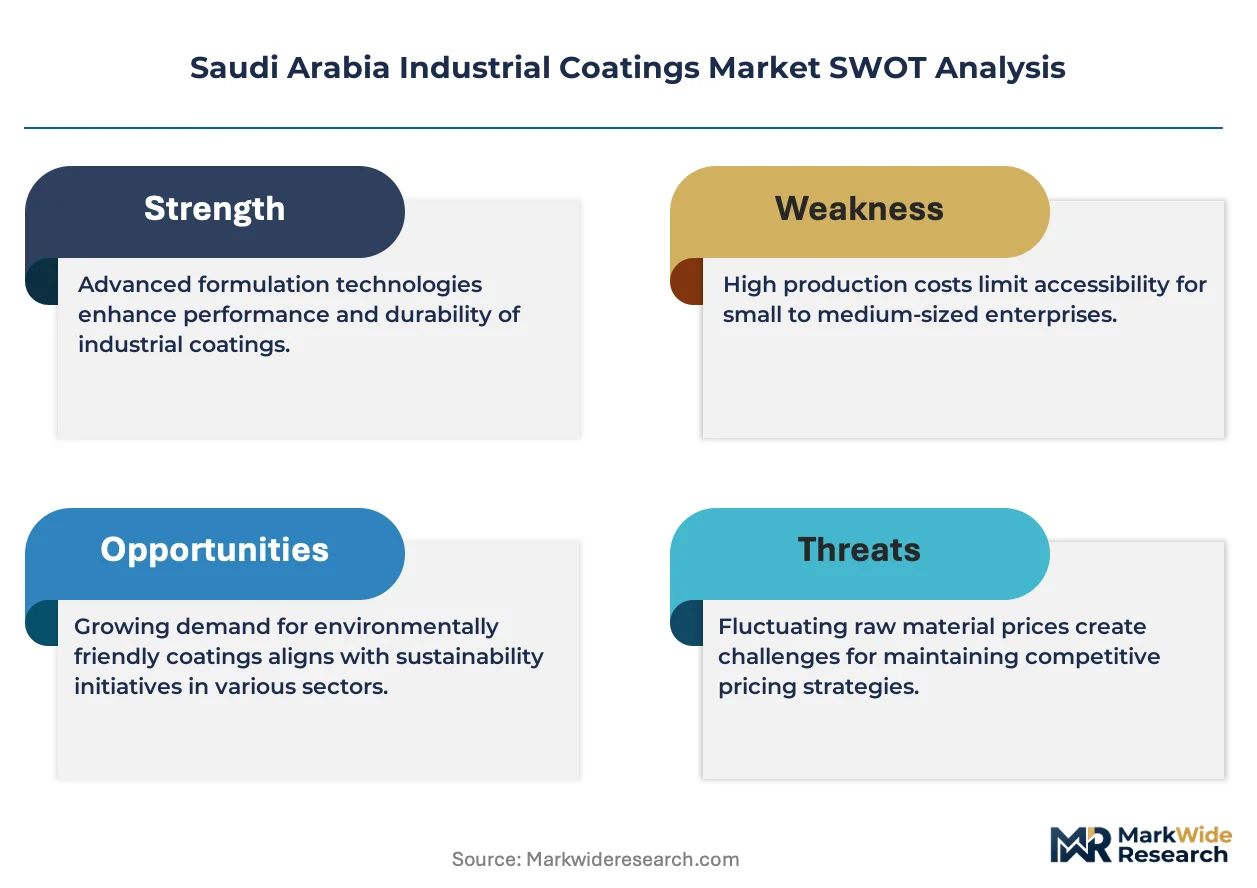
- Epoxy resin import dependency:Domestic formulation capacity remains constrained by limited local production of bisphenol-A and specialty curing agents, exposing margins to feedstock price volatility from Asian suppliers.
- Technical service scarcity:Application engineering expertise for complex immersion service coatings concentrates in Dammam and Jubail, creating deployment bottlenecks for remote upstream oilfield projects.
- Solvent-based system phase-out friction:Legacy specifications in existing maintenance contracts and contractor familiarity barriers are slowing water-based system penetration in spot repair applications.
Strategic Opportunities
- Neom construction pipeline:The giga-project's linear city and industrial zone development will require specialized concrete protection and architectural coating systems with extended durability warranties.
- Carbon capture infrastructure:Emerging amine treatment and CO2 compression facilities are creating demand for chemically resistant lining systems not previously specified in conventional petrochemical applications.
- Local content incentives:The National Industrial Development and Logistics Program's domestic manufacturing subsidies are enabling backward integration into resin synthesis and captive additive production.
Industry Challenges
- Applicator certification bottlenecks:SSPC and NACE coating inspector credentials remain concentrated among a limited contractor base, constraining quality-assured deployment for critical infrastructure.
- Specification fragmentation:Divergent standards between Saudi Aramco engineering procedures, SABIC technical requirements, and SASO conformity assessment protocols are complicating product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Industrial Coatings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyester Application: Automotive, Construction, Marine, Oil & Gas End User: Manufacturing, Infrastructure, Transport, Energy Formulation: Water-based, Solvent-based, Powder, UV-cured |
| Companies Covered | PPG Industries, Hempel, Jotun, Saudi Industrial Paint Company, Sigma Paints, AkzoNobel, Sherwin-Williams, Zamil Industrial Coating Company, Al-Jazeera Paints, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Industrial Coatings Market Evolving Landscape
Formulation chemistry and application methods are converging around extended lifecycle performance and reduced environmental footprint, reshaping procurement criteria and technical service delivery models across the Kingdom's industrial corridors.
High-solids epoxy technology is collapsing the trade-off between application efficiency and film-build performance in immersion service. Offshore platform operators are specifying these systems for ballast water tank rehabilitation, compressing project timelines from conventional three-coat to two-coat protocols without sacrificing corrosion protection durability.
SASO's Technical Regulation for Paints and Varnishes is mandating VOC content ceilings that ratchet down through sequential compliance phases. Formulators are accelerating waterborne polyurethane and polysiloxane development programs, with marine and protective segments facing the most aggressive substitution timelines due to their historical reliance on solvent-borne epoxies.
Asset owner engineering departments are consolidating coating specifications around performance-based warranty contracts rather than prescriptive product approvals. This procurement evolution is disintermediating traditional distributor technical sales roles in favor of direct manufacturer-applicator partnerships, most visible in Saudi Aramco's long-term maintenance agreements for Aboveground Storage Tanks.
Saudi Arabia Industrial Coatings Market Segmentation
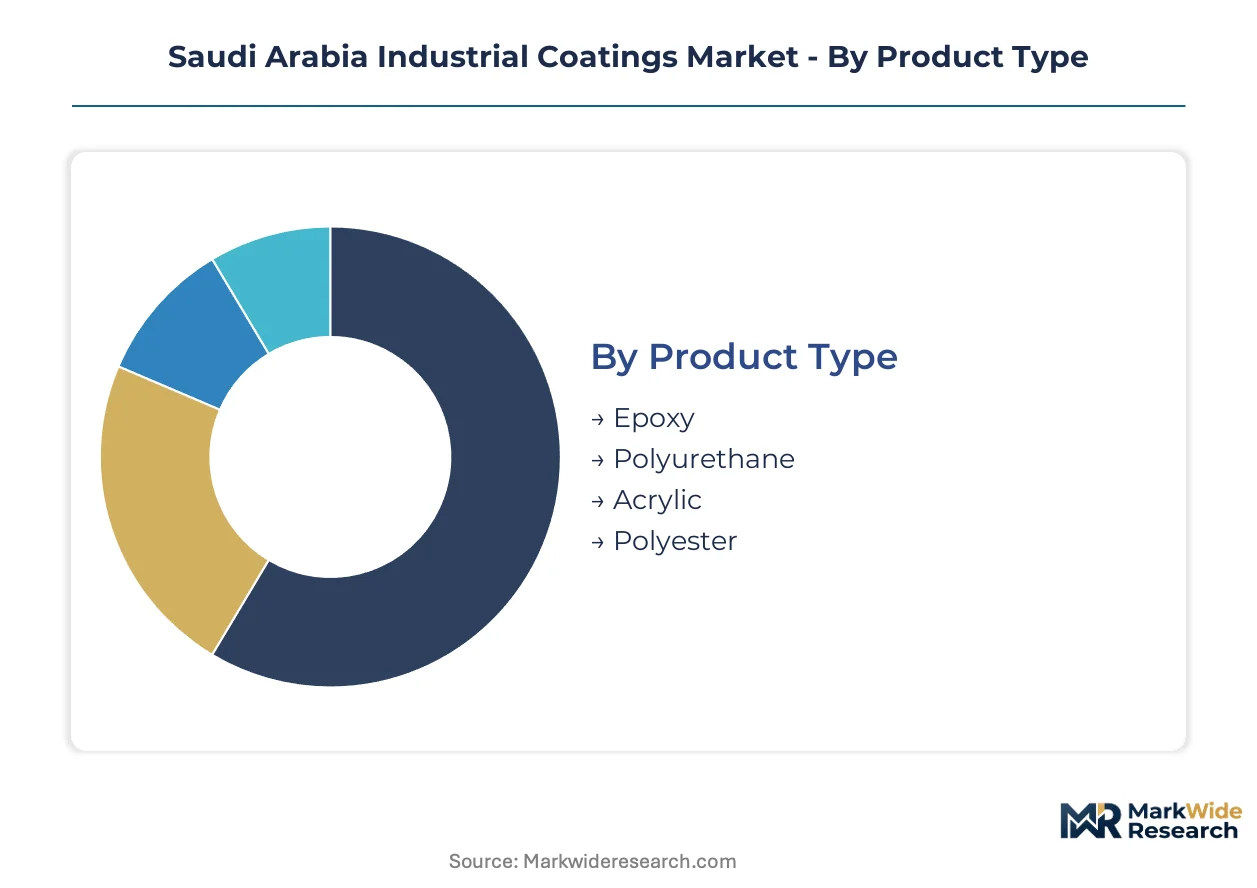
Saudi Arabia's industrial coatings procurement patterns diverge sharply across formulation chemistry, application environment, and end-user contracting structures. Understanding these fault lines reveals where specification power concentrates and where reformulation investments will yield competitive advantage.
Product Type:
Cost tier differentiation separates commodity protective systems from premium chemically resistant formulations in Saudi procurement.
- Epoxy:Two-component thermoset systems built from bisphenol-A resins and polyamine curing agents deliver superior adhesion and continuous immersion resistance. Demand concentrates in Jubail and Ras Al-Khair petrochemical complexes where tank lining and pipeline coating specifications mandate epoxy systems for sulfuric acid and hydrocarbon exposure. SASO VOC phase-out timelines are forcing high-solids and waterborne epoxy development programs.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems provide UV-stable topcoats with gloss retention critical to lifecycle valuation. Automotive OEM operations in King Abdullah Economic City and transport fleet operators specify polyurethane for exterior durability warranties. Premium pricing over epoxy reflects shorter recoat intervals and aesthetic performance requirements.
- Acrylic:Thermoplastic emulsion systems offer rapid drying and low-odor application for interior architectural and light industrial environments.
- Polyester:Saturated and unsaturated resin formulations serve powder coating applications in metal fabrication and appliance manufacturing segments.
Epoxy commands the established base. The steepest expansion runs through polyurethane as automotive and transport warranty specifications tighten.
Application:
Application environment dictates performance specifications, certification requirements, and contractor qualification thresholds across Saudi project portfolios.
- Oil & Gas:Protective coating systems for upstream production facilities, downstream refineries, and midstream pipeline infrastructure operate under Saudi Aramco engineering procedure constraints. Offshore platform specifications require NORSOK M-501 compliance for splash zone and submerged service. Dry film thickness requirements of 350-500 microns for immersion service exceed general industrial standards.
- Marine:Antifouling, ballast tank, and cargo hold coating systems serve King Abdulaziz Port and King Fahd Industrial Port drydock maintenance cycles. IMO PSPC regulations for ballast water tank coatings mandate epoxy-based systems with 15-year target service life. Hempel and PPG technical service teams concentrate in Dammam to support specification compliance.
- Construction:Concrete protection and steel fireproofing coatings address Neom giga-project infrastructure and urban building stock.
- Automotive:OEM assembly plant coatings and refinish systems serve local vehicle production and aftermarket repair networks.
Oil & Gas anchors procurement volume. Marine is climbing the fastest as fleet modernization accelerates drydock coating replacement cycles.
End User:
Customer type determines contracting structure, technical service intensity, and specification authority in Saudi coating procurement.
- Energy:Saudi Aramco and SABIC maintain captive engineering standards that override generic SASO specifications for critical assets. Long-term maintenance agreements for Aboveground Storage Tanks consolidate procurement around performance-based warranty contracts rather than prescriptive product approvals. Direct manufacturer relationships disintermediate traditional distributor channels.
- Infrastructure:Public sector tenders under the Saudi Building Code and Gulf Standardization Organization harmonized specifications constrain solvent-based system deployment. Neom development authority and Ministry of Transport projects require extended durability warranties for concrete protection systems.
- Manufacturing:Industrial facility owners in Jubail Industrial City specify coatings for processing equipment, structural steel, and flooring systems under SASO conformity assessment protocols.
- Transport:Fleet operators and automotive OEMs prioritize UV stability, gloss retention, and rapid return-to-service characteristics in coating selection.
Energy holds specification authority. Infrastructure is gaining share fastest as giga-project construction scales procurement volumes.
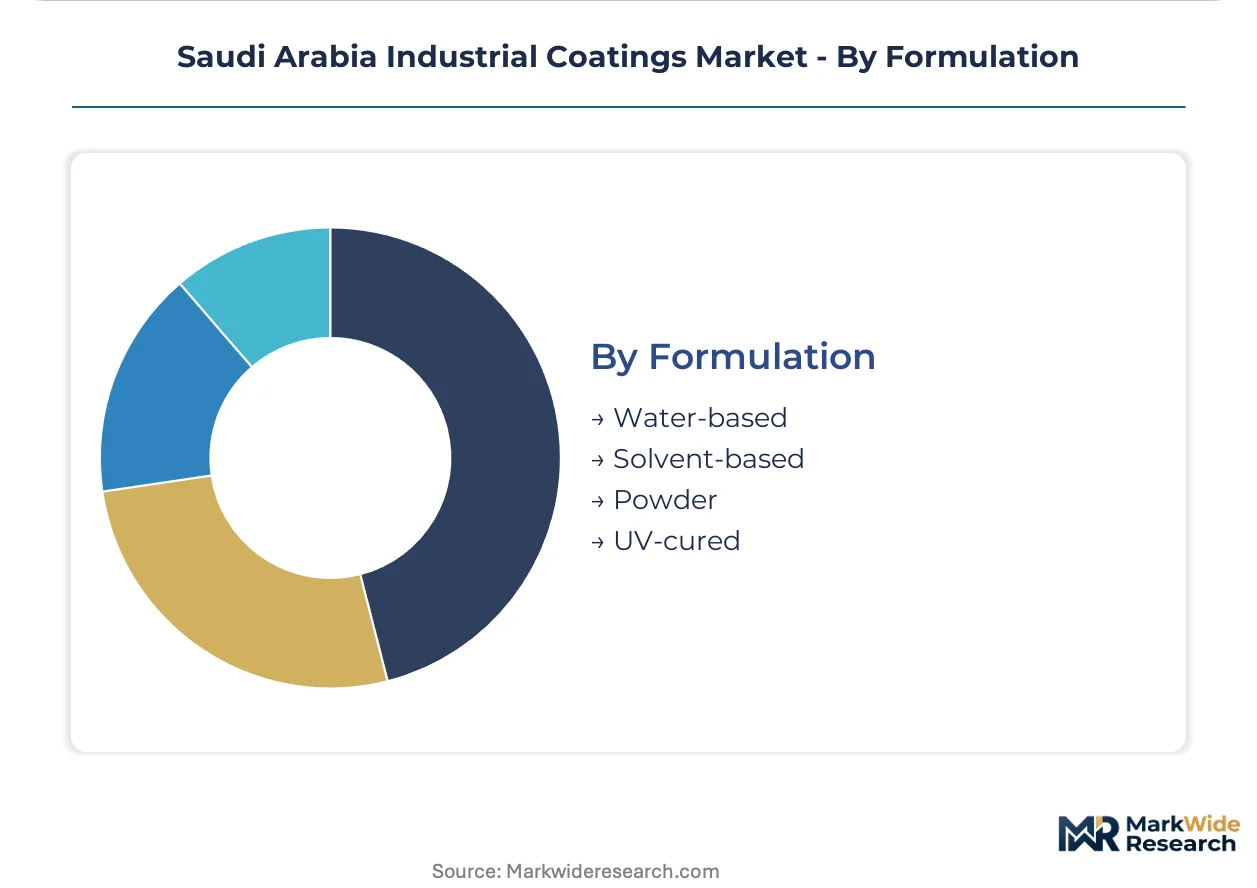
Formulation:
Formulation chemistry sits at the center of SASO regulatory enforcement and technical reformulation investment priorities.
- Solvent-based:Traditional epoxy and polyurethane systems using aromatic hydrocarbon and ketone solvents face phased VOC emission reductions under SASO Technical Regulation for Paints and Varnishes. Legacy maintenance contracts and contractor familiarity barriers slow substitution in spot repair applications. Import dependency for specialty solvents exposes margins to feedstock volatility.
- Water-based:Acrylic and polyurethane dispersions with VOC content below regulatory ceilings are gaining formulation share as enforcement intensifies. Application engineering expertise for complex immersion service waterborne systems concentrates in Dammam and Jubail, creating deployment bottlenecks for remote upstream projects.
- Powder:Thermoset epoxy and polyester powder coatings for metal fabrication operate outside VOC regulatory scope but face curing energy cost pressures.
- UV-cured:Rapid-cure acrylic and epoxy systems serve niche applications where production throughput constraints dominate coating selection criteria.
Solvent-based retains the installed base. Water-based is expanding most quickly as compliance deadlines force specification substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO anchors regulatory harmonization across the Gulf Cooperation Council, yet coating procurement patterns fragment sharply across Saudi sub-regions based on industrial asset concentration and infrastructure investment pipelines.
Eastern Province
Jubail Industrial City and Ras Al-Khair anchor petrochemical coating demand through SABIC and Ma'aden processing complexes. The National Industrial Development and Logistics Program subsidizes local formulation facilities in Ras Al-Khair. Dammam hosts concentrated technical service teams supporting offshore platform maintenance at King Fahd Industrial Port.
Riyadh
Central Region infrastructure tenders under the Saudi Building Code drive specification authority for water-based architectural and protective systems. The Royal Commission for Riyadh City mandates extended durability warranties for municipal steel structures. Local manufacturing zones in Sudair Industrial City are attracting powder coating operations for metal fabrication supply.
Western Region
Jeddah Islamic Port drydock cycles sustain marine coating procurement for Red Sea fleet operators. King Abdullah Economic City automotive OEM operations specify polyurethane topcoats for exterior durability warranties. SFDA chemical substance registration requirements shape import pathways for specialty resin formulations.
NEOM Northwest
The linear city construction pipeline is generating demand for concrete protection systems with 25-year performance warranties. NEOM development authority specifications override generic SASO requirements for critical infrastructure. Oxagon industrial zone planning includes dedicated coating application facilities for wind turbine and solar component manufacturing.
Saudi Arabia Industrial Coatings Market Competitive Landscape
Capability concentration sits with specialized marine and petrochemical formulators; scale advantage sits with diversified multinational suppliers with regional blending infrastructure. The market structures around three tiers: global integrated suppliers with captive Saudi facilities, regional specialists with dedicated technical service teams, and domestic formulators leveraging backward integration into resin supply. Competitive moves center on performance-based warranty contracting and direct manufacturer-applicator partnerships displacing traditional distribution channels.
Among global integrated suppliers, PPG Industries and AkzoNobel occupy positions anchored by regional formulation capacity serving Saudi Aramco engineering procedures. Hempel exemplifies the specialist tier through concentrated technical service deployment in Dammam. Zamil Industrial Coating Company represents domestic backward integration, with captive resin supply and distribution infrastructure across the Kingdom.
| Leading Market Players |
|---|
| PPG Industries |
| Hempel |
| Jotun |
| Saudi Industrial Paint Company |
| Sigma Paints |
| AkzoNobel |
| Sherwin-Williams |
| Zamil Industrial Coating Company |
| Al-Jazeera Paints |
| Others |
Value Network & Pricing Analysis
Asian epoxy resin concentration—particularly bisphenol-A and specialty polyamine curing agents from South Korean and Chinese suppliers—feeds directly into margin compression for Saudi formulators lacking backward integration into feedstock synthesis.
Pricing Analysis
Price spreads between Dammam-based technical service formulations and generic import alternatives can reach 40% for immersion-grade epoxy systems. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels reflects divergence in warranty backing and applicator certification. Pricing pressure stems from feedstock volatility as Saudi formulators absorb currency fluctuation costs to maintain Aramco contract competitiveness. State-owned energy operators show lowest price sensitivity due to lifecycle-cost procurement models, while spot repair contractors in remote upstream fields drive aggressive commodity tier negotiation.
Supply Chain Analysis
Export control regimes on specialty chemical precursors—particularly amine hardeners and corrosion inhibitors subject to dual-use technology classifications—constrain feedstock flows from European and North American suppliers into Saudi formulation plants. Geographic supply concentration centers on China for bisphenol-A resins, South Korea for isocyanate polyurethane intermediates, and Germany for high-performance polysiloxane additives. Raw material dependencies include aromatic hydrocarbon solvents facing SASO phase-out timelines, titanium dioxide pigments, and zinc dust for sacrificial corrosion protection. Single-source vulnerability runs through Jubail Industrial City port logistics for bulk resin discharge. Distribution runs through manufacturer-direct partnerships with certified applicator networks, bypassing traditional distributor markups for Aramco and SABIC critical assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO's sequential VOC compliance deadlines are triggering a platform shift where formulation interoperability—waterborne systems compatible with existing epoxy primers—determines procurement lock-in across maintenance contract renewals.
For Market Incumbents: Insulate specification authority by embedding technical service teams within Saudi Aramco engineering departments for direct coating system design. Deepen backward integration into resin synthesis through National Industrial Development and Logistics Program subsidies in Ras Al-Khair manufacturing zones. Certification investment in SSPC and NACE applicator training programs creates contractor dependency that slows substitute formulation penetration.
For New Entrants and Emerging Players: Build out waterborne polyurethane capabilities targeting automotive OEM operations in King Abdullah Economic City where UV stability warranties command premium positioning. Neom concrete protection systems offer the most penetrable white-space given 25-year performance specifications that favor new entrant warranty structures. Go-to-market should route through direct Oxagon industrial zone partnerships rather than competing for established petrochemical procurement channels.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic formulators with captive resin supply and established SASO conformity assessment pathways. Long-term viability hinges on positioning ahead of solvent-based system phase-out completion. Acquisition target archetype: mid-cap Saudi coating companies with Jubail or Ras Al-Khair production footprints and existing SABIC technical qualification. The signal to watch is carbon capture infrastructure coating specifications as amine-resistant lining demand creates new qualification barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Ras Al-Khair manufacturing subsidies reduce feedstock import dependency for Saudi formulators. |
| Waterborne Formulation Development | SASO VOC compliance deadlines accelerate substitution timelines for solvent-based epoxy systems. |
| Technical Service Team Expansion | Dammam-based application engineering supports offshore platform specification compliance for Aramco. |
| Performance-Based Warranty Contracting | Direct manufacturer-applicator partnerships disintermediate traditional distributor channels in energy procurement. |
| Applicator Certification Program Investment | SSPC and NACE credential concentration constrains quality-assured deployment for critical infrastructure. |
Research Methodology
The analysis maps epoxy, polyurethane, acrylic, and polyester formulation sub-sectors, each validated through coating procurement managers at Saudi Aramco and SABIC, technical directors at regional formulators, and certified applicator contractors across Dammam and Jubail. Primary interview intelligence combined with secondary validation from SASO technical regulations, Saudi Customs import data, and Gulf Standardization Organization harmonized specifications. Bottom-up volume triangulation against top-down petrochemical capacity expansion announcements anchored market sizing across the analysis window.
Assumption sets held feedstock price volatility and SASO enforcement intensity as bounded variables while modeling Neom construction acceleration and maritime fleet modernization as scenario-weighted demand drivers. Segmentation dimensions include formulation chemistry, application environment, end-user contracting structure, and regional industrial cluster concentration. CAGRs derived from elasticity-adjusted demand curves tied to named project pipelines. Forecast inputs incorporated SFDA chemical substance registration timelines and carbon capture infrastructure coating specification emergence.
Practitioners should monitor SASO VOC phase-out enforcement intensity and Asian epoxy resin export pricing for early signals of margin compression or specification substitution acceleration. Forecasts reflect these documented assumptions alongside petrochemical capacity expansion schedules and giga-project construction pacing. Cross-checking against Saudi Aramco engineering procedure revision cycles and SABIC technical requirement updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Germany Industrial Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Yacht Coatings Market
Coatings
China Protective Coatings Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
Industrial Liquid Coating Market
Coatings
Compound Coating Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Global Coated Steel Market
Coatings
High Performance Coatings Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Hydrophilic Coatings Market
Coatings
Antimicrobial Coil Coating Market