
 Europe Super Hydrophobic Coatings Market | 2026-2036
Europe Super Hydrophobic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Super Hydrophobic Coatings Market Foresight
Buyer concentration among European automotive OEMs is expanding as tier-one suppliers consolidate coating procurement across German, French, and Italian assembly networks. BASF SE leverages its integrated polymer research campus in Ludwigshafen to sustain formulation leadership for spray-applied fluoropolymer systems. P2i Ltd anchors its position through vapor deposition technology specialized for electronics moisture protection. AkzoNobel N.V. competes across marine and industrial equipment segments where salt-spray resistance commands specification priority.
Super hydrophobic coatings are thin-film surface treatments engineered with contact angles exceeding 150 degrees, typically incorporating fluorinated compounds or nano-structured silica to repel water, oil, and particulate contamination across substrates. Their primary commercial purpose centers on corrosion prevention, self-cleaning functionality, and extended service intervals for exposed components in transportation and infrastructure systems. Polymer-based formulations occupy the volume core due to lower material costs and compatibility with existing spray lines, while fluoropolymer coatings capture premium margin pools in aerospace and medical device applications where FAA-equivalent durability standards and biocompatibility certifications apply. Silane-based systems are gaining traction in electronics and textile finishing where thinner film builds and substrate-specific adhesion properties matter.
REACH registration requirements and the EU F-Gas Regulation are constraining perfluorinated precursor availability, forcing reformulation investments toward hybrid and silane-based alternatives that reduce environmental persistence. ECHA substance evaluation protocols are extending testing timelines for new nano-structured coatings entering the European market. CE marking obligations under the Construction Products Regulation shape market access for building envelope applications in France and Spain. Stakeholders must monitor regulatory divergence between EU chemical hazard classifications and emerging national eco-label schemes in Germany and the Netherlands that could fragment specification standards across procurement zones.
Market Dynamics
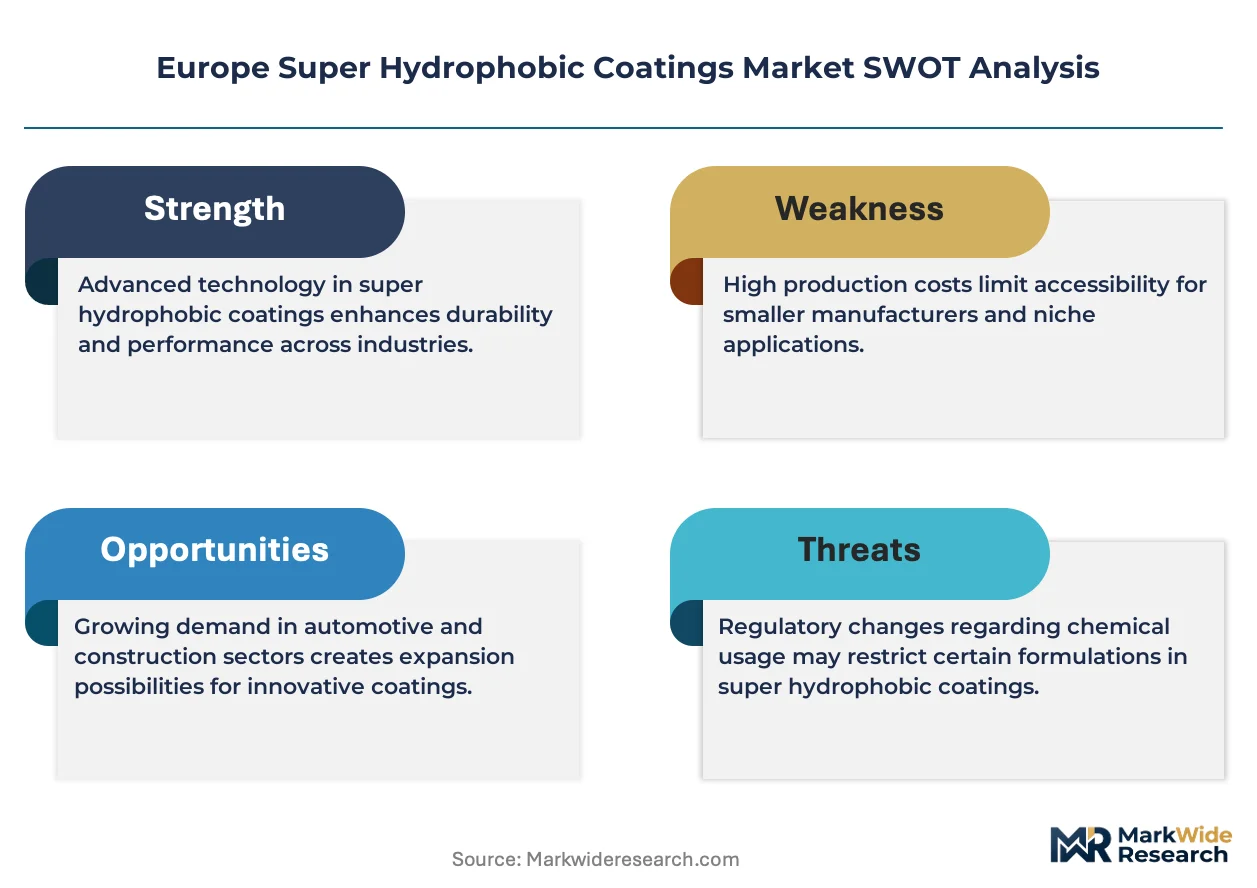
REACH registration deadlines and the EU F-Gas Regulation are forcing wholesale reformulation of fluoropolymer-based coatings, compressing supplier margins while accelerating silane and hybrid chemistry R&D cycles across European coating houses.
Growth Catalysts
- Automotive OEM specification:German and French assembly plants are integrating spray-applied super hydrophobic systems into underbody and wheel-arch protection protocols, extending corrosion warranty periods without structural redesign.
- REACH compliance innovation:Reformulation mandates are driving patentable hybrid chemistry development, creating first-mover advantages for coating houses that achieve ECHA substance evaluation clearance ahead of competitors.
- Aerospace cluster concentration:Maintenance facilities in Hamburg, Toulouse, and Milan are specifying fluoropolymer coatings for landing gear and control surface protection, anchoring premium procurement volumes.
Market Restraints
- Perfluorinated precursor scarcity:EU F-Gas Regulation quotas are constraining PTFE and fluorosilane feedstock availability, forcing coating manufacturers to absorb input cost volatility or pass through to price-sensitive industrial segments.
- Application equipment concentration:Precision spray and vapor deposition system supply concentrates among German and Swiss equipment builders, creating capex bottlenecks for mid-tier coating applicators seeking entry.
- Durability-performance tradeoff:Silane-based alternatives meeting REACH biodegradability thresholds exhibit shorter service intervals than legacy fluoropolymer systems, limiting substitution in aerospace and offshore applications.
Strategic Opportunities
- Medical device penetration:Biocompatibility certification pathways under EU MDR are opening catheter and implant coating specifications for hydrophobic barrier layers that reduce thrombogenicity and biofilm adhesion.
- Building envelope retrofit:CE marking under the Construction Products Regulation is enabling specification of self-cleaning facade coatings in Spanish and Italian renovation markets where labor cost reduction drives material selection.
- Textile finishing convergence:Nano-structured silica deposition is unifying water repellency with antimicrobial functionality for technical workwear, opening procurement channels through industrial laundries and rental uniform providers.
Industry Challenges
- Nano-toxicology assessment capacity:ECHA substance evaluation protocols require extended in-vitro and ecotoxicity testing for nano-structured coatings, stretching internal toxicology teams and external contract research organization lead times.
- Cross-substrate adhesion engineering:Hybrid formulations optimized for metal substrates underperform on polymer composites and treated glass, forcing application-specific qualification cycles that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Super Hydrophobic Coatings Market |
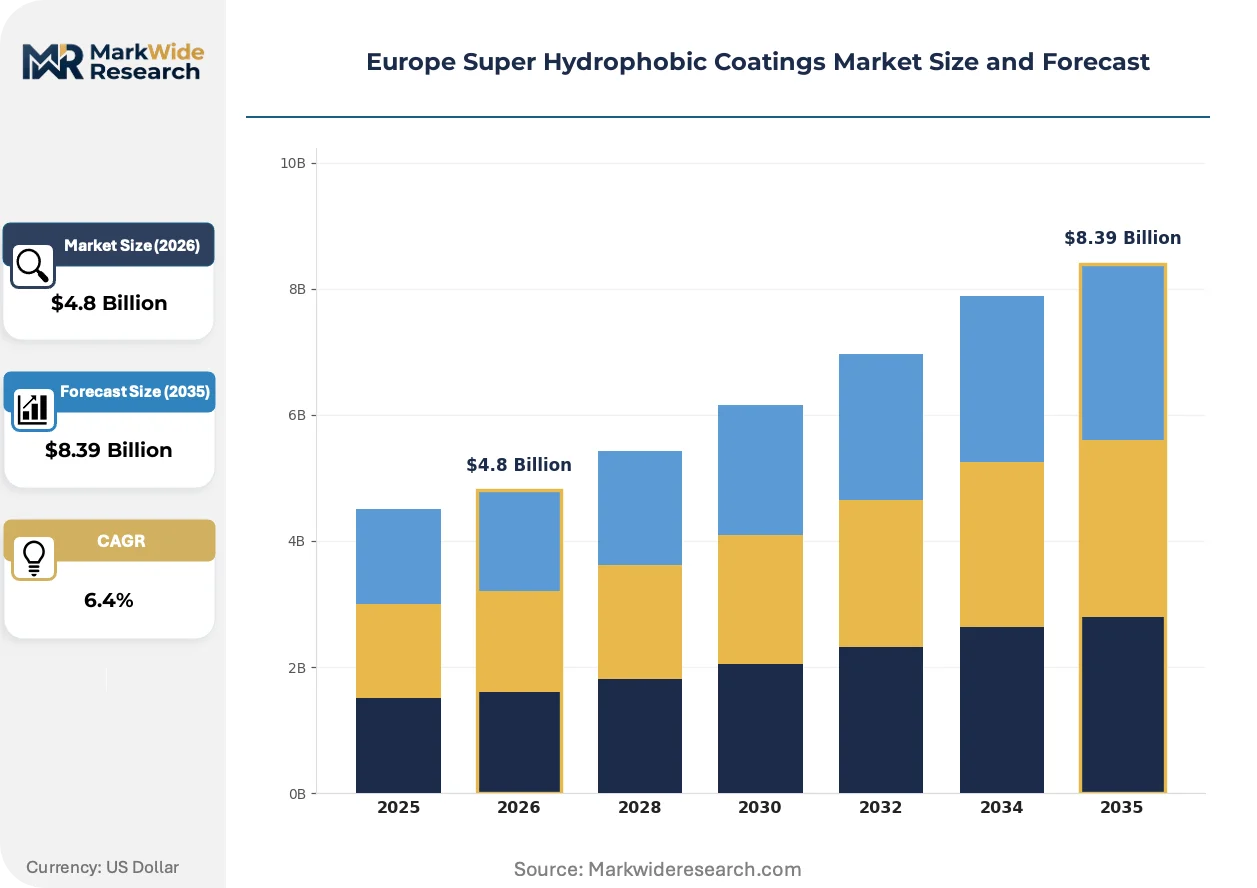
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Silane-Based, Fluoropolymer, Hybrid End User: Automotive, Aerospace, Electronics, Textiles Application: Consumer Goods, Industrial Equipment, Medical Devices, Construction Technology: Spray Coating, Dip Coating, Brush Coating, Vapor Deposition |
| Companies Covered | P2i Ltd, BASF SE, AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, 3M Company, NEI Corporation, Aculon, Inc., UltraTech International Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Super Hydrophobic Coatings Market Shifts & Advancements
Formulation chemistry, application methodology, and procurement specification are converging around sustainability compliance and functional integration, compressing the traditional separation between coating development and end-use system design.
Hybrid fluoropolymer-silane chemistry is unifying water repellency, oil resistance, and mechanical durability in single-layer deposition processes. Automotive tier-one suppliers in Stuttgart and Munich are qualifying these systems for powertrain component protection. The technology is unifying previously separate corrosion and fouling prevention specification categories, reducing coating stack complexity and assembly line capital requirements.
The EU F-Gas Regulation is phasing down hydrofluorocarbon production quotas through 2030, directly constraining fluorinated coating precursor supply. Coating manufacturers are accelerating bio-based silane feedstock partnerships and plasma-enhanced deposition processes that eliminate solvent carriers. Aerospace maintenance, repair, and overhaul operations in France and Germany face the steepest reformulation timelines due to FAA-EASA dual certification requirements.
Specification consolidation among European automotive OEMs is compressing qualified supplier lists and extending contract durations. Tier-one coating applicators are absorbing forward inventory risk and investing in captive spray capacity at assembly plant locations. This pattern is most visible in the German premium passenger vehicle segment, where single-source coating agreements now span five-year horizons with volume guarantees.
Europe Super Hydrophobic Coatings Market Segmentation
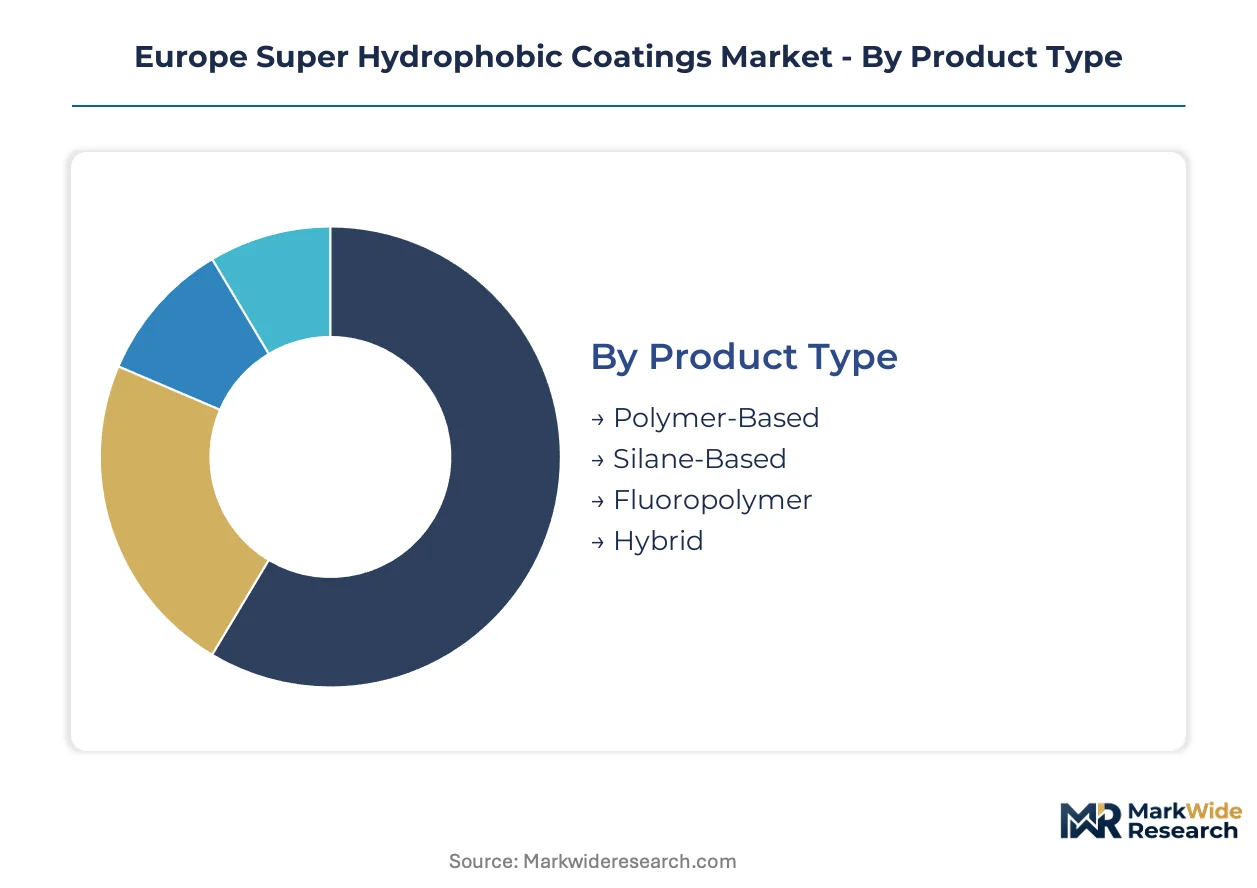
Super hydrophobic coatings in Europe fragment across four intersecting dimensions: chemistry, end-use vertical, application substrate, and deposition method. Each axis carries distinct margin profiles, regulatory burdens, and qualification timelines that shape supplier strategy.
Product Type:
Customization intensity varies sharply across this chemistry spectrum, from commoditized polymer dispersions to precision-engineered fluoropolymer systems requiring ECHA substance-by-substance registration.
- Polymer-Based:Acrylic and polyurethane dispersions dominate volume through compatibility with existing automotive spray lines. German tier-one suppliers specify these for underbody corrosion protection where cost-per-vehicle targets constrain formulation latitude.
- Fluoropolymer:PTFE and fluorosilane systems command premium positioning in aerospace landing gear and control surface applications. REACH registration deadlines and EU F-Gas Regulation quotas are compressing feedstock availability, forcing reformulation toward hybrid alternatives.
- Silane-Based:Organosilane chemistry enables sub-micron film builds for electronics moisture barriers. Thinner deposition profiles reduce material consumption but demand plasma-enhanced application equipment.
- Hybrid:Fluoropolymer-silane combinations unify water repellency with mechanical durability in single-layer systems. Stuttgart automotive clusters are qualifying these for powertrain component protection.
Leading the category by volume: Polymer-Based. Growing fastest: Hybrid.
End User:
Procurement sophistication escalates from price-sensitive textile finishers to specification-intensive aerospace MRO operations with dual FAA-EASA certification requirements.
- Automotive:OEM specification consolidation across German, French, and Italian assembly networks is compressing qualified supplier lists. Spray-applied systems for wheel-arch and underbody protection extend corrosion warranty periods without structural redesign.
- Aerospace:Maintenance facilities in Hamburg, Toulouse, and Milan anchor fluoropolymer demand for landing gear and control surface protection. Dual certification timelines constrain supplier switching.
- Electronics:Vapor-deposited nano-coatings protect smartphones and wearable devices from moisture ingress. P2i Ltd specializes in this segment through proprietary plasma-enhanced deposition.
- Textiles:Technical workwear and industrial uniform rental channels drive nano-structured silica demand. Antimicrobial convergence is unifying procurement specifications through industrial laundry networks.
Dominating procurement value: Aerospace. Expanding most quickly: Automotive.
Application:
Substrate diversity forces application-specific qualification cycles, with metal-focused formulations underperforming on polymer composites and treated glass.
- Industrial Equipment:Salt-spray resistance commands specification priority in marine and offshore machinery. AkzoNobel N.V. competes aggressively across North Sea oil platform maintenance contracts.
- Construction:CE marking under the Construction Products Regulation enables self-cleaning facade coating specifications. Spanish and Italian renovation markets prioritize labor cost reduction over material premiums.
- Consumer Goods:Smartphone and eyewear manufacturers specify ultra-thin hydrophobic layers for cosmetic and functional protection. Price compression limits margin capture.
- Medical Devices:EU MDR biocompatibility certification opens catheter and implant coating specifications. Hydrophobic barrier layers reduce thrombogenicity and biofilm adhesion in cardiovascular applications.
Highest volume concentration: Industrial Equipment. Steepest expansion trajectory: Medical Devices.
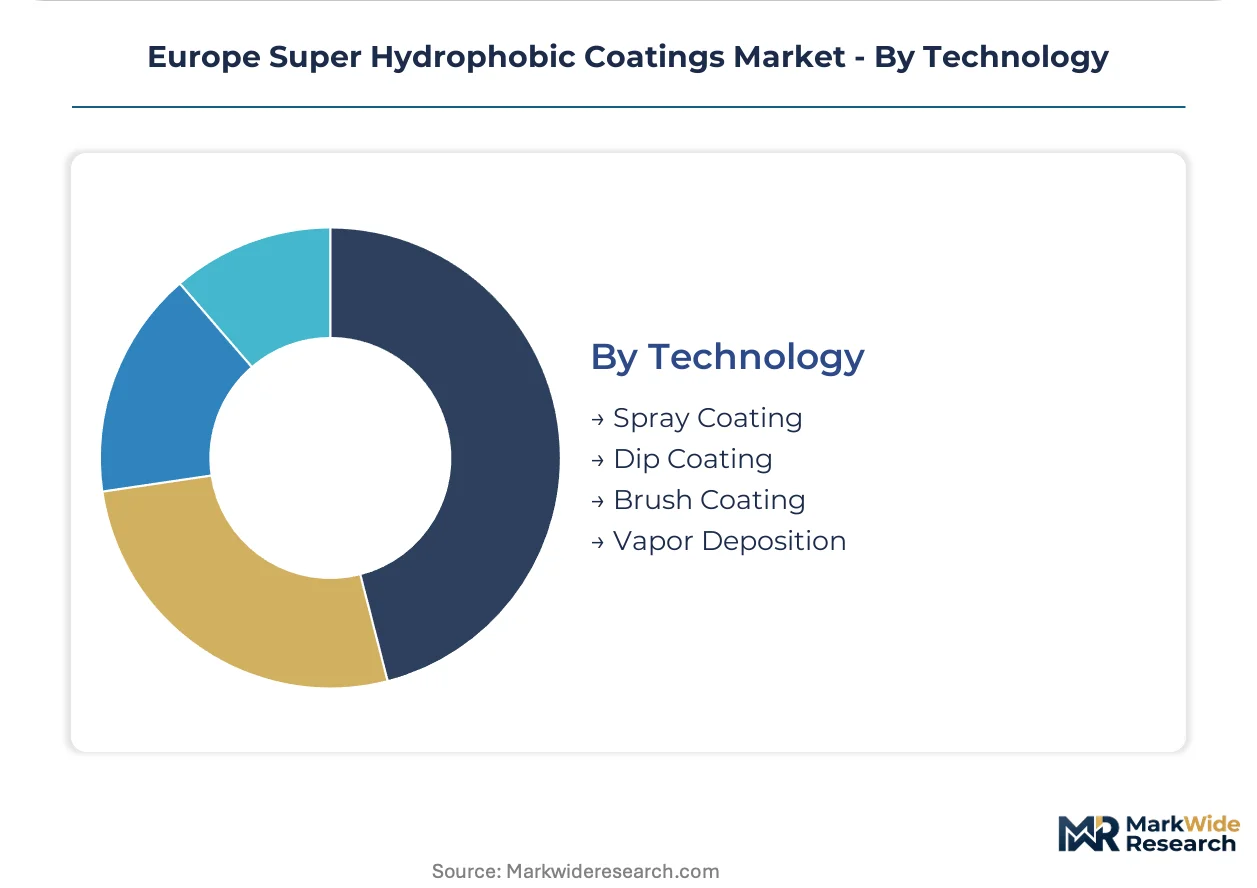
Technology:
Capital intensity and throughput scalability separate mass-production spray methods from precision vapor deposition systems concentrated among German and Swiss equipment builders.
- Spray Coating:Airless and electrostatic spray systems integrate with existing automotive paint lines. BASF SE leverages Ludwigshafen polymer research to optimize formulation viscosity for robotic application.
- Vapor Deposition:Plasma-enhanced chemical vapor deposition enables conformal coating of complex electronics geometries. Equipment supply concentrates among German and Swiss builders, creating capex bottlenecks.
- Dip Coating:Batch immersion suits small medical device components and textile finishing. Lower capital barriers attract mid-tier applicators.
- Brush Coating:Manual application persists in construction retrofit and maintenance repair operations. Labor intensity limits scalability.
Widest deployment: Spray Coating. Gaining share fastest: Vapor Deposition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for super hydrophobic coatings concentrates in German, French, and Italian industrial clusters where automotive OEMs and aerospace maintenance operations anchor procurement volumes. REACH compliance timelines and EU F-Gas Regulation quotas are reshaping supplier geography across the continent.
Germany
Automotive OEM specification drives volume through Stuttgart and Munich assembly networks, where tier-one suppliers consolidate coating procurement for underbody protection. KBA vehicle type approval requirements intersect with REACH registration deadlines, forcing reformulation investments. BASF SE leverages its Ludwigshafen polymer research campus to sustain formulation leadership for spray-applied systems.
France
Aerospace maintenance, repair, and overhaul operations in Toulouse anchor fluoropolymer demand for landing gear and control surface protection. ANSM biocompatibility evaluation pathways under EU MDR open medical device coating specifications. The Paris-Saclay research cluster hosts nano-structured coating development programs targeting reduced environmental persistence.
Italy
Precision manufacturing in Lombardy and Emilia-Romagna consumes industrial equipment coatings where salt-spray resistance commands specification priority. CE marking under the Construction Products Regulation enables self-cleaning facade specifications in Milan and Rome renovation markets. Italian textile finishers in Como and Prato drive nano-structured silica demand for technical workwear.
United Kingdom
Electronics vapor deposition demand concentrates in Cambridge and Oxfordshire technology clusters, where moisture barrier specifications protect smartphone and wearable device components. The UK's divergence from EU chemical hazard classifications creates parallel compliance obligations for coating suppliers serving both markets. P2i Ltd anchors its position through plasma-enhanced deposition technology.
Spain
Building envelope retrofit applications dominate procurement in Madrid and Barcelona, where labor cost reduction drives material selection for self-cleaning facade coatings. Spanish solar energy installations specify hydrophobic barrier layers for panel efficiency maintenance. ECHA substance evaluation protocols extend testing timelines for nano-structured coatings entering the Iberian market.
Europe Super Hydrophobic Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid chemistry and bio-based feedstock partnerships. The European vendor base fragments across integrated chemical conglomerates, specialized coating houses, and equipment-integrated applicators. Three archetypes dominate: polymer research-led formulators, vapor deposition technology specialists, and marine-industrial diversified players. Competitive intensity concentrates on REACH-compliant reformulation speed and captive spray capacity investments at OEM assembly locations.
Among research-integrated chemical producers, BASF SE exemplifies the formulation-led archetype through its Ludwigshafen polymer campus operations. P2i Ltd occupies a distinct position as a vapor deposition technology specialist serving electronics moisture protection requirements. AkzoNobel N.V. represents the diversified industrial coating house competing across marine and infrastructure segments where salt-spray resistance specifications apply.
| Leading Market Players |
|---|
| P2i Ltd |
| BASF SE |
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| 3M Company |
| NEI Corporation |
| Aculon, Inc. |
| UltraTech International Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between REACH-compliant hybrid formulations and legacy fluoropolymer systems manifests in both pricing power concentration and supply chain restructuring across European coating houses. Premium procurement for aerospace landing gear applications commands sustained margins while automotive underbody protection faces cost-per-vehicle compression, splitting supplier investment between captive spray capacity and reformulation R&D.
Pricing Analysis
Volume-margin splits sharply across chemistry tiers. Polymer-based dispersions for automotive underbody protection operate on contract-based long-term offtake with German OEMs, where volume scale and REACH registration status drive price differentiation. Fluoropolymer coatings for aerospace maintenance command value-based premiums anchored in FAA-EASA dual certification requirements. Cost compression in silane-based alternatives is intensifying because EU F-Gas Regulation quotas constrain perfluorinated feedstock availability. Tier-one automotive suppliers exhibit highest price sensitivity, while aerospace MRO operations prioritize performance durability over material cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision spray and vapor deposition equipment builders, creating capex bottlenecks for mid-tier applicators seeking market entry. Raw material sourcing draws from Belgium for fluorinated precursors, Germany for organosilane feedstocks, and the Netherlands for nano-structured silica. Regulatory restriction through REACH substance evaluation protocols extends lead times for new formulation clearance. Distribution runs through integrated chemical conglomerates with captive polymer research campuses and specialized coating houses serving vertical-specific qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European super hydrophobic coatings constitute a supply-constrained market where fluorinated precursor scarcity under EU F-Gas quotas props pricing power for reformulation-capable suppliers.
For Market Incumbents: Deepen backward integration into bio-based silane feedstock partnerships to secure input supply against F-Gas quota constraints. Expand captive spray capacity at Stuttgart and Munich assembly plant locations to absorb forward inventory risk from OEM specification consolidation. Lock in five-year single-source agreements with volume guarantees before hybrid chemistry patents expire. For New Entrants and Emerging Players: Launch via industrial laundry and rental uniform networks to access textile finishing procurement channels without confronting automotive OEM qualification barriers. Target Spanish and Italian building envelope retrofit segments where CE marking requirements are less stringent than aerospace certification and labor cost reduction drives material selection over brand loyalty. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid chemistry specialists given REACH-compliant reformulation speed advantages over legacy fluoropolymer incumbents. Five-to-ten year viability hinges on patent-protected deposition processes and ECHA substance evaluation clearance backlogs. Watch for ANSM biocompatibility certification milestones under EU MDR as inflection indicators for medical device coating specification capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures silane supply chains against EU F-Gas quota constraints for coating manufacturers. |
| Captive Spray Capacity Expansion | Locks in automotive OEM single-source agreements at Stuttgart and Munich assembly locations. |
| Hybrid Chemistry Patent Filing | Creates first-mover advantage through ECHA substance evaluation clearance ahead of competitors. |
| ANSM Biocompatibility Certification | Opens EU MDR pathways for catheter and implant coating specifications in cardiovascular applications. |
| Long-Term Equipment Supply Agreement | Mitigates single-source vulnerability to German and Swiss vapor deposition system builders. |
Research Methodology
Independent corroboration across ECHA substance evaluation databases, EU F-Gas Regulation quota disclosures, and Cefic chemical production statistics underwrites the qualitative findings. Primary interviews with coating R&D directors, automotive tier-one procurement leads, aerospace MRO specification engineers, and industrial textile finishers combined with secondary validation from REACH registration filings, customs trade data, and SEC 10-K disclosures from listed chemical producers. Bottom-up volume estimates from application-specific deposition rates triangulate against top-down market sizing from polymer feedstock consumption patterns.
Rate-of-change decomposition across the analysis window segments volume and value by chemistry type, end-use vertical, deposition technology, and regional production cluster. CAGRs derive from regression analysis of historical automotive production data, aerospace MRO cycle frequencies, and electronics manufacturing output indexed to coating content per unit. Industry-specific forecast inputs include ECHA substance evaluation pipeline timelines and EU F-Gas phase-down trajectory assumptions.
REACH registration deadline delays, ECHA nano-toxicology assessment capacity constraints, and automotive OEM specification consolidation are the dominant revision risks. Forecasts reflect documented assumptions on regulatory compliance timelines and feedstock substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Water-Based Alkyd Coatings Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Global Conformal Coatings Market
Coatings
Global Smart Coating Market
Coatings
Sustained Release Coatings Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Global Coated Steel Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Heavy Duty Glass Coating Market
Coatings
Global Floor Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Extrusion Coating Market
Coatings
BPA-Free Coatings Market