
 Polypropylene Foams Market | 2026-2036
Polypropylene Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Foams Market Analytics
Performance-grade polypropylene foam is decoupling from commodity sheet supply on the basis of bead consistency, compression set resilience, and OEM qualification cycles. BASF SE leverages its Styropor-derived process knowledge to sustain premium positioning in automotive seat cores. Kaneka Corporation anchors Asian supply through its Eperan bead foam platform, while JSP Corporation dominates North American automotive cushioning with its Arpro molded particle technology.
Polypropylene foams are closed-cell thermoplastic structures produced from polypropylene resin via physical or chemical expansion, typically achieving densities between 20 and 200 kg/m³ for load-bearing and thermal insulation functions. Expanded Foam leads volume due to mature bead molding infrastructure, while Injection Moulded Foam captures margin pools in complex automotive interior components requiring tight dimensional tolerance. The Building & Construction end user segment channels demand toward laminated sheet configurations for wall insulation, though Automotive remains the dominant value sink through energy-absorbing bumper cores and door panel inserts.
The US EPA and NHTSA coordinate fuel-economy standards that reward vehicle weight reduction, directly incentivizing polypropylene foam substitution in interior assemblies. REACH and RoHS frameworks in Europe restrict halogenated flame retardants, compelling reformulation of compounded polypropylene foam grades for electronics packaging and construction applications. Stakeholders must monitor evolving OEM qualification protocols for recycled content integration, as post-consumer polypropylene feedstock certification becomes a gate for supplier retention in closed-loop automotive programs.
Market Dynamics
Automotive lightweighting mandates and thermal insulation efficiency codes are compressing material selection cycles, forcing polypropylene foam suppliers to synchronize bead consistency certification with OEM platform timelines.
Growth Catalysts
- MIIT Fuel-Efficiency Mandates:China's Ministry of Industry and Information Technology enforces corporate average fuel consumption targets that reward vehicle weight reduction through expanded polypropylene bead foam adoption in seating and bumper systems.
- EU F-Gas Regulation:The phasedown of high-GWP blowing agents redirects building insulation demand toward physically expanded polypropylene foams with lower climate impact profiles.
- Bead Molding Infrastructure:Mature expanded polypropylene molding networks in East Asian manufacturing clusters enable rapid prototyping for automotive interior components with tight dimensional tolerances.
Market Restraints
- Propylene Feedstock Volatility:Naphtha-cracking economics and shale-gas differentials inject cost instability into polypropylene resin pricing, compressing foam processor margins.
- Asian Supply Concentration:Bead foam production clusters in Japan and South Korea create geographic risk exposure for European and North American automotive Tier-1 suppliers.
- Halogenated Flame-Retardant Restrictions:REACH and RoHS frameworks in Europe compel reformulation of compounded grades, extending qualification timelines for electronics packaging applications.
Strategic Opportunities
- India Automotive Localization:PLI scheme incentives for electric vehicle manufacturing create white space for molded polypropylene foam suppliers establishing domestic bead production.
- Recycled Content Certification:Post-consumer polypropylene feedstock verification protocols are becoming gate criteria for supplier retention in closed-loop automotive programs.
- HVAC Ducting Convergence:Thermal-acoustic insulation specifications for heat-pump systems are absorbing polymer foam substitution from legacy fiberglass and mineral wool.
Industry Challenges
- OEM Qualification Compression:Platform development cycles have shortened below 24 months, forcing foam suppliers to parallel-track material validation with die engineering.
- Bead Consistency Talent Scarcity:Process engineering expertise for controlling expansion ratio uniformity resides with a narrow cohort of specialists nearing retirement.
- Multi-Material Bonding Complexity:Laminated sheet configurations for wall insulation require adhesive systems compatible with polypropylene's low surface energy, complicating installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Foams Market |
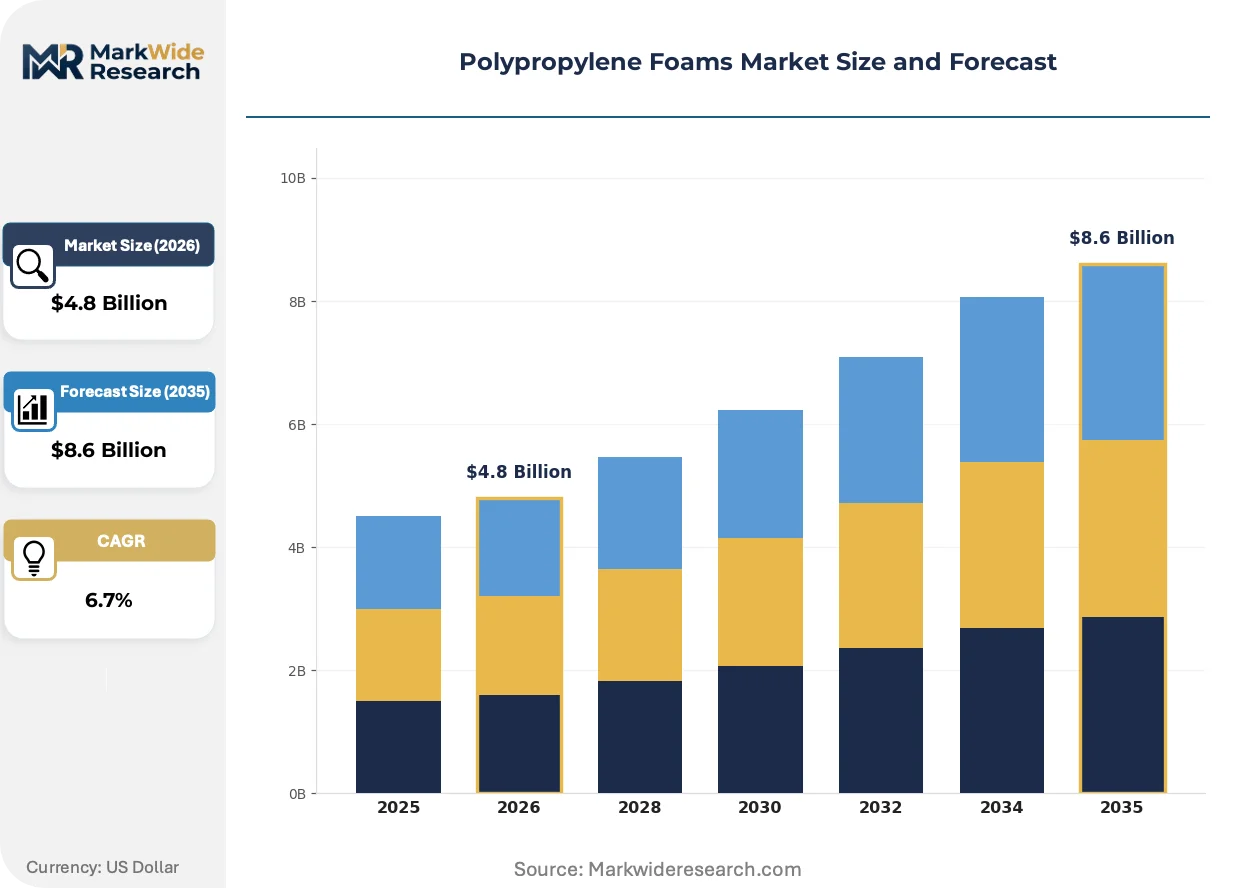
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Foam, Laminated Foam, Coated Foam, Injection Moulded Foam End User: Automotive, Packaging, Consumer Goods, Building & Construction Application: Insulation, Cushioning, Soundproofing, Sealing Form: Sheets, Rolls, Blocks, Shapes |
| Companies Covered | BASF SE, Kaneka Corporation, Hanwha Corporation, Mitsui Chemicals Inc., Borealis AG, Furukawa Electric Co., Ltd., JSP Corporation, SABIC, Pregis Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Foams Market Evolving Landscape
Physical expansion processes and closed-cell structural engineering are displacing chemical blowing agent dependence, while regulatory chemistry restrictions accelerate material redesign across automotive and construction supply chains.
High-pressure physical foaming technology is absorbing investment from European and Japanese equipment suppliers seeking to eliminate residual blowing agent emissions. Tier-1 seating manufacturers in Germany are adopting these systems for bumper core production, compressing the qualification window for traditional bead foam grades. The technology is absorbing market share in load-bearing applications where compression set resilience determines warranty exposure.
REACH authorization procedures for halogenated flame retardants are compelling reformulation of electronics packaging and construction grades toward phosphorus-nitrogen synergists. Compounders in the Netherlands and Belgium are scaling alternative masterbatch production to serve automotive interior specifications. Building & Construction applications face the steepest compliance curve, with laminated sheet producers accelerating testing of intumescent coating compatibility.
Automotive procurement departments are consolidating supplier panels around vertically integrated resin-to-foam processors capable of certifying recycled content streams. German OEMs now require mass-balance documentation for seat core materials, displacing spot-market resin sourcing. This concentration is most visible in Bavaria and Baden-Württemberg manufacturing corridors, where platform engineering teams co-locate with material qualification labs.
Polypropylene Foams Market Segmentation
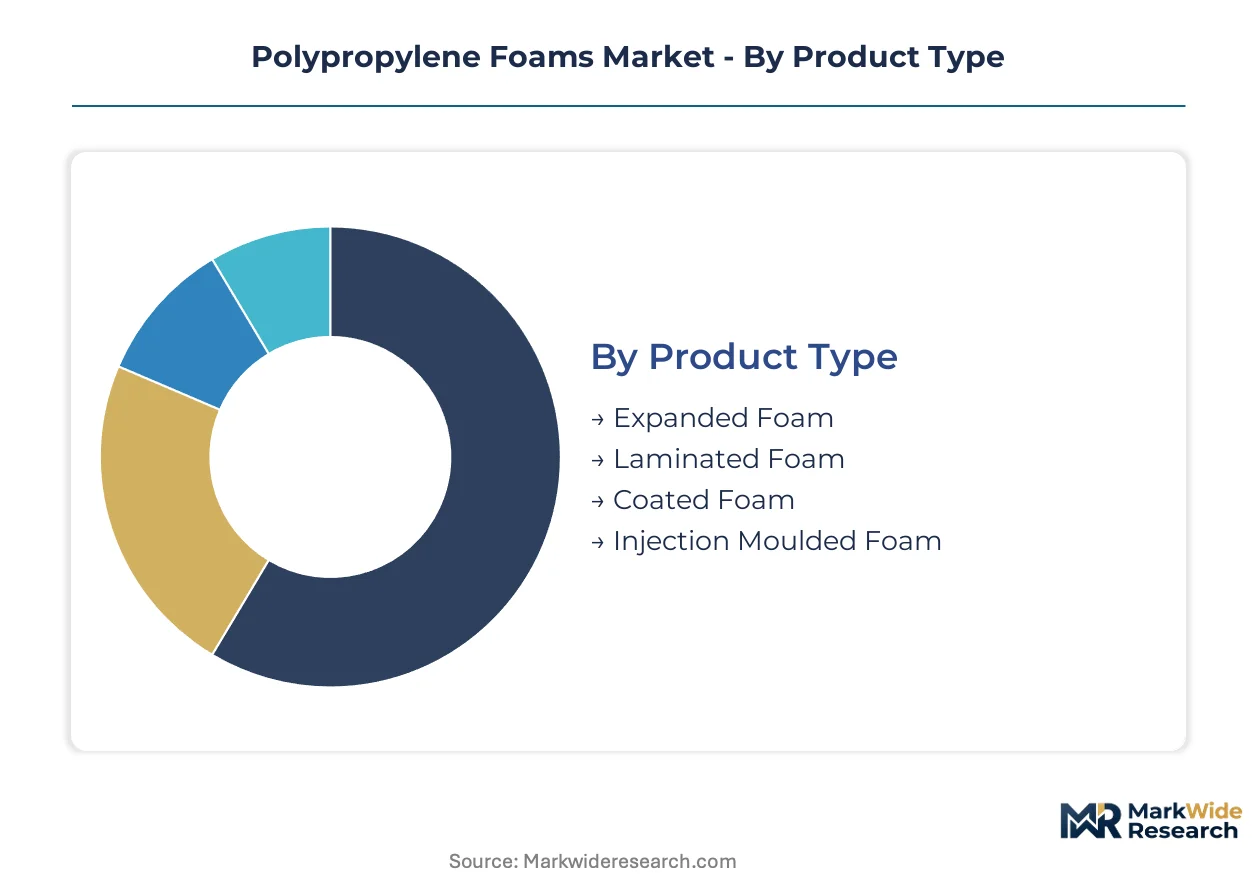
Polypropylene foam specifications diverge sharply across certification regimes. MIIT automotive qualification, REACH chemical compliance, and OEM recycled-content protocols each gate access to distinct revenue pools.
Product Type:
MIIT fuel-efficiency mandates and EU F-Gas phasedown schedules impose divergent certification burdens on each process technology.
- Expanded Foam:Physical expansion of polypropylene beads yields densities between 20 and 80 kg/m³ for energy-absorbing structures. German and Japanese OEMs concentrate procurement for seat cores and bumper systems where compression set resilience determines warranty exposure.
- Injection Moulded Foam:High-pressure physical foaming achieves complex geometries with tight dimensional tolerances for automotive interior components. East Asian manufacturing clusters absorb capacity expansion as platform development cycles compress below 24 months.
- Laminated Foam:Multi-layer sheet configurations serve Building & Construction wall insulation where REACH flame-retardant restrictions compel phosphorus-nitrogen synergist reformulation.
- Coated Foam:Surface-treated grades address low-surface-energy bonding challenges in laminated construction panels and specialty packaging applications.
Expanded Foam sits at the top of the volume ranking, with Injection Moulded Foam climbing the fastest.
End User:
Customer procurement patterns split between specification-heavy automotive programs and price-sensitive packaging contracts.
- Automotive:US EPA and NHTSA fuel-economy standards reward vehicle weight reduction through expanded bead foam adoption in seating, door panels, and bumper cores. German OEMs now require mass-balance documentation for seat core materials.
- Building & Construction:EU F-Gas Regulation redirects insulation demand toward physically expanded foams with lower GWP profiles. Laminated sheet configurations dominate wall insulation specifications.
- Packaging:Electronics and consumer goods applications face REACH and RoHS halogenated flame-retardant restrictions, extending qualification timelines for compounded grades.
- Consumer Goods:Sporting equipment and furniture applications prioritize cost efficiency over certification complexity, sourcing standard expanded foam grades.
Automotive commands the highest margin tier, with Building & Construction gaining share fastest on regulatory tailwinds.
Application:
Functional performance requirements dictate material density, cell structure, and additive loading across use cases.
- Insulation:Closed-cell structures with low thermal conductivity serve HVAC ducting and building envelope applications where China's dual carbon goals and EU energy codes drive specification upgrades.
- Cushioning:Compression set resilience and durability specifications dominate automotive seating and protective packaging procurement in Germany, Japan, and the United States.
- Soundproofing:Acoustic absorption coefficients determine specification for automotive NVH reduction and construction partition systems.
- Sealing:Gasket and weatherstrip applications require controlled compression-deflection characteristics for automotive and industrial use.
Cushioning holds the largest installed base, with Insulation expanding most quickly on heat-pump system adoption.
Form:
Supply chain configuration and installation labor economics shape form factor selection across end-use segments.
- Sheets:Flat-stock configurations serve construction lamination and industrial fabrication where adhesive compatibility with polypropylene's low surface energy remains a technical constraint.
- Rolls:Continuous-web formats enable automated processing in packaging and automotive component manufacturing.
- Blocks:Bun stock for CNC machining and custom fabrication serves low-volume specialty applications and prototyping.
- Shapes:Molded and die-cut configurations deliver finished geometry for direct assembly, minimizing downstream processing steps.
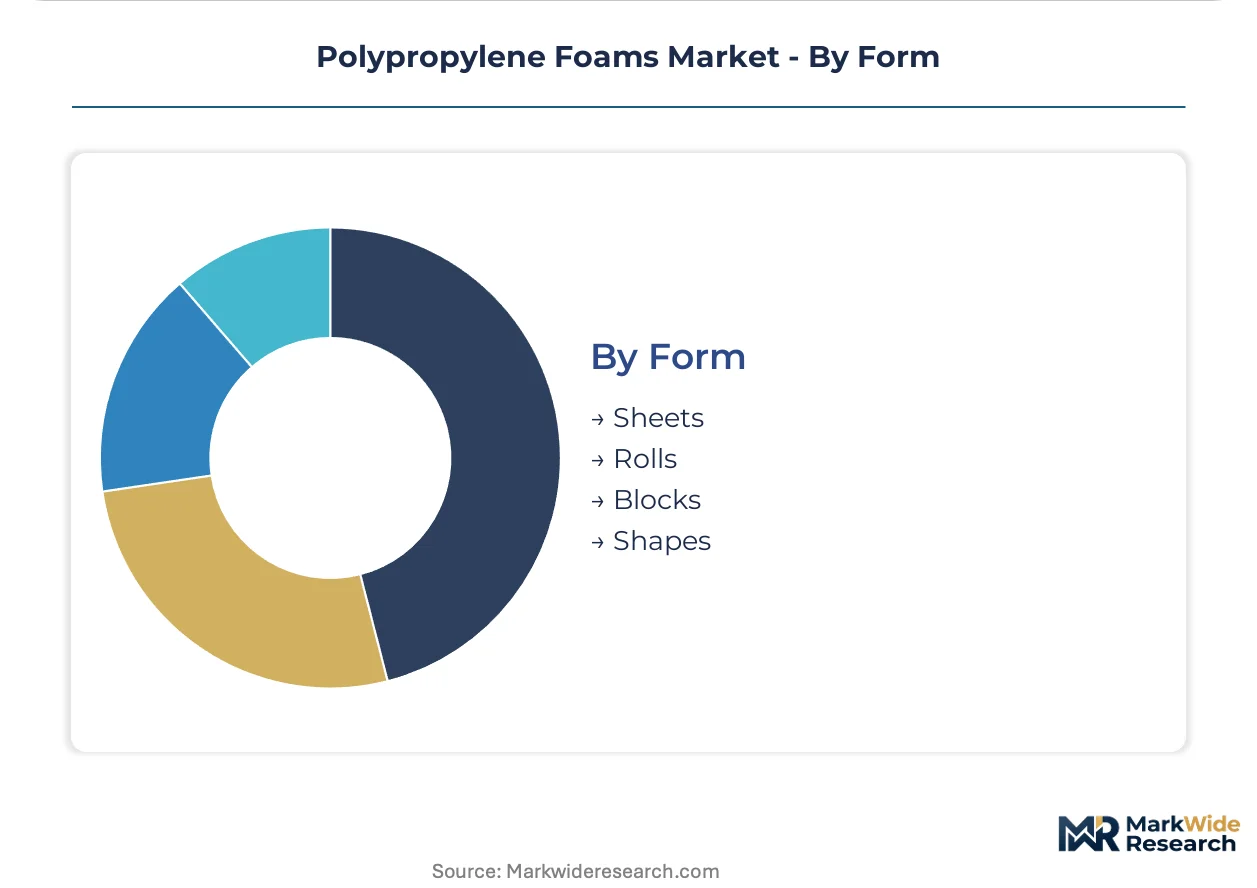
Sheets dominate construction and industrial volume, with Shapes capturing margin expansion through value-added conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers for bead consistency certification concentrate in German automotive corridors, Japanese chemical manufacturing clusters, and Chinese industrial zones serving MIIT-mandated lightweighting programs.
United States
Automotive seating and bumper core procurement absorbs expanded polypropylene volumes as EPA and NHTSA fuel-economy standards reward vehicle weight reduction. Domestic OEMs require mass-balance documentation for recycled content integration. Michigan and Ohio manufacturing corridors host Tier-1 suppliers synchronizing bead foam qualification with platform engineering timelines.
Germany
Bavaria and Baden-Württemberg anchor European demand for compression-set-resilient seat cores and energy-absorbing structures. REACH authorization procedures for halogenated flame retardants compel reformulation of compounded grades. Platform engineering teams co-locate with material qualification labs to compress development cycles below 24 months.
China
MIIT corporate average fuel consumption targets redirect procurement toward expanded bead foam in seating and HVAC ducting applications. Yangtze River Delta and Pearl River Delta manufacturing clusters absorb capacity expansion for heat-pump system insulation. Dual carbon goals accelerate specification upgrades for building envelope applications.
Japan
METI industrial standards and automotive OEM qualification protocols govern bead foam adoption in interior assemblies. Chubu and Kansai manufacturing zones maintain mature expanded polypropylene molding infrastructure. Process expertise for controlling expansion ratio uniformity resides with specialist engineers nearing retirement.
India
PLI scheme incentives for electric vehicle manufacturing create white space for molded polypropylene foam suppliers establishing domestic bead production. Maharashtra and Tamil Nadu automotive corridors attract Tier-1 seating manufacturers seeking localization. BIS standards for automotive materials are converging with OEM recycled-content verification protocols.
Polypropylene Foams Market Competitive Landscape
Top-tier vendors anchor premium automotive qualification tiers, while mid-scale compounders occupy construction and packaging segments. The vendor base stratifies around resin-to-foam vertical integration, bead molding specialization, and regional distribution density. Three archetypes dominate: integrated petrochemical-to-foam processors, independent bead foam specialists, and construction-focused sheet laminators. Capacity expansion and recycled-content certification represent the dominant competitive moves.
Within the integrated processor tier, BASF SE and Kaneka Corporation exemplify archetypes combining resin supply control with OEM qualification depth. JSP Corporation occupies a position representing North American automotive cushioning specialization. These three anchors demonstrate how geographic concentration of process engineering talent reinforces competitive positioning across distinct regional demand centers.
| Leading Market Players |
|---|
| BASF SE |
| Kaneka Corporation |
| Hanwha Corporation |
| Mitsui Chemicals Inc. |
| Borealis AG |
| Furukawa Electric Co., Ltd. |
| JSP Corporation |
| SABIC |
| Pregis Corporation |
| Others |
Value Network & Pricing Analysis
High-pressure physical foaming adoption in German and Japanese automotive corridors is simultaneously compressing production cost curves and concentrating supply among equipment-integrated processors capable of certifying bead consistency at OEM-specified tolerances.
Pricing Analysis
Resin-to-foam bundled service contracts dominate automotive procurement, separating mass-balance-certified premium grades from spot-market commodity sheet. Price differentiation rests on OEM qualification depth and recycled-content verification tier. Cost compression in standard expanded foam is intensifying because naphtha-cracking economics inject volatility into propylene feedstock. Packaging buyers exhibit highest price sensitivity; German automotive seating procurement shows lowest, prioritizing compression set resilience over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for platform-standardized seat cores and bumper systems. Supply concentrates in Germany, Japan, and China, with bead molding infrastructure anchored in Bavarian automotive corridors and Chubu manufacturing zones. Raw material flows draw from naphtha crackers, polypropylene resin compounders, and phosphorus-nitrogen flame-retardant masterbatch suppliers. Single-source vulnerability resides with specialist process engineers controlling expansion ratio uniformity. Distribution runs through Tier-1 seating manufacturers co-located with OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in polypropylene foams rests on physical foaming technology cost-down curves and premium-tier pull from mass-balance-certified automotive grades.
For Market Incumbents: Lock in OEM qualification cycles by co-locating technical service teams with Bavaria and Baden-Württemberg platform engineering corridors. Deepen backward integration into post-consumer polypropylene feedstock streams before recycled-content verification becomes a supplier retention gate. Defend against high-pressure physical foaming entrants by accelerating bead consistency certification timelines below 18 months.
For New Entrants and Emerging Players: Capture white space in Indian PLI-scheme electric vehicle corridors where domestic bead production capacity lags demand. Target HVAC ducting specifications for heat-pump systems absorbing polymer foam substitution from mineral wool. Lead with laminated sheet configurations for Building & Construction wall insulation where REACH flame-retardant reformulation disrupts incumbent supply.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent bead foam specialists lacking resin supply control but holding OEM qualification depth. Five-to-ten year viability favors processors with verified post-consumer feedstock streams and East Asian manufacturing footprint. Watch MIIT fuel-efficiency mandate tightening as inflection indicator for Chinese demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Mass-balance certification secures supplier retention in German OEM closed-loop programs. |
| High-Pressure Physical Foaming Capacity Expansion | Eliminates residual blowing agent emissions for EU F-Gas Regulation compliance. |
| Joint Venture in Indian Automotive Corridor | PLI scheme incentives accelerate localization for electric vehicle seating demand. |
| Phosphorus-Nitrogen Masterbatch Scale-Up | REACH authorization timelines compel halogen-free reformulation for construction grades. |
| Long-Term Supply Agreement with Heat-Pump OEM | Thermal-acoustic specifications absorb polymer foam substitution from fiberglass ducting. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from polypropylene foam plant managers, automotive Tier-1 procurement leads, OEM platform engineers, construction distribution channel partners, and chemical R&D directors specializing in physical expansion processes. Secondary validation drew from customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings of integrated petrochemical processors, and vehicle production registration data. Bottom-up bead molding capacity estimates triangulated against top-down automotive content-per-vehicle calculations.
Historical reference periods anchored volume and value trajectories across the analysis window. The forecasting framework modeled segmentation across product type, end-use industry, application function, and regional production hub. CAGRs were derived from slope analysis of qualification-corrected adoption curves. Key inputs included MIIT corporate average fuel consumption target trajectories, EU F-Gas phasedown schedules, and OEM platform development cycle compression trends.
Underlying measurement precision varies by segment; automotive seating specifications carry tighter precision than construction packaging grades. Forecasts reflect assumptions around propylene feedstock cost stability, REACH authorization timelines for flame-retardant chemistry, and OEM recycled-content mandate adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Technical Foam Market