
 UV Coatings Market | 2026-2036
UV Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
UV Coatings Market Outlook
Automotive OEMs is rotating toward UV-cured clearcoats as sustainability mandates tighten across passenger vehicle production. PPG Industries leverages its integrated resin supply to dominate North American automotive finishing programs. BASF SE sustains R&D intensity in waterborne UV hybrids for European regulatory compliance. AkzoNobel NV anchors marine and industrial maintenance demand through specialized photoinitiator formulations.
UV coatings are photochemically reactive liquid or powder systems that polymerize upon exposure to ultraviolet radiation in the 200–400 nanometer range, typically incorporating oligomers, monomers, photoinitiators, and functional additives to achieve instant cure without thermal energy input. Acrylic formulations lead volume due to their optical clarity and adhesion versatility across substrates, while polyurethane segments command premium positioning in abrasion-intensive automotive and electronics applications where scratch resistance determines specification approval. Powder UV systems represent the fastest-growing form category as manufacturers eliminate solvent handling costs and volatile organic compound reporting burdens.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that directly limit solvent content in coating operations, compelling facility upgrades toward UV curing infrastructure. REACH registration requirements in Europe restrict certain photoinitiator chemistries, redirecting formulation investment toward benzophenone-free alternatives. China's MEE implements parallel emission controls that favor domestic UV coating adoption in Yangtze River Delta manufacturing clusters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets and misaligned capacity investments.
Market Dynamics
Photoinitiator chemistry evolution and REACH-driven reformulation mandates are compressing product development cycles while fragmenting supply chains across European and North American coating operations.
Growth Catalysts
- REACH Annex XVII restrictions on benzophenone:Formulators accelerate migration to amine synergist alternatives, expanding addressable market for Type II photoinitiator suppliers serving automotive OEM clearcoat programs.
- China Yangtze River Delta manufacturing clusters:MEE emission enforcement drives domestic UV line adoption among electronics contract manufacturers seeking solvent-free conformal coating capabilities.
- Dual-cure hybrid systems:Moisture-cure secondary mechanisms enable UV coating penetration into shadow-cure geometries previously excluded from radiation-cured specifications.
Market Restraints
- Acrylate monomer supply concentration:German and Chinese petrochemical producers control upstream specialty acrylate feedstocks, exposing formulators to input cost volatility during olefin cycle swings.
- Mercury lamp phase-out timelines:Minamata Convention ratification deadlines force premature capital retirement for installed mercury vapor curing infrastructure before LED UV equipment cost parity.
- Thermoset epoxy substitution in thick-film applications:Electronics potting and automotive underbody segments retain thermal-cure systems where UV penetration depth limitations prevent specification capture.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Smartphone and component assembly localization creates greenfield UV coating line demand without legacy solvent infrastructure displacement costs.
- UV-cured powder on temperature-sensitive substrates:Wood and plastic finishing applications previously excluded from powder coating thermal windows open through low-temperature photopolymerization.
- Waterborne UV hybrid convergence:Formulators combining aqueous dispersion stability with radiation cure speed target furniture and flooring segments under tightening EPA NESHAP woodworking facility standards.
Industry Challenges
- Photoinitiator stability expertise gap:Formulation chemists with combined radiation chemistry and shelf-life stabilization experience command premium compensation, constraining R&D team scaling.
- Legacy thermal-cure line retrofit complexity:Automotive finishing plants face production downtime penalties during UV oven and conveyor reconfiguration, delaying payback period calculations.
- Photoinitiator migration testing protocols:Food-contact and toy applications require extended migration study timelines under EFSA and FDA guidelines, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Coatings Market |
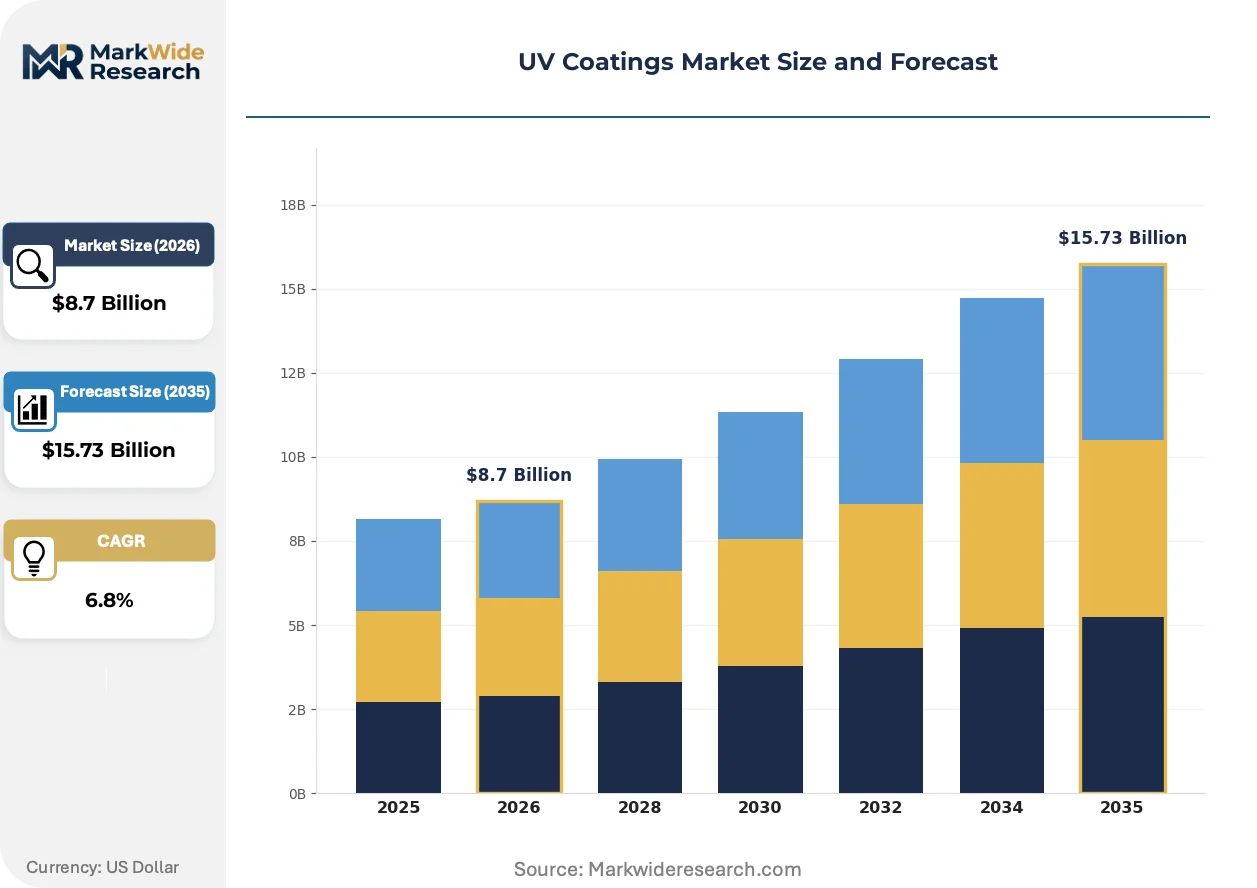
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Epoxy, Polyester Application: Automotive, Electronics, Wood Finishing, Packaging End User: Manufacturers, Retailers, Contractors, Exporters Form: Liquid, Powder, Gel, Emulsion |
| Companies Covered | AkzoNobel NV, PPG Industries, BASF SE, The Dow Chemical Company, The Sherwin-Williams Company, DIC Corporation, Dymax Corporation, Axalta Coating Systems, Royal DSM NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Coatings Market Strategic Shifts
Formulation architectures are diverging between high-performance industrial specifications and cost-optimized decorative applications, with equipment manufacturers racing to match lamp technology with chemistry advances.
LED UV curing systems operating at 395 nanometer peak wavelength are fragmenting equipment investment patterns across the installed base. Automotive tier suppliers in Stuttgart and Detroit accelerate LED retrofits to eliminate mercury handling compliance and reduce energy intensity. The technology is fragmenting supplier consolidation patterns as Chinese LED array manufacturers bypass traditional mercury lamp incumbents.
EPA NESHAP Subpart HHHHHH enforcement intensifies for miscellaneous metal coating operations, compelling job shops toward UV conversion or shutdown. Small and mid-size coating applicators in Ohio and Michigan face capital constraints that favor toll-coating partnerships over in-house UV line investment. Wood furniture segments in North Carolina experience the most acute compliance pressure due to concentrated EPA regional office inspection activity.
Specification consolidation among automotive OEMs compresses approved vendor lists for exterior clearcoat programs. Tier-1 suppliers must maintain dual UV and thermal-cure competency to serve mixed-model assembly lines. Procurement teams at German premium manufacturers now mandate carbon footprint disclosure alongside technical performance, favoring European photoinitiator suppliers with verified renewable feedstock pathways.
UV Coatings Market Segmentation
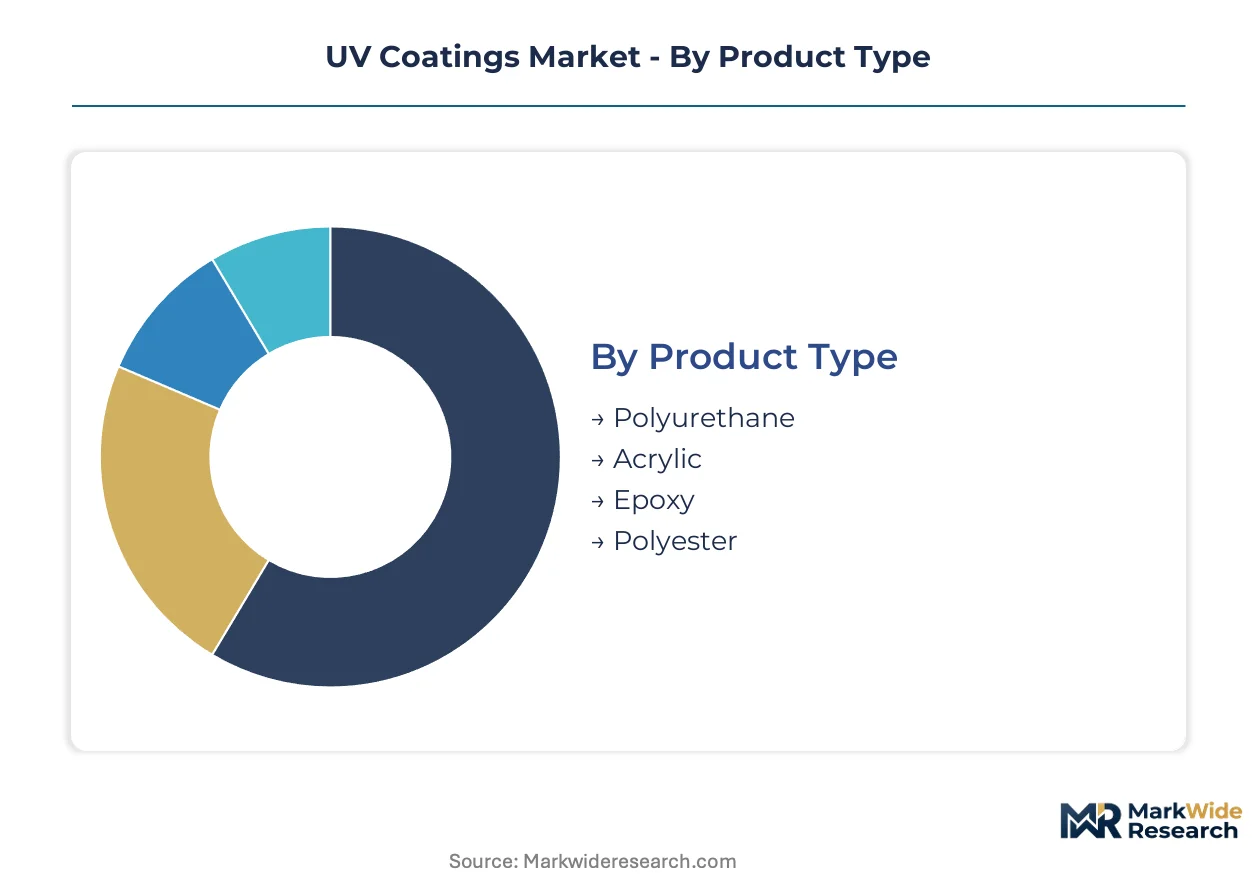
UV coatings segment along four distinct axes that determine specification pathways, procurement channels, and margin structures. Product chemistry governs performance ceilings in abrasion and optical clarity. Application verticals dictate regulatory exposure and cure system requirements. End-user categories separate volume contracting from specification influence. Form factor determines equipment capital requirements and solvent handling obligations.
Product Type:
Channel flows diverge sharply between commodity acrylics moving through distributors and specification-grade polyurethanes locked in direct OEM programs.
- Polyurethane:Aliphatic isocyanate-urethane networks deliver exceptional scratch resistance and weathering stability for automotive clearcoats and consumer electronics housings. German premium automotive OEMs specify these formulations for exterior programs where gloss retention determines warranty exposure. REACH Annex XVII pressures on aromatic photoinitiators are redirecting R&D toward aliphatic alternatives with equivalent reactivity.
- Acrylic:Ester-functional oligomers polymerize rapidly under UV exposure to yield optically clear films with versatile substrate adhesion. Wood furniture manufacturers in North Carolina and packaging converters in the Yangtze River Delta procure these through regional distributor networks serving mid-volume job shops. Acrylics dominate volume throughput due to formulation flexibility and raw material availability.
- Epoxy:Cationic cure mechanisms suit thick-film applications where oxygen inhibition compromises radical systems.
- Polyester:Unsaturated backbone structures target cost-sensitive industrial maintenance and general metal finishing.
Polyurethane commands specification premiums in automotive and electronics. Acrylics anchor volume expansion in packaging and decorative wood.
Application:
Regulatory intensity varies dramatically across end-use verticals, with automotive and electronics facing the most stringent emission and migration testing protocols.
- Automotive:Exterior clearcoat and interior trim applications demand UV-cured finishes that meet OEM scratch resistance and chemical exposure specifications. Tier-1 suppliers in Stuttgart and Detroit maintain dual-cure capability to serve mixed-model assembly lines. LED retrofit investments are accelerating as mercury lamp phase-out deadlines approach under Minamata Convention obligations.
- Electronics:Conformal coatings and device housings require low-VOC finishes compatible with temperature-sensitive substrates. Contract manufacturers in China's Pearl River Delta and India's NCR region are installing UV lines under PLI scheme incentives and MEE enforcement pressure. Dual-cure hybrids penetrate shadow-cure geometries in complex PCB assemblies.
- Wood Finishing:Furniture and flooring applications face concentrated EPA NESHAP enforcement in North Carolina and Ohio.
- Packaging:Food-contact and pharmaceutical applications require extended migration study timelines under FDA and EFSA guidelines.
Automotive concentrates value per liter. Electronics is expanding most quickly through Asia-Pacific manufacturing localization.
End User:
Procurement authority separates volume aggregators from specification gatekeepers, with manufacturers capturing direct formulation relationships.
- Manufacturers:OEMs and tier suppliers with in-house coating operations specify directly with formulators, locking in photoinitiator chemistry and cure system parameters. These relationships span multi-year program cycles with embedded technical service requirements.
- Retailers:Private-label furniture and consumer electronics brands procure finished goods with coating specifications delegated upstream to contract manufacturers.
- Contractors:Job shops and finishing service providers purchase through distribution, prioritizing shelf stability and application latitude over performance extremes.
- Exporters:Trading companies serving emerging markets aggregate demand across fragmented regional requirements.
Manufacturers dominate specification capture. Contractors represent the channel where distributor relationships consolidate.
Form:
Capital intensity and regulatory burden separate liquid systems from powder alternatives, with emulsion formats bridging waterborne compliance and radiation cure speed.
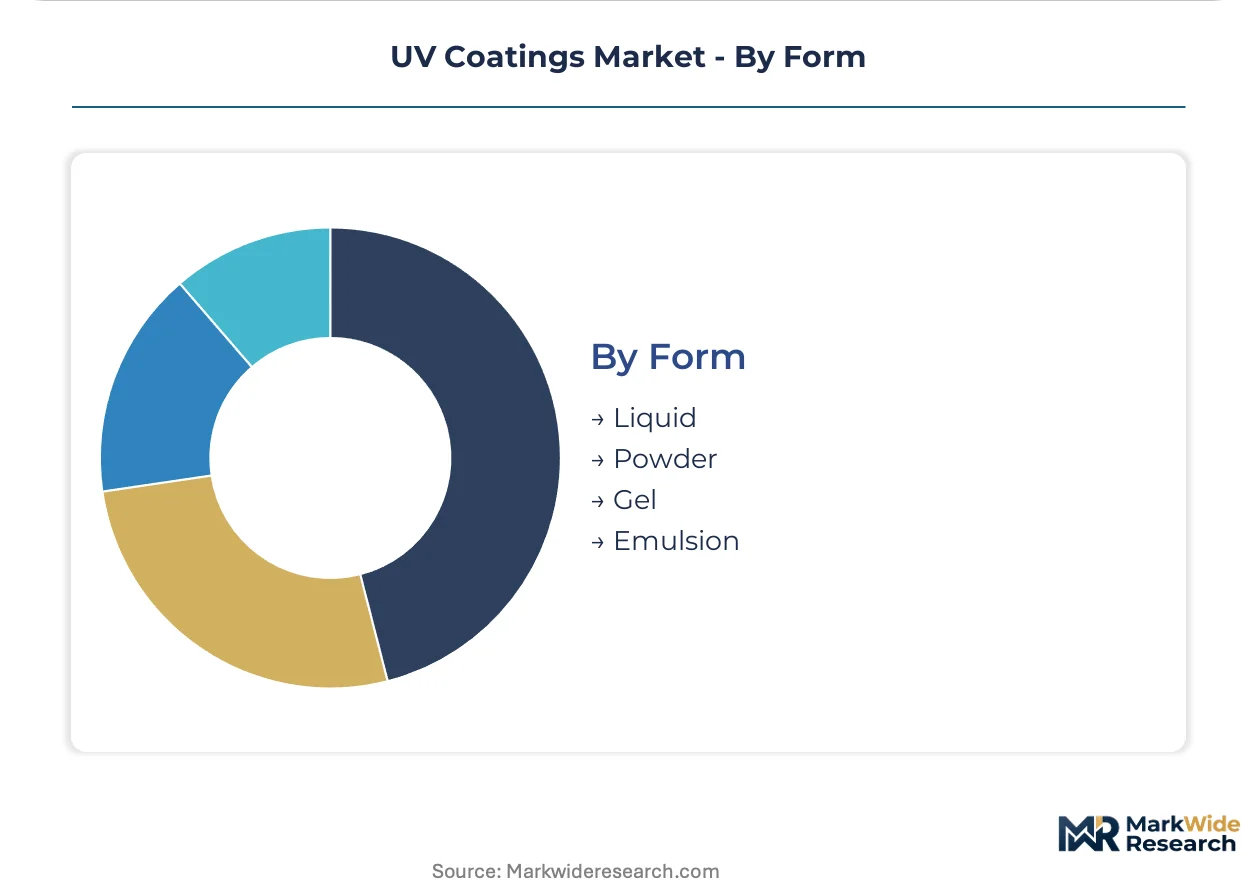
- Liquid:Solvent-borne and waterborne formulations serve the installed base of mercury and LED curing lines across automotive and industrial applications. These systems require solvent handling infrastructure and VOC reporting compliance.
- Powder:100% solid systems eliminate solvent handling costs and emission reporting burdens, gaining traction in automotive underbody and general metal finishing. Low-temperature UV powder variants open wood and plastic substrates previously excluded from thermal powder windows.
- Gel:Thixotropic formulations target vertical surface applications and repair scenarios where flow control determines finish quality.
- Emulsion:Aqueous UV hybrids combine dispersion stability with instant cure, targeting furniture and flooring segments under tightening EPA woodworking standards.
Liquid systems anchor the installed equipment base. Powder formats are climbing the fastest as mercury phase-out and emission enforcement intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty acrylate feedstock production concentrates in German and Chinese petrochemical corridors, while UV curing line procurement clusters in automotive and electronics manufacturing belts across three continents.
United States
Automotive OEMs in Detroit and tier suppliers across Michigan and Ohio drive specification-grade polyurethane demand for exterior clearcoat programs. EPA NESHAP Subpart HHHHHH enforcement intensifies for metal coating job shops, compelling UV line conversion or toll-coating partnerships. Wood furniture manufacturers in North Carolina face concentrated regional inspection activity, accelerating waterborne UV hybrid adoption.
Germany
Premium automotive manufacturers in Stuttgart specify aliphatic polyurethane networks for warranty-critical gloss retention. REACH Annex XVII restrictions on benzophenone redirect formulation R&D toward amine synergist alternatives at BASF SE and specialty chemical houses. The Rhine-Ruhr industrial corridor anchors photoinitiator production and UV equipment engineering competence.
China
Electronics contract manufacturers in the Yangtze River Delta and Pearl River Delta install UV lines under MEE emission enforcement pressure and dual carbon policy alignment. Domestic UV coating adoption accelerates in smartphone assembly and PCB conformal coating operations. LED UV array manufacturing concentrates in Shenzhen and Suzhou, bypassing traditional mercury lamp supply chains.
India
Smartphone and component assembly localization under the PLI scheme creates greenfield UV coating line demand in the NCR region and Karnataka. Electronics manufacturers avoid legacy solvent infrastructure displacement costs by specifying radiation-cure systems from project inception. BIS standards development for industrial coatings lags adoption, creating specification ambiguity for early entrants.
Japan
Precision electronics and automotive component suppliers in the Nagoya and Osaka industrial zones maintain dual-cure competency for mixed-model assembly lines. METI carbon neutrality roadmaps favor low-temperature curing processes for energy-intensive coating operations. Photoinitiator suppliers with verified renewable feedstock pathways gain procurement preference at tier-1 automotive suppliers.
UV Coatings Market Competitive Environment
Concentration sits with integrated resin suppliers and diversified coating formulators that control upstream oligomer production and downstream OEM specification relationships. Three archetypes dominate: petrochemical-backed resin-integrated players, specification-grade automotive coating specialists, and regional distributor-dependent commodity formulators. Competitive dynamics center on backward integration into photoinitiator chemistry and LED curing equipment partnerships that lock in line conversion cycles.
Within the resin-integrated tier, BASF SE and The Dow Chemical Company exemplify upstream control over specialty acrylate and polyurethane oligomer supply chains. PPG Industries occupies a position as a specification-grade automotive coating anchor with integrated color and clearcoat program relationships. Among diversified industrial formulators, AkzoNobel NV represents marine and industrial maintenance specialization through photoinitiator formulation expertise.
| Leading Market Players |
|---|
| AkzoNobel NV |
| PPG Industries |
| BASF SE |
| The Dow Chemical Company |
| The Sherwin-Williams Company |
| DIC Corporation |
| Dymax Corporation |
| Axalta Coating Systems |
| Royal DSM NV |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Chinese specialty acrylate producers determines price floors across polyurethane and acrylic formulation tiers, concentrating margin pressure on formulators without captive oligomer supply. REACH-driven photoinitiator reformulation and mercury lamp phase-out timelines compress pricing power at the mid-market tier while premium aliphatic polyurethane clearcoats retain specification premiums.
Pricing Analysis
Volume-discount tiering separates automotive OEM direct programs from distributor-served job shop volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales technical service bundling. Cost compression in standard-grade acrylics is intensifying because Chinese electronics contract manufacturers consolidate procurement through Yangtze River Delta manufacturing clusters. Contractors represent the most price-sensitive segment, while German premium automotive OEMs prioritize gloss retention warranties over unit cost.
Supply Chain Analysis
Germany and China anchor specialty acrylate and photoinitiator production, with the Rhine-Ruhr corridor and Yangtze River Delta petrochemical complexes feeding downstream formulation. Upstream draws from aromatic and aliphatic isocyanate feedstocks, benzophenone and amine synergist photoinitiators, and LED UV curing equipment components. Single-source vulnerability concentrates in mercury lamp replacement cycles ahead of Minamata Convention deadlines. Distribution runs through direct OEM specification channels for polyurethane clearcoats and regional distributor networks for commodity acrylics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV coatings demand follows automotive production cycles and electronics capital expenditure waves, with current positioning reflecting post-correction capacity tightness in specialty acrylate supply.
For Market Incumbents: Shield specification-grade polyurethane programs through backward integration into aliphatic isocyanate feedstocks. Accelerate LED curing equipment partnerships to lock in automotive tier supplier retrofit cycles before Chinese LED array manufacturers capture line conversion demand. Prioritize amine synergist photoinitiator R&D to preempt REACH Annex XVII compliance gaps.
For New Entrants and Emerging Players: CE marking fast-track for waterborne UV hybrids opens European furniture and flooring segments under intensifying EPA NESHAP enforcement pressure. India's PLI scheme for electronics manufacturing presents the most penetrable geography, with greenfield UV line demand avoiding legacy solvent infrastructure displacement. Target dual-cure hybrid formulations for complex PCB shadow-cure geometries excluded from pure radiation-cure specifications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors photoinitiator-integrated resin suppliers with verified renewable feedstock pathways. Long-term viability centers on formulators controlling upstream oligomer production and downstream OEM specification relationships. Watch LED UV equipment cost parity against mercury lamp phase-out deadlines as the inflection signal for line conversion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Acrylates | Captive oligomer supply insulates margin pressure from German and Chinese petrochemical cycle swings. |
| LED UV Equipment Partnership | Mercury lamp phase-out under Minamata Convention creates locked-in line conversion demand from automotive tier suppliers. |
| REACH-Compliant Photoinitiator Reformulation | Amine synergist alternatives to benzophenone capture specification approval at European automotive OEMs. |
| India PLI Scheme Localization | Greenfield electronics assembly in NCR and Karnataka bypasses legacy solvent infrastructure displacement costs. |
| Waterborne UV Hybrid Development | Aqueous dispersion stability combined with radiation cure speed targets EPA NESHAP-pressured North Carolina furniture manufacturers. |
Study Parameters
A spread of perspectives from coating formulators, automotive tier supplier procurement leads, photoinitiator R&D directors, and LED UV equipment engineers converged on the working assumptions. Primary fieldwork combined with secondary validation through customs trade data, ECHA REACH registration databases, EPA NESHAP enforcement records, and SEC filings from resin-integrated chemical producers. Bottom-up volume modeling triangulated against top-down value estimates across product chemistry, application vertical, and regional production cluster dimensions.
Segmentation dimensions modeled include polyurethane-acrylic-epoxy-polyester chemistry tiers, automotive-electronics-wood-packaging end-use verticals, and liquid-powder-emulsion form factors across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating automotive production forecasts, electronics capital expenditure cycles, and regulatory enforcement intensity indices. Industry-specific inputs captured photoinitiator migration study timelines, LED UV equipment adoption curves, and dual-cure hybrid penetration rates in complex geometries.
Underlying assumptions cover specialty acrylate supply continuity, REACH Annex XVII enforcement timelines, and Minamata Convention ratification schedules, with deviation risk concentrated in photoinitiator chemistry substitution rates and mercury lamp phase-out acceleration. Recalibration cycles align with material shifts in automotive OEM specification consolidation, MEE emission enforcement intensity in Chinese manufacturing clusters, and LED UV equipment cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Flexible Waterproof Coating Market
Coatings
Paper Coating Binders Market
Coatings
Marine Coatings Market
Coatings
Qatar Protective Coatings Market
Coatings
Glazes Market
Coatings
Global Pipe Coatings Market
Coatings
Polyester Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Silicate Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Anti-Microbial Nano Coatings Market
Coatings
Global Water-Based Coatings Market
Coatings
Technical Coil Coatings Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Solar Reflective Film Market