
 Waterproofing Admixture Market | 2026-2036
Waterproofing Admixture Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproofing Admixture Market Analysis
Multi-source procurement for active ingredients is decoupling from traditional single-source petrochemical supply chains. Sika AG leverages its integrated mortar-admixture platform to control specification conversations with European contractors. BASF SE sustains R&D intensity in crystalline chemistry, anchoring its position in infrastructure-grade projects across Germany and France.
Waterproofing admixtures are hydrophobic or crystalline compounds dosed into fresh concrete to block water ingress through capillary pore networks, typically comprising active silicates, stearates, or pore-blocking polymers at 0.5-2.0% by cement weight. Their primary purpose is extending structural service life in basements, tunnels, and marine environments by preventing reinforcement corrosion. Crystalline formulations now capture premium margin pools as infrastructure owners specify lifetime waterproofing warranties rather than membrane-dependent systems. Flexible product types dominate residential application volumes, though rigid systems lead commercial segments where load-bearing slabs require dimensional stability.
REACH compliance in Europe and BIS certification in India now mandate disclosure of volatile organic compound content and chloride ion permeability thresholds, respectively, forcing reformulation of legacy hydrophobic admixtures. The EU Green Deal's embodied carbon tracking for construction materials is redirecting specification authority toward environmental product declarations. Contractors and engineers must monitor how regional building codes synchronize with these chemical safety and carbon accounting frameworks to avoid project bid disqualification.
Market Dynamics
Specification authority is migrating from general contractors to asset owners demanding lifetime waterproofing warranties, compressing membrane-dependent procurement cycles and elevating crystalline chemistry platforms in infrastructure tender evaluations.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Environmental product declarations now gate eligibility for public infrastructure tenders across Germany and France, redirecting specification authority toward low-carbon admixture formulations.
- Metropolitan India tunneling:Underground construction in Mumbai and Delhi accelerates crystalline system uptake as BIS durability codes tighten chloride permeability thresholds for coastal foundations.
- Crystalline chemistry:Self-healing capillary pore networks in infrastructure-grade concrete extend service life beyond membrane-dependent alternatives, capturing premium specification slots in marine environments.
Market Restraints
- Petrochemical input volatility:Stearate and polymer feedstock costs fluctuate with naphtha cracking margins, squeezing hydrophobic admixture margins during energy price spikes.
- REACH compliance friction:ECHA disclosure mandates for volatile organic compound content force reformulation of legacy hydrophobic chemistries, extending R&D timelines for European suppliers.
- Membrane substitution threat:Sheet-applied and spray-applied membrane systems retain cost advantages in residential basements where dimensional stability requirements remain modest.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea coastal developments specify 100-year design life concrete, creating specification windows for crystalline warranty-backed systems.
- Smart dosing integration:Convergence of IoT-enabled batching plants with real-time rheology monitoring enables precision admixture dosing, reducing cement overdesign waste.
- India PLI scheme alignment:Domestic manufacturing incentives for construction chemicals localize supply chains for Maharashtra and Gujarat infrastructure contractors facing import duty pressure.
Industry Challenges
- Certification timeline compression:BIS and ECHA parallel approval pathways for new silicate-active formulations extend time-to-revenue by 18-24 months for reformulated products.
- Specification engineer scarcity:Shortage of concrete technologists capable of translating warranty terms into mix design parameters limits owner-direct selling effectiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproofing Admixture Market |
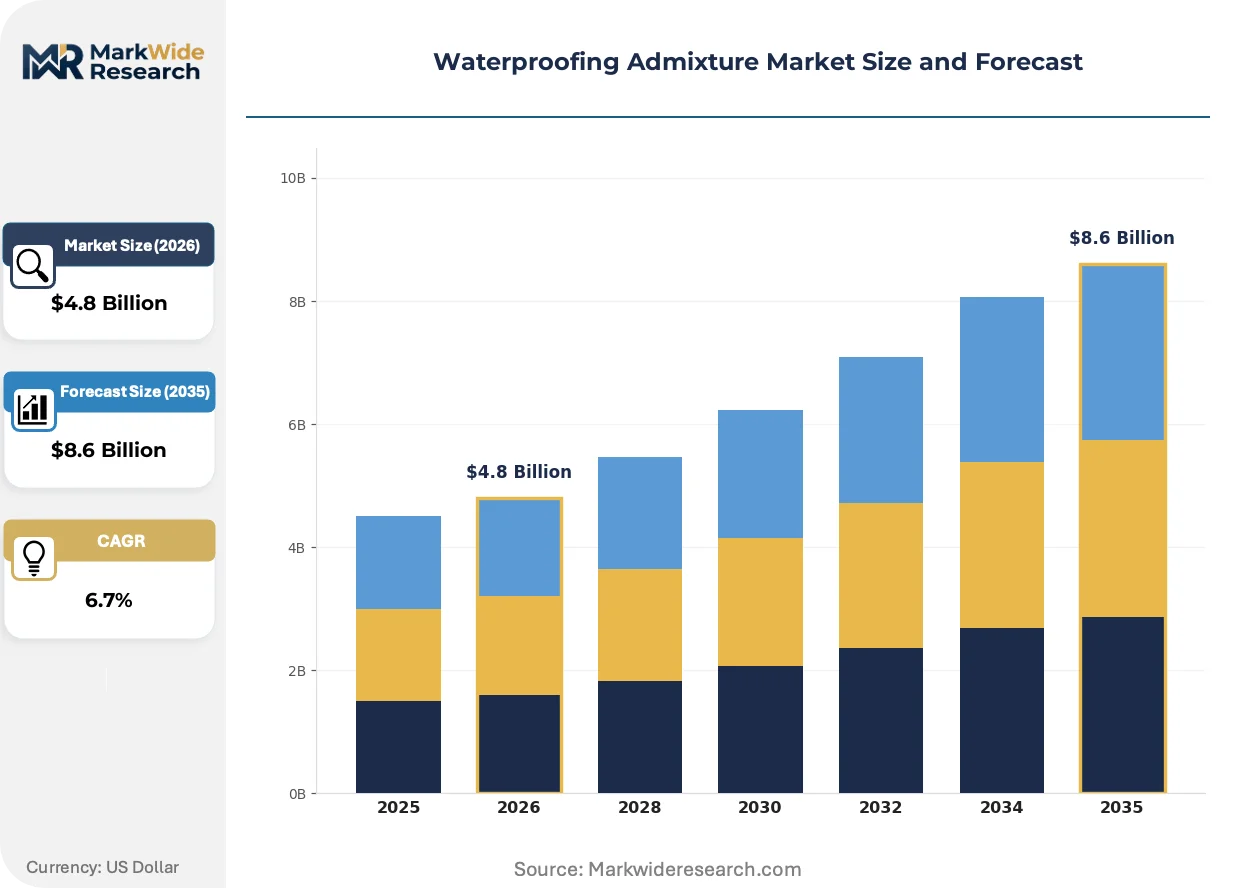
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Crystalline, Hydrophobic Application: Residential, Commercial, Infrastructure, Industrial End User: Contractors, Builders, Architects, Engineers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Saint-Gobain SA, Dow Inc., BASF SE, Xypex Chemical Corporation, Penetron, Sika AG, RPM International Inc., Kryton International Inc., MAPEI S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproofing Admixture Market Emerging Trajectories
Crystalline self-healing chemistry is displacing passive hydrophobic barriers as the default specification for infrastructure assets requiring century-scale durability guarantees.
Colloidal silica and active silicate blends penetrate capillary networks to precipitate insoluble calcium silicate hydrate crystals upon moisture ingress. Infrastructure owners in Germany and France now mandate these systems for tunnel linings and marine piles. This mechanism is rewriting warranty economics by shifting liability from membrane installers to concrete suppliers.
REACH Article 33 disclosure requirements for Substances of Very High Concern now extend to construction chemical imports. Suppliers must document full supply chain SVHC content above 0.1% w/w. Crystalline formulations with simplified chemistry stacks gain compliance velocity versus polymer-heavy hydrophobic alternatives in European public tenders.
Asset owners increasingly unbundle material procurement from application contracting, issuing separate specifications for admixture performance and concrete placement. This bifurcation concentrates buying power among ready-mix producers in Maharashtra and Gujarat who control batching infrastructure. Direct supplier-owner relationships compress traditional distributor margins in high-volume coastal markets.
Waterproofing Admixture Market Segmentation
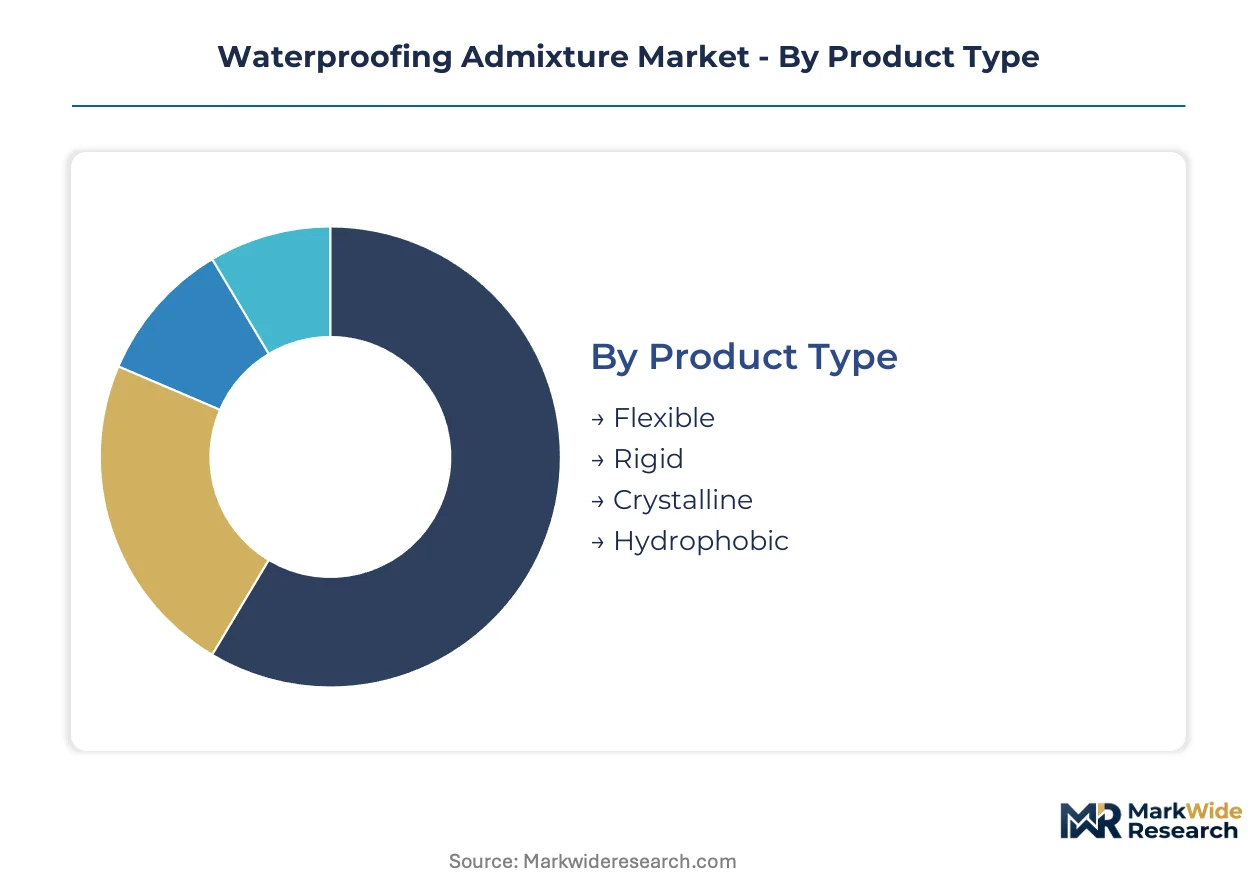
Waterproofing admixture specification varies sharply across construction tiers, with infrastructure owners demanding crystalline chemistry while residential contractors prioritize cost-flexible hydrophobic systems. Understanding these segment boundaries prevents misallocation of formulation R&D and distribution resources.
Product Type:
Upgrade cycles from membrane-dependent waterproofing to integral admixture systems are compressing replacement timelines in infrastructure-grade concrete specifications.
- Crystalline:Active silicate chemistry precipitates insoluble calcium silicate hydrate crystals within capillary pores upon moisture contact. Mumbai and Delhi metro tunneling projects specify these systems for 100-year design life guarantees, displacing external membrane procurement cycles.
- Hydrophobic:Stearate and polymer-based formulations create water-repellent surfaces through pore-blocking action at 0.5-2.0% cement weight. Maharashtra residential basements favor these for first-cost economy despite shorter effective service intervals than crystalline alternatives.
- Flexible:Polymer-modified compounds accommodate substrate movement in below-grade walls subject to settlement stress.
- Rigid:Dense mineral formulations suit load-bearing slabs requiring dimensional stability under structural load.
Volume placements concentrate in Hydrophobic formulations; the faster expansion belongs to Crystalline systems.
Application:
Cost tier differentiation separates specification authority between asset owners with lifecycle accounting capacity and first-cost-sensitive developers.
- Infrastructure:Tunnels, marine piles, and coastal foundations in Germany and France mandate crystalline chemistry with embodied carbon disclosures under EU Green Deal procurement rules. ECHA REACH compliance gates eligibility for public tender participation.
- Residential:Basement and foundation waterproofing in Gujarat coastal zones faces aggressive chloride exposure, driving BIS-certified admixture uptake despite membrane cost competition.
- Commercial:High-rise podium slabs and parking structures require load-bearing compatibility with rigid or crystalline systems.
- Industrial:Chemical containment structures and wastewater treatment facilities specify corrosion-resistant integral waterproofing.
Specification intensity peaks in Infrastructure; the steepest volume climb occurs in Residential coastal markets.
End User:
Customer type fragmentation concentrates buying power among ready-mix producers who control batching infrastructure and admixture dosing precision.
- Contractors:Application-focused procurement favors flexible hydrophobic formulations with rapid placement characteristics and minimal cure-time constraints.
- Builders:Volume-scale residential developers in Maharashtra unbundle material procurement from placement contracting, issuing direct admixture specifications to ready-mix suppliers.
- Architects:Design-phase influence wanes as asset owners assume specification authority for warranty-backed infrastructure projects.
- Engineers:Concrete technologists translate owner warranty terms into mix design parameters, creating scarcity premiums for qualified specification support.
Procurement volume aggregates with Builders; the specification authority shift most favors Engineers in infrastructure tenders.
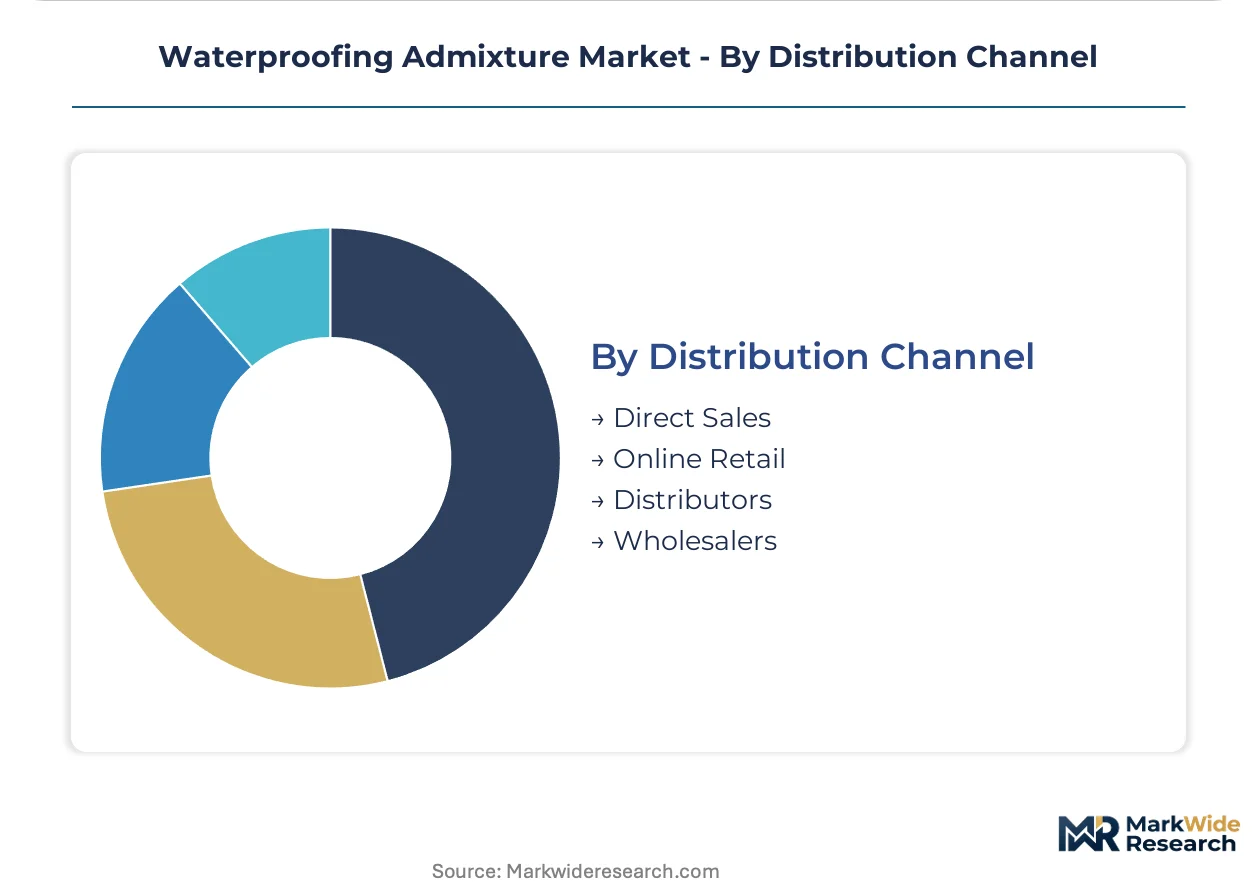
Distribution Channel:
Supply concentration among integrated mortar-admixture platforms is compressing traditional distributor margins in high-volume coastal markets.
- Direct Sales:Supplier-owner relationships bypass distributor networks for NEOM and Red Sea giga-projects requiring 100-year warranty documentation and batch-to-batch traceability.
- Distributors:Regional construction chemical specialists retain relevance in Gujarat and Maharashtra where contractors require localized technical service and rapid replenishment.
- Online Retail:Small-package hydrophobic admixtures for repair and renovation applications migrate to digital procurement channels.
- Wholesalers:Bulk cement and aggregate suppliers bundle admixture offerings for mid-scale commercial developers.
Transaction volume flows through Distributors; the channel gaining share fastest is Direct Sales for warranty-critical infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in coastal metropolitan corridors where chloride exposure and tunneling projects drive specification intensity. Infrastructure durability codes are tightening across multiple jurisdictions, redirecting procurement toward certified crystalline formulations. The analysis tracks five countries where regulatory acceleration and construction volume intersect.
Germany
EU Green Deal embodied carbon tracking now gates public infrastructure tenders, elevating environmental product declarations in specification decisions. ECHA REACH compliance mandates full SVHC disclosure above 0.1% w/w for construction chemical imports. The Rhine-Ruhr corridor anchors crystalline system uptake for tunnel linings and marine piles requiring century-scale durability warranties.
India
Metropolitan tunneling in Mumbai and Delhi accelerates crystalline waterproofing adoption as underground construction expands. BIS tightened concrete durability codes, pushing builders toward certified admixture formulations with verified chloride permeability thresholds. Demand concentrates in Maharashtra and Gujarat, where coastal infrastructure faces aggressive chloride exposure from Arabian Sea conditions.
France
Public procurement rules now synchronize with EU Green Deal carbon accounting frameworks for construction materials. ECHA disclosure requirements extend to imported construction chemicals, favoring simplified chemistry stacks in crystalline formulations. The Paris metropolitan region drives specification authority shifts as asset owners unbundle material procurement from placement contracting.
Saudi Arabia
NEOM and Red Sea coastal developments specify 100-year design life concrete, creating demand windows for warranty-backed crystalline systems. The national construction chemical regulator enforces durability certification for marine foundation applications. The Eastern Province and northwestern giga-project zones concentrate direct supplier-owner relationships bypassing traditional distribution networks.
United States
EPA stormwater management requirements and state-level embodied carbon tracking in California and New York redirect specification toward low-carbon admixture formulations. OSHA workplace exposure standards influence hydrophobic admixture reformulation timelines. The Northeast Corridor and Gulf Coast metropolitan areas drive residential basement waterproofing volume despite membrane cost competition.
Waterproofing Admixture Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers position batching infrastructure near high-volume coastal markets. The vendor base organizes around three tiers: integrated chemical conglomerates controlling specification conversations, specialized crystalline chemistry developers, and regional construction chemical distributors. Two strategic archetypes define competitive positioning: integrated mortar-admixture platforms leveraging cross-product bundling, and pure-play crystalline specialists anchoring infrastructure-grade warranty offerings. Geographic expansion and strategic partnerships represent the dominant competitive moves, particularly around Saudi giga-projects and Indian PLI-aligned manufacturing.
Within the integrated chemical tier, BASF SE and Sika AG exemplify platform-based competitive positioning. BASF SE anchors European infrastructure-grade crystalline chemistry through sustained R&D intensity. Sika AG occupies a position controlling specification conversations via its integrated mortar-admixture platform. Kryton International Inc. represents the pure-play crystalline specialist archetype, with its corporate name signaling dedicated focus on reactive waterproofing chemistry. MAPEI S.p.A. sits within the construction chemical specialist tier, its Italian corporate structure indicating regional manufacturing heritage with multinational distribution reach. These three anchors demonstrate how competitive positioning stratifies across integrated platforms, pure-play technology developers, and regional specialists.
| Leading Market Players |
|---|
| Saint-Gobain SA |
| Dow Inc. |
| BASF SE |
| Xypex Chemical Corporation |
| Penetron |
| Sika AG |
| RPM International Inc. |
| Kryton International Inc. |
| MAPEI S.p.A. |
| Others |
Supply Flow & Price Mechanics
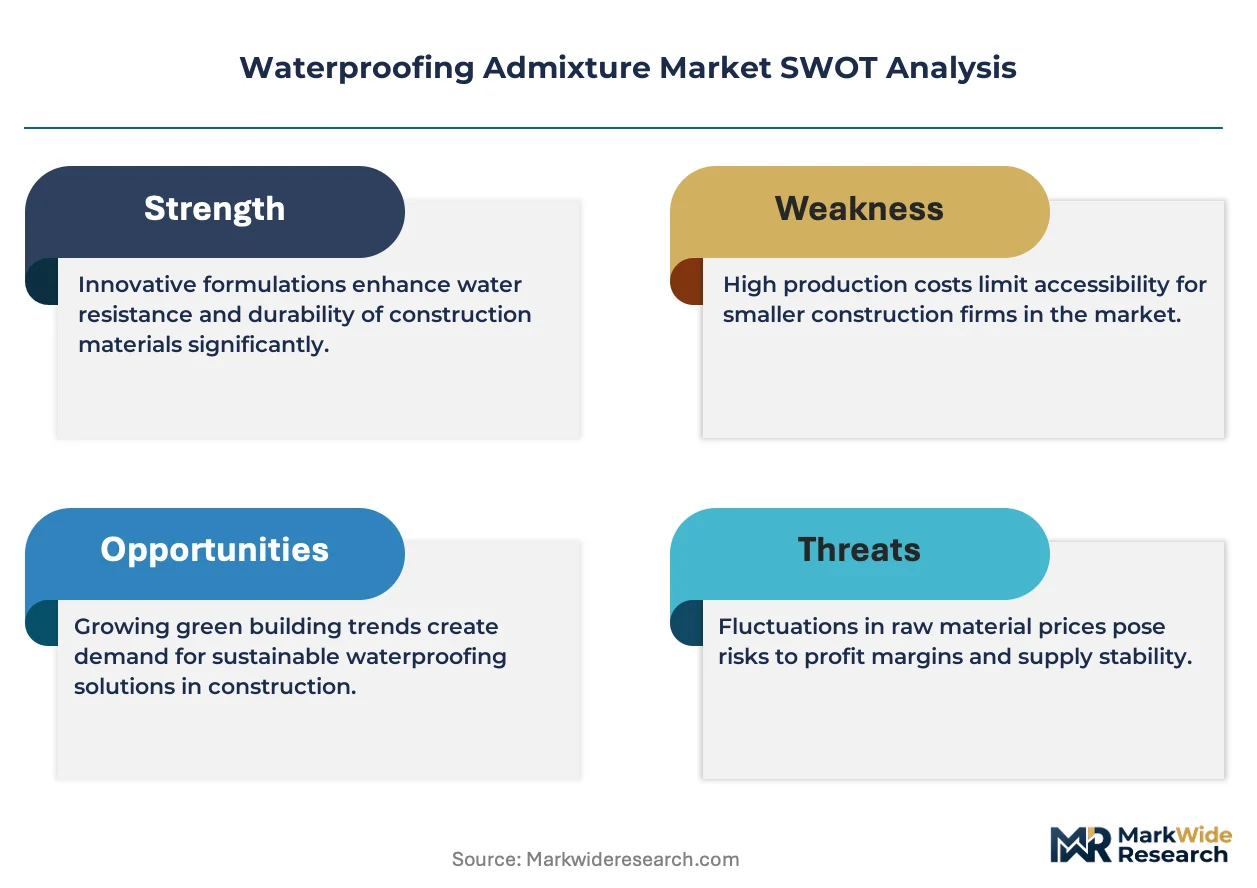
Crystalline-hydrophobic bifurcation splits the market into warranty-backed premium tiers and cost-optimized commodity grades, with this divergence mapping directly onto supply chain configurations. Premium crystalline formulations anchor pricing power through BIS and ECHA certification requirements, while hydrophobic grades compete on petrochemical input arbitrage across regional distribution networks.
Pricing Analysis
Volume placements concentrate in hydrophobic formulations at compressed margins, while crystalline systems capture premium pools through lifetime warranty bundling. Price differentiation rests on certification tier and performance guarantee duration, with BIS-verified chloride permeability thresholds commanding substantial premiums over uncertified alternatives. Pricing pressure intensifies in residential basements where membrane systems retain first-cost advantages, compressing hydrophobic admixture margins. Residential contractors in Maharashtra exhibit highest price sensitivity, whereas infrastructure asset owners in Germany and France prioritize lifecycle cost over initial outlay.
Supply Chain Analysis
Regional distribution centers in Germany, India, and Saudi Arabia anchor hub-and-spoke patterns for construction chemical logistics. Active silicate and stearate feedstock supplies draw from China, Germany, and the United States, with polymer modifiers sourced from South Korean and Japanese petrochemical complexes. Single-source vulnerability concentrates in naphtha-derived stearate inputs during energy price volatility episodes. Distribution runs through integrated mortar-admixture platforms controlling batching infrastructure, displacing traditional construction chemical distributors in high-volume coastal corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crystalline self-healing chemistry is displacing passive hydrophobic barriers as the default infrastructure specification, creating transition-phase winners and losers across formulation portfolios.
For Market Incumbents: Anticipate membrane system cost competition in residential segments by accelerating crystalline chemistry R&D for mid-tier warranty offerings. Backward integration into active silicate feedstock production defends margin position against petrochemical input volatility. Certification investment in BIS and ECHA parallel approval pathways extends competitive moats despite 18-24 month timeline compression risks. For New Entrants and Emerging Players: EU Green Deal embodied carbon tracking in Germany and France opens a window for low-carbon crystalline formulations with simplified chemistry stacks. White-space targets concentrate in Saudi giga-projects requiring 100-year warranty documentation and direct supplier-owner relationships bypassing entrenched distribution networks. Smart dosing integration partnerships with IoT-enabled batching plant operators provide differentiated go-to-market positioning against legacy hydrophobic suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated mortar-admixture platforms with specification conversation control across European infrastructure tenders. Long-term viability favors crystalline chemistry specialists with established warranty-backed track records in marine and tunneling applications. The signal to watch is BIS durability code harmonization with EU Green Deal carbon accounting frameworks, which would accelerate procurement consolidation among certified formulation suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Silicate Feedstock | Captive supply of crystalline chemistry inputs insulates margin from naphtha volatility in European markets. |
| Smart Dosing Platform Partnership | IoT-enabled batching integration reduces cement overdesign waste for ready-mix producers in Maharashtra. |
| BIS-ECHA Dual Certification Investment | Parallel approval velocity gates eligibility for infrastructure tenders in India and EU member states. |
| Direct Sales Infrastructure for Giga-Projects | Supplier-owner relationships bypass distributor networks for NEOM and Red Sea warranty-critical specifications. |
| Low-Carbon Formulation Development | Environmental product declarations gate public tender participation under EU Green Deal procurement rules. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across concrete technologists, ready-mix plant managers, infrastructure procurement officers, and construction chemical distributors. Bottom-up volume triangulation from batching plant capacity and admixture dosing rates was reconciled with top-down construction spend allocation across residential, commercial, and infrastructure segments. ECHA REACH disclosure databases, BIS certification registries, and EU Green Deal procurement notices provided regulatory validation layers.
Data-stream reconciliation across shipment volumes, tender awards, and formulation patent filings informed the analytical framework. Segmentation dimensions modeled include product chemistry type, application durability tier, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from construction pipeline tracking and admixture specification penetration curves. Crystalline chemistry warranty adoption rates and hydrophobic membrane substitution elasticities served as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for crystalline self-healing chemistry would alter the outlook if membrane systems achieve comparable lifecycle cost positioning. Forecasts reflect documented assumptions regarding BIS code enforcement intensity and EU carbon accounting implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market