
 Anti-Friction Coatings Market | 2026-2036
Anti-Friction Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Friction Coatings Market Analytics
High-performance PTFE and nanotechnology-grade specifications is unwinding legacy solvent-based demand across industrial buyer segments. DuPont de Nemours Inc leverages its fluoropolymer heritage to dominate premium aerospace qualification programs. Fuchs Petrolub SE anchors European automotive supply chains through captive tribology laboratories. Klüber Lubrication specializes in application-specific formulations for wind turbine gearbox maintenance, a segment where coating longevity directly determines service intervals.
Anti-friction coatings are thin-film surface treatments, typically 5–50 microns thick, composed of PTFE, molybdenum disulfide, or graphite particles bound in resin matrices; they reduce coefficient of friction between mating surfaces while eliminating liquid lubricant contamination in clean-room or vacuum environments. Dry film lubricants lead product-type revenue due to decades of military specification adoption, though nanotechnology-enabled coatings represent the fastest-expanding margin pool as semiconductor fabrication equipment demands atomic-scale uniformity. Water-based technology formulations are displacing solvent-based equivalents in automotive assembly plants where volatile organic compound thresholds tighten, while powder coating methods gain traction in heavy manufacturing for their elimination of hazardous air pollutants.
EPA hazardous air pollutant standards under NESHAP constrain solvent-based coating operations in US automotive and aerospace facilities, while REACH annex XVII restrictions on perfluorinated substances force European formulators toward shorter-chain fluoropolymer alternatives. China's MEE enforces volatile organic compound emission ceilings at provincial level, redirecting manufacturing investment toward water-based and UV-curable system capacity. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance with one geography's chemical restrictions may disqualify products from another's qualified supplier lists.
Market Dynamics
Water-based fluoropolymer formulations are decomposing solvent-based coating demand as automotive OEMs face tightening volatile organic compound thresholds across manufacturing footprints.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH annex XVII limits on perfluorinated substances force formulators toward shorter-chain fluoropolymer alternatives, accelerating reformulation investment across European precision engineering clusters.
- Semiconductor fabrication equipment:Atomic-scale uniformity requirements in clean-room environments pull nanotechnology-enabled coatings into qualification programs for wafer handling robotics.
- Wind turbine gearbox maintenance:Service interval extension mandates drive specification of PTFE-based dry film systems in offshore installations where accessibility costs dominate lifecycle economics.
Market Restraints
- Fluoropolymer feedstock concentration:Tetrafluoroethylene monomer supply concentrates among limited chemical producers, exposing coating formulators to input cost volatility and allocation risk.
- Long-chain perfluorinated substance substitution:Shorter-chain alternatives deliver inferior wear resistance in high-load aerospace bearing applications, creating performance gaps during regulatory transition periods.
- Application equipment capex:Water-based system conversion requires spray booth reconfiguration and curing oven upgrades, locking out smaller job shops from automotive qualification programs.
Strategic Opportunities
- India precision component manufacturing:PLI scheme incentives for automotive and aerospace component production create first-mover advantage for coating applicators establishing local technical service centers.
- UV-curable coating convergence:Hybrid formulations combining instant cure speed with fluoropolymer durability address electronics assembly throughput requirements in high-mix manufacturing environments.
- Digital coating thickness monitoring:Inline eddy current and ultrasonic measurement systems enable predictive maintenance contracts, shifting revenue from material supply to performance-guaranteed service models.
Industry Challenges
- Tribology specialist scarcity:Formulation chemistry expertise in solid lubricant particle-resin matrix interaction remains concentrated among retiring technical staff at established European suppliers.
- Multi-jurisdiction qualification burden:Aerospace OEMs require separate NADCAP and EASA coating process approvals, extending new product introduction timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Friction Coatings Market |
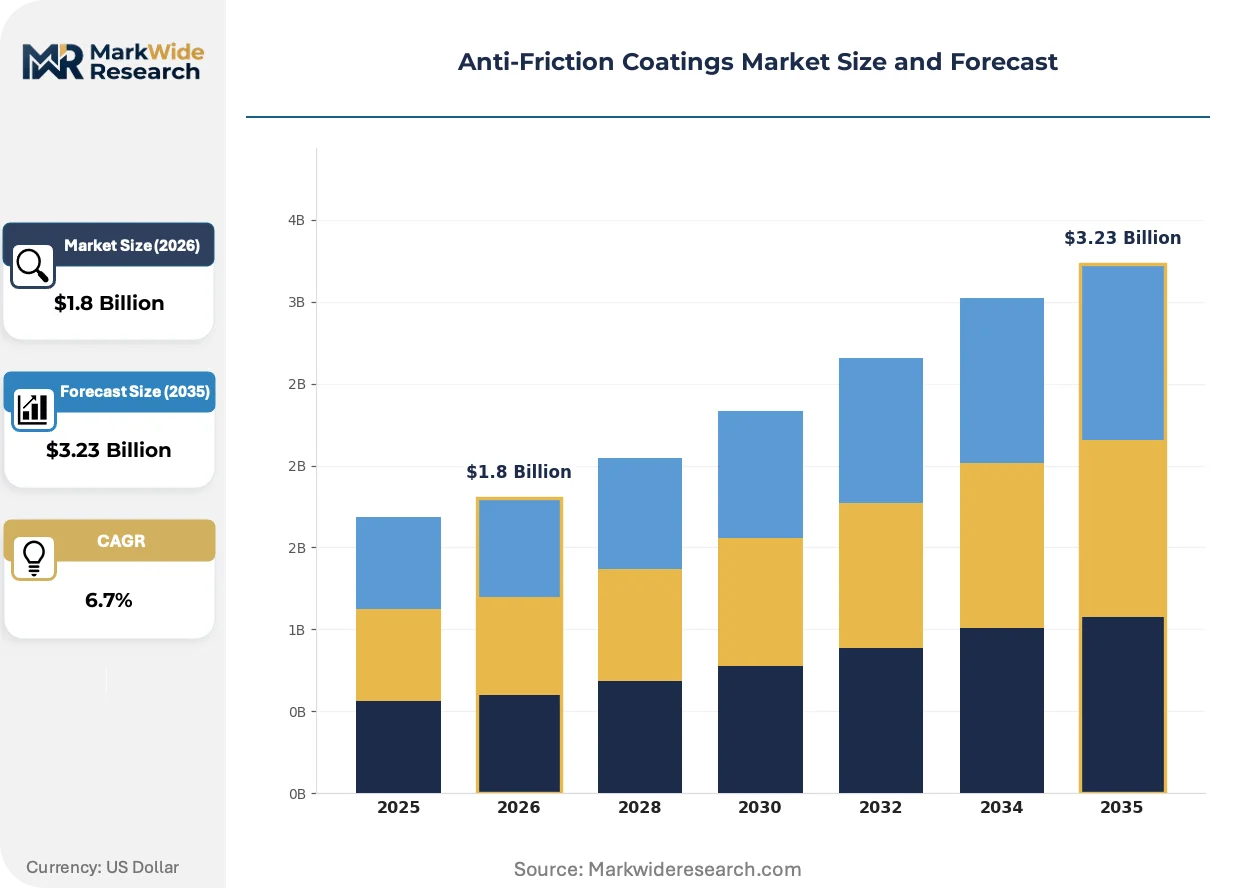
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Film Lubricants, Liquid Lubricants, Graphite Coatings, PTFE Coatings Application: Aerospace, Automotive, Manufacturing, Construction End User: OEMs, Aftermarket Providers, Industrial Users, Repair Services Technology: Solvent-Based, Water-Based, Nanotechnology, Powder Coating |
| Companies Covered | Carl Bechem GMBH, Fuchs Petrolub SE, DuPont de Nemours Inc, Poeton Industries, Klüber Lubrication, The Chemours Company, Whitford Corporation, AGC Inc, Parker Hannifin Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Friction Coatings Market Evolving Landscape
Formulation chemistry, application methodology, and service delivery models are simultaneously transforming as regulatory pressure intersects with performance demands from advanced manufacturing sectors.
Plasma-enhanced chemical vapor deposition of fluoropolymer thin films is decomposing traditional spray-applied coating dominance in semiconductor equipment manufacturing. Wafer handling robotics manufacturers specify 2-5 micron vapor-deposited layers for atomic-scale thickness uniformity. This technology is compressing the addressable market for conventional dip-spin coating services in precision electronics applications.
China's MEE volatile organic compound emission ceilings at provincial level redirect manufacturing investment toward water-based and UV-curable system capacity. Guangdong and Jiangsu provinces enforce the strictest thresholds, forcing automotive tier-one suppliers to consolidate coating operations at centralized facilities with advanced abatement infrastructure. Domestic formulators accelerate water-based PTFE dispersion development to capture displaced solvent-based volume.
Automotive powertrain engineers now specify coated components at the design stage rather than retrofitting existing assemblies. Tier-one suppliers in Germany's precision engineering belt embed tribology specialists within customer technical teams to influence material selection early in development cycles. This behavior shift concentrates specification authority among qualified coating applicators with captive laboratory validation capabilities.
Anti-Friction Coatings Market Segmentation
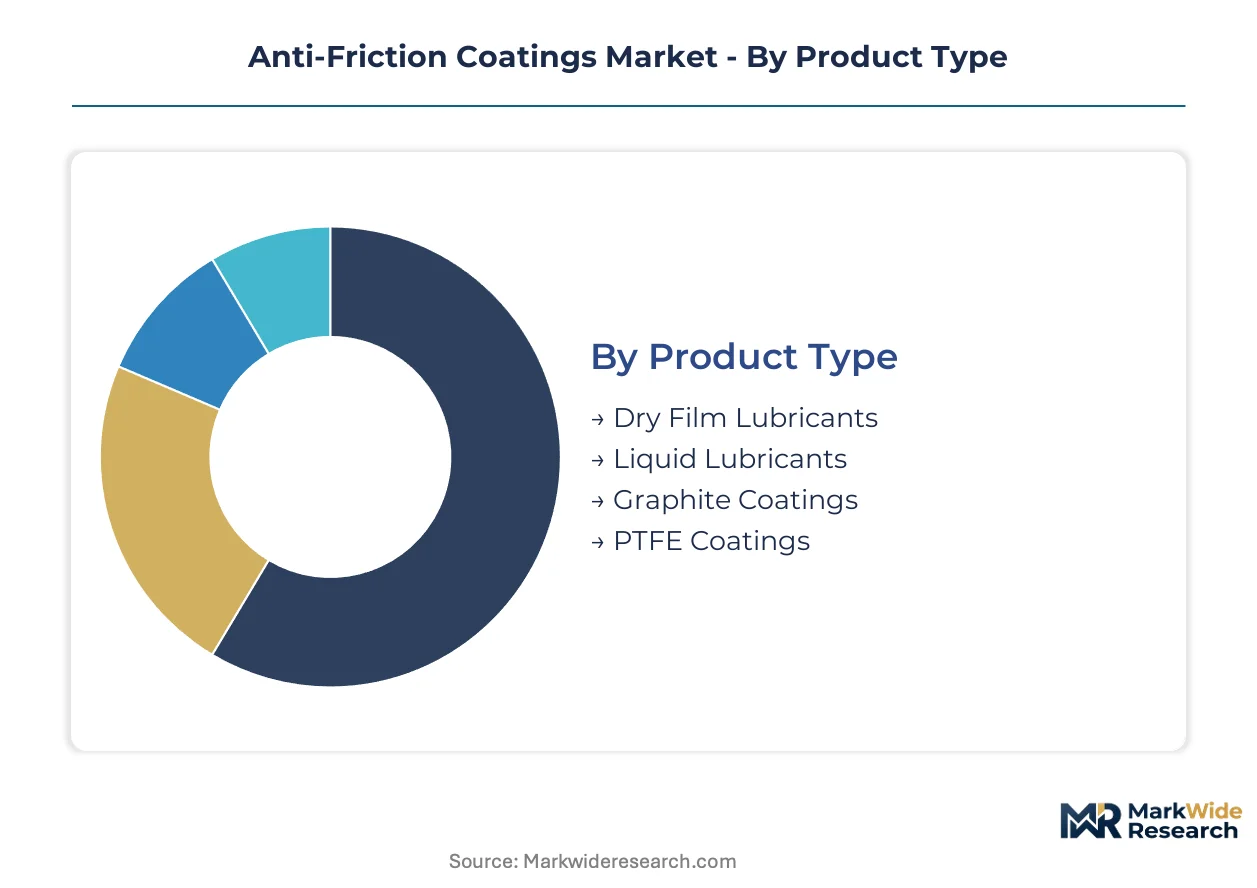
Anti-friction coatings serve divergent performance requirements across friction-critical applications. Segmentation reveals how formulation chemistry, application method, and end-use specifications create distinct competitive arenas with varying margin profiles and qualification barriers.
Product Type:
German automotive OEMs and US aerospace primes drive export demand for high-specification formulations, while domestic manufacturing in China and India absorbs commodity-grade coatings for general industrial machinery.
- Dry Film Lubricants:PTFE or molybdenum disulfide particles bound in thermoset resin matrices cure to 5-50 micron films that eliminate liquid lubricant contamination. Military specification heritage sustains dominance in US aerospace bearing applications where MIL-PRF-46147 qualification remains mandatory. REACH solvent restrictions are forcing European formulators toward water-borne resin systems.
- PTFE Coatings:Fluoropolymer dispersions deliver coefficient of friction below 0.05 in powertrain assemblies. German tier-one suppliers specify these for camshaft and valve train components facing stricter wear-resistance mandates. Tetrafluoroethylene monomer supply concentration among limited chemical producers exposes formulators to allocation risk.
- Liquid Lubricants:Conventional oil-based formulations with suspended solid lubricant particles serve legacy industrial equipment where retrofitting dry film systems proves uneconomical.
- Graphite Coatings:Carbon-based solid lubricants withstand extreme temperature cycling in furnace equipment and high-temperature processing machinery.
Dry Film Lubricants holds the largest share; momentum sits with PTFE Coatings.
Application:
Cost tier segmentation separates qualification-intensive aerospace programs from volume-driven automotive assembly and price-sensitive general manufacturing.
- Aerospace:NADCAP and EASA process approvals mandate 18-24 month qualification timelines for coating applicators. Atomic-scale uniformity requirements in clean-room environments pull nanotechnology-enabled formulations into wafer handling robotics specifications. Plasma-enhanced chemical vapor deposition is compressing addressable market for conventional spray-applied services.
- Automotive:Powertrain engineers now specify coated components at design stage rather than retrofitting existing assemblies. Tier-one suppliers embed tribology specialists within customer technical teams to influence material selection early in development cycles.
- Manufacturing:General industrial machinery maintenance represents volume demand with lower specification barriers and shorter sales cycles.
- Construction:Heavy equipment manufacturers specify coatings for articulating joints and hydraulic cylinder rods facing abrasive operating environments.
Aerospace commands premium pricing; automotive delivers volume scale.
End User:
Customer type determines whether coatings are specified at design stage or procured reactively through maintenance budgets.
- OEMs:Original equipment manufacturers integrate coating specifications into component drawings during product development, locking in qualified applicators for production runs. Captive tribology laboratories at major suppliers anchor European automotive supply chains through early-stage design influence.
- Aftermarket Providers:Independent distributors and service networks supply replacement coatings for maintenance and repair, with demand patterns tied to equipment utilization rates rather than new build cycles.
- Industrial Users:Factory maintenance departments procure coatings for in-house equipment refurbishment based on operational expenditure budgets.
- Repair Services:Specialized applicators serve localized demand from job shops and field service operations with shorter lead time requirements.
OEMs concentrate specification authority; aftermarket Providers expand fastest.
Technology:
Regulatory pressure is accelerating solvent-to-water formulation shifts while nanotechnology-enabled systems capture premium positioning.
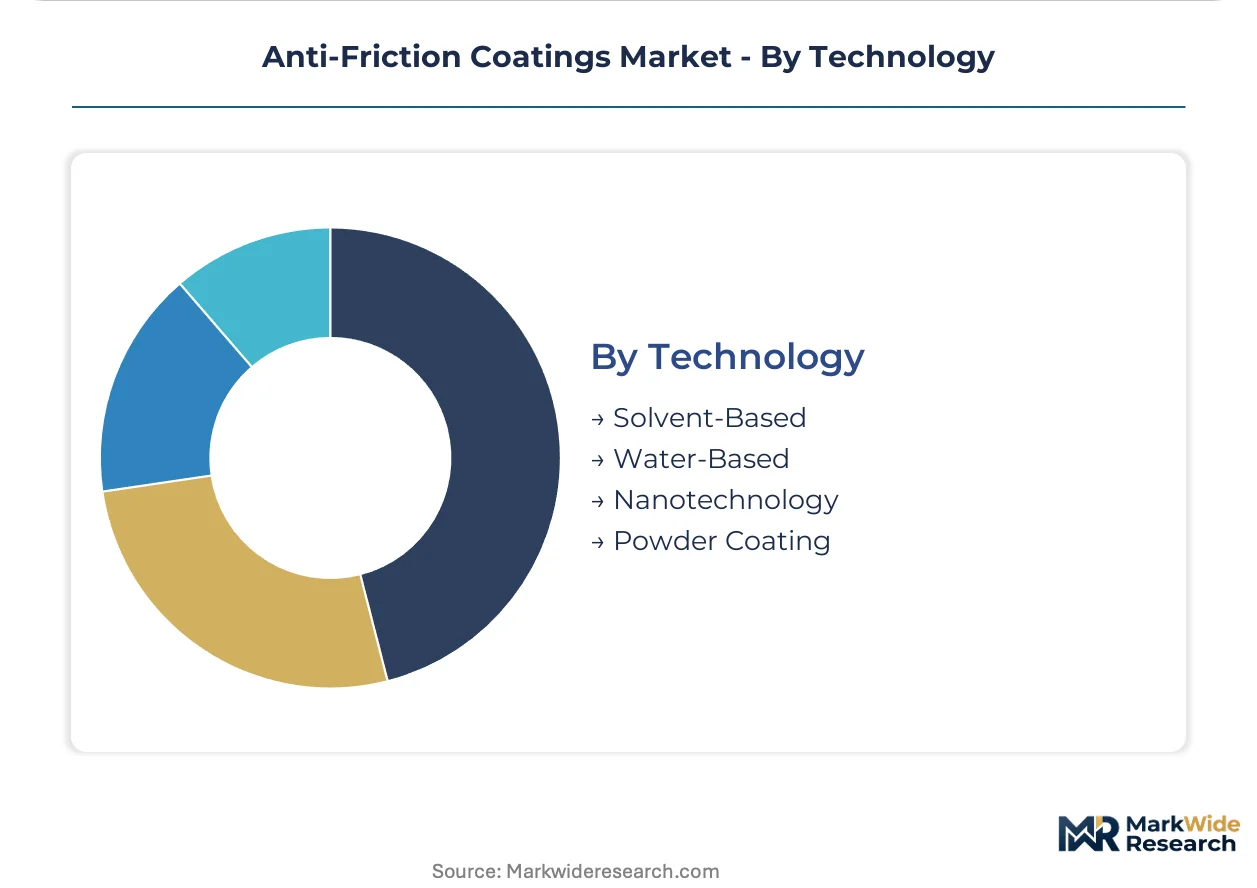
- Water-Based:Fluoropolymer dispersions in aqueous carriers meet tightening volatile organic compound thresholds in automotive assembly plants. Guangdong and Jiangsu provinces enforce China's strictest emission ceilings, forcing tier-one suppliers to consolidate operations at centralized facilities.
- Nanotechnology:Sub-micron particle formulations achieve atomic-scale thickness uniformity for semiconductor fabrication equipment. Wafer handling robotics manufacturers specify 2-5 micron vapor-deposited layers, expanding the fastest.
- Solvent-Based:Legacy formulations face EPA NESHAP constraints in US facilities and REACH annex XVII restrictions on perfluorinated substances across Europe.
- Powder Coating:Thermoplastic fluoropolymer powders eliminate hazardous air pollutants in heavy manufacturing applications with thick-film requirements.
Water-Based systems hold installed base dominance; nanotechnology climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tetrafluoroethylene monomer production concentrates among limited chemical producers in the United States, Germany, and China, exposing coating formulators across all demand centers to input cost volatility and allocation risk. This supply-side concentration shapes regional competitive dynamics.
United States
Aerospace bearing applications sustain MIL-PRF-46147 specification demand for dry film lubricants. EPA NESHAP hazardous air pollutant standards constrain solvent-based coating operations in automotive and aerospace facilities. Wichita, Kansas and Seattle, Washington industrial clusters host qualified applicators serving Boeing and defense prime supply chains.
Germany
Precision engineering belt tier-one suppliers specify PTFE-coated powertrain components for stricter wear-resistance mandates. REACH annex XVII restrictions on perfluorinated substances force formulators toward shorter-chain fluoropolymer alternatives. Stuttgart and Munich automotive clusters embed tribology specialists within OEM technical teams to influence early-stage design specifications.
China
Semiconductor fabrication equipment demand pulls nanotechnology-enabled coatings into wafer handling robotics qualification programs. MEE volatile organic compound emission ceilings at provincial level redirect manufacturing investment toward water-based and UV-curable system capacity. Guangdong and Jiangsu provinces enforce strictest thresholds, forcing tier-one suppliers to consolidate coating operations at centralized facilities.
Japan
Electronics assembly throughput requirements drive specification of hybrid UV-curable fluoropolymer formulations in high-mix manufacturing environments. METI industrial standards govern coating performance specifications for precision machinery exports. Nagoya automotive and Osaka electronics clusters concentrate qualified applicator technical service capabilities.
India
Automotive and aerospace component production incentives under PLI scheme create first-mover advantage for coating applicators establishing local technical service centers. BIS standards adoption accelerates as domestic OEMs integrate international specification requirements. Maharashtra and Tamil Nadu precision manufacturing clusters attract formulation chemistry expertise transfer from European suppliers.
Anti-Friction Coatings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with fluoropolymer heritage specialists commanding premium aerospace qualification positions while regional applicators compete on automotive volume scale. The market structure tiers between formulation innovators with captive laboratory capabilities and job-shop applicators dependent on external resin supply. Three archetypes dominate: integrated chemical producers with backward control into tetrafluoroethylene monomer supply, European tribology specialists with embedded OEM design influence, and Asian applicators consolidating water-based system capacity under MEE emission enforcement. Competitive moves concentrate on qualification timeline acceleration through NADCAP and EASA process approval stacking, and geographic expansion into India PLI scheme catchment areas.
Among integrated chemical producers, DuPont de Nemours Inc and The Chemours Company represent the fluoropolymer heritage tier with monomer supply chain positioning. Fuchs Petrolub SE anchors European automotive supply chain influence through captive tribology laboratory presence. These three exemplify distinct strategic positions: monomer-integrated formulation control, regional OEM design integration, and application-specific service depth respectively.
| Leading Market Players |
|---|
| Carl Bechem GMBH |
| Fuchs Petrolub SE |
| DuPont de Nemours Inc |
| Poeton Industries |
| Klüber Lubrication |
| The Chemours Company |
| Whitford Corporation |
| AGC Inc |
| Parker Hannifin Corp |
| Others |
Value Network & Pricing Analysis
Water-based fluoropolymer substitution for solvent-based systems is redrawing supply geography toward centralized coating facilities in Guangdong and Jiangsu provinces while compressing margins for job-shop applicators unable to fund spray booth reconfiguration and curing oven upgrades. This dual shift concentrates pricing power among integrated formulators with captive water-based capacity.
Pricing Analysis
REACH annex XVII dictates the pricing tier structure across European precision engineering clusters, separating NADCAP-qualified aerospace applicators from automotive tier-one suppliers and general industrial job shops. Price differentiation hinges on certification grade and volume scale, with MIL-PRF-46147 qualification commanding substantial premiums over commercial specifications. Cost compression in the standard tier is intensifying as Chinese domestic formulators scale water-based PTFE dispersion output. General industrial maintenance departments exhibit highest price sensitivity, while semiconductor equipment OEMs prioritize atomic-scale uniformity over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for tetrafluoroethylene monomer shipments originating from United States, Germany, and China production centers. Raw material dependencies center on fluoropolymer resin supply, thermoset curing agents, and sub-micron solid lubricant particles. Single-source vulnerability concentrates in tetrafluoroethylene monomer production, where limited chemical producers expose coating formulators to allocation risk. Distribution runs through qualified applicator networks with NADCAP and EASA process approvals, locking out unqualified job shops from specification-intensive end uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-friction coatings constitute a high-growth disruption as nanotechnology-enabled formulations displace conventional spray-applied systems in semiconductor fabrication equipment, with plasma-enhanced chemical vapor deposition compressing addressable markets for legacy service providers.
For Market Incumbents: Secure monomer supply chain positioning through backward integration or long-term offtake agreements with tetrafluoroethylene producers in the United States, Germany, or China. Accelerate NADCAP and EASA qualification stacking to compress new product introduction timelines against emerging UV-curable formulation specialists. Defensive consolidation should target captive tribology laboratory capabilities in Germany's precision engineering belt, where OEM design influence concentrates specification authority. For New Entrants and Emerging Players: Lead with UV-curable fluoropolymer hybrid formulations targeting electronics assembly throughput requirements in Japan's high-mix manufacturing environments. India's PLI scheme catchment areas for automotive and aerospace component production offer the most penetrable geography, with first-mover advantage accruing to applicators establishing local technical service centers in Maharashtra and Tamil Nadu. A technical service partnership model with European formulation chemistry specialists enables rapid capability assembly without decade-long tribology expertise development. For Investors and Strategic Acquirers: Capital is best deployed toward integrated chemical producers with backward control into tetrafluoroethylene monomer supply and established aerospace qualification positions. Long-term viability over the projection horizon favors formulators with water-based system capacity expansion underway in China's MEE-enforced provincial consolidation zones. The signal to monitor is qualification timeline compression for nanotechnology-enabled coatings in wafer handling robotics specifications, indicating technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Secures tetrafluoroethylene allocation priority against feedstock concentration risk from limited chemical producers. |
| Water-Based System Capacity Expansion | Captures solvent-based volume displacement driven by REACH annex XVII and EPA NESHAP enforcement. |
| NADCAP and EASA Qualification Stacking | Compresses 18-24 month aerospace approval timelines against multi-jurisdiction burden. |
| Technical Service Center Establishment | Secures first-mover positioning in India's PLI scheme precision manufacturing clusters. |
| UV-Curable Formulation Development | Addresses electronics assembly throughput requirements in Japan's METI-governed high-mix environments. |
Research Methodology
Desk research of fluoropolymer industry association reports, customs and trade flow databases, and SEC 10-K filings preceded structured interviews with coating applicator technical directors, automotive tier-one supplier procurement leads, aerospace OEM materials engineers, and tribology laboratory R&D heads. Primary fieldwork across Germany's precision engineering belt, China's Guangdong and Jiangsu province manufacturing clusters, and India's Maharashtra precision component zones validated secondary data through bottom-up and top-down triangulation.
Variance decomposition across product type, application, end user, and technology segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume and value build-ups, with cross-referencing to fluoropolymer resin consumption patterns and qualified applicator capacity expansion announcements. Forecast inputs incorporated REACH annex XVII implementation timelines, MEE provincial emission ceiling enforcement trajectories, and semiconductor fabrication equipment capital expenditure cycles.
Forecasts assume regulatory continuity in REACH, EPA NESHAP, and MEE enforcement regimes; material policy shifts would require re-modeling. Specific risk factors include tetrafluoroethylene monomer supply disruption, faster-than-anticipated plasma-enhanced chemical vapor deposition adoption in semiconductor equipment, and divergence between EU and US fluoropolymer chain-length restrictions. Practitioners should keep alternative scenarios live as nanotechnology qualification velocity and India PLI scheme uptake evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Low Friction Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Clear Coatings Market
Coatings
Global Powder Coating Market
Coatings
France Protective Coatings Market
Coatings
Silicate Coatings Market
Coatings
Global Water-Based Coatings Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
BPA-Free Coatings Market
Coatings
Epoxy Coating Market
Coatings
Global Photocatalytic Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Global Diamond Coatings Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Powder Coating Booth Market