
 Fire Retardant Coatings Market | 2026-2036
Fire Retardant Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Retardant Coatings Market Analysis
Waterborne resin chemistry is narrowing the performance gap between solvent-based and low-VOC fire retardant formulations. PPG Industries leverages its automotive refinish channel infrastructure to cross-sell protective coatings into commercial construction. Hempel A/S anchors its marine franchise with SOLAS-compliant deck and bulkhead systems. Akzo Nobel N.V. competes through Coil and Extrusion coatings that integrate intumescent layers for architectural steel.
Fire retardant coatings are reactive surface treatments formulated with halogen-free phosphorus, nitrogen, or expandable graphite compounds that char upon heat exposure to insulate substrates from flame propagation and limit smoke density. These systems typically achieve Class A or B ratings under ASTM E84 or EN 13501-1 protocols, with film builds ranging from dry thicknesses of one millimeter for thin-film intumescents to twenty-five millimeters for cementitious sprays. Intumescent coatings for structural steel dominate value pools due to code-mandated passive fire protection in high-rise construction. Epoxy-based marine formulations represent the fastest-growing chemistry segment as shipyards adopt IMO-compliant systems for newbuild LNG carriers and cruise vessels. Acrylic waterborne products occupy the economy tier in residential wood applications where brush-and-roll delivery limits specification complexity.
Construction Products Regulation in the European Union mandates CE marking under EN 13501-1 fire-reaction classification, forcing reformulation away from legacy halogenated additives. The US National Fire Protection Association's NFPA 251 and ICC's International Building Code govern hourly fire-resistance ratings for structural steel in commercial occupancies. China's Ministry of Emergency Management enforces GB 14907 standards for fireproof coatings on steel structures in public buildings. Stakeholders must monitor regulatory divergence between regional test protocols and the accelerating shift toward third-party certified environmental product declarations.
Market Dynamics
Construction safety codes are tightening fire-reaction class requirements across major economies, forcing coating formulators to abandon legacy halogenated chemistries and recertify entire product portfolios under stricter char-performance thresholds.
Growth Catalysts
- EU Construction Products Regulation:CE marking mandates under EN 13501-1 are pulling intumescent steel coatings into commercial retrofits across Germany, France, and Poland.
- LNG carrier newbuilds:IMO SOLAS compliance deadlines are accelerating specification of epoxy-based marine fireproofing systems in South Korean and Chinese shipyards.
- High-rise residential corridors:China's GB 14907 enforcement is mandating thin-film intumescents on structural steel in public buildings across the Yangtze River Delta.
Market Restraints
- Phosphorus feedstock concentration:Ammonium polyphosphate supply concentrates among Chinese producers, exposing formulators to export quota volatility.
- Test protocol divergence:ASTM E84 char ratings do not automatically transfer to EN 13501-1 certification, forcing redundant R&D expenditure for dual-market suppliers.
- Cementitious spray substitution:Lower-cost gypsum-based boards compete for structural steel protection in budget-sensitive Middle Eastern hospitality projects.
Strategic Opportunities
- India's smart cities program:Metro rail and airport infrastructure expansion is opening specification channels for waterborne intumescent systems in Mumbai and Delhi corridors.
- Mass timber construction:Cross-laminated timber commercial buildings in Canada and Scandinavia are creating demand for transparent fire-retardant wood finishes.
- Environmental product declarations:Third-party EPD certification is becoming a pre-qualification filter for public procurement in the Netherlands and Nordic markets.
Industry Challenges
- Intumescent formulator scarcity:Chemists with expertise in expandable graphite char-layer engineering command premium compensation, constraining mid-tier coating houses.
- Fire-test facility bottlenecks:ISO 834 furnace availability at accredited laboratories extends certification timelines for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Retardant Coatings Market |
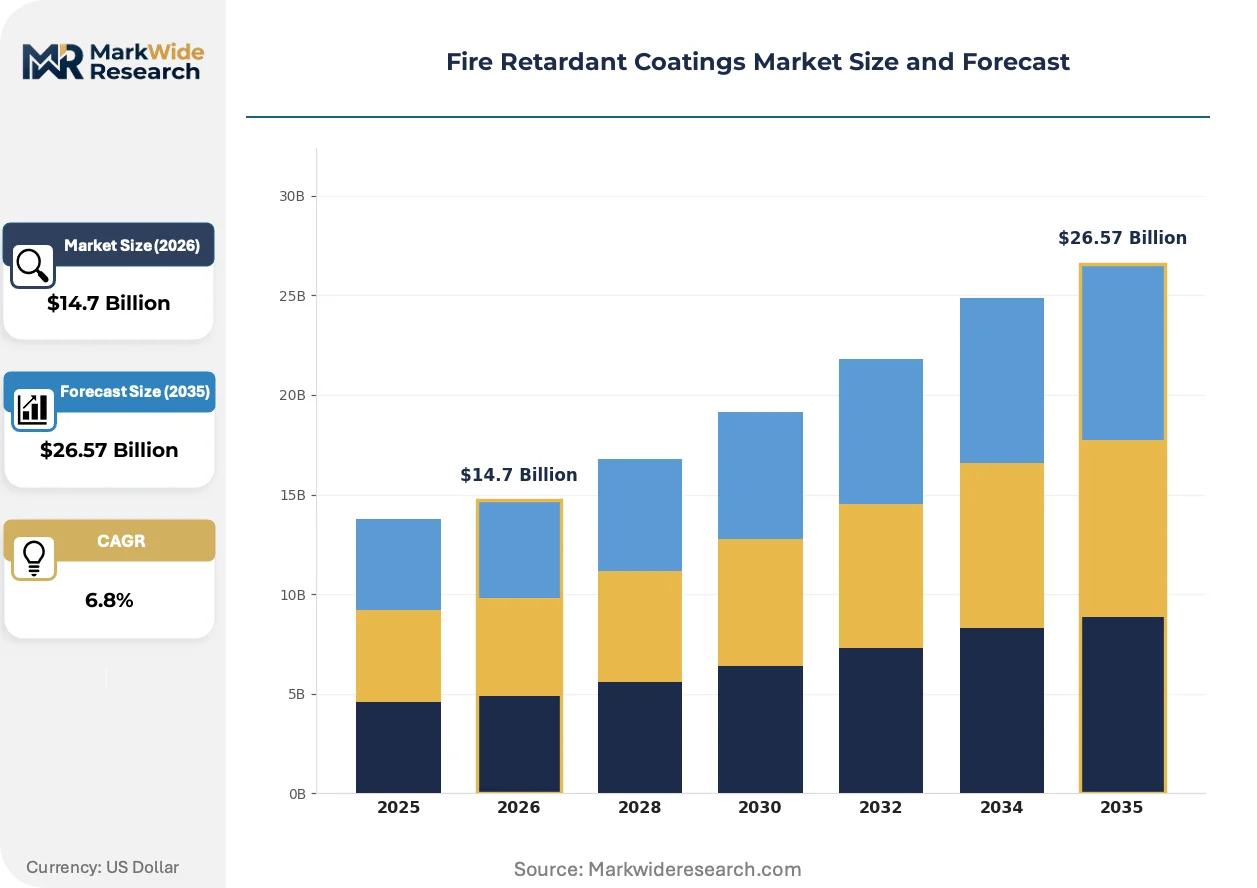
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Intumescent, Cementitious, Epoxy Application: Wood, Steel, Electrical, Fabric End User: Construction, Aerospace, Automotive, Marine Delivery Mode: Spray, Brush, Roll, Dip |
| Companies Covered | Jotun, BASF SE, Akzo Nobel N.V., Carboline, Nippon Paint Co., Ltd., PPG Industries, Hempel A/S, Promat International, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Retardant Coatings Market Emerging Trajectories
Waterborne resin platforms are narrowing the performance delta with solvent-based systems while regulatory pressure on volatile organic compounds intensifies. Formulators are embedding intumescent functionality into architectural coil coatings and exploring nano-additive char reinforcement.
Hybrid phosphorus-nitrogen intumescent chemistry is rendering obsolete conventional brominated flame retardants in interior architectural applications. Specifiers in Nordic commercial construction are prioritizing these halogen-free systems for LEED and BREEAM compliance. The shift is compressing demand for legacy additive packages and forcing raw material suppliers to reconfigure production assets.
REACH restrictions on halogenated substances are compelling coating houses to eliminate brominated and chlorinated additives from European formulations by fixed deadlines. Industrial consequences include accelerated patent filings for phosphorus-based alternatives and joint development agreements between resin suppliers and intumescent compound manufacturers. Architectural steel coatings for German and French infrastructure projects are experiencing the most acute certification pressure.
Certification-driven procurement is compressing supplier qualification cycles as EPC firms consolidate approved vendor lists around third-party fire-test documentation. Distributor relationships are displacing direct technical sales for standard-grade residential wood treatments. This pattern is most pronounced in the US residential construction channel where national homebuilders are centralizing specification authority.
Fire Retardant Coatings Market Segmentation
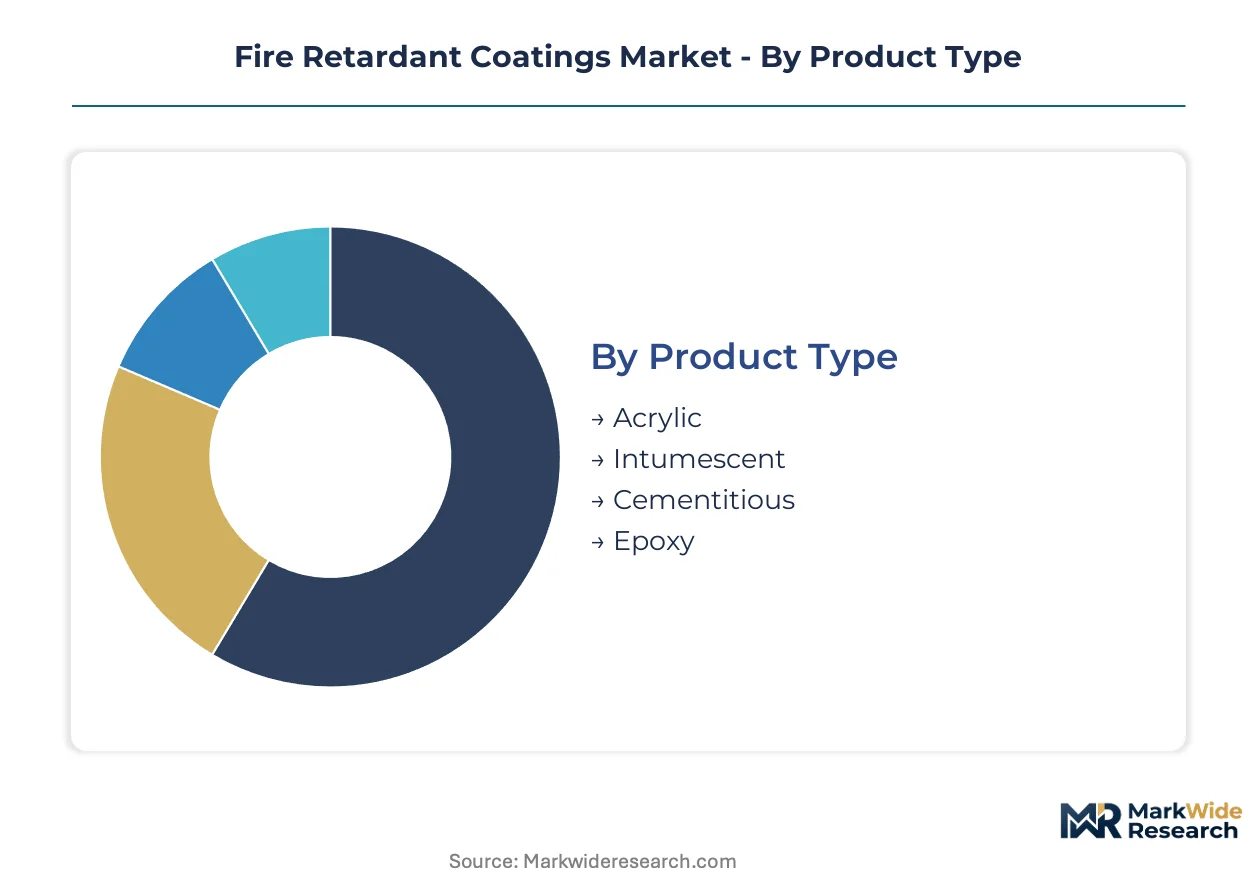
Fire retardant coatings fragment across formulation chemistry, substrate compatibility, and application method — each axis carrying distinct specification cycles, certification burdens, and margin profiles. Understanding segment turnover rates helps suppliers allocate R&D capacity and inventory investment across volatile versus stable demand pools.
Product Type:
Intumescent formulations turn over fastest as code revisions force char-performance recertification, while cementitious sprays cycle slowest due to entrenched specification in industrial infrastructure.
- Intumescent:Expandable graphite or phosphorus-nitrogen systems that swell into insulating char layers when heated. Demand concentrates on structural steel in China's high-rise residential corridors, driven by GB 14907 enforcement tightening hourly fire-resistance mandates.
- Epoxy:Marine-grade formulations achieving SOLAS compliance for LNG carrier newbuilds in South Korean shipyards. IMO deadlines are accelerating specification of these high-build systems for deck and bulkhead protection.
- Acrylic:Waterborne economy-tier products for residential wood applications where brush-and-roll delivery limits technical complexity.
- Cementitious:Spray-applied mineral-based coatings for heavy industrial steel, favored in budget-sensitive Middle Eastern hospitality projects.
Cementitious sprays anchor the volume base while intumescent coatings gain share at the steepest rate.
Application:
Steel applications command premium pricing due to code-mandated passive fire protection, while fabric treatments occupy the lowest margin tier with minimal regulatory specification.
- Steel:Thin-film intumescents and cementitious sprays protecting structural members in commercial construction. EU Construction Products Regulation mandates CE marking under EN 13501-1, pulling coatings into German and French retrofit projects.
- Wood:Transparent and pigmented finishes for mass timber buildings in Canada and Scandinavia. Cross-laminated timber commercial construction is creating specification channels for halogen-free systems.
- Electrical:Cable tray and junction box coatings for data center and utility infrastructure.
- Fabric:Theater curtains, event tents, and transportation seating textiles requiring NFPA 701 or EN 1021 compliance.
Steel coatings generate the highest revenue per liter applied, with wood finishes expanding most quickly in Nordic sustainable construction.
End User:
Construction consumes the largest absolute volume with the longest sales cycles, while marine procurement operates on compressed timelines tied to shipyard launch schedules.
- Construction:Commercial, residential, and infrastructure projects across Germany, France, Poland, and China's Yangtze River Delta. Public procurement in the Netherlands and Nordic markets now filters on third-party EPD certification.
- Marine:Newbuild and retrofit fireproofing for LNG carriers, cruise vessels, and offshore platforms. South Korean and Chinese shipyards dominate specification of IMO-compliant epoxy systems.
- Aerospace:Interior cabin materials and cargo bay coatings governed by FAA flammability standards.
- Automotive:Underhood components and battery enclosure protection for electric vehicle platforms.
Construction anchors demand volume while marine applications climb the fastest on LNG fleet expansion.
Delivery Mode:
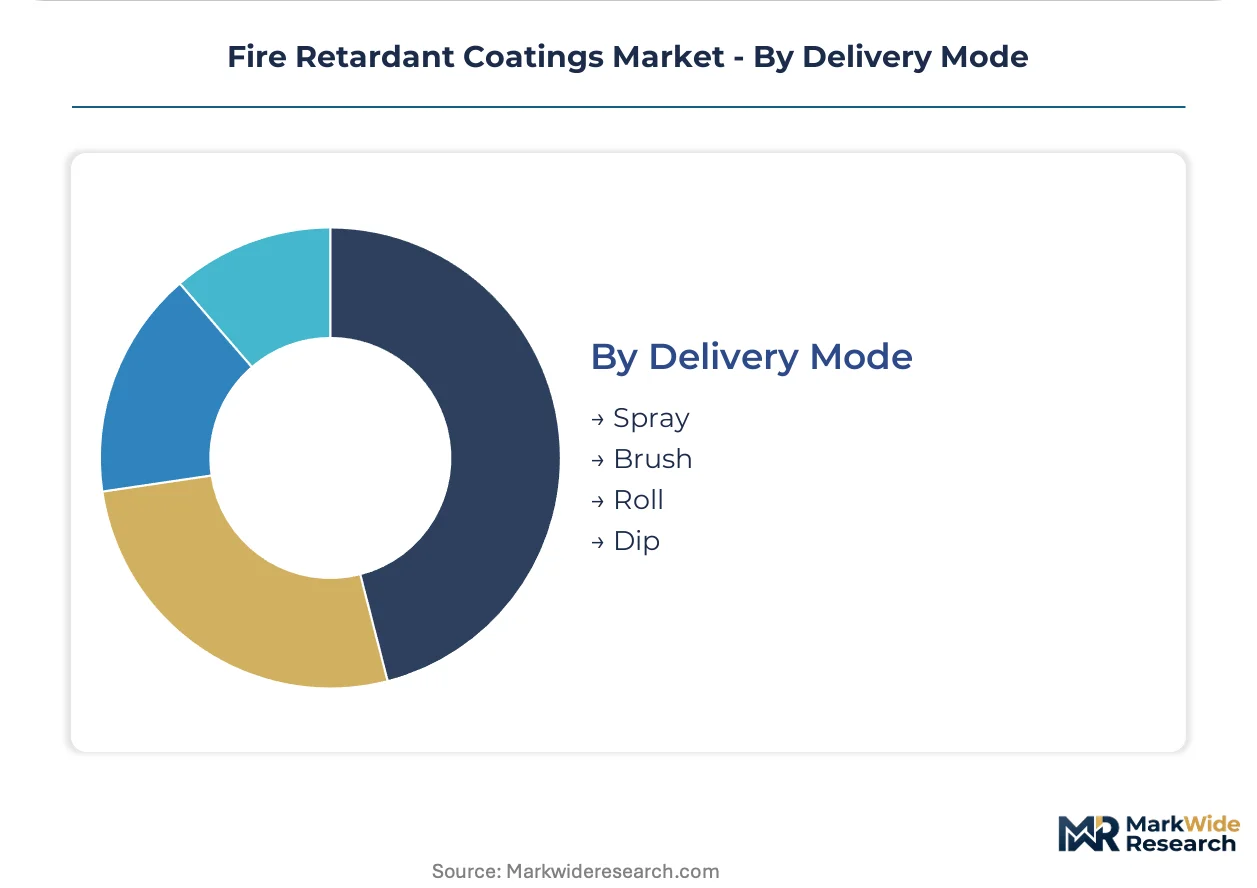
Spray application dominates commercial and industrial volume with the highest equipment barriers to entry, while brush-and-roll serves fragmented residential channels.
- Spray:Airless and plural-component equipment for intumescent and cementitious steel coatings. Certified applicator networks in Germany and France control specification access for infrastructure projects.
- Brush:Residential wood treatments distributed through DIY retail and contractor channels.
- Roll:Mid-tier commercial applications where film thickness tolerance is less critical.
- Dip:High-volume industrial processing for small components and electrical enclosures.
Spray delivery commands the value pool while brush application retains the widest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fire retardant coating exports flow predominantly into Southeast Asian infrastructure projects and Middle Eastern commercial developments, establishing trade corridors that shape regional pricing and specification standards.
China
High-rise residential construction along the Yangtze River Delta and Pearl River Delta drives thin-film intumescent demand. GB 14907 standards enforced by the Ministry of Emergency Management mandate hourly fire-resistance ratings on structural steel in public buildings. Shanghai and Hangzhou corridors concentrate specification activity for waterborne systems in metro rail and airport terminals.
Germany
Commercial retrofit projects across the Rhine-Ruhr and Bavarian industrial zones pull intumescent coatings into aging steel infrastructure. CE marking under EN 13501-1 mandated by the Construction Products Regulation forces reformulation away from legacy halogenated chemistries. Stuttgart and Munich clusters anchor specification channels for certified applicator networks in infrastructure tenders.
United States
Data center construction in Northern Virginia and Texas expands cable tray and junction box coating procurement. NFPA 251 and International Building Code provisions govern hourly fire-resistance ratings for commercial steel occupancies. Houston and Dallas-Fort Worth corridors concentrate demand for spray-applied cementitious systems in petrochemical and logistics facilities.
South Korea
LNG carrier newbuilds at Ulsan and Geoje shipyards accelerate epoxy-based marine fireproofing specification. IMO SOLAS compliance deadlines enforced by the maritime administration drive deck and bulkhead system procurement. Busan-Ulsan industrial belt concentrates coating application capacity for IMO-compliant systems in cruise vessel construction.
United Arab Emirates
Hospitality and commercial tower developments in Dubai and Abu Dhabi specify intumescent steel coatings for passive fire protection. Local building codes aligned with British Standards and NFPA protocols govern fire-reaction classification for high-rise structures. Dubai South and Abu Dhabi Reem Island clusters concentrate specification activity for luxury hotel and mixed-use projects.
Fire Retardant Coatings Market Vendor Landscape
Channel-controlling players compete with product-specialist players across certification-heavy procurement environments. The vendor base organizes into three tiers: multinational coating houses with certified applicator networks, regional formulators with localized fire-test documentation, and raw material suppliers backward-integrated into compound production. Consolidation pressure concentrates among mid-tier European formulators facing REACH compliance deadlines. Dominant competitive moves include capacity expansion in Asian marine coating facilities and technology licensing agreements for phosphorus-nitrogen intumescent chemistry.
Among diversified chemical conglomerates, BASF SE and Akzo Nobel N.V. exemplify the integrated-resin-to-coating archetype with control over phosphorus additive supply chains. PPG Industries represents the channel-leveraging archetype, cross-selling protective coatings through automotive refinish infrastructure into commercial construction specification. Jotun occupies a specialist position in marine-grade epoxy systems, anchoring its competitive stance through SOLAS-compliant deck and bulkhead formulations for LNG carrier newbuilds.
| Leading Market Players |
|---|
| Jotun |
| BASF SE |
| Akzo Nobel N.V. |
| Carboline |
| Nippon Paint Co., Ltd. |
| PPG Industries |
| Hempel A/S |
| Promat International |
| The Sherwin-Williams Company |
| Others |
Supply Flow & Price Mechanics
Phosphorus feedstock concentration among Chinese ammonium polyphosphate producers creates dual vulnerability—export quota volatility compresses margins for formulators while simultaneously forcing tiered pricing spreads between certified premium grades and economy-tier alternatives.
Pricing Analysis
The technology-generation pricing gap separates solvent-based legacy formulations from waterborne next-generation systems and hybrid phosphorus-nitrogen advanced chemistries. Three-tier pricing structure across premium certified, standard compliant, and economy generic levels dominates, with differentiation driven by EN 13501-1 certification tier and applicator network access. Pricing pressure stems from cementitious spray substitution in Middle Eastern budget projects. Residential wood brush-and-roll buyers exhibit highest price sensitivity; marine LNG newbuild specifiers show lowest.
Supply Chain Analysis
Tariff exposure between China and Western coating houses dominates supply chain risk planning for phosphorus additive procurement. Manufacturing concentrates in China, Germany, and South Korea. Formulation draws from ammonium polyphosphate, expandable graphite, and epoxy resin feedstocks. Single-source vulnerability concentrates in Chinese phosphorus compound production. Distribution runs through certified applicator networks in commercial construction and shipyard direct procurement in marine.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
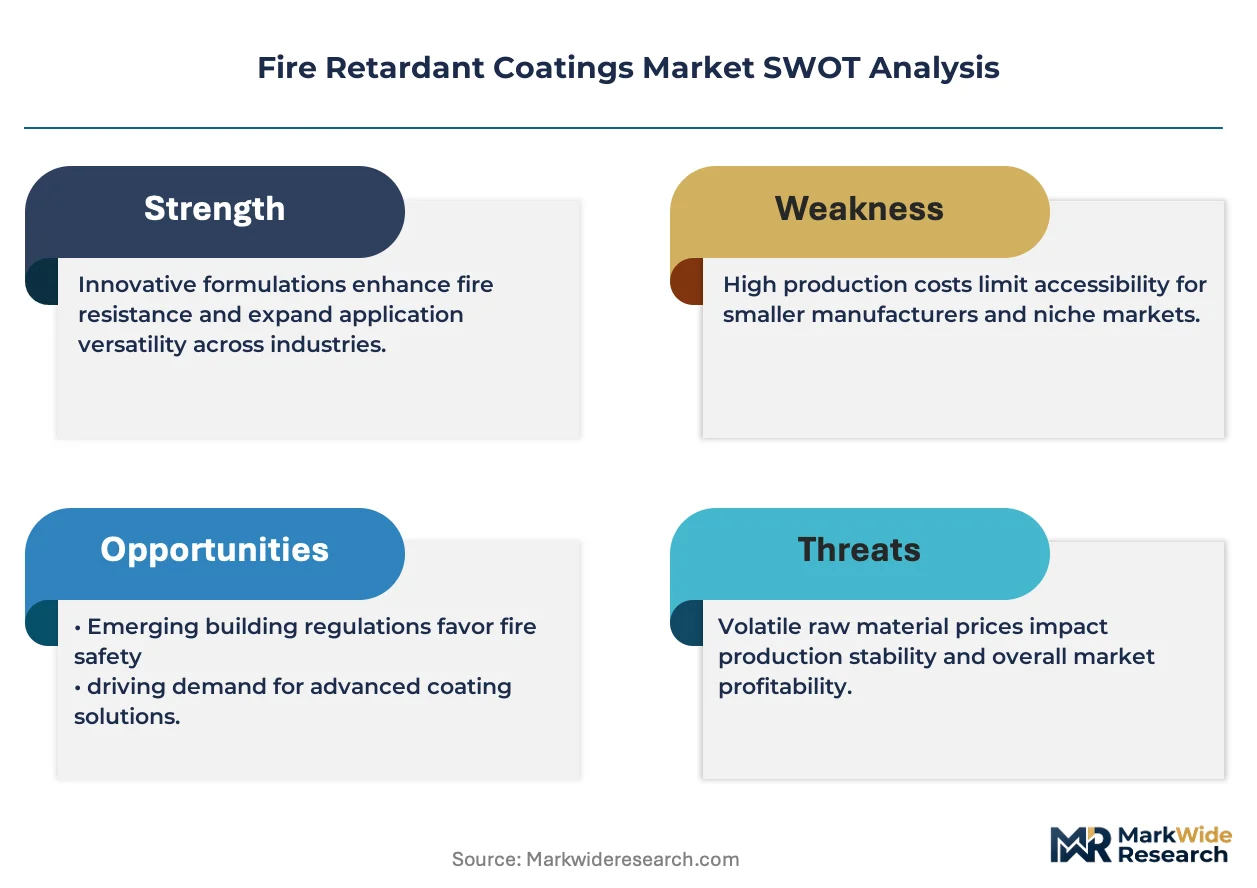
Fire retardant coatings are approaching a platform-economics inflection where CE marking databases and third-party EPD registries create interoperability moats that lock in specification authority.
For Market Incumbents: Build certification-database moats by embedding products into national procurement portals and EPC pre-approved vendor lists. Cementitious spray substitution in Middle Eastern hospitality and REACH deadline compression for halogenated legacy portfolios demand accelerated phosphorus-nitrogen R&D partnerships and captive applicator network expansion in German infrastructure corridors. For New Entrants and Emerging Players: Pursue India's smart cities metro rail and airport infrastructure as the most penetrable geography, where waterborne intumescent specification channels remain underdeveloped. Mass timber commercial construction in Canada and Scandinavia offers second white-space target. Go-to-market angle: transparent halogen-free wood finish certification for LEED/BREEAM compliance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-tier European formulators with REACH-compliant product portfolios and established EN 13501-1 documentation. Long-term viability hinges on regulatory certification assets rather than manufacturing scale. Watch for phosphorus additive supply agreements as inflection signal—backward-integrated compound producers command durable margin advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Additives | Captive ammonium polyphosphate supply shields formulators from Chinese export quota volatility. |
| CE Marking Database Registration | EN 13501-1 pre-qualification locks incumbents into German and French public procurement filters. |
| Certified Applicator Network Expansion | Stuttgart and Munich infrastructure tenders require approved installer relationships for specification access. |
| Waterborne Resin Platform Migration | Low-VOC chemistry narrows performance gap with solvent systems under tightening EU emissions rules. |
| Marine Epoxy Capacity Buildout | Ulsan and Geoje shipyard proximity accelerates IMO SOLAS-compliant system delivery for LNG carriers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coating formulators, certified applicator network managers, shipyard procurement officers, and EPC firm specification engineers. Secondary validation drew from EN 13501-1 certification databases, IMO SOLAS compliance registries, customs trade data for phosphorus additive flows, and SEC filings of listed coating houses. Bottom-up segment sizing triangulated against top-down construction and marine output metrics.
Calibration anchored volume and value outputs to observed specification cycles across the analysis window, modeling chemistry type, substrate application, end-use sector, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from fitted growth curves applied to base-year verified consumption. Industry-specific inputs included shipyard orderbook pipelines for marine epoxy demand and high-rise residential permit data for intumescent steel coating projections.
Macroeconomic conditions sit as an overlay; deviation in construction investment cycles, maritime freight rates, or phosphorus commodity pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Plastic Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
2K Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
PU Coatings Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Zero Friction Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Asia-Pacific Protective Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Global Passive Fire Protection Coatings Market