
 Global Thermal Paste Market | 2026-2036
Global Thermal Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Paste Market Outlook
Chiplet-based processor architectures is fragmenting thermal management strategies across high-performance computing platforms. Shin-Etsu Chemical leverages its silicone polymer expertise to supply metal-based formulations for advanced packaging nodes. Thermal Grizzly anchors the enthusiast and workstation segments with specialized liquid metal compounds. Momentive Performance Materials competes through captive silane chemistry and vertical integration into thermal filler production.
Thermal paste is a thermally conductive compound, typically formulated with metal oxides, ceramic particles, or liquid metal alloys suspended in a silicone or synthetic oil matrix, designed to eliminate air gaps between heat-generating components and cooling hardware. Its primary purpose is to reduce thermal resistance at interface surfaces, enabling efficient heat dissipation in processors, power semiconductors, and LED modules. Metal-based pastes command premium positioning in data center and AI accelerator applications where thermal conductivity exceeds 70 W/mK. Ceramic-based formulations sustain broader adoption in automotive power electronics where electrical isolation properties prove critical. Silicone-based products occupy cost-sensitive consumer electronics channels with mature supply chains and standardized performance tiers.
EPA energy efficiency standards for data center equipment are tightening thermal design requirements, pushing OEMs toward higher-performance interface materials. REACH compliance in Europe restricts certain heavy metal fillers, redirecting formulation R&D toward gallium-based and boron nitride alternatives. China's GB standards for electronic product safety are converging with IEC thermal cycling test protocols, harmonizing qualification barriers for multinational suppliers. Stakeholders must monitor how chiplet disaggregation and heterogeneous integration reshape contact area geometries and thermal paste application volumes.
Market Dynamics
Chiplet disaggregation in AI accelerators is fragmenting thermal interface requirements, multiplying contact geometries per processor package while compressing allowable thermal resistance thresholds.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated greenhouse gases used in competing liquid cooling systems redirect data center operators toward high-conductivity paste solutions for air-cooled racks.
- GPU-intensive AI server deployment:Hyperscalers in Taiwan and the United States are expanding procurement of metal-based thermal interface materials for densely packed accelerator modules.
- Heterogeneous integration:Advanced packaging nodes combining logic dies with high-bandwidth memory are creating non-planar thermal profiles that demand specialized filler formulations.
Market Restraints
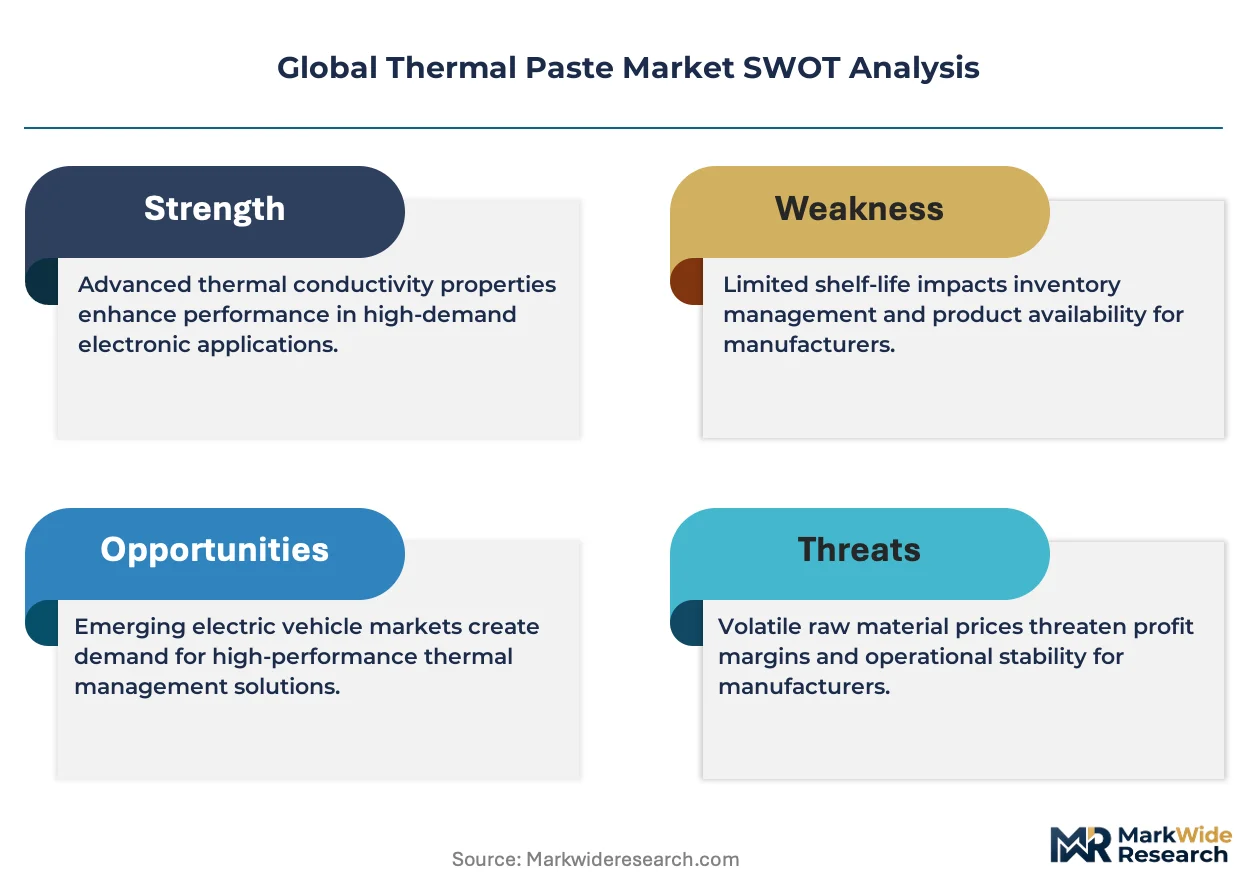
- Gallium supply concentration:Liquid metal paste producers depend on Chinese gallium refining capacity, exposing formulation costs to export control volatility.
- REACH heavy metal restrictions:European chemical regulations are phasing out certain metallic fillers, forcing reformulation cycles that extend qualification timelines.
- Solid-state thermal interface substitution:Phase-change materials and graphite sheets are capturing socket applications where paste reapplication cycles create maintenance liability.
Strategic Opportunities
- India electronics manufacturing:Production-linked incentive schemes for semiconductor assembly and test facilities are creating first-mover advantage for localized thermal paste supply.
- Automotive power module electrification:Silicon carbide inverter platforms require ceramic-based formulations combining thermal conductivity with dielectric isolation.
- Direct-to-OEM digital channels:Contract manufacturers in Taiwan's semiconductor packaging corridor are consolidating supplier relationships through integrated e-procurement platforms.
Industry Challenges
- Application automation skill gaps:Precision dispensing of nano-filled pastes at chiplet scale requires technicians trained in robotic surface-mount integration.
- Cross-regional certification latency:Simultaneous qualification under EPA energy efficiency standards, EU REACH, and China's GB protocols extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Paste Market |
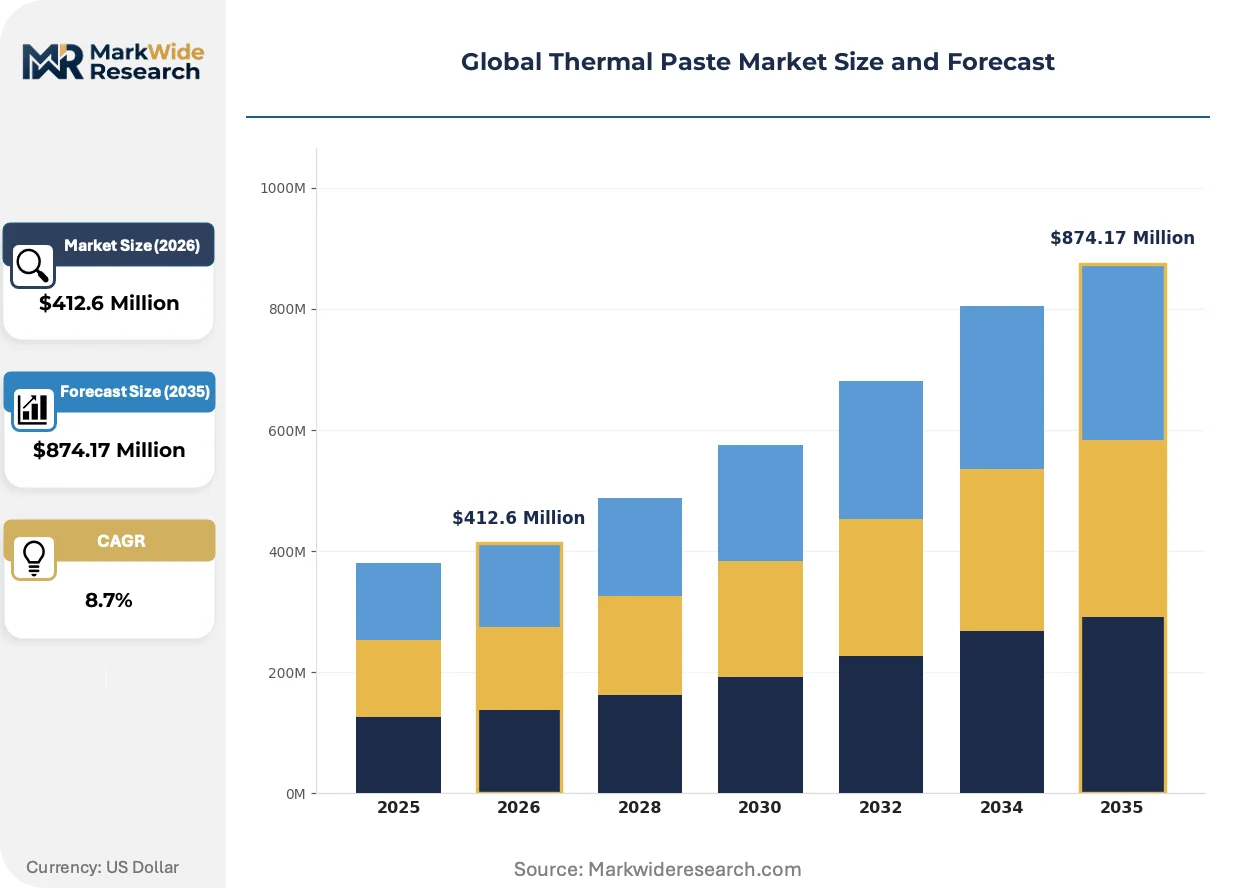
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Metal-Based, Ceramic-Based, Epoxy-Based Application: CPU, GPU, Power Devices, LED End User: Consumer Electronics, Automotive, Industrial Equipment, Aerospace Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Thermalright, Shin-Etsu Chemical, Thermal Grizzly, Momentive Performance Materials, Dow Corning, Arctic, Alphacool, Henkel, Noctua, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Paste Market Strategic Shifts
Thermal management architectures are pivoting from monolithic processor designs toward distributed heat sources, forcing interface material suppliers to engineer for non-uniform contact pressure and variable gap tolerances.
Metal-based thermal paste formulations incorporating gallium-indium-tin eutectics are migrating from enthusiast overclocking segments into data center GPU accelerators. Hyperscale operators in Taiwan and the United States are qualifying these compounds for direct-die applications where thermal conductivity exceeds 70 W/mK. This migration from silicone-ceramic matrices is compressing the performance gap between air-cooled and liquid-cooled rack architectures.
EPA energy efficiency standards for data center equipment are tightening thermal design power thresholds, compelling OEMs to specify higher-grade interface materials in server bill-of-materials. The regulatory pressure is accelerating qualification of boron nitride and aluminum nitride fillers as REACH-compliant alternatives to legacy metal oxides. North American server manufacturers are responding by consolidating supplier audits around dual-certified formulation houses.
Consolidated procurement by Taiwan-based semiconductor packaging foundries is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. These foundries are shifting toward specification-defined spot purchasing through digital exchanges, displacing long-term volume agreements. The pattern is most pronounced in advanced packaging nodes where thermal paste consumption scales with chiplet count rather than package area.
Global Thermal Paste Market Segmentation
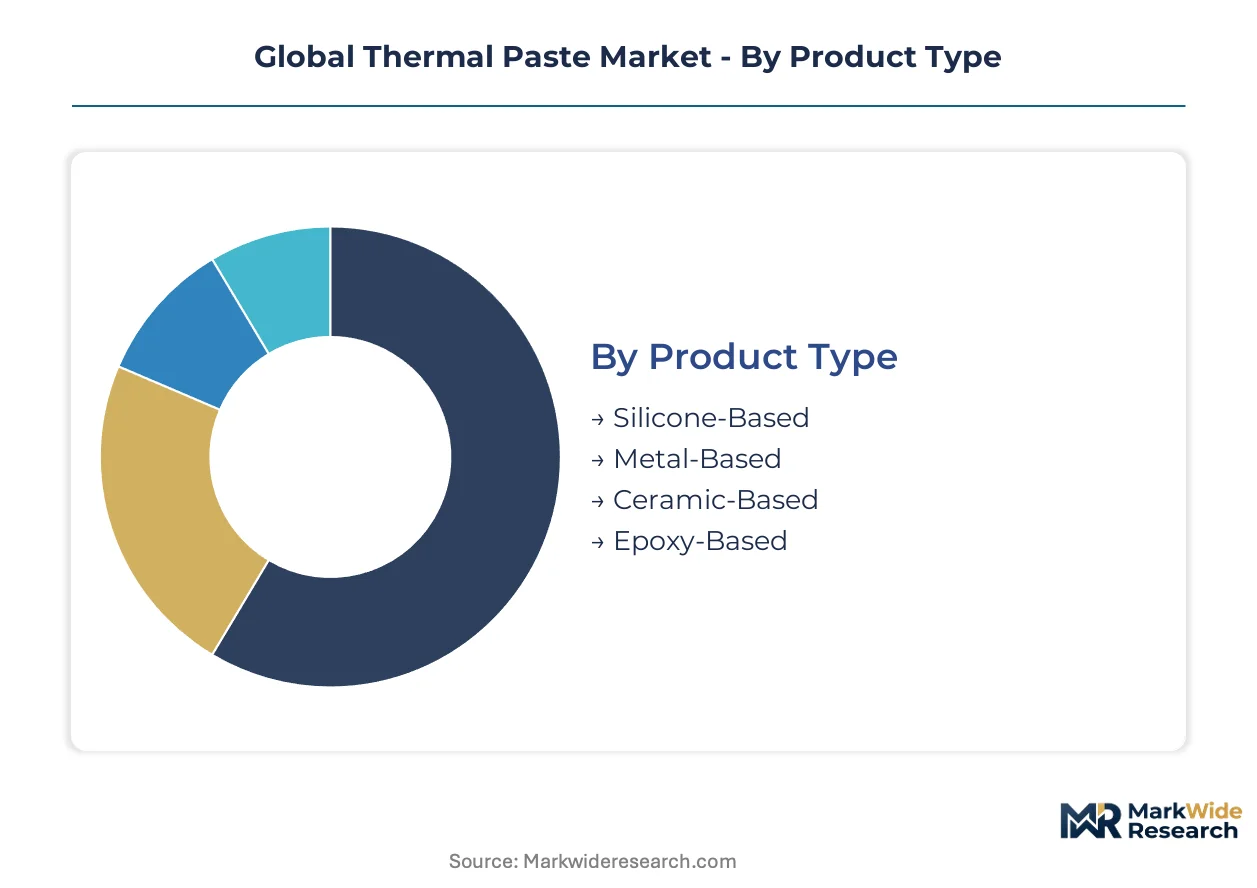
Thermal paste formulations diverge sharply across thermal conductivity requirements, electrical isolation needs, and application automation compatibility. Segmentation reveals how suppliers align material chemistry with specific heat dissipation challenges in semiconductor packaging.
Product Type:
The use-case spectrum spans consumer electronics repair kits to AI accelerator direct-die attachment, with conductivity thresholds dictating formulation chemistry.
- Metal-Based:Gallium-indium-tin eutectics and silver-filled suspensions achieve thermal conductivity exceeding 70 W/mK. Hyperscale data centers in Taiwan and the United States specify these compounds for GPU-intensive AI server racks where thermal resistance compression is critical.
- Ceramic-Based:Boron nitride and aluminum oxide particles suspended in silicone matrices deliver dielectric isolation alongside moderate conductivity. Automotive silicon carbide inverter platforms in Germany and Japan demand these formulations for power module electrification where electrical isolation proves mandatory.
- Silicone-Based:Cost-optimized metal oxide fillers serve high-volume consumer electronics assembly in China and Vietnam.
- Epoxy-Based:Thermally conductive adhesives with permanent bonding properties anchor LED module manufacturing in South Korea.
Established volume favors silicone-based compounds; emerging adoption favors metal-based formulations.
Application:
Contact geometry complexity escalates from planar CPU heat spreaders to non-uniform chiplet architectures.
- GPU:Accelerator modules with dense memory stacking create variable gap tolerances demanding specialized filler rheology. Taiwan-based packaging foundries consume premium metal-based pastes for NVIDIA and AMD chiplet disaggregation designs.
- CPU:Traditional planar interfaces sustain ceramic and silicone formulation demand across server and desktop segments.
- Power Devices:Silicon carbide and gallium nitride switches in automotive traction inverters require ceramic-based thermal management with voltage isolation.
- LED:High-brightness lighting modules specify epoxy-based compounds for permanent thermal path establishment.
GPU applications are climbing the fastest; CPU volumes anchor baseline demand.
End User:
Certification intensity separates aerospace qualification cycles from consumer electronics spot purchasing.
- Automotive:AEC-Q100 thermal cycling standards and IEC 60747 compliance dominate supplier selection. German and Japanese OEMs specify ceramic formulations for 800V silicon carbide platforms.
- Consumer Electronics:Mature supply chains in China prioritize cost-optimized silicone-based products with standardized performance tiers.
- Industrial Equipment:Motor drive and power supply manufacturers specify mid-tier ceramic formulations.
- Aerospace:DO-160 environmental testing and outgassing requirements restrict qualified suppliers to specialized epoxy and ceramic compounds.
Automotive qualification timelines favor established ceramic suppliers; consumer electronics procurement favors flexible formulation houses.
Distribution Channel:
Contract manufacturer consolidation is compressing channel diversity in advanced packaging nodes.
- Direct Sales:Taiwan semiconductor packaging foundries specify thermal paste through integrated e-procurement platforms, unbundling technical service from material supply.
- Distributors:Regional electronics component distributors serve mid-tier automotive and industrial customers with stocked ceramic and silicone formulations.
- Online Retail:Enthusiast overclocking segments purchase liquid metal compounds through specialized e-commerce channels.
- Wholesalers:Volume assembly operations in Vietnam and India source cost-optimized silicone products through bulk procurement.
Direct sales capture premium specification-defined purchasing; distributors sustain fragmented regional demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and semiconductor packaging foundries concentrate procurement decisions in five countries where thermal paste specifications directly track AI accelerator deployment cycles and domestic chemical regulations.
United States
Hyperscale cloud operators in Northern Virginia and Phoenix drive metal-based thermal paste consumption for GPU-intensive AI training clusters. EPA energy efficiency standards for data center equipment tighten thermal design power thresholds, compelling server OEMs to specify higher-conductivity interface materials. Texas and Arizona host the densest concentrations of air-cooled rack deployments where paste solutions substitute for restricted liquid cooling systems.
Taiwan
Semiconductor packaging foundries in Hsinchu and Taichung consume premium formulations for chiplet disaggregation designs serving NVIDIA and AMD accelerator modules. The island's GB standards convergence with IEC thermal cycling protocols streamlines qualification for multinational suppliers. Kaohsiung-based contract manufacturers consolidate procurement through integrated e-procurement platforms, compressing supplier negotiation cycles.
Germany
Automotive OEMs in Stuttgart and Munich specify ceramic-based formulations for 800V silicon carbide inverter platforms requiring dielectric isolation. REACH heavy metal restrictions phase out certain metallic fillers, redirecting formulation R&D toward boron nitride alternatives. Bavarian power electronics clusters anchor European demand for AEC-Q100 qualified thermal interface materials.
China
Consumer electronics assembly in Shenzhen and Dongguan sustains high-volume silicone-based paste consumption for cost-optimized devices. Gallium refining capacity concentration exposes liquid metal paste producers to export control volatility affecting formulation costs. Yangtze River Delta packaging facilities scale procurement for domestic AI accelerator programs.
Japan
Automotive and industrial equipment manufacturers in Toyota City and Osaka specify mid-tier ceramic formulations for motor drive applications. METI industrial standards influence thermal management specifications across precision electronics sectors. Kyushu-based power module producers qualify specialized compounds for silicon carbide traction inverter deployment.
Global Thermal Paste Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Chemical conglomerates with captive silicone polymer capabilities dominate volume supply to semiconductor packaging foundries, while niche formulators capture premium positioning in enthusiast and data center segments. Three archetypes structure competition: integrated chemical majors, specialized thermal interface material houses, and regional formulation contractors. Capacity expansion in Taiwan and strategic partnerships with AI server OEMs constitute the dominant competitive moves reshaping supplier relationships.
Within the integrated chemical major tier, Shin-Etsu Chemical and Momentive Performance Materials exemplify players leveraging backward integration into silane chemistry and thermal filler production. Thermal Grizzly occupies a position representing the specialized enthusiast-to-data-center migration archetype, anchoring premium metal-based formulation demand. Henkel and Arctic sit within the diversified industrial-adhesives segment, representing European and regional German fabrication capabilities respectively.
| Leading Market Players |
|---|
| Thermalright |
| Shin-Etsu Chemical |
| Thermal Grizzly |
| Momentive Performance Materials |
| Dow Corning |
| Arctic |
| Alphacool |
| Henkel |
| Noctua |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's silicone polymer feedstock sector is compressing raw material costs for mid-tier thermal paste producers while tightening margin pressure on specialized metal-based formulators serving hyperscale data centers. This utilization asymmetry splits supplier behavior between commodity-grade volume players and premium-positioned niche houses.
Pricing Analysis
Cost-plus contracts indexed to gallium spot prices dominate liquid metal paste procurement between Taiwan packaging foundries and Japanese chemical suppliers. Pricing stratifies across premium metal-based, standard ceramic, and economy silicone tiers, with differentiation driven by thermal conductivity certification and volume scale commitments. Cost compression in the silicone tier is intensifying because Vietnamese assemblers are consolidating spot purchasing through digital exchanges. Consumer electronics OEMs in Shenzhen exhibit highest price sensitivity; data center operators in Northern Virginia prioritize conductivity thresholds over unit cost.
Supply Chain Analysis
Upstream gallium refining concentrates in China, while silicone polymer production clusters in Japan and Germany. Formulation houses draw from boron nitride deposits in Turkey, aluminum oxide from Australian bauxite, and synthetic silanes from South Korean petrochemical complexes. Single-source vulnerability around Chinese gallium export controls exposes liquid metal paste producers to supply disruption. Distribution runs through Taiwan-based semiconductor packaging foundries for premium specifications, with regional electronics distributors serving fragmented automotive and industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of technicians trained in robotic nano-paste dispensing at chiplet scale is constraining capacity expansion for advanced packaging nodes. This capability gap separates formulators with automated application partnerships from commodity suppliers locked in manual assembly channels.
For Market Incumbents: Build formulation IP moats around REACH-compliant gallium alternatives and boron nitride suspensions to preempt regulatory displacement. Deepen backward integration into thermal filler production through captive silane chemistry investments. Consolidate supplier audits around dual-certified formulation houses to compress qualification timelines for EPA and EU compliance. For New Entrants and Emerging Players: Build out localized supply capabilities in India's semiconductor assembly corridor under production-linked incentive schemes before incumbent foundry relationships solidify. Target automotive power module electrification in Germany and Japan where AEC-Q100 certification barriers filter out commodity competitors. Pursue direct-to-OEM digital channel partnerships with Kaohsiung contract manufacturers bypassing traditional distribution markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across metal-based thermal paste sub-segments as gallium refining capacity and precision dispensing automation require concentrated capital deployment. Viable acquisition targets include mid-tier ceramic formulators with existing REACH certification infrastructure and foundry-adjacent technical service capabilities. Monitor gallium export control announcements from Chinese regulators as the critical inflection signal for formulation cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Filler Production | Captive silane chemistry reduces gallium price volatility exposure for metal-based formulators. |
| REACH-Compliant Alternative Formulation | Boron nitride suspensions preempt regulatory phase-out of legacy metal oxide fillers in EU markets. |
| Localized Supply Agreement in India | Production-linked incentive schemes create first-mover advantage for semiconductor assembly corridors. |
| Direct-to-OEM Digital Channel Partnership | Taiwan foundries consolidate procurement through integrated e-procurement platforms. |
| Robotic Dispensing Automation Investment | Precision application at chiplet scale addresses technician scarcity in advanced packaging nodes. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with thermal interface material R&D directors, semiconductor packaging procurement managers, data center infrastructure engineers, automotive power electronics sourcing leads, and chemical distribution channel partners. Secondary validation drew from EPA energy efficiency filings, ECHA REACH substance registrations, Taiwan customs trade data, SEC 10-K disclosures from listed chemical conglomerates, and IEC thermal cycling test protocols. Bottom-up volume estimates from foundry consumption patterns were triangulated against top-down market sizing from chemical feedstock production data.
Calibration against historical gallium price volatility and Taiwan semiconductor equipment capex cycles anchored the projection framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, application contact geometry complexity, end-use certification intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating GPU server deployment trajectories and automotive silicon carbide inverter adoption rates.
Stress conditions across gallium export restriction severity, REACH heavy metal phase-out acceleration, and chiplet disaggregation penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about thermal design power thresholds and heterogeneous integration timelines. Cross-checking against hyperscaler data center capex disclosures and AEC-Q100 qualification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
Solar-Grade Polysilicon Market