
 Encapsulant Market | 2026-2036
Encapsulant Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulant Market Foresight
Asian chemical producers is consolidating output of advanced silicone encapsulants for photovoltaic and electronics applications. Dow leverages integrated silicone monomer capacity across its manufacturing network. Shin-Etsu Chemical Co., Ltd. sustains leadership in high-purity silicone materials through captive quartz refining. Henkel competes in epoxy and polyurethane formulations for automotive electronics protection.
An encapsulant is a protective barrier material, typically formulated from silicone, epoxy, or polyurethane with controlled viscosity between 500 and 5000 cPs and dielectric strength exceeding 15 kV/mm, that is applied to enclose sensitive components against moisture, thermal shock, and mechanical stress. Its primary purpose is to extend operational life of electronics, LEDs, and solar cells by preventing environmental degradation. Silicone encapsulants command the largest share of product type demand due to thermal stability requirements in photovoltaic modules. Solar cell application represents the fastest-growing segment as bifacial and heterojunction technologies require advanced barrier properties. Electronics application anchors margin pools where miniaturization demands precision dispensing of high-purity formulations.
EPA regulates volatile organic compound emissions from encapsulant curing processes in the United States, while REACH restricts hazardous substance content in European formulations, and IEC 61215 sets reliability testing standards for photovoltaic module encapsulation. These frameworks compel manufacturers to reformulate toward halogen-free, low-outgassing chemistries and document full material transparency for module certification. Stakeholders must monitor evolving photovoltaic efficiency standards and corresponding encapsulant thermal conductivity requirements as cell architectures advance.
Market Dynamics
Photovoltaic module manufacturers are forcing rapid encapsulant reformulation as bifacial and heterojunction cell architectures multiply thermal cycling demands beyond legacy silicone specifications.
Growth Catalysts
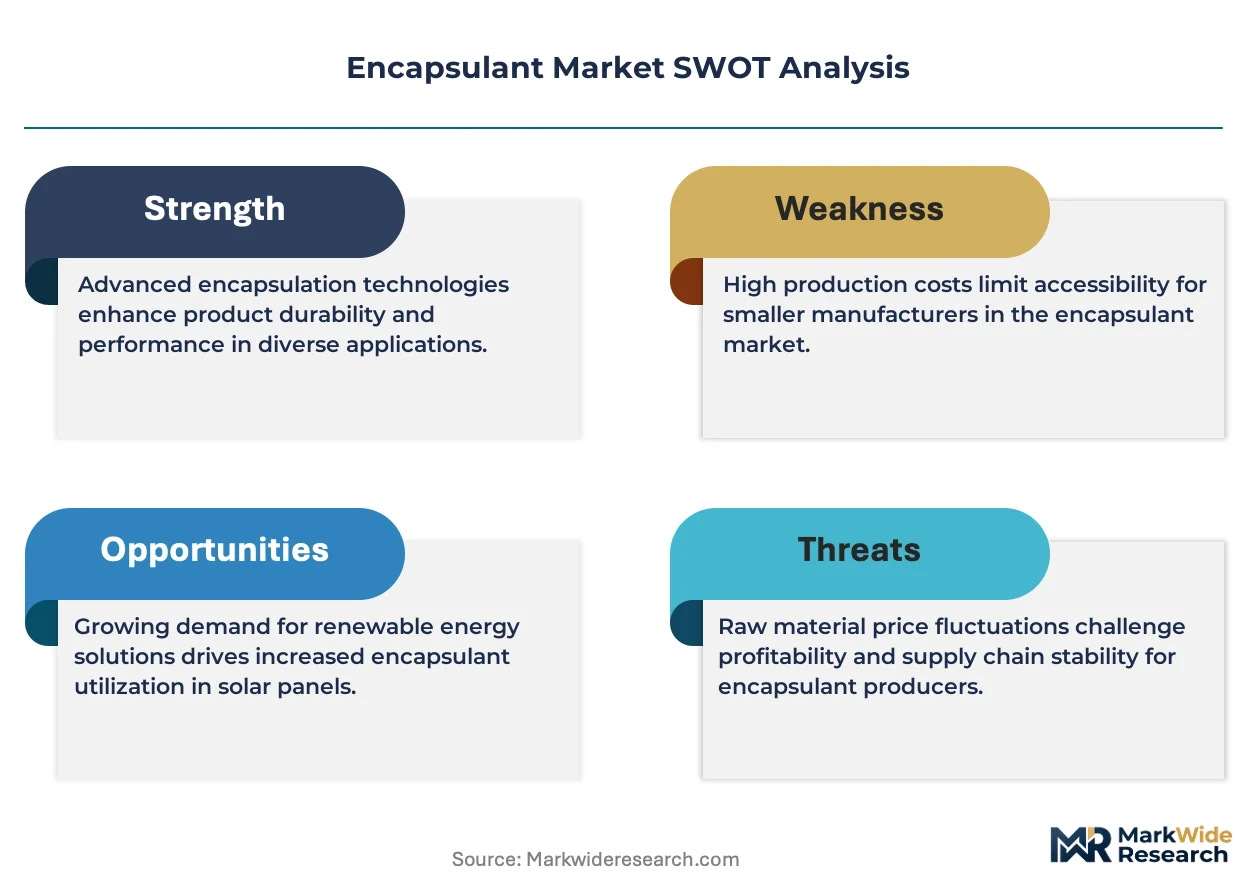
- REACH and RoHS compliance deadlines:European formulators are accelerating low-VOC silicone system development to meet substance restrictions, creating pull-through demand for compliant raw materials.
- China's domestic module production:Concentrated solar cell manufacturing in Jiangsu and Zhejiang provinces sustains captive encapsulant consumption at scale unmatched elsewhere.
- Heterojunction cell diffusion:Advanced barrier requirements for moisture-sensitive cell architectures are expanding specification ranges for high-purity silicone grades.
Market Restraints
- Metallurgical-grade silicon price volatility:Quartz feedstock cost swings compress margins for silicone encapsulant producers without captive mining operations.
- Single-source quartz refining:High-purity silicon metal supply concentrates among limited Japanese and Chinese producers, amplifying disruption risk.
- Epoxy substitution in automotive:Polyurethane and epoxy systems are capturing select electronics protection applications where thermal stability requirements moderate.
Strategic Opportunities
- India's solar manufacturing buildout:PLI scheme subsidies for domestic module production are creating new encapsulant demand centers outside established supply chains.
- Perovskite tandem cell commercialization:Emerging cell architectures with distinct barrier requirements will necessitate formulation partnerships between encapsulant suppliers and cell developers.
- IEC 61215 revision cycles:Accelerated reliability testing standard updates are opening certification service adjacencies for materials suppliers with in-house testing capabilities.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in silicone rheology and photovoltaic degradation mechanisms concentrates among retiring specialists at incumbent suppliers.
- Module certification timeline compression:IEC 61215 testing protocols now require 12-18 month validation cycles that delay new encapsulant commercialization.
- Multi-jurisdiction substance documentation:Divergent REACH, EPA TSCA, and China MEE filing requirements multiply compliance overhead for global formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulant Market |
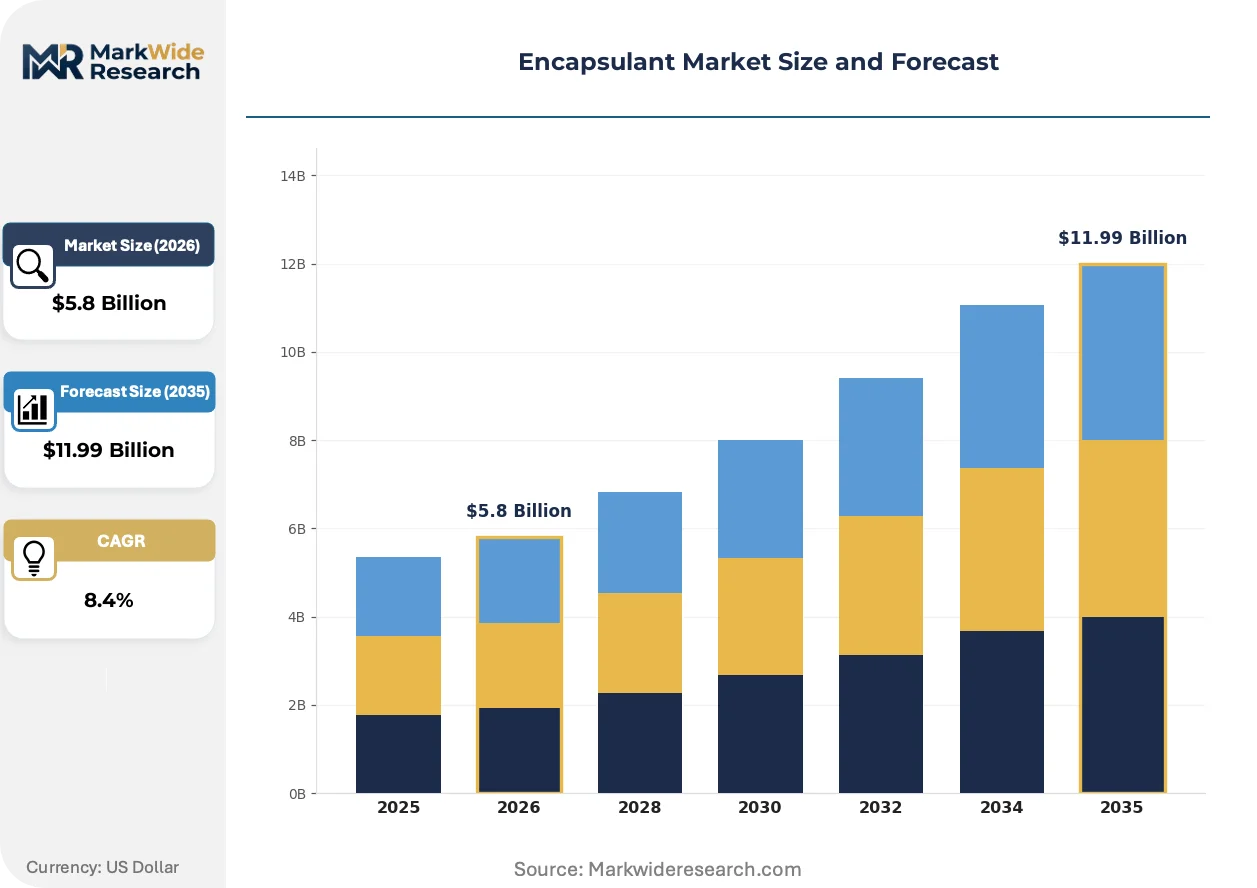
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Silicone, Epoxy, Polyurethane Application: Solar Cells, LEDs, Electronics, Medical Devices End User: Manufacturers, Contractors, Distributors, OEMs Technology: Thermal, Optical, Chemical, Electrical |
| Companies Covered | Dow, Shin-Etsu Chemical Co., Ltd., Sumitomo Bakelite Co., Ltd., 3M, Henkel, BASF, Parker Hannifin Corp, H.B. Fuller, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulant Market Shifts & Advancements
Automation of dispensing and curing processes is compressing unit economics while regulatory substance restrictions are fragmenting formulation portfolios across jurisdictions.
Precision dispensing robotics is automating encapsulant application in electronics miniaturization workflows. High-mix, low-volume LED and semiconductor packagers in South Korea and Taiwan are deploying closed-loop viscosity control systems. This automation is compressing labor cost differentials between established and emerging manufacturing locations.
EPA volatile organic compound emission rules are tightening curing process controls for US-based encapsulant applicators. Formulators must now document capture efficiency for thermal and UV cure chemistries. Photovoltaic module assembly operations in Arizona and Texas are retrofitting abatement systems to maintain operating permits.
Direct procurement contracts between cell manufacturers and silicone monomer suppliers are displacing distributor intermediaries in high-volume segments. Long-term offtake agreements now specify thermal conductivity thresholds tied to cell efficiency roadmaps. This channel consolidation is most advanced in China where integrated module producers command procurement scale.
Encapsulant Market Segmentation
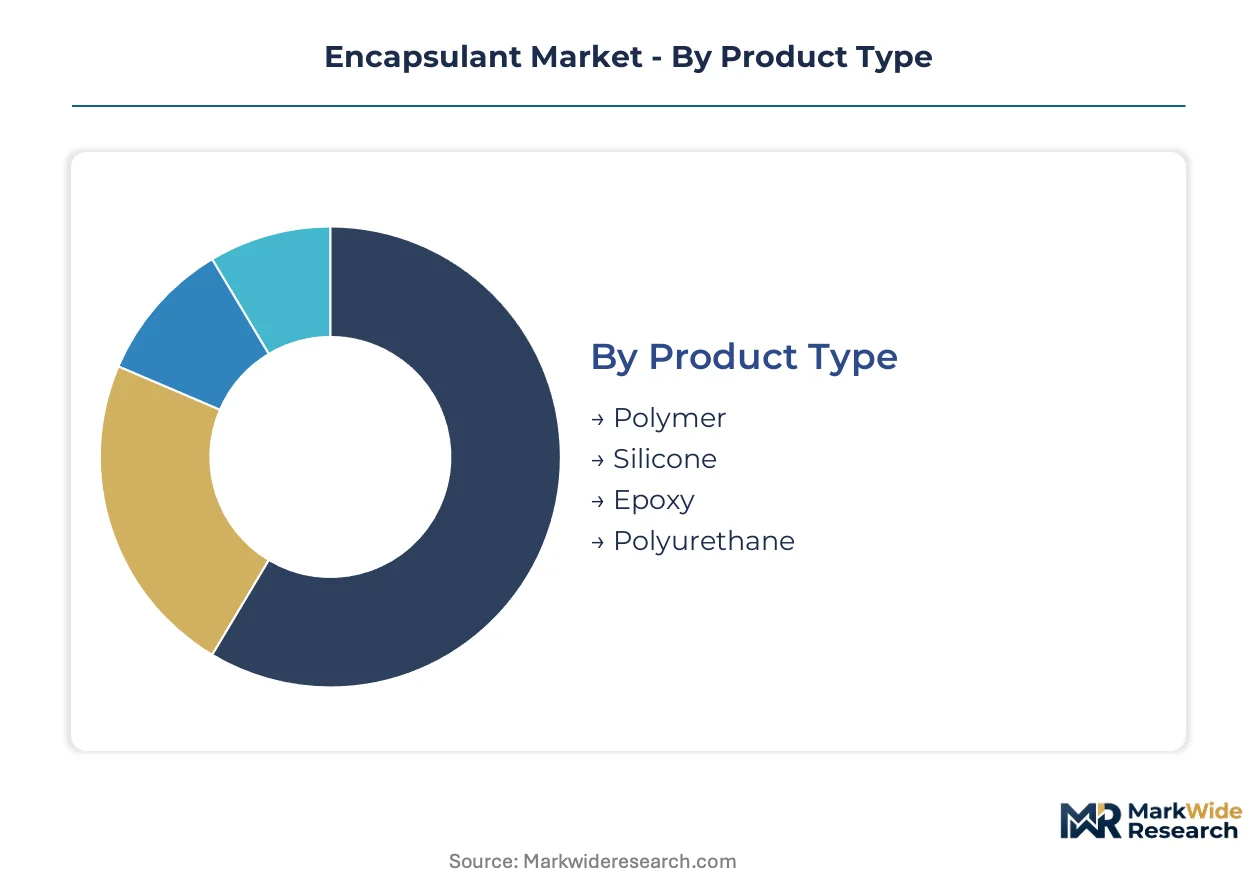
Encapsulant formulation varies sharply across protection requirements, from thermal cycling resilience in photovoltaic modules to biocompatibility in implantable devices. Segmentation reveals where specification premiums concentrate versus where commodity substitution threatens margins.
Product Type:
Standardization dominates commodity polymer grades while silicone systems require extensive customization to meet cell manufacturer thermal conductivity roadmaps.
- Silicone:Formulated from polydimethylsiloxane with viscosity between 500 and 5000 cPs and dielectric strength exceeding 15 kV/mm. Jiangsu and Zhejiang province module producers consume captive volumes that dwarf other regional demand. REACH and RoHS compliance deadlines are forcing reformulation toward low-VOC curing systems.
- Epoxy:Rigid thermoset systems with excellent adhesion to metal substrates and chemical resistance. Automotive electronics protection in Germany and Japan anchors demand where thermal stability requirements moderate against cost pressure. Epoxy substitution is capturing select applications from silicone where operating temperatures permit.
- Polyurethane:Flexible, abrasion-resistant formulations for dynamic stress environments. Medical device manufacturers specify medical-grade versions for catheter and probe encapsulation.
- Polymer:Lower-cost commodity encapsulants for general electronics protection where performance specifications are less stringent. Consumer electronics assembly in Vietnam and Mexico drives volume procurement.
Leading the category by volume: Silicone. Growing fastest: Epoxy.
Application:
Application segmentation tracks directly to certification burden and thermal cycling intensity, with photovoltaic modules demanding the most rigorous qualification protocols.
- Solar Cells:Bifacial and heterojunction architectures require advanced barrier properties against moisture ingress and thermal shock. IEC 61215 reliability testing standards mandate 12-18 month validation cycles that delay new encapsulant commercialization. India's PLI scheme subsidies are creating new demand centers outside established Chinese supply chains.
- Electronics:Miniaturization trends in South Korea and Taiwan drive precision dispensing of high-purity formulations. Closed-loop viscosity control systems automate application for high-mix, low-volume semiconductor packagers.
- LEDs:Optical clarity and thermal management requirements for high-brightness applications. Street lighting and automotive headlamp modules specify silicone encapsulants for outdoor durability.
- Medical Devices:Biocompatibility and sterilization resistance requirements per ISO 10993 and FDA 21 CFR 175.300. Implantable device manufacturers demand full material transparency and extractables testing.
Photovoltaic applications command the steepest expansion trajectory. Electronics applications anchor margin pools.
End User:
Procurement scale and technical integration depth separate direct manufacturers from intermediary channels.
- Manufacturers:Integrated module and electronics producers with in-house formulation expertise and direct silicone monomer offtake agreements. Long-term contracts now specify thermal conductivity thresholds tied to cell efficiency roadmaps.
- OEMs:Original equipment manufacturers with design authority over encapsulant specification. Automotive and medical device OEMs in Germany and the United States drive qualification requirements.
- Contractors:Installation and field service providers purchasing encapsulants for repair and retrofit applications. Distributed solar installers in India and Brazil represent emerging volume.
- Distributors:Channel intermediaries facing displacement as direct procurement concentrates among high-volume consumers. Inventory holding and technical service remain viable in fragmented regional markets.
Direct manufacturer procurement dominates volume. OEM specification authority determines formulation priorities.
Technology:
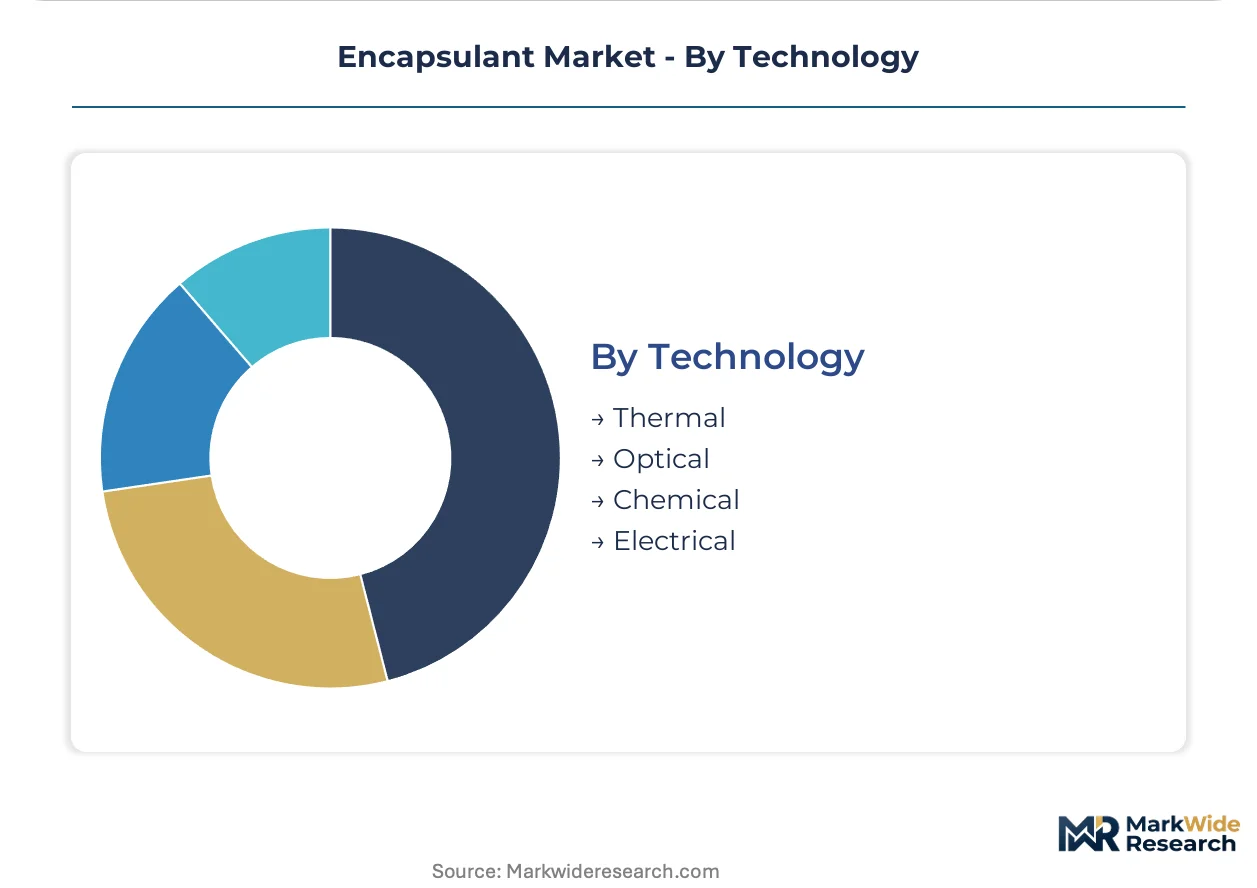
Technology segmentation maps to the physical protection mechanism and corresponding test methodology.
- Thermal:Heat dissipation and thermal cycling resistance specifications measured by thermal conductivity and coefficient of thermal expansion. Photovoltaic module manufacturers drive the most demanding requirements.
- Optical:Light transmission, refractive index matching, and yellowing resistance for LED and display applications. South Korean display panel producers specify optical-grade silicones.
- Electrical:Dielectric strength, volume resistivity, and tracking resistance for high-voltage electronics. Electric vehicle power electronics in China and Germany demand advanced grades.
- Chemical:Solvent resistance, outgassing control, and environmental stability. Aerospace and satellite applications in the United States specify low-outgassing formulations per ASTM E595.
Thermal technology leads by revenue. Electrical protection specifications are climbing fastest with electrification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quartz refining clusters in Japan and high-purity silicon metal production in China anchor the encapsulant supply chain geography. These feedstock localities determine where formulation expertise concentrates and where procurement power accumulates.
China
Jiangsu and Zhejiang provinces host concentrated solar module manufacturing that consumes captive silicone encapsulant volumes. MEE filing requirements for chemical substance documentation compel reformulation transparency. Domestic producers leverage direct monomer offtake agreements to bypass distributor channels entirely.
United States
Arizona and Texas photovoltaic assembly operations drive demand for low-outgassing silicone grades. EPA volatile organic compound rules tighten curing process controls and abatement system requirements. Southwestern manufacturing clusters retrofit thermal and UV capture equipment to maintain operating permits.
Germany
Automotive electronics OEMs in Bavaria and Baden-Württemberg anchor epoxy and polyurethane demand for powertrain protection. REACH substance restrictions and RoHS compliance deadlines force low-VOC silicone system development. Stuttgart and Munich industrial corridors qualify materials against IEC reliability standards for module certification.
Japan
High-purity silicone material production concentrates among captive quartz refining operations. METI industrial standards govern electronics-grade formulation specifications. Nagoya and Osaka manufacturing basins supply specialty grades for heterojunction cell barrier requirements.
India
Gujarat and Rajasthan solar installation growth creates new encapsulant demand outside Chinese supply chains. PLI scheme subsidies for domestic module production attract formulation partnerships. Domestic manufacturing buildout in these western states requires IEC 61215 certification alignment.
Encapsulant Market Competitive Landscape
Global majors compete with regional champions across silicone monomer supply and formulation specialization. The vendor base separates into integrated chemical conglomerates with captive feedstock, mid-scale specialists with photovoltaic certification depth, and regional distributors facing channel compression. Three archetypes dominate: quartz-integrated silicone producers, epoxy-urethane hybrid formulators, and electronics-grade precision compounders. Capacity expansion and direct procurement contracting represent the primary competitive vectors as module manufacturers consolidate supplier relationships.
Among integrated chemical producers, Dow and Shin-Etsu Chemical Co., Ltd. exemplify the quartz-captive archetype with monomer network control. Henkel occupies a position within the diversified formulation tier, bridging epoxy and polyurethane systems across automotive electronics protection. These three entities represent distinct strategic postures: upstream integration, high-purity material specialization, and multi-chemistry portfolio breadth.
| Leading Market Players |
|---|
| Dow |
| Shin-Etsu Chemical Co., Ltd. |
| Sumitomo Bakelite Co., Ltd. |
| 3M |
| Henkel |
| BASF |
| Parker Hannifin Corp |
| H.B. Fuller |
| DuPont |
| Others |
Supply & Pricing Matrix
Metallurgical-grade silicon feedstock costs cascade through three distinct pricing tiers as quartz mining concentration in China and Japan shapes procurement power across module assembly operations. Long-term offtake agreements now embed thermal conductivity thresholds that tie raw material grades directly to cell efficiency roadmaps, compressing margin buffers for non-integrated formulators.
Pricing Analysis
Warranty bundling separates premium silicone grades from commodity alternatives, with IEC 61215 certification and 25-year performance guarantees commanding substantial premiums over uncertified formulations. Price differentiation rests on thermal conductivity specifications and REACH compliance documentation, with photovoltaic module manufacturers in Jiangsu and Zhejiang provinces showing lowest price sensitivity due to captive supply integration. Cost compression in standard-grade silicones intensifies as epoxy systems capture automotive electronics applications where thermal requirements moderate. Distributors and fragmented regional installers exhibit highest price sensitivity, driving spot-market volatility for non-contract volumes.
Supply Chain Analysis
Ocean freight rate volatility from Asia-Pacific ports to Arizona and Texas assembly operations amplifies landed cost uncertainty for US-based module producers. Supply concentrates in China, Japan, and Germany, with high-purity silicon metal production drawing from captive quartz refining in Japanese coastal prefectures and Chinese inland mining provinces. Raw material dependencies span metallurgical-grade silicon, specialty catalysts for low-VOC curing systems, and high-purity solvents for electronics-grade formulations. Single-source vulnerability concentrates in Japanese quartz refining capacity. Distribution runs through direct procurement contracts that displace distributor intermediaries in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where REACH substance restrictions and IEC 61215 certification requirements erect formidable barriers against non-compliant competitors, entrenching incumbents with established documentation infrastructure.
For Market Incumbents: Deepen backward integration into quartz refining or captive silicone monomer production to insulate margins from feedstock volatility. Prioritize certification investment in India's PLI scheme-aligned testing capabilities before domestic module manufacturing scales. Epoxy substitution in automotive electronics and formulation chemist retirement waves represent immediate threats requiring defensive capability retention.
For New Entrants and Emerging Players: Distributor partnerships in fragmented regional markets offer viable entry vectors where technical service and inventory holding retain value. India's Gujarat and Rajasthan solar corridors present the most penetrable geography outside Chinese supply chain dominance. Perovskite tandem cell development partnerships provide a formulation collaboration angle bypassing incumbent certification lock-in.
For Investors and Strategic Acquirers: IEC 61215 revision announcements are the leading indicator that certification-capable testing assets will command acquisition premiums. Long-term viability favors vertically integrated specialists with captive feedstock and in-house reliability testing infrastructure over pure formulation players. Monitor heterojunction cell diffusion rates as the demand inflection signal for high-purity silicone grade expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Refining | Captive silicon metal supply secures margin stability against Shin-Etsu and Chinese producer pricing power. |
| Long-term Supply Agreement with Module Producers | Direct procurement contracts with Jiangsu manufacturers displace distributor channels and lock volume commitments. |
| Green Manufacturing Transition | Low-VOC curing system investment aligns with REACH deadlines and EPA emission rules in core markets. |
| Joint Venture with Cell Developers | Perovskite tandem partnerships position formulators for emerging barrier specifications before standards crystallize. |
| Capacity Expansion in India | PLI scheme-aligned manufacturing in Gujarat captures subsidy-supported demand outside Chinese supply chains. |
Research Methodology
Independent corroboration across silicone monomer producers, photovoltaic module procurement leads, and specialty chemical distributors underwrites the qualitative findings in this analysis. Primary interviews with plant managers at encapsulant formulation facilities, technical R&D directors specifying thermal conductivity roadmaps, and procurement officers at integrated module manufacturers combined with secondary validation from customs trade data, SEC 10-K filings of listed chemical producers, and IEC certification registry records. Bottom-up volume estimates from application-level consumption patterns triangulate against top-down market sizing from regional production capacity assessments.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by chemistry type, application intensity, and regional regulatory cluster. The analytical framework models silicone, epoxy, polyurethane, and polymer grade tiers against solar cell, electronics, LED, and medical device end-use industries, with additional dimensioning by thermal, optical, electrical, and chemical protection technology. CAGRs derive from fitted growth curves applied to segment-level baseline estimates, incorporating heterojunction cell diffusion rates and India's PLI scheme implementation pace as industry-specific forecast inputs.
Caveats apply where metallurgical-grade silicon price volatility, IEC 61215 testing protocol revisions, or perovskite commercialization timelines could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and cell architecture transition speeds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Rhenium Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Semiconductor Fabrication Material Market