
 Medical Laser Marking Machine Market | 2026-2036
Medical Laser Marking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Laser Marking Machine Market Intelligence
The gap between premium fiber-laser systems and commodity CO2 configurations is repositioning how OEMs evaluate total cost of ownership against throughput requirements. Trumpf leverages its German manufacturing base to sustain dominance in high-precision medical applications. Han's Laser anchors Asian supply through vertical integration of laser source production. Laserax differentiates by specializing in traceability solutions for orthopedic implants.
A medical laser marking machine directs a focused beam to alter surface properties of stainless steel, titanium, or polymer substrates, producing permanent alphanumeric codes, 2D matrices, or logos without material removal exceeding 0.001 inches. Fiber laser systems lead installed base due to beam quality suited for annealing medical-grade metals, while UV laser adoption accelerates in pharmaceutical packaging where thermal damage must be eliminated. Engraving technology occupies the mature core of revenue, though scanning configurations capture expanding margin pools in high-mix, low-volume device manufacturing.
FDA's UDI rule and the EU MDR's enhanced traceability mandates shape product specifications across all export-oriented suppliers. ISO 13485 quality system requirements and CE marking under the EU Machinery Directive filter market access for non-compliant equipment builders. Stakeholders must monitor how FDA's evolving guidance on reprocessed device marking interacts with state-level hospital procurement consolidation to determine whether captive marking operations or outsourced service models prevail.
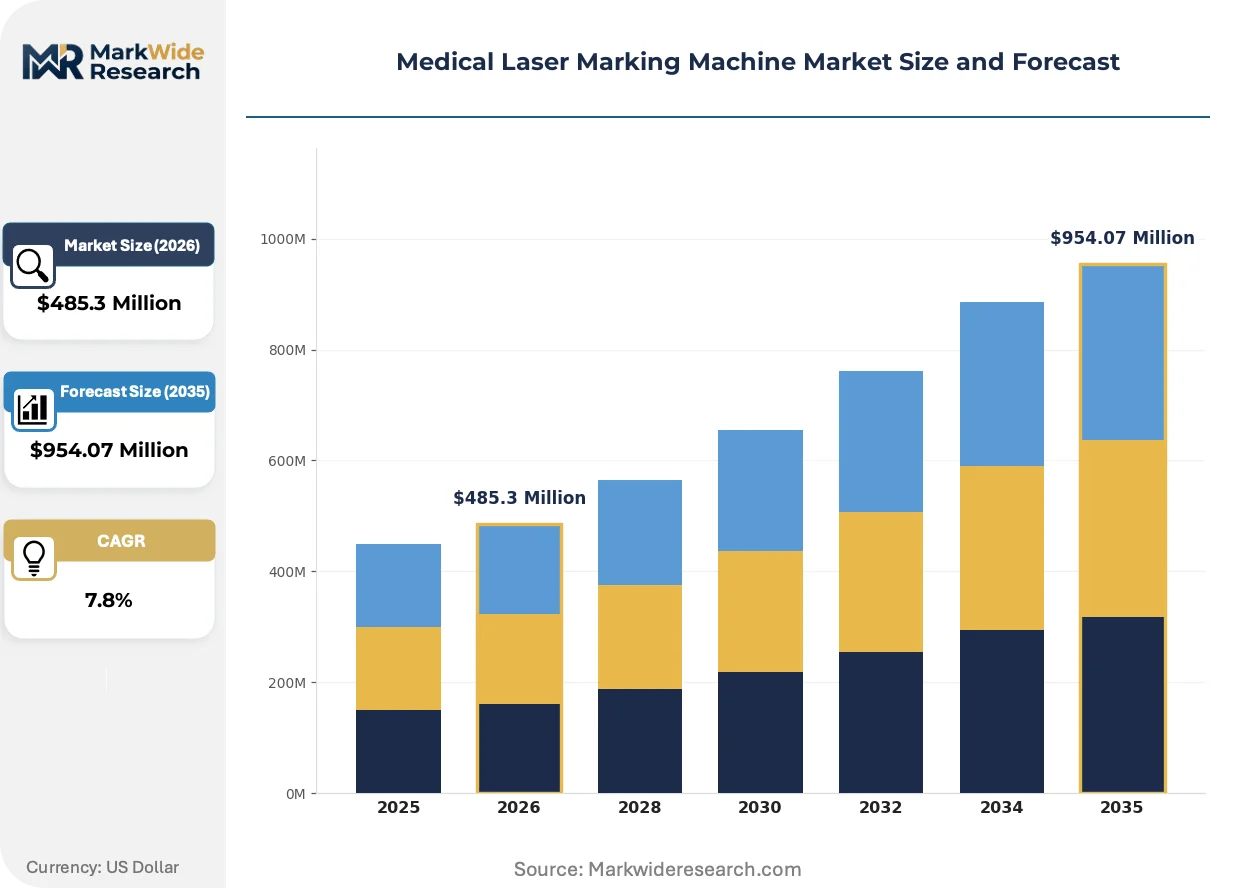
Market Dynamics
FDA's UDI mandate and the EU MDR's traceability requirements are compressing equipment replacement cycles while forcing OEMs to prioritize fiber-laser precision over legacy CO2 systems for surgical instrument marking.
Growth Catalysts
- FDA UDI Compliance Deadlines:Medical device manufacturers face phased enforcement of unique device identification rules, requiring permanent laser-marked codes on Class II and III instruments. This mandates capital deployment into annealing-capable fiber systems.
- German Precision Engineering Clusters:Concentrated supplier networks around Stuttgart and Munich enable rapid prototyping of medical-grade marking configurations, shortening validation timelines for orthopedic implant producers.
- Annealing Process Maturation:Fiber laser annealing on 316L stainless steel and titanium-6Al-4V now achieves corrosion-resistant black marks without material removal, satisfying biocompatibility requirements for reusable surgical tools.
Market Restraints
- Supply Concentration in German Laser Sources:Premium fiber resonator production concentrates among Trumpf, IPG Photonics, and nLIGHT facilities, creating vulnerability to export control disruptions and extended lead times for Asian OEMs.
- UV Laser Input Cost Volatility:Nonlinear crystal materials for 355nm UV systems—particularly LBO and BBO—face price instability due to limited mining operations in specific jurisdictions, compressing margins for pharmaceutical packaging integrators.
- Substitution by Electrochemical Etching:Low-throughput device manufacturers in cost-sensitive segments retain electrochemical marking for non-implant instruments, limiting addressable market expansion for laser system vendors.
Strategic Opportunities
- India Medical Device Manufacturing:PLI scheme incentives for domestic stent and orthopedic implant production create demand for ISO 13485-compliant marking systems as CDSCO tightens traceability enforcement.
- Convergence of Vision and Laser Control:Deep learning-based part recognition integrated with galvo scanning enables autonomous marking of irregular implant geometries, reducing fixture engineering costs for dental abutment producers.
- Reprocessed Device Marking Requirements:FDA's evolving guidance on third-party reprocessor accountability creates aftermarket demand for secondary marking stations in hospital sterilization departments across the United States.
Industry Challenges
- Laser Safety Officer Certification Bottlenecks:IEC 60825-1 compliance requires trained personnel for Class 4 fiber systems, but accredited training programs in emerging manufacturing hubs face 6-12 month enrollment backlogs.
- Legacy MES Integration Complexity:Medical device ERP systems from SAP and Oracle require custom OPC-UA middleware to synchronize laser marking data with electronic device history records, extending deployment timelines.
- CE Marking Technical File Assembly:EU Machinery Directive conformity assessment demands extensive risk analysis documentation for laser interlocks and fume extraction, burdening smaller system integrators without dedicated regulatory staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Laser Marking Machine Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $954.07 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, CO2 Laser, UV Laser, Green Laser Technology: Direct Marking, Engraving, Scanning, Printing Application: Medical Devices, Surgical Instruments, Pharmaceuticals, Implants End User: Hospitals, Clinics, Laboratories, OEMs |
| Companies Covered | Han's Laser, Laserax, Trumpf, TYKMA Electrox, OPMT, Telesis Technologies, Rofin, HeatSign, FOBA (ALLTEC GmbH), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Laser Marking Machine Market Strategic Shifts & Innovations
Traceability mandates are compressing validation timelines while forcing convergence between marking hardware and factory software layers. Equipment vendors now compete on integration depth rather than beam specifications alone.
Picosecond fiber lasers are unifying marking and surface texturing functions within single platforms. Orthopedic implant manufacturers in Switzerland and the United States adopt these systems to create antimicrobial surface topologies alongside UDI codes, eliminating separate processing steps. This unification reduces capital footprint and cleanroom logistics complexity for high-mix implant producers.
EU MDR's enhanced post-market surveillance requirements are mandating machine-readable data matrices with 20-year readability guarantees. Device manufacturers now specify laser systems with redundant galvo encoders and real-time power monitoring to satisfy notified body audits. German and Irish implant producers lead this specification tightening, forcing Asian equipment vendors to upgrade feedback control architectures.
Hospital procurement consolidation across the United States is shifting vendor relationships from equipment sales to managed marking services. IDN-owned central sterilization facilities now demand per-part pricing with guaranteed uptime, displacing capital purchase models. This servitization concentrates in the Southeast and Midwest, where health system mergers have created multi-hospital device processing hubs.
Medical Laser Marking Machine Market Segmentation
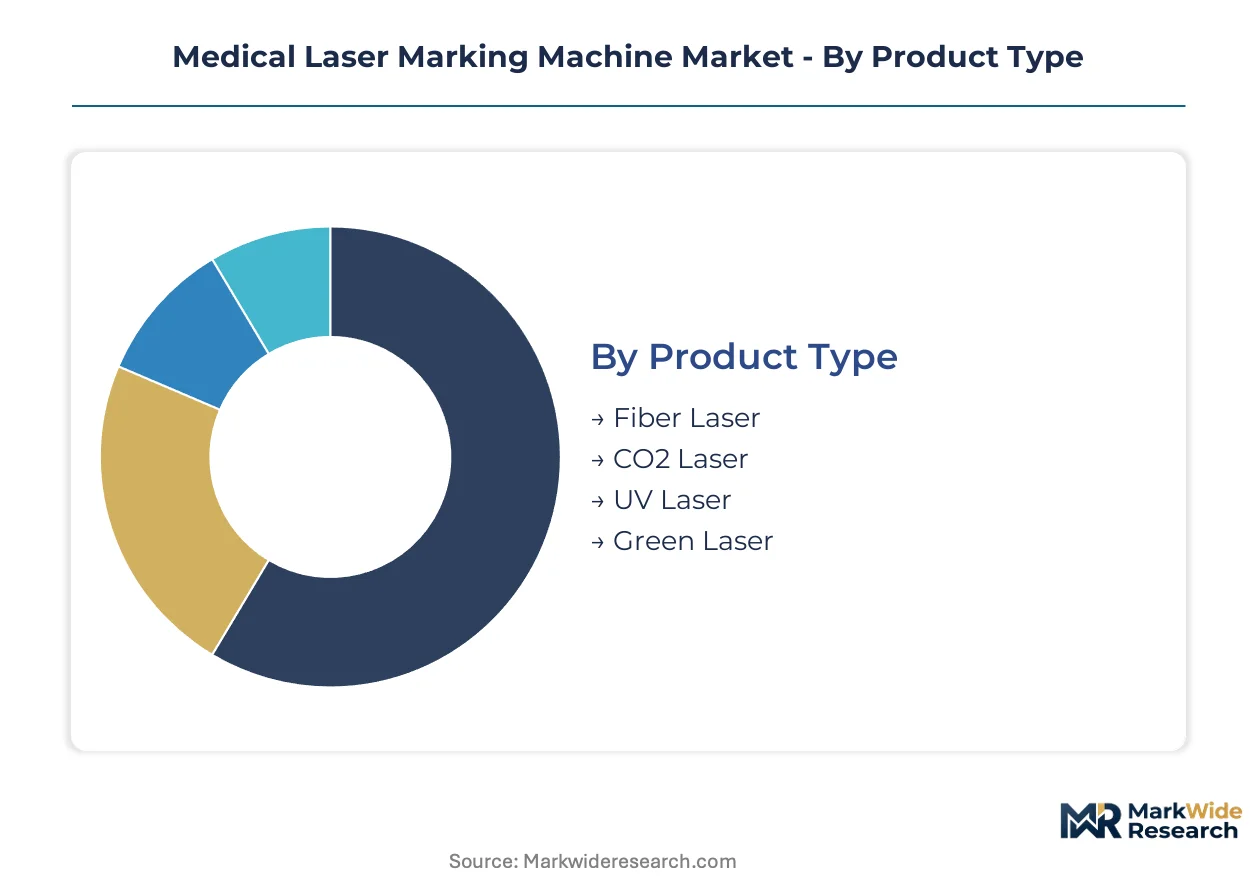
Equipment selection in medical laser marking hinges on substrate compatibility, regulatory compliance depth, and integration complexity with existing production lines. Buyers evaluate total cost of ownership across validation timelines, maintenance contracts, and software upgrade pathways rather than capital expenditure alone.
Product Type:
Capital allocation decisions pivot on beam wavelength precision against material reactivity requirements.
- Fiber Laser:Ytterbium-doped fiber resonators emit at 1064nm with exceptional beam quality for annealing 316L stainless steel and titanium alloys. German orthopedic implant manufacturers specify these systems for corrosion-resistant black marks that satisfy biocompatibility protocols for reusable surgical instruments.
- UV Laser:Third-harmonic generation produces 355nm output with minimal heat-affected zones, enabling marking on pharmaceutical blister packs and polymer catheter shafts. Swiss pharmaceutical packaging integrators drive specification tightening as EU MDR traceability mandates extend to primary containers.
- CO2 Laser:10.6μm wavelength systems target non-metallic substrates including glass ampoules and polymer surgical drapes; cost-sensitive device manufacturers retain these for low-throughput electrosurgical pencil marking.
- Green Laser:532nm frequency-doubled Nd:YAG sources penetrate reflective precious metals in dental restoration components; limited installed base concentrates in Italian and Japanese dental manufacturing clusters.
Fiber laser configurations lead on scale; UV laser systems lead on momentum.
Technology:
Process selection determines throughput ceiling and mark permanence under sterilization cycling.
- Direct Marking:Galvo-steered beams execute alphanumeric codes and Data Matrix symbols without consumables; FDA UDI compliance deadlines concentrate demand among Class III device OEMs requiring permanent identification through thousands of autoclave cycles.
- Scanning:High-speed polygon or galvanometer scanning enables batch processing of irregular implant geometries; vision-integrated configurations reduce fixture engineering costs for dental abutment producers in the United States.
- Engraving:Material removal exceeding surface alteration creates tactile depth for instrument differentiation; mature demand concentrates in legacy surgical tool refurbishment operations.
- Printing:Laser-induced forward transfer deposits ceramic or metal inks for color coding on polymer substrates; niche adoption in French and German in-vitro diagnostic consumable manufacturing.
Direct marking dominates current installed capacity; scanning configurations are expanding most quickly.
Application:
End-use regulatory burden shapes equipment specification stringency and validation documentation requirements.
- Medical Devices:Electrosurgical generators, infusion pumps, and diagnostic equipment require durable marks through cleaning chemistries and thermal sterilization; US and EU notified body audits drive redundant galvo encoder specifications.
- Surgical Instruments:Reusable graspers, retractors, and scissors demand annealed marks without material removal that could harbor biological contamination; German precision engineering clusters anchor supply for orthopedic and cardiovascular instrument sets.
- Pharmaceuticals:Primary packaging and secondary labeling require machine-readable codes with 20-year readability guarantees; nonlinear crystal cost volatility compresses margins for 355nm system integrators.
- Implants:Hip stems, spinal cages, and cranial plates combine UDI marking with antimicrobial surface texturing; picosecond fiber platforms unify both functions for Swiss and US manufacturers.
Surgical instruments command the largest equipment footprint; implant marking shows the steepest expansion trajectory.
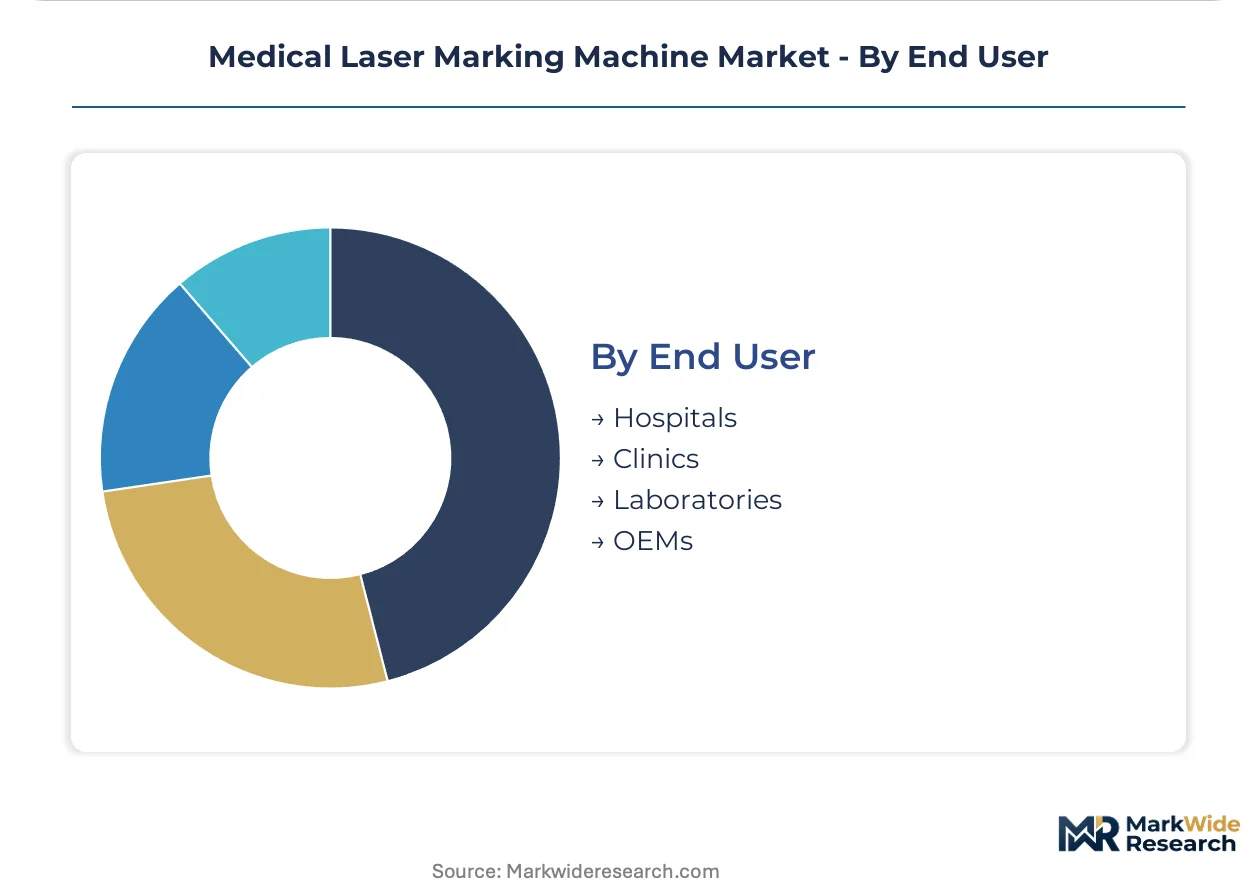
End User:
Procurement authority and technical staffing determine service model preference versus capital acquisition.
- OEMs:Medical device manufacturers integrate marking stations within validated production lines; ISO 13485 quality system requirements filter supplier qualification with extensive risk analysis documentation.
- Hospitals:Integrated delivery network central sterilization facilities shift toward managed marking services with per-part pricing; Southeast and Midwest US health system mergers create multi-hospital processing hubs.
- Laboratories:In-vitro diagnostic and research consumable producers specify compact benchtop systems for low-volume prototype marking; CE marking technical file assembly burdens smaller integrators without dedicated regulatory staff.
- Clinics:Ambulatory surgical centers and specialty practices represent minimal direct equipment demand, instead relying on OEM-marked instruments or third-party reprocessor services.
OEMs dominate capital deployment; hospitals are shifting fastest toward servitization models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters command premium-tier fiber laser deployments, while Indian production-scale incentives accelerate capacity buildouts for export-oriented device manufacturers.
United States
FDA UDI enforcement deadlines and hospital procurement consolidation drive fiber laser adoption for surgical instrument traceability. The agency's phased implementation for Class II and III devices mandates permanent annealed marks. Southeast and Midwest integrated delivery networks now operate multi-hospital central sterilization facilities with captive marking stations.
Germany
Stuttgart and Munich engineering clusters anchor European supply for orthopedic implant marking systems. EU MDR traceability requirements and CE marking under the Machinery Directive filter market access for non-compliant equipment builders. Trumpf leverages its domestic manufacturing base to sustain dominance in high-precision medical applications.
China
Domestic medical device manufacturing expansion and NMPA regulatory tightening create demand for ISO 13485-compliant marking platforms. Han's Laser anchors Asian supply through in-house production of laser sources. Yangtze River Delta precision manufacturing hubs concentrate system integration capacity for export markets.
Switzerland
Orthopedic implant producers lead specification tightening for 20-year readability guarantees on machine-readable data matrices. Swissmedic post-market surveillance requirements mandate redundant galvo encoders and real-time power monitoring. Basel and Zurich medical technology clusters drive adoption of picosecond fiber platforms unifying marking with antimicrobial surface texturing.
India
PLI scheme incentives for domestic stent and orthopedic implant production accelerate capital deployment into compliant marking infrastructure. CDSCO traceability enforcement tightens alongside state-level medical device manufacturing zones. Maharashtra and Gujarat industrial corridors concentrate demand for validated fiber laser systems serving export markets.
Medical Laser Marking Machine Market Key Industry Players
Top-tier vendors anchor premium fiber-laser precision, while mid-scale fabricators compete on throughput economics for pharmaceutical packaging. The vendor base stratifies across German engineering houses, Chinese integrated manufacturers, and North American traceability specialists. Three archetypes dominate: precision-engineering incumbents with captive resonator production, vertically integrated Asian suppliers controlling laser source manufacturing, and application-focused specialists bundling vision systems with marking hardware. Competitive moves concentrate on M&A for software integration capabilities and capacity expansion in Indian medical device manufacturing zones.
Within the precision-engineering tier, Trumpf exemplifies German manufacturing dominance in high-reliability medical applications. Among Asian-integrated suppliers, Han's Laser occupies a position representing upstream control over resonator production. Specializing in orthopedic implant traceability, Laserax sits within the application-focused archetype bundling vision integration with marking platforms.
| Leading Market Players |
|---|
| Han's Laser |
| Laserax |
| Trumpf |
| TYKMA Electrox |
| OPMT |
| Telesis Technologies |
| Rofin |
| HeatSign |
| FOBA (ALLTEC GmbH) |
| Others |
Cost & Logistics Intelligence
Precision optics specialists concentrated in Stuttgart and Munich anchor labor-cost differentials that widen spreads between premium fiber-laser configurations and economy-grade CO2 alternatives. German engineering wages compress margins for mid-tier system integrators while Asian manufacturing clusters exploit cost arbitrage in resonator assembly.
Pricing Analysis
The bundled-versus-unbundled service split separates capital-equipment vendors from managed-marking providers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in pharmaceutical packaging tiers intensifies because nonlinear crystal volatility for UV systems squeezes integrator margins. OEMs in surgical instrument manufacturing show least price sensitivity due to UDI compliance mandates; contract sterilization services exhibit highest sensitivity as IDNs consolidate procurement.
Supply Chain Analysis
Ytterbium-doped fiber resonator supply rests on German, American, and Chinese specialty laser source producers. Critical inputs encompass rare-earth doping fibers, precision galvo scanners, and nonlinear crystals for harmonic generation. Single-source vulnerability concentrates in LBO and BBO crystal mining jurisdictions. Distribution runs through direct OEM sales channels for validated production lines and regional system integrators for aftermarket service deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-layer bundling as hardware commoditization pressures force differentiation toward integration depth. Premium-tier shifts toward picosecond platforms unifying marking with surface texturing sustain pricing power.
For Market Incumbents: Cement dominance in high-reliability medical applications through captive resonator production and ISO 13485 certification depth. Electrochemical etching substitution in cost-sensitive segments threatens volume-tier positioning; defend through backward integration into laser source manufacturing and capacity expansion in Indian medical device zones.
For New Entrants and Emerging Players: Vision-guided autonomous marking systems offer a technology-first wedge into dental abutment and orthopedic implant niches. White-space targets include CDSCO-traceability-compliant systems for Maharashtra manufacturing corridors and per-part managed services for Southeast US hospital sterilization hubs. Go-to-market angle: bundle deep-learning part recognition with galvo scanning to reduce fixture engineering costs.
For Investors and Strategic Acquirers: Industrial automation conglomerates represent the most active acquirer category in this space. Long-term viability hinges on software integration capabilities rather than beam specification differentiation. Acquisition target archetype: application-focused specialists bundling vision systems with marking hardware. Watch FDA guidance evolution on reprocessed device accountability as inflection indicator for aftermarket service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Integration Acquisition | Vision system bundling with marking platforms displaces pure-hardware competition for orthopedic implant producers. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives for stent production create validated-system demand as CDSCO tightens traceability enforcement. |
| Picosecond Platform Development | Antimicrobial surface texturing unification with UDI marking eliminates separate processing for Swiss implant manufacturers. |
| Managed Service Model Launch | Per-part pricing with guaranteed uptime captures IDN central sterilization consolidation across Midwest health systems. |
| Laser Safety Training Program Investment | IEC 60825-1 certification bottlenecks in emerging hubs create six-month enrollment backlogs that constrain deployment timelines. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each combining structured interviews with laser system OEMs, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Secondary validation draws from FDA UDI guidance documents, EU MDR technical file requirements, CDSCO traceability circulars, and SEC filings of listed precision equipment manufacturers. Bottom-up equipment shipment analysis triangulates against top-down medical device production forecasts.
Rate-of-change decomposition separates volume effects from mix-shift and pricing components across the analysis window. Segmentation dimensions modeled encompass laser source type, marking technology, application regulatory burden, and end-user procurement authority. CAGRs derive from installed base evolution and replacement cycle compression under traceability mandates. Industry-specific forecast inputs include FDA phased enforcement timelines and EU notified body audit intensity.
The model holds under stable regulatory enforcement schedules; deviation in FDA reprocessed device guidance or export control expansion would shift replacement demand timing. A small set of named triggers warrants ongoing watch: nonlinear crystal supply disruptions, IEC training program expansion rates, and IDN servitization contract penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Washdown Scales Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Global Pneumatic Actuators Market