
 Active and Passive Electronic Components Market | 2026-2036
Active and Passive Electronic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Active and Passive Electronic Components Market Outlook
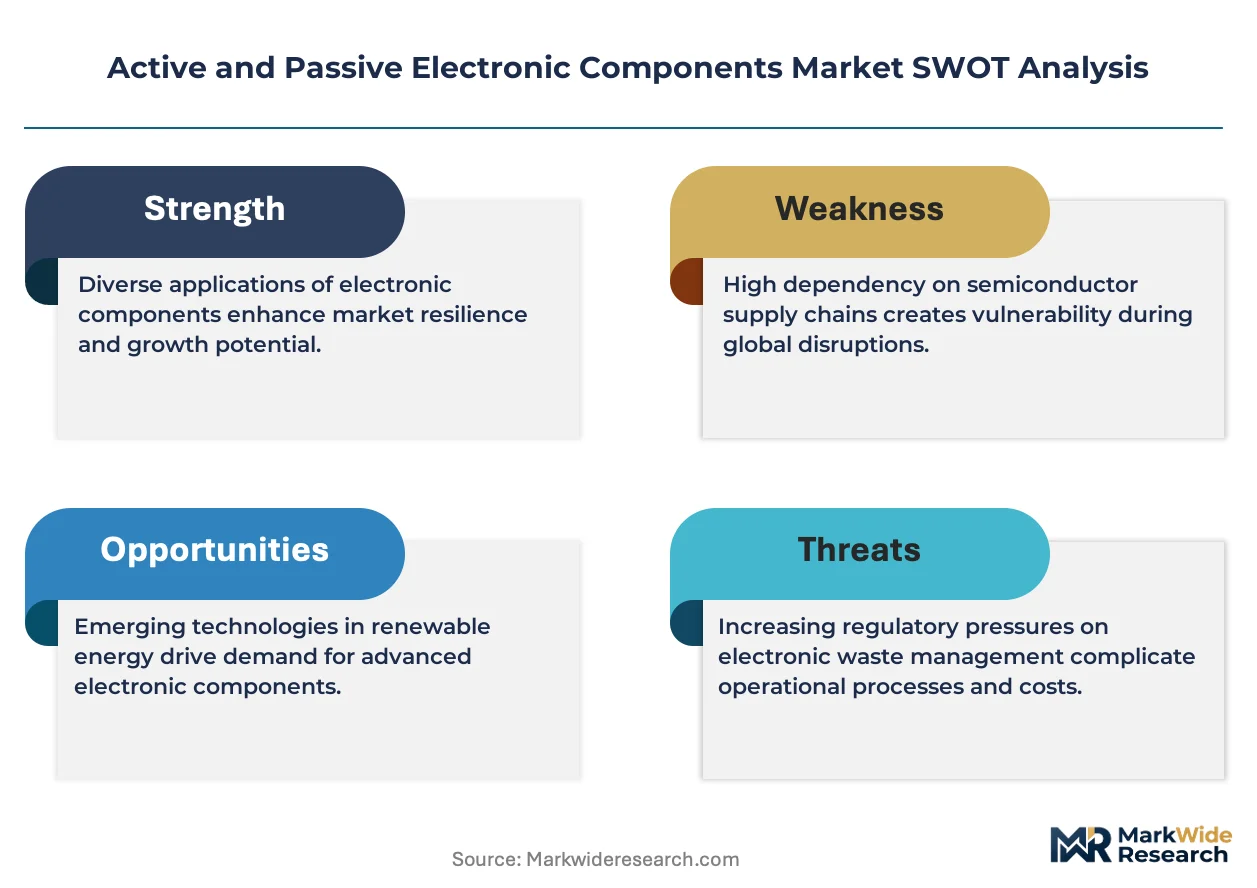
Multi-source procurement for ceramic capacitors and power MOSFETs is consolidating as tier-1 automotive suppliers reduce vendor counts to secure volume commitments. Samsung Electronics leverages captive semiconductor fabrication to anchor its position in memory-dependent active modules. Murata Manufacturing Co. Ltd. specializes in monolithic ceramic capacitors and dominates MLCC supply for high-frequency RF applications. Infineon Technologies AG controls silicon carbide device architectures that differentiate its power semiconductor portfolio.
Active and passive electronic components encompass energy-storing, filtering, switching, and amplifying elements constructed from dielectric ceramics, silicon substrates, metal oxides, and conductive polymers, typically operating across frequency ranges from DC to millimeter-wave bands to manage electrical signals in electronic systems. Capacitors and inductors within the component type category represent mature margin pools where supply constraints on palladium and nickel electrodes periodically disrupt pricing stability. RF and mixed-signal technologies are capturing expanded design wins as 5G base stations and automotive radar modules multiply filter and oscillator counts per unit. Automotive electronics applications command the fastest-growing demand segment as 48-volt mild-hybrid architectures and battery management systems multiply passive component counts per vehicle platform.
FCC equipment authorization rules in the United States, REACH substance restrictions administered by ECHA in Europe, and China's GB standards enforced by SAMR collectively shape material composition, recycling obligations, and electromagnetic compatibility thresholds for components sold across major economies. RoHS and CE marking requirements in Europe restrict hazardous substances in solder joints and substrate coatings, compelling suppliers to reformulate plating chemistries and dielectric formulations. Stakeholders must monitor how tightening conflict mineral tracing rules and export control expansions on gallium and germanium reshape sourcing strategies for substrate and dopant materials.
Market Dynamics
Automotive electrification is compressing design cycles for power-dense passive components as 48-volt architectures and silicon carbide inverters multiply filter and capacitor counts per vehicle platform.
Growth Catalysts
- China's GB energy-efficiency standards:SAMR enforcement of dual carbon targets accelerates procurement of low-loss inductors and advanced ceramic capacitors across industrial motor drives.
- 5G base station deployment:Millimeter-wave spectrum allocations multiply RF filter and oscillator counts per installation, concentrating demand in East Asian manufacturing clusters.
- Electric powertrain expansion:Battery management systems and onboard chargers require high-reliability MLCCs and film capacitors with extended temperature ratings.
Market Restraints
- Palladium electrode volatility:Precious metal supply disruptions from Russian and South African mining operations periodically destabilize multilayer ceramic capacitor pricing.
- Silicon carbide substrate scarcity:Wolfspeed and II-VI captive production limits external wafer availability for fabless power semiconductor designers.
- REACH substance restrictions:ECHA enforcement of SVHC candidate list expansions forces reformulation of dielectric coatings and solder joint chemistries.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for semiconductor and component manufacturing attract greenfield fab investments away from concentrated East Asian supply.
- Automotive radar module proliferation:77-81 GHz frequency bands for adaptive cruise control create design wins for high-Q inductors and temperature-compensated capacitors.
- GaN-on-silicon convergence:Integration of gallium nitride epitaxy with standard CMOS foundry processes enables cost-competitive high-frequency power conversion.
Industry Challenges
- RF simulation talent scarcity:Electromagnetic field modeling for millimeter-wave component design outpaces university pipeline output in Japan, Taiwan, and South Korea.
- AEC-Q200 certification timelines:Extended qualification cycles for automotive-grade passive components delay revenue recognition by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active and Passive Electronic Components Market |
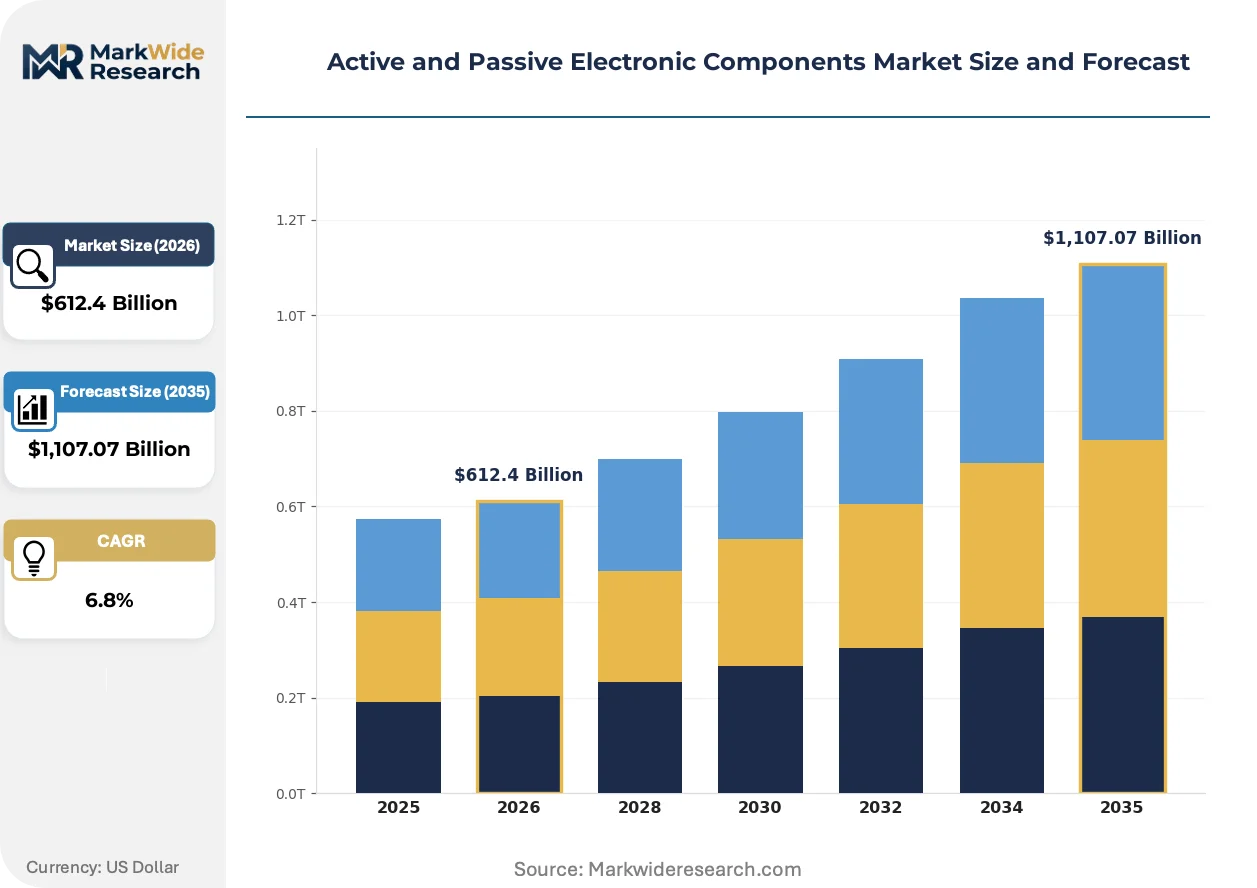
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Resistors, Capacitors, Inductors, Diodes Technology: Analog, Digital, Mixed-Signal, RF Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunication End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Electronics Manufacturers |
| Companies Covered | Samsung Electronics, Murata Manufacturing Co. Ltd., Infineon Technologies AG, Vishay Intertechnology Inc., TDK Corporation, NXP Semiconductors NV, Panasonic Corporation, Eaton Corporation, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active and Passive Electronic Components Market Strategic Shifts
Silicon carbide and gallium nitride power semiconductors are compressing the performance gap between passive component ratings and active switch capabilities, forcing concurrent upgrades across the component stack.
Silicon carbide MOSFETs enable switching frequencies above 100 kHz in traction inverters, reducing passive component volume requirements while demanding higher ripple-current ratings from DC-link capacitors. Tier-1 automotive suppliers in Germany and Japan are consolidating vendor lists to secure volume commitments for these co-designed active-passive subsystems. The technology is consolidating procurement power around integrated module suppliers who control both semiconductor fabrication and passive component specification.
REACH substance restrictions administered by ECHA now cover 233 SVHCs, compelling capacitor manufacturers to eliminate lead-bearing terminations and cadmium-plated housings from European-bound production lines. Industrial automation OEMs in Italy and the Netherlands face reformulation costs exceeding €2 million per product line. Passive component distributors are responding by segregating inventory streams between RoHS-compliant and legacy industrial-grade stock.
Multi-year supply agreements are displacing spot-market purchasing for ceramic capacitors and power inductors as automotive electronics manufacturers lock in palladium-nickel electrode supply. Tier-2 EMS providers in Mexico and Eastern Europe lose negotiating leverage against consolidated component distributors. The shift is most visible in North American electric vehicle supply chains, where battery pack manufacturers now contract directly with Murata and TDK for three-year volume commitments.
Active and Passive Electronic Components Market Segmentation
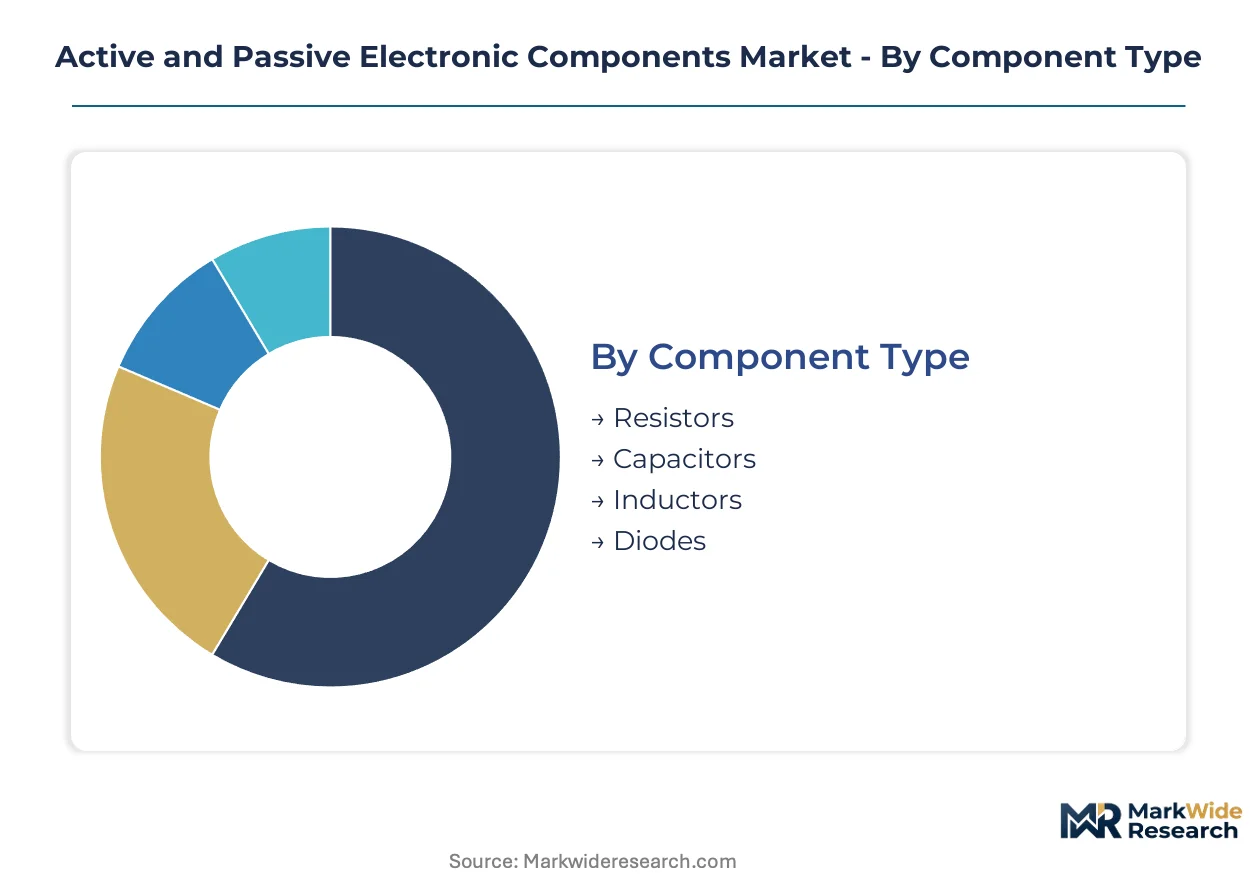
Component categorization in this market tracks the divergence between commodity passive elements and application-specific active modules. Segmentation by integration depth reveals which categories demand co-design with semiconductor foundries versus standalone procurement.
Component Type:
Integration depth varies sharply: capacitors and inductors embed directly into power modules, while discrete diodes often ship as standalone catalog items.
- Capacitors:Multilayer ceramic and film constructions dominate DC-link and filtering applications. Demand concentrates in German and Japanese automotive electronics as 48-volt mild-hybrid architectures multiply unit counts per inverter subsystem.
- Inductors:Ferrite-core and metal-composite winding technologies manage ripple current in switching converters. Procurement from South Korean battery pack manufacturers is accelerating for low-loss geometries that meet China's GB energy-efficiency standards.
- Resistors:Thick-film and thin-film precision elements provide current sensing and voltage division.
- Diodes:Silicon and silicon carbide rectifiers handle reverse-voltage protection and power steering.
Volume placements concentrate in Capacitors; the faster expansion belongs to Inductors.
Technology:
Cost tier separation distinguishes high-volume digital CMOS from premium-priced RF and mixed-signal processes requiring specialized foundry access.
- Mixed-Signal:Analog-digital integration enables precision sensor interfaces and power management ICs. German industrial automation OEMs in Bavaria and Baden-Württemberg are expanding procurement for motor drive controllers that combine ADC channels with PWM outputs.
- RF:Millimeter-wave transceivers and filter banks operate above 6 GHz for 5G infrastructure. Taiwan-based base station manufacturers are capturing design wins as FCC spectrum allocations in the United States drive filter count multiplication.
- Analog:Continuous signal processing for audio, power regulation, and linear amplification.
- Digital:Binary logic and memory-dependent processing for computational workloads.
Volume placements concentrate in Digital; the steepest expansion trajectory belongs to RF.
Application:
Customer type differentiation separates high-volume consumer procurement from long-cycle automotive qualification requirements.
- Automotive Electronics:Battery management systems and onboard chargers demand AEC-Q200 certified passives with extended temperature ratings. Tier-1 suppliers in Stuttgart and Nagoya are consolidating vendor lists to secure three-year volume commitments for MLCC and film capacitor supply.
- Telecommunication:5G base stations and optical transport equipment require high-frequency passive components. South Korean network equipment manufacturers are driving oscillator and filter demand as millimeter-wave spectrum deployment accelerates.
- Consumer Electronics:Smartphones, wearables, and computing devices prioritize miniaturization and cost optimization.
- Industrial Automation:Motor drives, robotics, and process control systems emphasize reliability and long service life.
Volume placements concentrate in Consumer Electronics; the fastest climb belongs to Automotive Electronics.
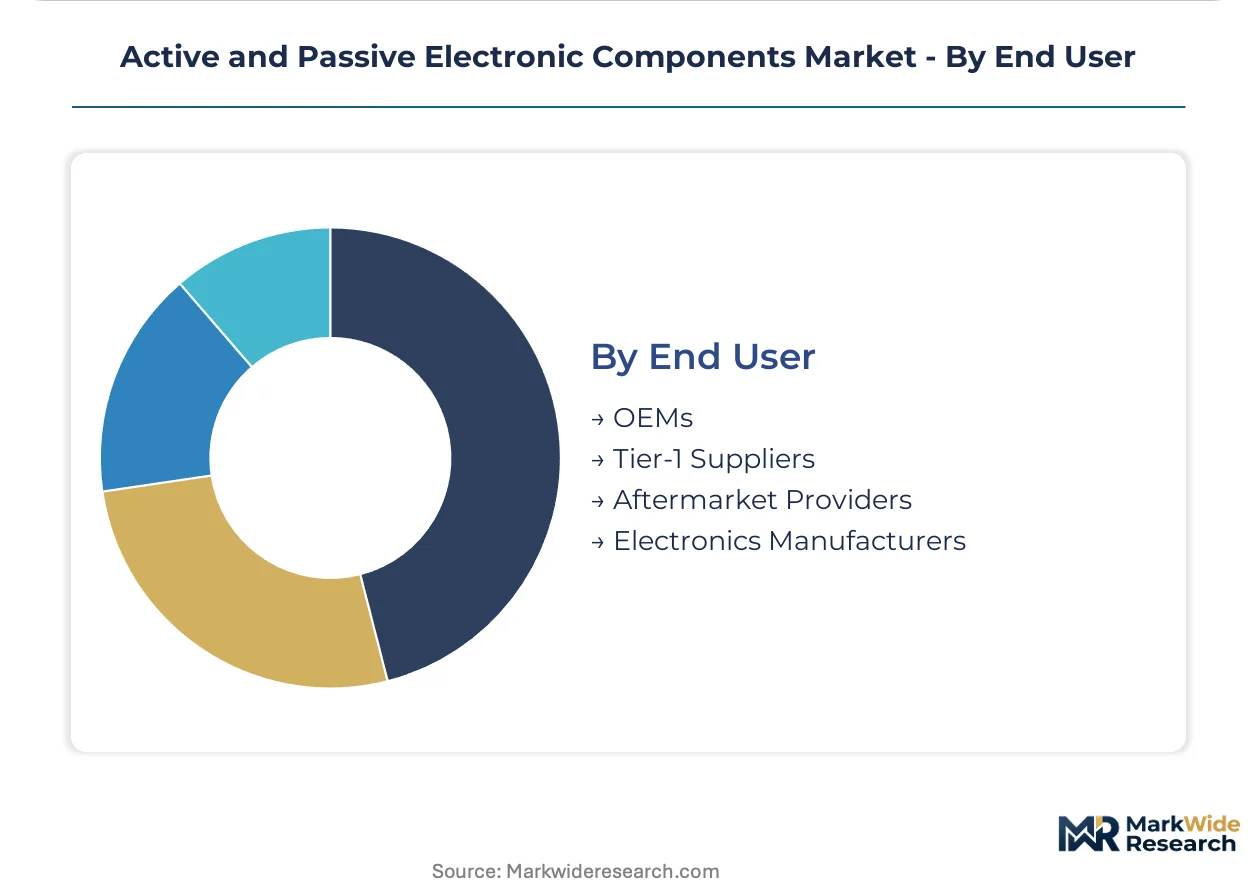
End User:
Supply concentration maps to procurement scale: OEMs and Tier-1 suppliers dominate high-volume negotiations, while aftermarket channels fragment across distributor networks.
- Tier-1 Suppliers:Continental, Bosch, and Denso-class integrators specify co-designed active-passive subsystems. These Stuttgart, Tokyo, and Seoul-based manufacturers are locking multi-year agreements directly with Murata and TDK to bypass distributor markup.
- OEMs:Apple, Samsung Electronics, and Dell-class brands control specification authority for consumer and enterprise electronics. Their Shenzhen, Cupertino, and Suwon procurement centers are consolidating ceramic capacitor sourcing to secure palladium-nickel electrode supply.
- Electronics Manufacturers:Foxconn, Jabil, and Flex-class EMS providers assemble to customer specification.
- Aftermarket Providers:Distributors and service channels address replacement demand and repair markets.
Volume placements concentrate in OEMs; the fastest share gain belongs to Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palladium and nickel mining operations in South Africa and Russia anchor raw material supply for multilayer ceramic capacitors, while East Asian manufacturing clusters in Taiwan, South Korea, and Japan concentrate component fabrication capacity.
China
Dual carbon goals and GB energy-efficiency standards enforced by SAMR are accelerating procurement of low-loss inductors and advanced ceramic capacitors across industrial motor drives. The Yangtze River Delta and Pearl River Delta clusters host dense concentrations of MLCC and power inductor fabrication facilities serving domestic EV battery pack manufacturers.
United States
FCC equipment authorization rules for 5G infrastructure and automotive radar modules are multiplying RF filter and oscillator counts per installation. Austin, Texas and Phoenix, Arizona semiconductor corridors are attracting power semiconductor packaging investments to support domestic electric vehicle supply chains.
Germany
REACH substance restrictions administered by ECHA are compelling reformulation of dielectric coatings and solder joint chemistries for European-bound production. Stuttgart and Munich-based Tier-1 automotive suppliers are consolidating vendor lists to secure three-year volume commitments for AEC-Q200 certified passives.
Japan
METI industrial policy and JIS standards are reinforcing domestic supply chain resilience for high-reliability passive components. Kyoto and Nagoya manufacturing clusters specialize in monolithic ceramic capacitors and ferrite-core inductors for automotive electronics and telecommunications equipment.
South Korea
MFDS-equivalent industrial standards and national semiconductor strategies are driving demand for high-frequency passive components in 5G base stations and memory modules. Suwon and Seoul Capital Area electronics manufacturers are expanding procurement of temperature-compensated capacitors for millimeter-wave applications.
Active and Passive Electronic Components Market Competitive Environment
Multi-year supply agreement consolidation dominates the current landscape as tier-1 automotive suppliers reduce vendor counts to secure volume commitments. The market structure tilts toward consolidated procurement power concentrated in integrated module suppliers who control both semiconductor fabrication and passive component specification. Three archetypes define competitive positioning: captive semiconductor fabricators with backward component integration, specialized passive component pure-plays, and diversified industrial conglomerates with cross-sector electronics portfolios. Capacity expansion in silicon carbide substrates and palladium-nickel electrode supply chains represent the dominant competitive vectors.
Among diversified Korean electronics conglomerates, Samsung Electronics exemplifies the captive fabrication archetype through in-house memory and logic production. Japanese specialists Murata Manufacturing Co. Ltd. and TDK Corporation occupy positions within the passive component pure-play tier, anchoring supply relationships with automotive and telecommunications OEMs. German power semiconductor designer Infineon Technologies AG represents the integrated module supplier archetype, controlling silicon carbide device architectures that differentiate its portfolio.
| Leading Market Players |
|---|
| Samsung Electronics |
| Murata Manufacturing Co. Ltd. |
| Infineon Technologies AG |
| Vishay Intertechnology Inc. |
| TDK Corporation |
| NXP Semiconductors NV |
| Panasonic Corporation |
| Eaton Corporation |
| Texas Instruments |
| Others |
Value Chain & Pricing Dynamics
Captive semiconductor fabrication anchors supply position and pricing power for integrated module suppliers who co-design active-passive subsystems with automotive Tier-1s. This backward integration into silicon carbide device architectures and palladium-nickel electrode supply chains concentrates procurement leverage among Murata, TDK, and Infineon-class players while squeezing distributor margins and Tier-2 EMS pricing autonomy.
Pricing Analysis
Warranty and AEC-Q200 certification bundling separate automotive-grade MLCC and film capacitor pricing from industrial catalog pricing. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-tier components tracks qualification investment and temperature rating differentiation. Cost compression in consumer-tier ceramic capacitors intensifies because Samsung Electronics and Chinese manufacturers expand captive production. Tier-2 EMS providers in Mexico and Eastern Europe exhibit highest price sensitivity; Tier-1 automotive suppliers in Germany and Japan show lowest sensitivity due to multi-year volume commitment structures.
Supply Chain Analysis
RF simulation talent scarcity in Kyoto, Nagoya, and Suwon manufacturing clusters constrains millimeter-wave component design throughput and extends lead times for 5G base station filter procurement. Component fabrication concentrates in Japan, South Korea, and Taiwan; raw material supply draws from South African palladium mining and Russian nickel operations. Single-source vulnerability around Wolfspeed and II-VI silicon carbide substrate captive production threatens fabless power semiconductor designers. Distribution runs through Arrow Electronics and Avnet-class broadline distributors serving Tier-2 EMS and aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over silicon carbide substrate supply and AEC-Q200 certification timelines determines competitive durability. Players pursue backward integration into electrode material supply and captive foundry capacity as the decisive upstream lever.
For Market Incumbents: To counter silicon carbide substrate scarcity from Wolfspeed and II-VI captive production, secure multi-year electrode supply agreements with South African and Russian mining operations. Add AEC-Q200 certification capacity in Nagoya or Stuttgart to compress 18-24 month qualification timelines. Deepen backward integration into palladium-nickel electrode supply chains to defend margin position against distributor consolidation. For New Entrants and Emerging Players: Tier-2 EMS providers in Mexico and Eastern Europe represent the most penetrable channel partner type for specialty inductor and temperature-compensated capacitor penetration. Target India's PLI scheme greenfield fab investments as geographic white space. Pursue automotive radar module design wins at 77-81 GHz as the specific go-to-market angle bypassing saturated consumer capacitor markets. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking cross-sector electronics portfolios. Long-term viability across the analysis window hinges on silicon carbide device architecture control and GB standards compliance for China market access. Watch for SAMR enforcement intensity on dual carbon goals as the inflection indicator for low-loss inductor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Capacity Expansion | Wolfspeed and II-VI captive production limits external wafer availability for fabless designers. |
| AEC-Q200 Certification Investment | Stuttgart and Nagoya-based Tier-1s consolidate vendor lists around three-year volume commitments. |
| Multi-Year Electrode Supply Agreement | Murata and TDK lock palladium-nickel supply directly with battery pack manufacturers. |
| GaN-on-Silicon Foundry Integration | Standard CMOS process convergence enables cost-competitive high-frequency power conversion. |
| India PLI Scheme Manufacturing Footprint | Production-linked incentives attract greenfield fab investments away from East Asian concentration. |
Study Parameters
Multi-period observation of MLCC pricing volatility, silicon carbide substrate allocation patterns, and AEC-Q200 certification timelines anchored the trend analysis, supplemented by interviews with Tier-1 automotive procurement directors, passive component plant managers in Kyoto and Nagoya, RF design engineers at Taiwan base station manufacturers, and distributor inventory planners at Arrow Electronics. Secondary validation drew from SAMR GB standards documentation, ECHA REACH SVHC candidate list expansions, SEC 10-K filings of listed component manufacturers, and Japan Customs trade statistics. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segment-weighting approach distributed value and volume across component type, technology node, application end-use, and customer tier dimensions. The projection horizon incorporated automotive electrification content-per-vehicle trajectories, 5G base station deployment cadence in FCC-allocated millimeter-wave spectrum, and industrial motor drive efficiency upgrade cycles under China's dual carbon targets. CAGRs derived from regression analysis of historical procurement patterns and elasticity-adjusted demand curves for palladium electrode pricing.
Caveats apply where palladium supply disruptions from Russian or South African mining operations, REACH SVHC list expansions beyond 233 substances, or export control tightening on gallium and germanium could materially shift the outlook. Forecasts reflect assumptions about SAMR enforcement consistency and FCC spectrum allocation timelines. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market