
 Silicon Base Paper Market | 2026-2036
Silicon Base Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Base Paper Market Analytics
REACH compliance is restructuring the cost-of-entry calculus for European silicon base paper imports, forcing non-EU mills to reformulate coating chemistries or absorb certification burdens. Lintec Corporation leverages its captive polymer research to navigate these requirements, while Ahlstrom-Munksjö Oyj anchors Nordic pulp supply chains with integrated kraft paper production. Mondi Group competes through geographic dominance in Central European converting corridors.
Silicon base paper denotes a cellulose substrate coated with polydimethylsiloxane or similar silicone polymers, typically achieving release forces between 5 and 50 g/inch to enable clean separation from pressure-sensitive adhesives. Release liner applications dominate volume flows, sustained by labelstock and medical tape demand, while electrical insulation grades command premium positioning amid EV battery module assembly expansion. Food grade segments occupy a narrower but defensible niche as FDA and EU food-contact compliance requirements raise qualification barriers for new entrants.
FDA food-contact rules, EU REACH substance restrictions, and China's GB standards collectively shape product formulation, testing protocols, and cross-border shipment eligibility for silicon base paper suppliers. The EU F-Gas Regulation indirectly pressures solvent-based silicone curing processes, redirecting capital toward UV and electron-beam curing infrastructure. Stakeholders must monitor divergence between EU and Chinese chemical registration regimes, as misalignment threatens to fragment global formulation strategies and duplicate compliance costs.
Market Dynamics
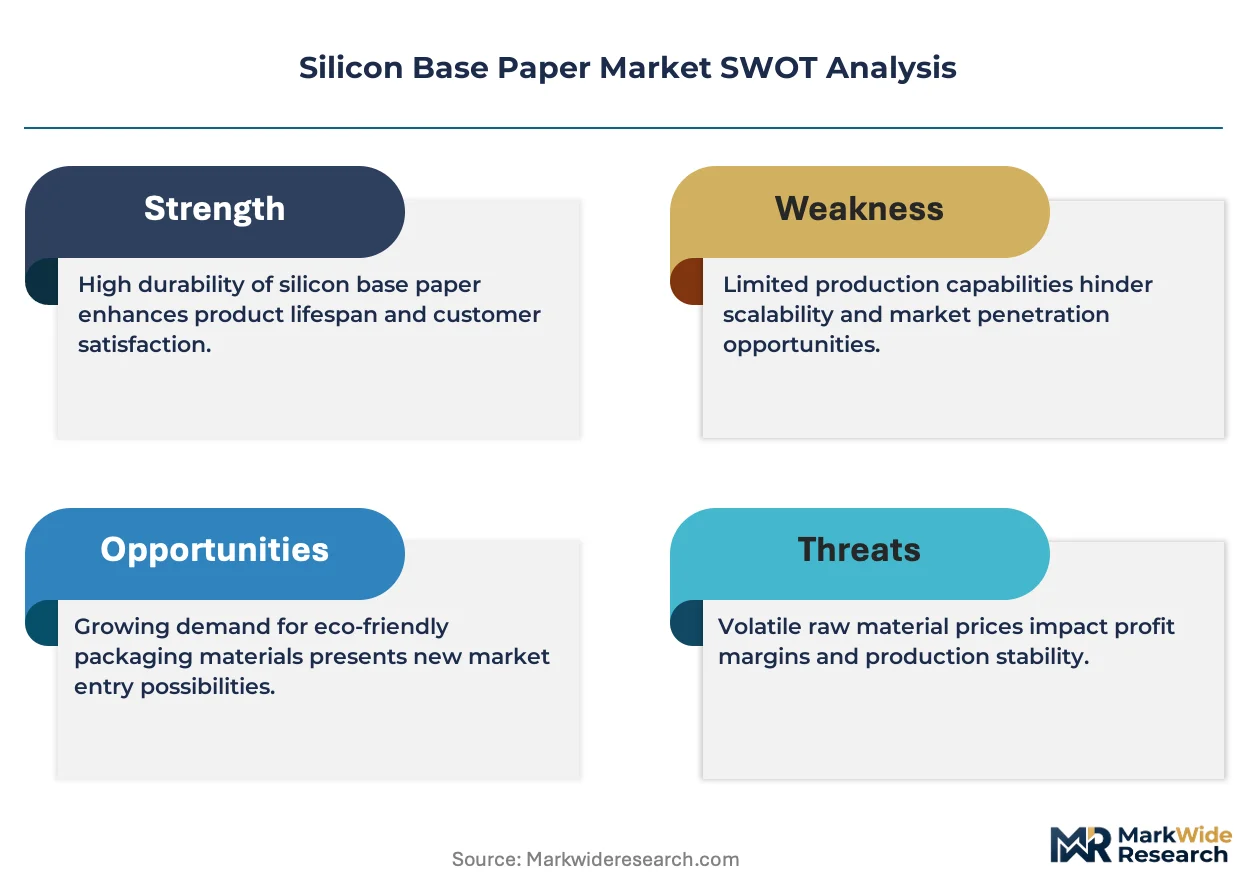
Water-based silicone coating migration is compressing solvent-based capacity utilization across European and Chinese mills, forcing converters to rebuild curing infrastructure ahead of EU F-Gas Regulation deadlines.
Growth Catalysts
- EV battery module assembly:Electrical insulation grades for lithium-ion cell stacking are pulling premium release liner volumes into automotive supply chains.
- REACH substance restrictions:Reformulation mandates are accelerating compliant coating chemistry development among non-EU exporters seeking European market access.
- Jiangsu-Zhejiang cluster expansion:Labelstock and tape producers concentrated near Shanghai's port infrastructure are scaling consumption of release liner grades for adhesive component protection.
Market Restraints
- Platinum catalyst cost volatility:Hydrosilylation chemistry depends on platinum group metal pricing, compressing margin predictability for coating operations.
- German kraft pulp supply concentration:Nordic integrated producers control upstream cellulose substrate flows, creating bottleneck risk for non-captive converters.
- Fluorosilicone substitution threat:High-performance release applications in medical and electronics sectors are evaluating fluorinated alternatives for extreme temperature resistance.
Strategic Opportunities
- India labelstock penetration:Domestic packaging and logistics sectors remain underpenetrated by silicone release liner specifications relative to East Asian consumption intensity.
- UV-LED curing convergence:Electron-beam and ultraviolet curing technology integration is opening retrofit pathways for solvent-based coating lines facing F-Gas phase-down timelines.
- EU Green Deal recyclability mandates:Paper substrate circularity requirements are creating first-mover advantage for mills with certified recyclable water-based coating platforms.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in silicone-paper interface engineering and release force tuning is concentrated among retiring technical staff at legacy coating operations.
- Dual certification timelines:Simultaneous FDA food-contact and EU food-contact compliance pathways are extending product qualification cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Base Paper Market |
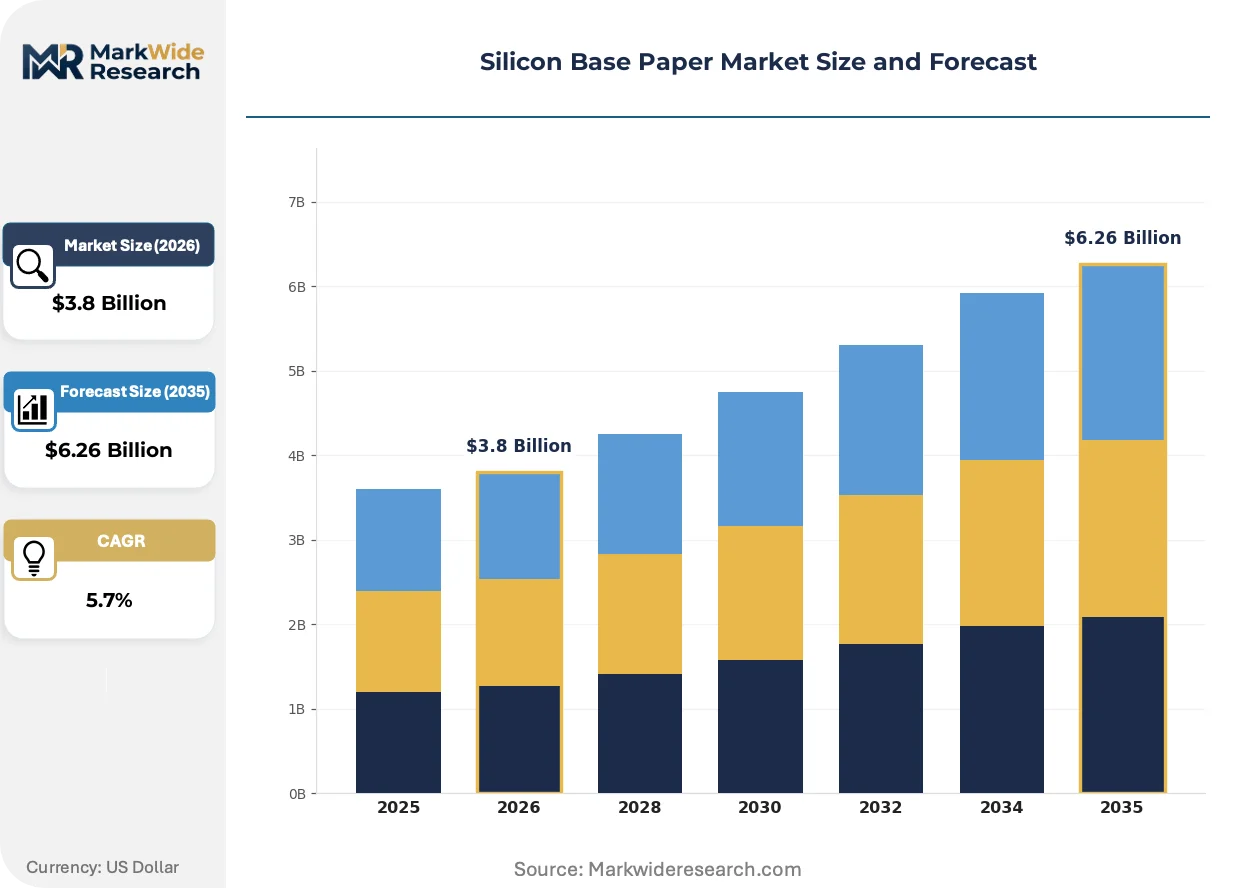
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Electrical Insulation, Release Liner, Industrial Packaging End Use Industry: Food and Beverage, Electronics, Automotive, Healthcare Form: Coated, Uncoated, Laminated, Printed Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Lintec Corporation, Ahlstrom-Munksjö Oyj, Mondi Group, UPM-Kymmene Corporation, Loparex LLC, Siliconature S.p.A., Mitsubishi Paper Mills Ltd., 3M, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Base Paper Market Evolving Landscape
Coating chemistry and curing infrastructure are undergoing parallel transformation as regulatory pressure and end-use performance requirements diverge from legacy solvent-based process economics.
UV-curable polydimethylsiloxane formulations are electrifying release liner production economics by eliminating thermal oxidation steps and reducing energy intensity per meter of coated substrate. Medical tape and electronics manufacturers in Germany and Japan are qualifying these platforms for clean-room applications. The technology is electrifying competitive positioning among mid-scale converters lacking capital for electron-beam infrastructure.
EU F-Gas Regulation phase-down schedules are forcing coating operators to retire solvent-based thermal curing lines ahead of planned asset life. Capital is redirecting toward water-based emulsion coating and radiation-cured alternatives. Food-grade and medical release liner segments face the steepest compliance timelines given residual solvent restrictions.
Direct mill-to-converter relationships are displacing distributor-mediated procurement in high-volume labelstock channels. Large adhesive manufacturers in China's Jiangsu province are securing dedicated coating capacity through off-take agreements rather than spot market purchasing. This concentration is most visible in electronics and automotive adhesive supply chains where release force consistency requirements favor qualified supplier lock-in.
Silicon Base Paper Market Segmentation
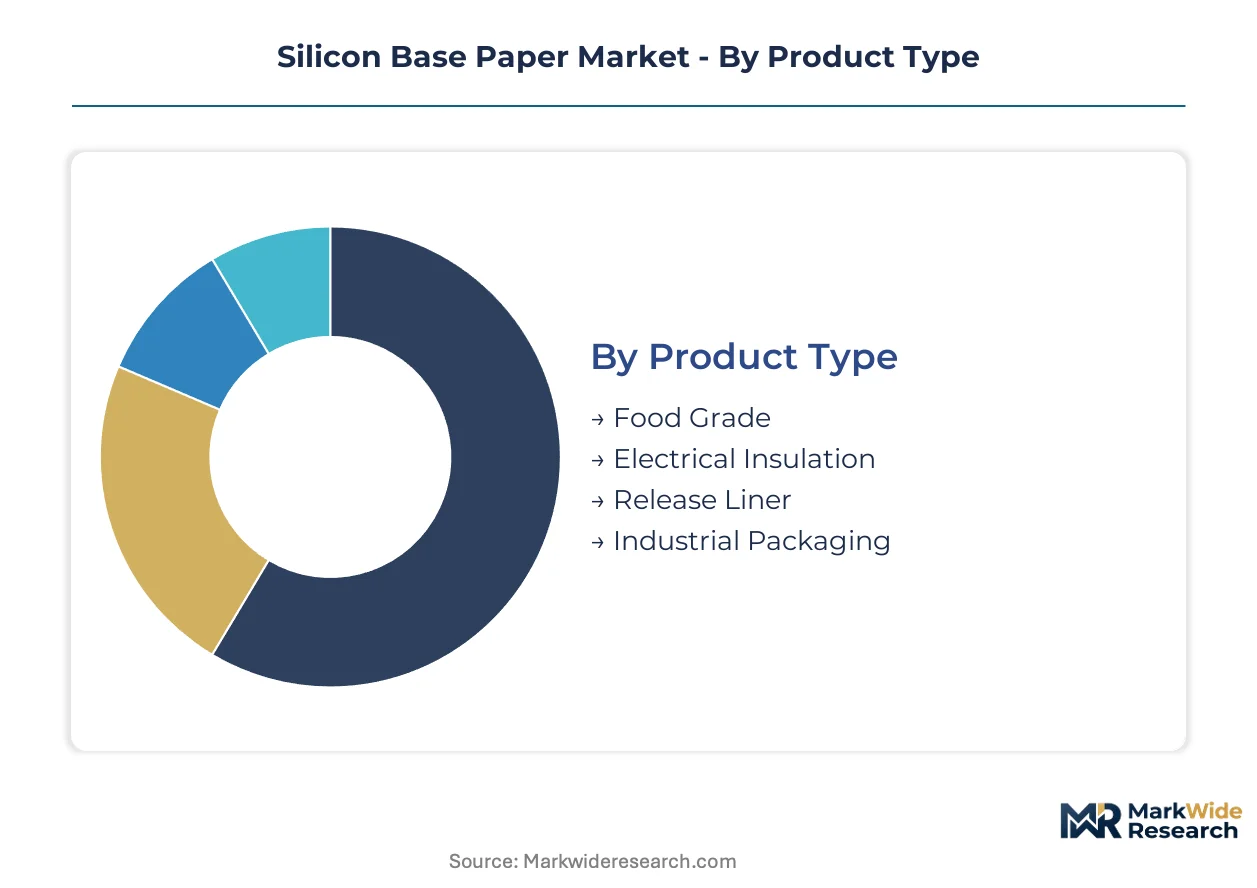
Segmentation in silicon base paper markets reveals how coating chemistry, end-use performance thresholds, and regulatory compliance requirements fragment supplier strategies. Each dimension carries distinct margin profiles and capital intensity demands that reshape competitive positioning across regional markets.
Product Type:
Upgrade cycles in silicone coating technology are driving specification divergence as converters retire solvent-based lines and qualify water-based alternatives for regulatory compliance.
- Release Liner:Polydimethylsiloxane-coated cellulose substrates achieve release forces between 5 and 50 g/inch for clean adhesive separation. Demand concentrates in China's Jiangsu and Zhejiang provinces where labelstock and tape producers cluster near Shanghai's port infrastructure, sustained by electronics manufacturers expanding adhesive component protection.
- Electrical Insulation:Higher-density silicone formulations withstand thermal cycling in lithium-ion battery module assembly. EV battery stacking operations in Germany and Japan are pulling premium volumes into automotive supply chains as cell-to-pack architectures proliferate.
- Food Grade:FDA and EU food-contact compliance requirements raise qualification barriers for new entrants, occupying a narrower but defensible niche with extended certification timelines.
- Industrial Packaging:Standard release specifications serve general protective applications with lower regulatory burden and compressed margin structures.
Volume placements concentrate in Release Liner; the faster expansion belongs to Electrical Insulation.
End Use Industry:
Cost tier differentiation separates premium-qualified medical and electronics specifications from commodity packaging applications with minimal coating customization.
- Electronics:Clean-room release liner specifications for semiconductor and display manufacturing command qualification premiums. East Asian manufacturers are scaling consumption of high-purity grades for adhesive component protection in module assembly.
- Healthcare:Medical tape and wound care applications require FDA and EU MDR compliance with residual solvent restrictions. German and Japanese converters are qualifying UV-curable platforms for clean-room production environments.
- Automotive:EV battery module assembly is pulling electrical insulation grades into automotive supply chains as lithium-ion cell stacking expands.
- Food and Beverage:Labelstock for packaging applications operates under GB standards in China and FDA rules in the US, with dual certification extending product qualification cycles.
Electronics commands the highest placement volumes; Healthcare is climbing the fastest on regulatory premium capture.
Form:
Application-specific requirements determine whether converters specify pre-coated substrates or integrate coating operations in-house.
- Coated:Silicone-polymer application via solvent-based, water-based, or radiation-cured processes dominates release liner production. EU F-Gas Regulation phase-down schedules are forcing coating operators to retire thermal curing lines ahead of planned asset life.
- Laminated:Multi-layer constructions for electrical insulation grades withstand thermal cycling in battery module assembly, commanding specification premiums in automotive supply chains.
- Uncoated:Base cellulose substrates for downstream coating integration serve converters with captive polymer research capabilities.
- Printed:Branded or instructional surface treatments for consumer-facing labelstock applications carry lower technical barriers.
Coated forms absorb the dominant placement share; Laminated formats are gaining share fastest on EV battery demand.
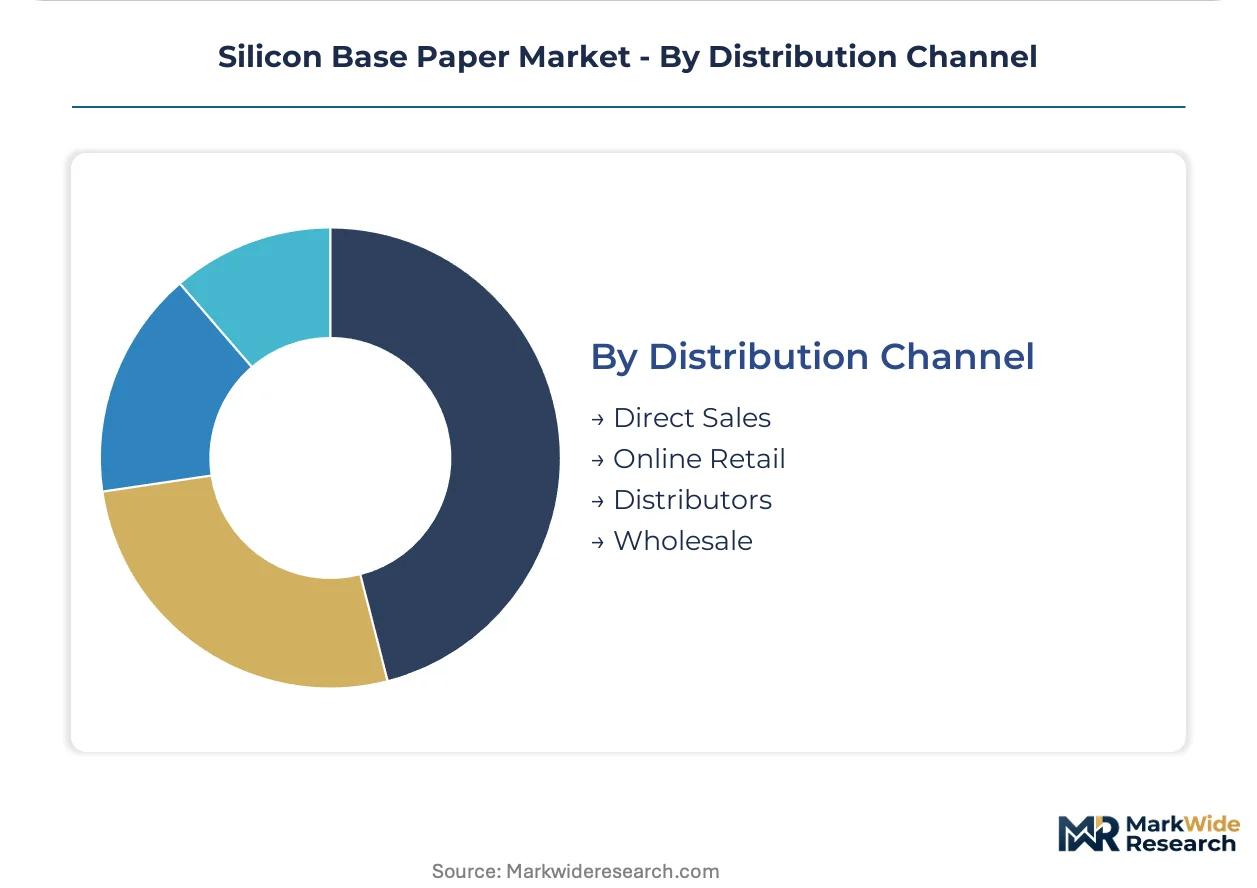
Distribution Channel:
Customer type fragmentation separates high-volume adhesive manufacturers seeking supplier lock-in from spot-market purchasers serving fragmented converting operations.
- Direct Sales:Mill-to-converter relationships are displacing distributor-mediated procurement in high-volume labelstock channels. Large adhesive manufacturers in Jiangsu province are securing dedicated coating capacity through off-take agreements rather than spot market purchasing.
- Distributors:Inventory aggregation serves mid-scale converters lacking capital for electron-beam infrastructure or qualified supplier development.
- Wholesale:Bulk paper substrate flows concentrate through Nordic integrated producers controlling upstream cellulose supply chains.
- Online Retail:Digital procurement platforms serve small-batch and specialty specification requirements with limited technical support.
Direct Sales channels capture the largest placement volumes; Distributor relationships are expanding most quickly among mid-scale converters retrofitting curing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters in East Asian electronics corridors and European automotive supply chains, with regulatory divergence fragmenting coating chemistry strategies across major producing regions.
China
Electronics manufacturers in Jiangsu and Zhejiang provinces drive release liner consumption for adhesive component protection. GB standards govern food-contact specifications, while MEE enforcement tightens volatile organic compound limits on solvent-based coating operations. Shanghai's port infrastructure anchors labelstock and tape producer clusters that source silicon base paper for export-oriented manufacturing.
Germany
EV battery module assembly pulls premium electrical insulation grades into automotive supply chains as cell-to-pack architectures proliferate. REACH substance restrictions and EU F-Gas Regulation phase-down schedules force coating operators to retire thermal curing lines ahead of planned asset life. Industrial corridors in Bavaria and Baden-Württemberg concentrate converter operations serving continental European demand.
United States
Medical tape and wound care applications require FDA compliance with residual solvent restrictions, extending qualification timelines for new entrants. Clean-room release liner specifications for semiconductor manufacturing command premiums in Arizona and Texas fabrication hubs. The EPA oversees air quality standards affecting coating facility siting decisions.
Japan
Electronics and display manufacturers qualify UV-curable platforms for clean-room production environments. METI promotes advanced materials development through industrial technology grants. The Kanto and Kansai regions concentrate converter operations with integrated polymer research capabilities serving precision adhesive applications.
India
Domestic packaging and logistics sectors remain underpenetrated by silicone release liner specifications relative to East Asian consumption intensity. BIS certification requirements create qualification barriers for imported substrate grades. Maharashtra and Gujarat host emerging converting capacity serving pharmaceutical and consumer goods labelstock demand.
Silicon Base Paper Market Competitive Landscape
Nordic integrated producers anchor one tier through captive pulp supply chains; East Asian specialists hold position via electronics corridor proximity and polymer research integration. The vendor base separates into three strategic archetypes: backward-integrated paper mills controlling substrate supply, coating specialists with qualified customer lock-in, and diversified materials conglomerates leveraging cross-segment technology transfer. Capacity expansion and UV-curing infrastructure retrofit represent dominant competitive moves as regulatory deadlines approach.
Within the integrated mill tier, Ahlstrom-Munksjö Oyj and UPM-Kymmene Corporation exemplify Nordic producers with captive kraft paper production. Lintec Corporation occupies a position among Japanese specialists leveraging polymer research capabilities. Mondi Group anchors Central European converting corridor presence.
| Leading Market Players |
|---|
| Lintec Corporation |
| Ahlstrom-Munksjö Oyj |
| Mondi Group |
| UPM-Kymmene Corporation |
| Loparex LLC |
| Siliconature S.p.A. |
| Mitsubishi Paper Mills Ltd. |
| 3M |
| Saint-Gobain |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA food-contact, EU REACH-compliant, and industrial non-certified tiers splits pricing power across converter relationships. Premium electrical insulation grades for EV battery assembly command contract-based offtake structures with locked-in volume commitments, while commodity release liner volumes trade on spot indices vulnerable to platinum catalyst cost swings. This bifurcation concentrates margin capture among Nordic integrated mills with captive pulp supply and qualified coating chemistry, leaving mid-scale converters exposed to input cost pass-through.
Pricing Analysis
Volume placements concentrate in standard release liner grades with compressed margins, while electrical insulation and medical-certified tiers sustain premium capture. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, coating chemistry complexity, and volume scale. Pricing pressure stems from water-based silicone coating migration forcing solvent-based capacity retirement ahead of EU F-Gas deadlines. Mid-scale converters without captive polymer research exhibit highest price sensitivity; integrated mills with Nordic pulp control exhibit lowest.
Supply Chain Analysis
Freight cost differentials favor Shanghai-port-proximate converters in Jiangsu and Zhejiang provinces sourcing from domestic coating operations. Supply concentration centers on Finland, Sweden, and Germany for kraft pulp substrate; Japan and China for silicone polymer formulation. Raw material dependencies include Nordic softwood pulp, platinum group metal catalysts, and polydimethylsiloxane resin. Single-source vulnerability runs through German kraft pulp supply concentration. Distribution runs through direct mill-to-converter relationships displacing distributor mediation in high-volume labelstock channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU F-Gas Regulation deadlines force solvent-based coating line retirement, eliminating converters lacking capital for UV-LED curing retrofit. Smaller players without qualified customer lock-in or captive substrate supply face exit or acquisition.
For Market Incumbents: Anchor Nordic pulp supply chains through long-term fiber sourcing agreements or integrated mill acquisition to defend against German kraft pulp bottleneck risk. Accelerate UV-curable platform qualification for medical tape and electronics clean-room specifications before F-Gas phase-down eliminates solvent-based competitors. Prioritize direct off-take relationships with Jiangsu province adhesive manufacturers to lock in volume against emerging Chinese coating specialists. For New Entrants and Emerging Players: Capture India's underpenetrated labelstock market through BIS-certified water-based coating platforms serving Maharashtra and Gujarat pharmaceutical packaging demand. Target mid-scale converters retrofitting curing infrastructure with UV-LED equipment leasing and technical service bundling. Lead with certified recyclable coating chemistry aligned with EU Green Deal circularity mandates to differentiate against legacy solvent-based incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with coating specialists possessing qualified FDA-EU dual certification and established automotive supply chain relationships given EV battery module assembly expansion. Long-term viability favors assets with water-based or radiation-cured platform deployment already operational. Watch UV-LED curing adoption rates among German and Japanese medical tape converters as inflection indicator for technology transition speed.| Strategic Initiative | Industry Significance |
|---|---|
| UV-LED Curing Infrastructure Retrofit | Enables F-Gas compliance for solvent-based coating lines facing regulatory phase-down deadlines. |
| Backward Integration into Kraft Pulp Supply | Secures Nordic softwood substrate flows against German supply concentration risk. |
| FDA-EU Dual Certification Investment | Extends qualification timelines but creates defensible niche in medical tape and food-grade release liners. |
| Direct Mill-to-Converter Off-Take Agreements | Locks in Jiangsu province labelstock volume against spot market price volatility. |
| Water-Based Coating Platform Development | Aligns with EU Green Deal recyclability mandates and MEE VOC enforcement in China. |
Research Methodology
Multi-period observation of coating chemistry migration patterns, regulatory deadline progression, and converter capacity utilization anchored the trend analysis, supplemented by interviews with silicone coating plant managers, procurement leads at adhesive manufacturers, technical R&D directors at paper mills, and distribution channel partners. Secondary validation drew from customs and trade data, SEC filings of listed paper and chemical companies, ECHA REACH substance registration databases, and MEE environmental enforcement disclosures. Bottom-up volume estimates triangulated against top-down market sizing across product type, end-use industry, and regional production hub segmentation.
Segment-weighting approaches applied differential growth assumptions across release liner, electrical insulation, food grade, and industrial packaging tiers. End-use industry splits modeled electronics, healthcare, automotive, and food and beverage demand trajectories. Form dimension captured coated, laminated, uncoated, and printed substrate flows. Distribution channel analysis weighted direct sales, distributor, wholesale, and online retail pathway evolution. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points and technology substitution curves. Platinum group metal price volatility and EU F-Gas phase-down schedules served as key forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to divergence between EU and Chinese chemical registration regimes, fluorosilicone substitution rates in high-temperature medical applications, and EV battery architecture shifts affecting electrical insulation grade specifications. Forecasts reflect assumptions about regulatory enforcement consistency, coating technology adoption curves, and pulp supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
North America Silicone Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Semiconductor PI Film Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
Rhenium Market
Semiconductor Material
OLED Materials Market