
 Taiwan Integrated Circuits Market | 2026-2036
Taiwan Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Integrated Circuits Market Insights
A capital-intensity divergence between foundry operators and fabless designers is redrawing competitive boundaries in Taiwan's semiconductor landscape. Taiwan Semiconductor Manufacturing Company Limited sustains the world's most advanced lithography investments, anchoring its dominance at sub-3 nanometer nodes. United Microelectronics Corporation competes through mature-node specialization, leveraging cost-optimized 28nm and above processes for automotive and industrial clients. ASE Technology controls advanced packaging capacity, extending its reach into chiplet integration and 3D stacking architectures that differentiate Taiwan's post-Moore value chain.
Integrated circuits are miniaturized electronic assemblies fabricated on semiconductor substrates, typically silicon, through photolithography, etching, and deposition processes that pattern billions of transistors onto die areas measured in square millimeters; these devices function as the computational and control cores of electronic systems, executing logic operations, signal processing, and power management across virtually all modern equipment. Digital ICs lead volume production as CMOS logic devices supply the processor and memory demands of data centers and mobile devices, while analog and mixed-signal categories capture margin pools in precision sensing and power conversion applications where design expertise creates defensible positions. GaN-on-silicon technology is gaining traction in power segments, particularly for telecommunications infrastructure and electric vehicle charging systems where efficiency thresholds exceed silicon capabilities.
Taiwan's Ministry of Economic Affairs enforces the Statute for Industrial Innovation, channeling tax incentives and R&D credits toward advanced semiconductor manufacturing and domestic supply chain resilience. The National Science and Technology Council coordinates with Hsinchu, Taichung, and Tainan science park administrations to zone land and utilities for expanding foundry and packaging capacity. BIS-equivalent export control frameworks, administered through Taiwan's Bureau of Foreign Trade, restrict certain process technologies to approved destinations, shaping customer access and fab investment timelines. Stakeholders must monitor how U.S. CHIPS Act domestic content requirements and EU chip sovereignty programs redirect end-user procurement patterns away from pure Taiwan sourcing.
Market Dynamics
Advanced lithography node transitions are compressing investment timelines across Taiwan's foundry sector, forcing capital allocation decisions years ahead of confirmed demand while mature-node specialists capture margin pools in automotive and industrial analog segments.
Growth Catalysts
- Statute for Industrial Innovation:Taiwan's tax incentive framework channels R&D credits toward advanced semiconductor manufacturing, lowering effective R&D costs for process node development.
- Electric vehicle powertrains:Automotive electronics adoption is accelerating demand for wide-bandgap semiconductors and high-voltage analog controllers from Taiwan-based suppliers.
- Hsinchu Science Park:Concentrated infrastructure clustering reduces logistics costs and enables rapid supplier-prototype iteration cycles for fabless design houses.
Market Restraints
- EUV equipment concentration:Single-source dependency on ASML for extreme ultraviolet lithography systems creates procurement bottlenecks and extended lead times for sub-5nm capacity expansion.
- Export control friction:BIS-equivalent frameworks administered through Taiwan's Bureau of Foreign Trade restrict certain process technologies to approved destinations, constraining customer addressable markets.
- Silicon carbide substitution:Power electronics applications above 600V increasingly migrate to SiC substrates, displacing traditional silicon-based IGBT and MOSFET solutions in EV inverters.
Strategic Opportunities
- Chiplet integration architectures:Advanced packaging capacity at ASE Technology and substrate suppliers enables 3D stacking and heterogeneous integration for AI accelerators and high-bandwidth memory.
- Tainan Science Park expansion:Greenfield fab sites offer utility-scaled water and power allocations unavailable in saturated Hsinchu and Taichung corridors.
- GaN-on-silicon convergence:Telecommunications infrastructure and EV charging systems are driving demand for gallium nitride power devices where Taiwan's LED heritage provides epitaxy expertise.
Industry Challenges
- Process engineering talent scarcity:Advanced node development requires specialized expertise in computational lithography and materials science that outpaces domestic university pipeline output.
- Multi-billion-dollar fab construction cycles:Each leading-edge facility demands five-year capital deployment horizons with uncertain demand visibility at completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Integrated Circuits Market |
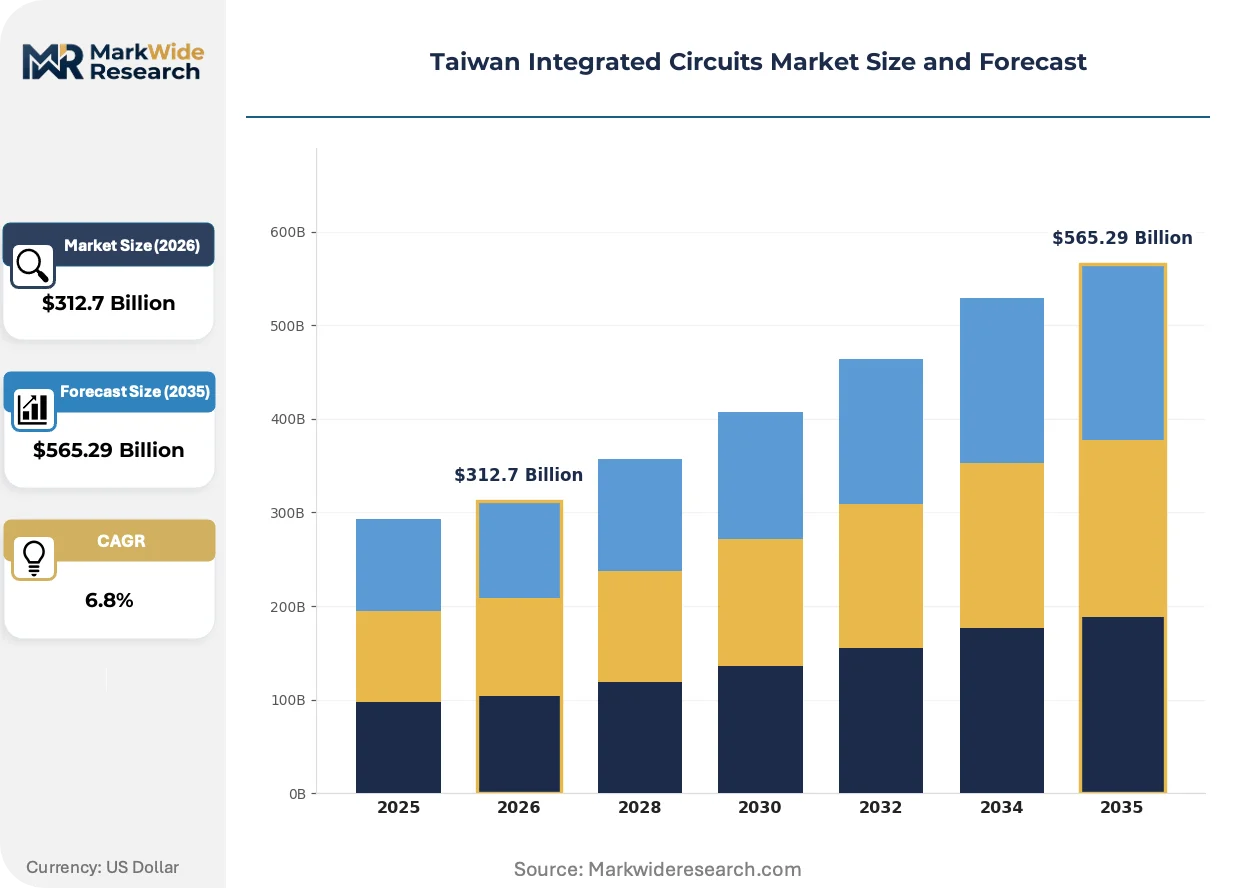
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Mixed-Signal, Power Application: Consumer Electronics, Automotive, Telecommunications, Industrial Technology: CMOS, BiCMOS, GaN, SOI End User: OEMs, Tier-1 Suppliers, Startups, Enterprises |
| Companies Covered | Taiwan Semiconductor Manufacturing Company Limited, United Microelectronics Corporation, ASE Technology, MediaTek Inc., Realtek Semiconductor Corp, Novatek Microelectronics Corp., Nuvoton Technology Corporation, Macronix International Co., Ltd., Powerchip Semiconductor Manufacturing Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Integrated Circuits Market Trends and Innovations
Process technology roadmaps are diverging between leading-edge digital logic and specialty analog segments, creating distinct competitive arenas where capital intensity and design expertise trade off differently.
Gate-all-around transistor architectures are fragmenting the foundry competitive landscape by separating sub-3nm capability from mature-node profitability. Data center GPU and AI accelerator designers are migrating designs to these structures for power efficiency gains. The technology is fragmenting customer portfolios into high-volume digital logic buyers and stranded analog specialists unable to justify migration costs.
Taiwan's Bureau of Foreign Trade has tightened BIS-equivalent export licensing for certain etching and deposition equipment categories. This regulatory friction is extending procurement timelines for mainland China-bound capacity expansions by 12-18 months. Memory and logic foundries with pre-approved end-user certifications are capturing redirected investment flows.
Long-term supply agreements are displacing spot-market wafer purchases among automotive tier-1 suppliers seeking guaranteed capacity allocation. Direct foundry relationships are replacing traditional distributor channels for power management and microcontroller categories. This pattern concentrates most visibly among German and Japanese automotive electronics procurement offices establishing Taipei-based sourcing teams.
Taiwan Integrated Circuits Market Segmentation
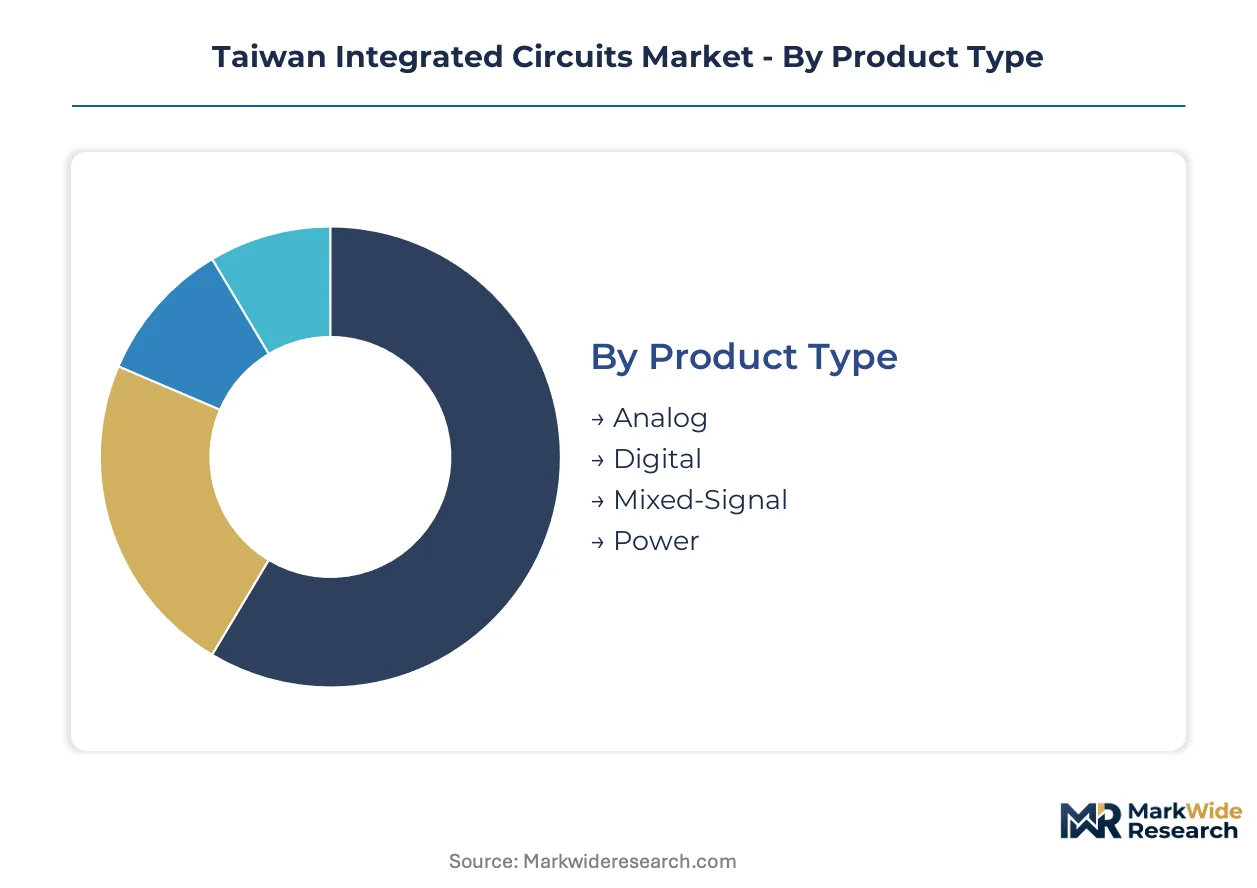
Segmentation in Taiwan's integrated circuits market exposes where process-node investments concentrate versus where specialty analog expertise defends margin pools. Foundry capacity allocation and end-user procurement patterns diverge sharply across these dimensions.
Product Type:
Substitution pressure from wide-bandgap semiconductors and advanced packaging integration is reshaping which product categories retain standalone viability versus absorption into system-level solutions.
- Digital:CMOS logic devices at sub-5nm nodes supply data center GPUs and AI accelerators. TSMC's N3E process anchors foundry revenue concentration as cloud hyperscalers lock in multi-year wafer supply agreements.
- Analog:Precision sensing and power conversion ICs leverage design expertise rather than lithography scale. Automotive tier-1 suppliers source voltage regulators and motor drivers through direct foundry relationships bypassing traditional distribution.
- Mixed-Signal:Data converters and RF transceivers bridge digital processing with physical interfaces. Baseband processors for telecommunications infrastructure require tight integration of high-speed ADCs and digital modems.
- Power:Discrete MOSFETs and IGBTs face displacement pressure from silicon carbide in EV inverters above 600V. GaN-on-silicon devices for telecommunications and charging systems exploit Taiwan's LED epitaxy heritage.
Digital ICs anchor the volume base while power semiconductors gain share at the steepest rate through EV electrification and renewable energy infrastructure buildout.
Application:
Cost tier stratification separates high-volume consumer shipments from automotive contracts demanding zero-defect traceability and decade-long supply guarantees.
- Automotive:Advanced driver-assistance systems and electric powertrains require AEC-Q100 qualified devices with functional safety certifications. German and Japanese OEMs have established Taipei-based procurement teams to secure direct foundry allocation.
- Consumer Electronics:Smartphones and wearables drive leading-edge node adoption with annual refresh cycles. Apple and MediaTek designs consume the majority of TSMC's N3 and N4 capacity.
- Telecommunications:5G baseband and mmWave infrastructure demand high-frequency mixed-signal expertise. GaN power amplifiers for macro cell towers exploit Taiwan's compound semiconductor foundry services.
- Industrial:Factory automation and smart manufacturing rely on microcontrollers with extended temperature ranges. Nuvoton Technology leverages Industrial Innovation Act incentives to deepen MCU development for this segment.
Consumer electronics commands the largest wafer volume while automotive applications expand most quickly as electrification penetrates vehicle platforms.
Technology:
Maturity differentiation separates entrenched CMOS scaling from emerging compound semiconductor alternatives competing on efficiency rather than transistor density.
- CMOS:FinFET and gate-all-around architectures dominate digital logic production. Sub-3nm transitions require EUV lithography systems with ASML single-source dependency creating procurement bottlenecks.
- GaN:Gallium nitride epitaxy on silicon substrates enables high-frequency power switching. Telecommunications infrastructure and EV charging systems drive demand where efficiency thresholds exceed silicon capabilities.
- BiCMOS:Bipolar-CMOS integration serves precision analog applications requiring high transconductance. RF front-end modules for smartphones combine high-speed bipolar transistors with dense CMOS logic.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance for RF and low-power designs. IoT edge devices exploit SOI's leakage advantages for extended battery operation.
CMOS technology anchors foundry output volumes while GaN processes climb the fastest as power electronics applications migrate beyond silicon limitations.
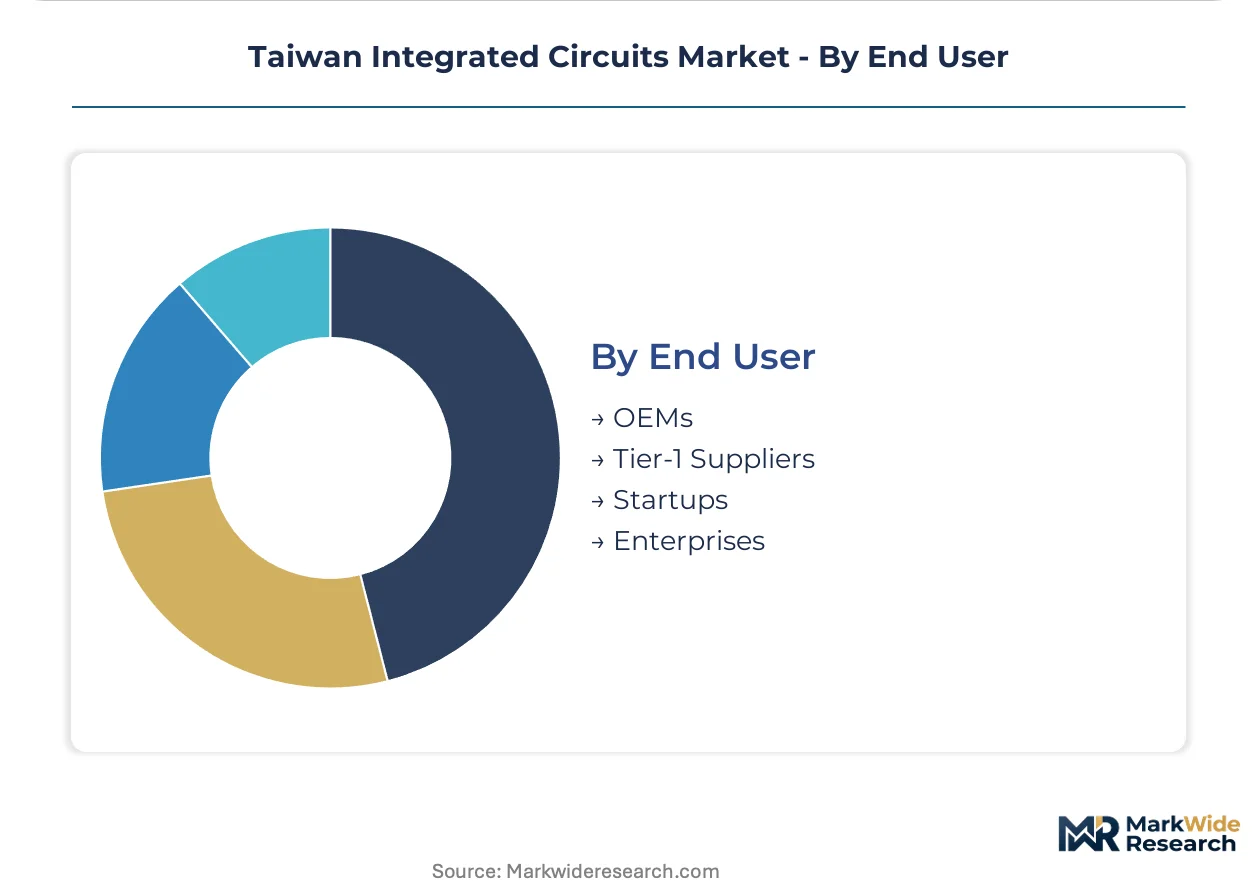
End User:
Customer type determines contract structure, with OEMs negotiating long-term supply agreements while startups face allocation constraints during capacity-constrained periods.
- OEMs:Original equipment manufacturers with internal semiconductor divisions, including Apple and Samsung, commission custom silicon at leading nodes. Direct foundry relationships displace merchant chip suppliers for system-level integration.
- Tier-1 Suppliers:Automotive electronics manufacturers like Bosch and Denso secure guaranteed capacity through multi-year supply contracts. Long-term agreements displace spot-market wafer purchases across power management and microcontroller categories.
- Startups:Fabless design houses in Hsinchu Science Park rely on rapid supplier-prototype iteration cycles. Clustered infrastructure reduces logistics costs but these customers face allocation priority challenges during demand surges.
- Enterprises:Cloud hyperscalers commission custom AI accelerators and data center processors. Google, Amazon, and Microsoft designs represent growing share of leading-edge foundry output.
OEMs anchor wafer volume commitments while enterprise custom silicon expands most quickly as cloud infrastructure buildout accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Taiwan's integrated circuits market. Hsinchu Science Park buyers accept premium pricing for sub-3nm capacity, while industrial microcontroller purchasers negotiate aggressively on mature-node wafer costs.
Hsinchu Science Park
Advanced lithography demand concentrates here as cloud hyperscalers and smartphone OEMs commission leading-edge silicon. The National Science and Technology Council coordinates land zoning and utility allocation through the Statute for Industrial Innovation framework. TSMC anchors the park's most advanced process node production, drawing fabless design houses into rapid supplier-prototype iteration cycles.
Taichung Science Park
Automotive electronics procurement teams from German and Japanese OEMs have established sourcing offices to secure AEC-Q100 qualified capacity. Taiwan's Bureau of Foreign Trade administers BIS-equivalent export licensing for equipment bound to this corridor. United Microelectronics Corporation specializes in cost-optimized 28nm and above processes for power management and motor driver applications.
Tainan Science Park
Greenfield fab development exploits utility-scaled water and power allocations unavailable in saturated northern corridors. The Ministry of Economic Affairs channels tax incentives toward expanding foundry and packaging capacity in this southern zone. ASE Technology controls advanced packaging installations here, enabling 3D stacking architectures for AI accelerators.
Kaohsiung Cluster
Compound semiconductor epitaxy leverages Taiwan's LED heritage for gallium nitride power device production. The Industrial Innovation Act provides R&D credits toward telecommunications infrastructure and EV charging system components. Nuvoton Technology deepens microcontroller development for smart manufacturing applications in this emerging southern hub.
Central Taiwan Science Park
Mixed-signal design houses cluster here to access precision analog expertise for data converter and RF transceiver development. National Science and Technology Council infrastructure investments reduce logistics costs between foundry and fabless operations. MediaTek and Realtek Semiconductor anchor baseband processor and connectivity chip design activities in this corridor.
Taiwan Integrated Circuits Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Taiwan's semiconductor landscape. The foundry segment concentrates around sub-3nm capability holders and mature-node cost optimizers, while packaging and design services fragment across specialty niches. Three archetypes dominate: capital-intensive foundry operators, fabless design specialists, and advanced packaging integrators. Competitive moves center on multi-year supply agreement negotiations and heterogeneous integration technology licensing.
Within the foundry tier, Taiwan Semiconductor Manufacturing Company Limited and United Microelectronics Corporation exemplify the divergence between leading-edge digital logic and mature-node profitability. ASE Technology occupies a position in advanced packaging, representing the post-Moore value chain extension. These three anchors illustrate how Taiwan's integrated circuits market stratifies across process technology generations and manufacturing stages.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company Limited |
| United Microelectronics Corporation |
| ASE Technology |
| MediaTek Inc. |
| Realtek Semiconductor Corp |
| Novatek Microelectronics Corp. |
| Nuvoton Technology Corporation |
| Macronix International Co., Ltd. |
| Powerchip Semiconductor Manufacturing Corporation |
| Others |
Pricing and Supply Chain Analysis
EUV lithography scale economies at sub-5nm nodes concentrate pricing power among foundries with ASML equipment access, compressing margin floors for mature-node specialists while elevating long-term contract premiums for automotive-qualified capacity. Taiwan's Bureau of Foreign Trade licensing timelines feed directly into cost structures, extending procurement cycles for restricted-destination shipments and amplifying price divergence between approved and constrained customer tiers.
Pricing Analysis
After-sales service contracts and multi-year wafer supply agreements anchor lifetime value capture beyond per-die spot pricing. Foundry pricing stratifies across premium leading-edge nodes, standard mature-process wafers, and economy-grade legacy capacity with volume-commitment discounts. Cost compression in automotive microcontroller tiers intensifies as German and Japanese OEMs consolidate procurement through direct foundry relationships. Tier-1 automotive suppliers exhibit lowest price sensitivity due to zero-defect traceability requirements, while consumer electronics OEMs negotiate aggressively on annual refresh cycle volumes.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication capacity while the USA and Japan concentrate etching and deposition equipment production. Raw material dependencies span high-purity silicon wafers, photoresist chemicals, and rare gases for EUV lithography. Single-source vulnerability to ASML for extreme ultraviolet systems creates procurement bottlenecks extending capacity expansion timelines. Distribution runs through direct foundry relationships displacing traditional merchant chip channels, particularly for automotive and data center custom silicon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide power devices threaten displacement of traditional silicon IGBTs and MOSFETs in EV inverters above 600V, forcing incumbents to defend analog and mixed-signal positions where design expertise creates defensible moats.
For Market Incumbents: Consolidate advanced packaging capabilities through ASE Technology's 3D stacking architectures to extend post-Moore value capture beyond lithography scaling limits. Deepen backward integration into GaN epitaxy substrates leveraging Taiwan's LED heritage, defending power electronics margins against SiC substitution in telecommunications and charging infrastructure.
For New Entrants and Emerging Players: Lead with heterogeneous integration services for AI accelerators and high-bandwidth memory, exploiting chiplet architecture fragmentation that separates advanced packaging demand from leading-edge foundry dependence. Target industrial microcontroller development in Kaohsiung's emerging compound semiconductor cluster, accessing Industrial Innovation Act R&D credits with shorter qualification cycles than automotive AEC-Q100 certification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foundries with multi-year supply agreements from cloud hyperscalers and automotive tier-1 suppliers, anchoring cash flow visibility across capacity investment cycles. Prioritize acquisition targets with pre-approved Bureau of Foreign Trade end-user certifications, avoiding 12-18 month licensing delays that strand capital in restricted-destination expansion. Monitor EU chip sovereignty program procurement shifts as the inflection signal for Taiwan sourcing concentration risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | ASE Technology's 3D stacking installations capture chiplet integration demand from AI accelerator designers. |
| GaN-on-Silicon Epitaxy Development | Taiwan's LED heritage enables power device efficiency gains in telecommunications infrastructure and EV charging. |
| Automotive Qualification Investment | AEC-Q100 certification opens direct procurement relationships with German and Japanese OEM sourcing teams. |
| Long-Term Supply Agreement Negotiation | Multi-year wafer contracts with cloud hyperscalers displace spot-market volatility in leading-edge node allocation. |
| Tainan Science Park Fab Development | Greenfield sites exploit utility-scaled water and power unavailable in saturated Hsinchu corridors. |
Research Methodology
Desk research of foundry capacity databases, equipment import records, and science park utility allocation filings preceded structured interviews with foundry operations executives, fabless design house CTOs, automotive tier-1 procurement directors, and Bureau of Foreign Trade licensing administrators. Secondary validation drew from Taiwan Ministry of Economic Affairs incentive disclosures, National Science and Technology Council infrastructure budgets, and ASML equipment delivery schedules. Bottom-up wafer demand estimates triangulated against top-down semiconductor consumption forecasts.
Variance decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application end-use, process technology node, and customer tier. CAGRs derived from fitted trend extrapolation adjusted for identified inflection points in node transition timelines and export control implementation phases. Forecast inputs incorporated EUV equipment delivery backlogs, automotive electrification penetration curves, and cloud hyperscaler capex disclosure patterns.
The analysis sits within stated boundaries; outcomes outside sustained Statute for Industrial Innovation incentive continuity or abrupt export control expansion would require recalibration. Forecasts reflect assumptions regarding ASML equipment access maintenance, automotive qualification timeline stability, and science park infrastructure completion schedules. Recalibration cycles align with material shifts in foundry node transition roadmaps, compound semiconductor substitution rates, and bilateral trade framework negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market