
 Rhenium Market | 2026-2036
Rhenium Market Size, Share, and Industry Trends Forecast 2026-2036
Rhenium Market Analysis
The divergence between premium rhenium metal and commodity-grade powder is hardening as aerospace superalloy specifications tighten purity thresholds while catalyst applications accept broader chemical variance. Freeport-McMoRan leverages its integrated molybdenum-rhenium byproduct streams to sustain cost advantages in primary extraction. Umicore competes through closed-loop recycling infrastructure that anchors European supply security. MOLYMET S.A. dominates South American refining capacity and extends geographic reach through long-term smelter partnerships.
Rhenium is a dense, refractory transition metal with a melting point exceeding 3,180 degrees Celsius, produced primarily as a byproduct of molybdenum and copper sulfide ore processing via hydrometallurgical solvent extraction. Its primary commercial purpose centers on nickel-based superalloys for single-crystal turbine blades, where rhenium additions of three to six percent by weight dramatically improve creep resistance and thermal fatigue life under jet engine operating conditions. Rhenium alloys command the dominant value share as turbine engine applications absorb the majority of primary metal output, while rhenium compounds represent a faster-growing segment driven by petrochemical catalyst regeneration cycles. Rhenium powder occupies a mature, price-sensitive niche in electrical contact manufacturing where platinum-group metal substitution limits margin expansion.
The EPA regulates rhenium-containing catalyst waste under hazardous material disposal frameworks, while the EU REACH regime mandates full substance registration and supply chain communication for imported rhenium compounds. The FAA's engine certification standards indirectly shape rhenium demand by specifying alloy performance thresholds that only rhenium-enhanced superalloys currently satisfy. Stakeholders must monitor how China's MIIT dual carbon goals and GB standards for critical mineral stockpiling redirect Asian rhenium flows toward domestic superalloy production rather than export markets.
Market Dynamics
The divergence between aerospace-grade purity specifications and catalyst-grade tolerance is hardening procurement segmentation, forcing suppliers to maintain dual metallurgical streams without cross-contamination.
Growth Catalysts
- Single-crystal turbine blade specifications:Next-generation propulsion systems require rhenium additions of three to six percent by weight to achieve creep resistance thresholds under sustained thermal stress.
- REACH substance registration mandates:Full supply chain communication requirements under EU REACH are accelerating formalized rhenium compound documentation across European petrochemical processors.
- Defense aerospace procurement:United States superalloy foundries anchor premium metal consumption through long-term offtake agreements tied to engine certification timelines.
Market Restraints
- Molybdenum-copper ore dependency:Primary rhenium extraction remains captive to byproduct recovery economics at sulfide ore processing facilities, constraining output responsiveness.
- Chile-China refining concentration:South American smelter partnerships and Asian concentrate flows create geographic chokepoints vulnerable to logistics disruption.
- Platinum-group metal substitution:Electrical contact manufacturers face persistent pressure to substitute rhenium powder with lower-cost alternatives in mature, price-sensitive applications.
Strategic Opportunities
- Closed-loop recycling infrastructure:Catalyst regeneration cycles in European petrochemical plants create recoverable rhenium streams that bypass primary extraction bottlenecks.
- MIIT dual carbon alignment:China's domestic superalloy production goals under GB standards may redirect Asian rhenium flows toward captive aerospace supply chains.
- Hydrometallurgical solvent extraction advances:Process intensification technologies are lowering recovery costs from low-grade molybdenum concentrates previously deemed uneconomic.
Industry Challenges
- Traceability system implementation:EU Green Deal emissions standards require granular material provenance documentation that many mid-stream processors lack technical capacity to generate.
- FAA certification timeline compression:Engine alloy qualification protocols demand extended thermal fatigue testing that delays new superalloy formulation commercialization by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhenium Market |
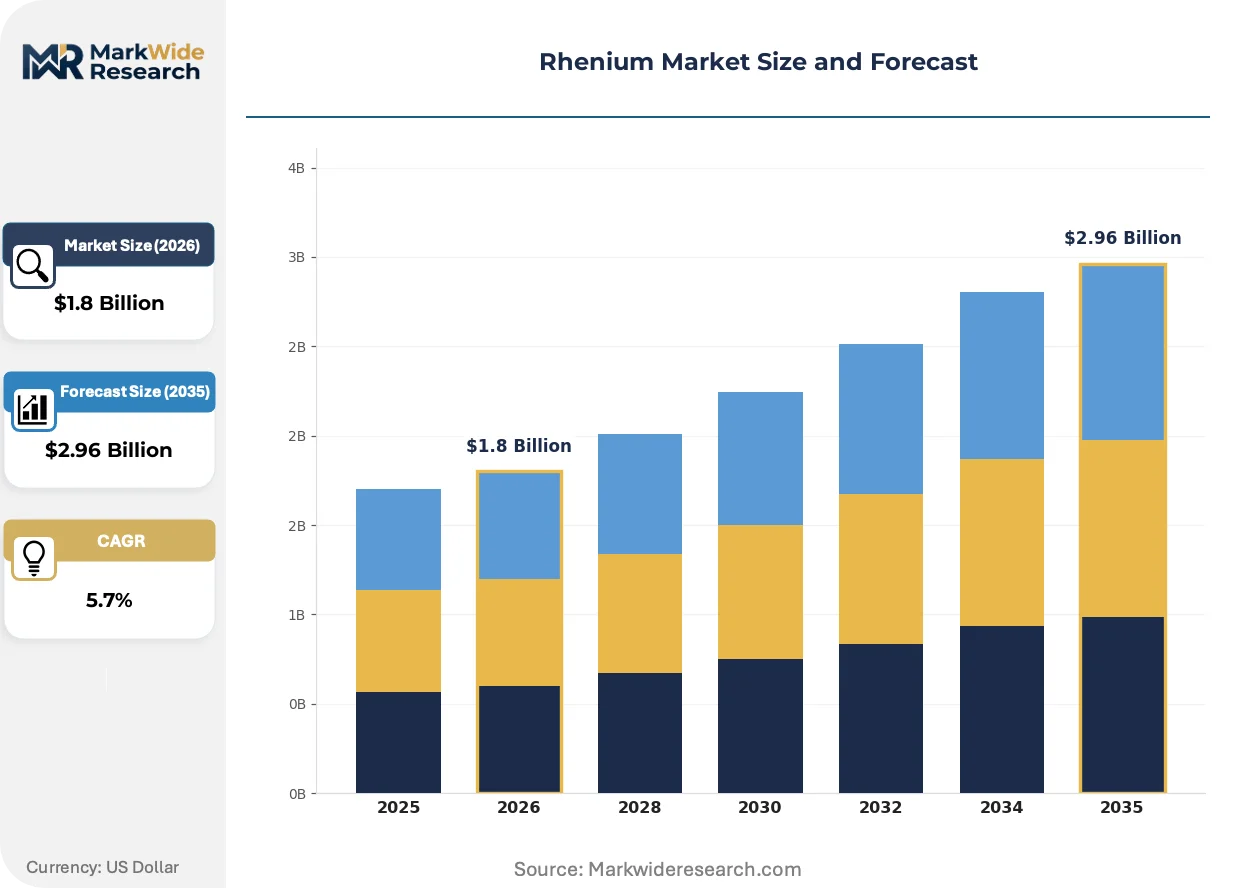
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rhenium Metal, Rhenium Alloys, Rhenium Compounds, Rhenium Powder End Use Industry: Aerospace, Electronics, Automotive, Chemical Processing Technology: Hydrometallurgy, Pyrometallurgy, Chemical Vapor Deposition, Superalloys Application: Turbine Engines, Catalysts, Thermocouples, Electrical Contacts |
| Companies Covered | American Elements, Umicore, Freeport-McMoRan, KAZ Minerals, Jiangxi Copper, MOLYMET S.A., Heraeus Holding, LS-Nikko, KGHM Polska Miedz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhenium Market Emerging Trajectories
Digital metallurgical tracking and process intensification are converging to compress qualification timelines while tightening purity verification standards across the value chain.
Additive manufacturing feedstock preparation is modularizing rhenium powder specifications for directed energy deposition systems. Aerospace maintenance, repair, and overhaul facilities are adopting these feedstocks for blade restoration rather than full replacement. The technology is modularizing repair economics by enabling localized superalloy rebuilding without foundry recasting.
EPA hazardous material disposal frameworks for spent catalyst waste are tightening manifest documentation and cradle-to-grave tracking obligations. Petrochemical refiners now face elevated compliance costs for rhenium-containing catalyst retirement. United States processors are responding by extending catalyst regeneration cycles and investing in on-site recovery capabilities.
Long-term offtake contracting is displacing spot market purchasing among superalloy foundries seeking supply security. Tier-one turbine engine manufacturers are consolidating supplier panels and demanding volume commitments with fixed-price escalators. This concentration is most visible in United States defense procurement channels where multi-year program funding enables decade-spanning metal agreements.
Rhenium Market Segmentation
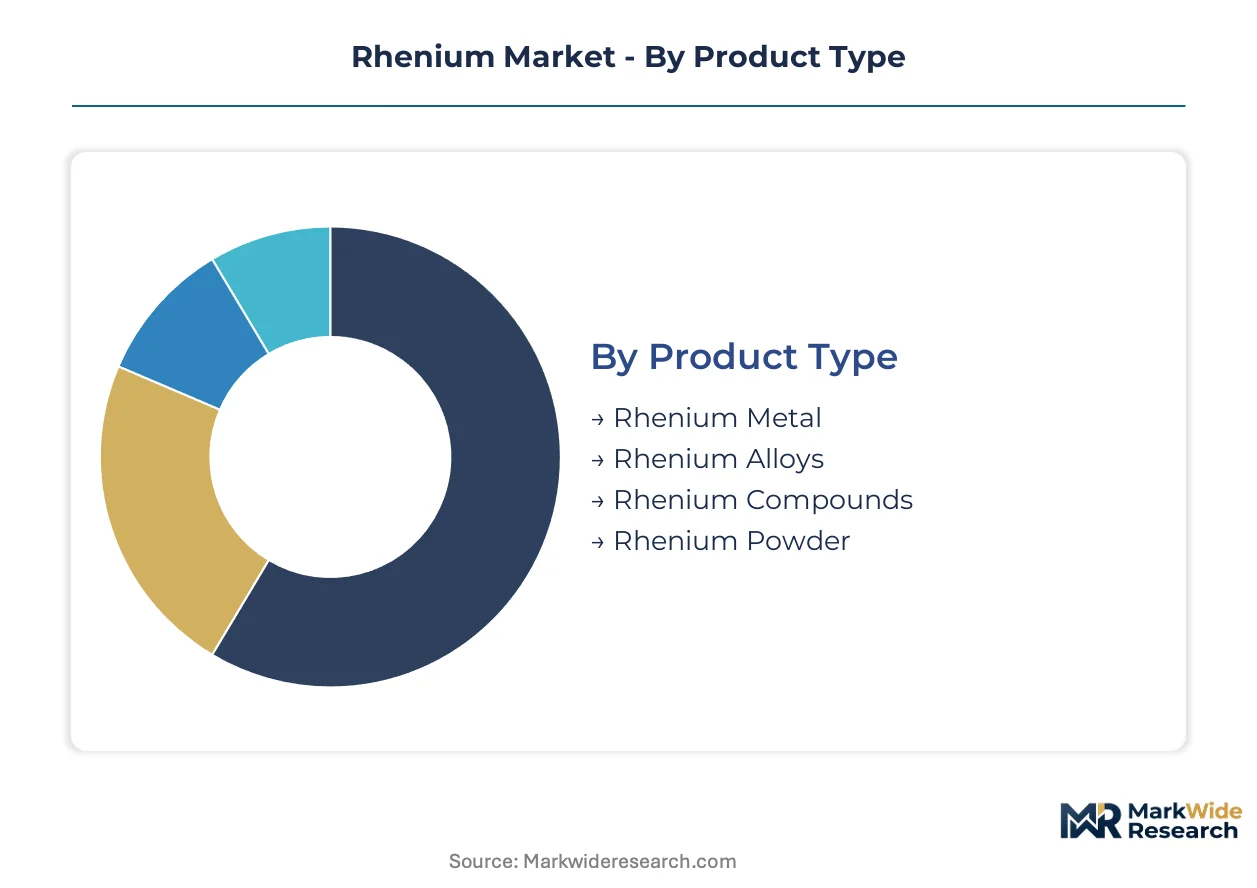
Rhenium procurement splits sharply between aerospace superalloy specifications demanding extreme purity and catalyst applications tolerating broader chemical variance. These divisions shape metallurgical processing investments, recycling economics, and regional trade flows across the value chain.
Product Type:
Purity thresholds and thermal performance requirements distinguish commercial grades, with aerospace specifications commanding premium positioning against industrial-grade alternatives.
- Rhenium Metal:Primary extraction yields high-purity ingots and pellets for single-crystal turbine blade casting. United States superalloy foundries anchor consumption through long-term offtake agreements tied to defense aerospace procurement cycles.
- Rhenium Alloys:Nickel-based superalloys incorporate three to six percent rhenium by weight to achieve creep resistance under sustained thermal stress. Next-generation propulsion systems from Pratt & Whitney and GE Aviation drive formulation advances in this segment.
- Rhenium Compounds:Petrochemical catalyst precursors including perrhenic acid and ammonium perrhenate support hydrocracking and reforming operations. REACH substance registration mandates accelerate formalized documentation across European processors.
- Rhenium Powder:Electrical contact manufacturing absorbs this mature, price-sensitive grade where platinum-group metal substitution pressures persist. Directed energy deposition systems are modularizing powder specifications for blade restoration applications.
Mature deployment sits with Rhenium Metal. Newer deployment is concentrated in Rhenium Powder for additive manufacturing feedstock preparation.
End Use Industry:
Heat tolerance requirements and regulatory compliance intensity vary dramatically across sectors, creating divergent procurement patterns and margin structures.
- Aerospace:Turbine engine manufacturers specify rhenium-bearing superalloys for single-crystal blade casting where thermal fatigue life determines airworthiness certification. FAA engine certification standards indirectly mandate rhenium content through alloy performance thresholds.
- Chemical Processing:Petrochemical refiners deploy rhenium catalysts for hydrocracking and catalytic reforming with regeneration cycles creating recoverable metal streams. EPA hazardous material disposal frameworks tighten manifest documentation for spent catalyst retirement.
- Electronics:Thermocouple and electrical contact applications consume lower-purity grades where cost sensitivity limits rhenium penetration against platinum-group alternatives.
- Automotive:Emerging interest in high-temperature sensor applications and specialized coating technologies remains exploratory with limited commercial scale.
Volume leadership belongs to Aerospace. Steepest expansion trajectory is emerging in Chemical Processing through closed-loop catalyst recovery infrastructure.
Technology:
Process selection determines recovery economics, environmental compliance burden, and final product purity achievable from molybdenum-copper ore byproduct streams.
- Hydrometallurgy:Solvent extraction and ion exchange circuits recover rhenium from molybdenum roaster off-gas and leach solutions. Freeport-McMoRan leverages integrated byproduct streams to sustain cost advantages in primary extraction.
- Superalloys:Vacuum induction melting and directional solidification processes incorporate rhenium into nickel-based formulations for single-crystal turbine blade production. Extended thermal fatigue testing under FAA protocols delays new formulation commercialization.
- Pyrometallurgy:Smelting and converting operations at South American concentrators feed hydrometallurgical refineries with intermediate products.
- Chemical Vapor Deposition:Thin-film coating applications for specialized electronics and wear-resistant surfaces remain niche with limited throughput scale.
Established capacity centers on Hydrometallurgy. Technology investment is flowing toward Superalloys as single-crystal specifications tighten.
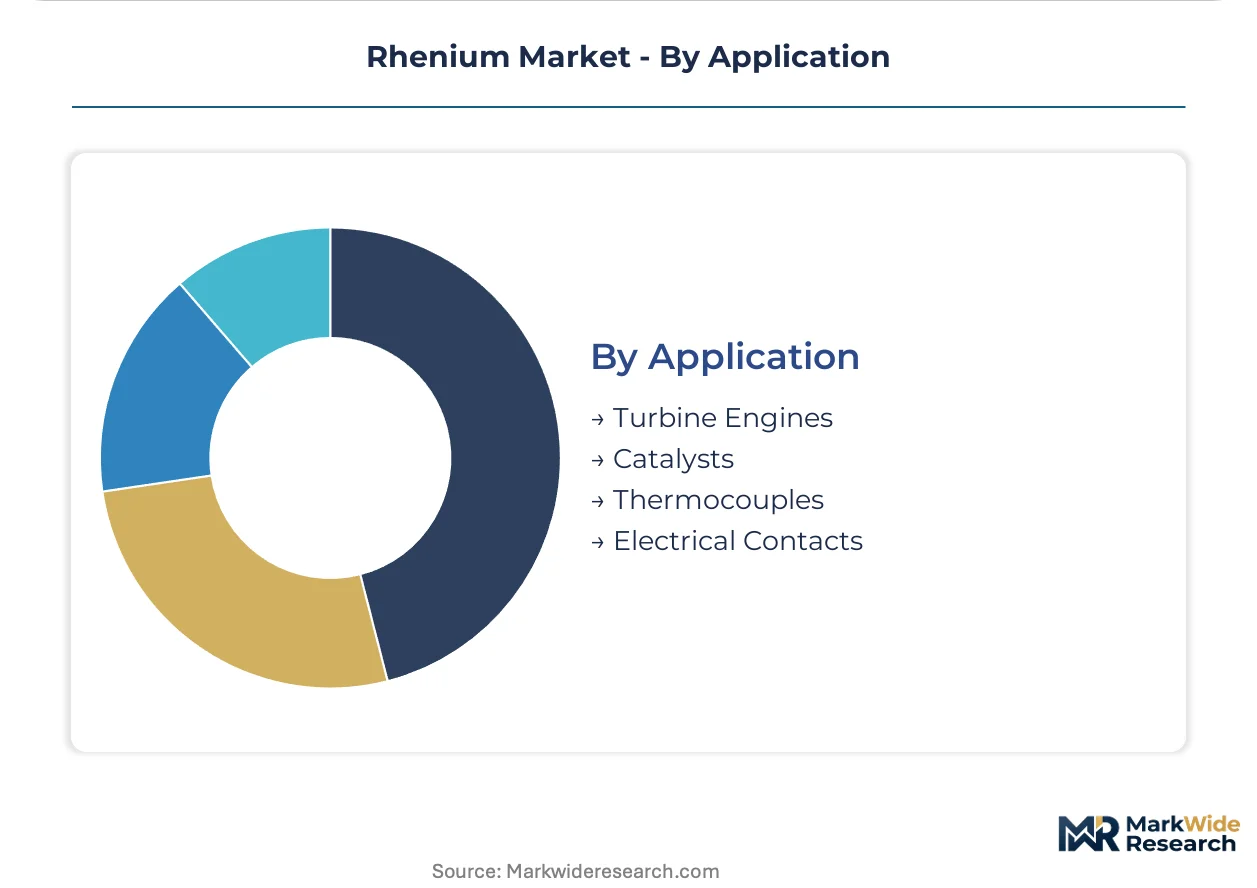
Application:
Functional performance requirements and replacement economics shape whether rhenium commands premium pricing or faces substitution pressure.
- Turbine Engines:Single-crystal blade casting represents the dominant value application where rhenium additions deliver unmatched creep resistance. United States defense aerospace programs anchor premium metal consumption through multi-year program funding.
- Catalysts:Petrochemical hydrocracking and reforming operations consume rhenium in alumina-supported configurations with regeneration extending effective service life. On-site recovery capabilities are displacing third-party reclamation.
- Thermocouples:Tungsten-rhenium and platinum-rhenium thermocouples serve high-temperature measurement applications in industrial furnaces and aerospace test facilities.
- Electrical Contacts:Rhenium-tungsten and rhenium-molybdenum contacts for high-duty switching face persistent platinum-group metal substitution in price-sensitive segments.
Revenue concentration rests with Turbine Engines. Application development is accelerating fastest in Catalysts through regeneration cycle optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix anchors North American rhenium consumption through superalloy foundry clusters serving Pratt & Whitney and GE Aviation engine programs. Domestic defense aerospace procurement channels concentrate demand in this corridor.
United States
Single-crystal turbine blade casting for next-generation propulsion systems drives rhenium demand at Connecticut and Ohio superalloy foundries. FAA engine certification standards indirectly mandate rhenium content through alloy performance thresholds. Defense aerospace programs in the Southeast anchor multi-year metal offtake agreements.
Chile
Primary rhenium extraction from molybdenum-copper sulfide ore processing dominates South American supply. MOLYMET S.A. operates refining capacity that feeds global concentrate flows. Antofagasta and Santiago smelter partnerships extend geographic reach through long-term supply arrangements.
Germany
REACH substance registration mandates accelerate formalized rhenium compound documentation across European petrochemical processors. EU Green Deal emissions standards tighten material traceability requirements. Industrial clusters in North Rhine-Westphalia host closed-loop recycling infrastructure.
China
MIIT dual carbon goals and GB standards for critical mineral stockpiling redirect Asian rhenium flows toward domestic superalloy production. Jiangxi Copper processes concentrates from regional molybdenum operations. Yangtze River Delta aerospace manufacturers expand captive rhenium consumption.
Japan
METI industrial policy supports high-temperature alloy development for aerospace and power generation applications. Kanto region precision foundries serve domestic turbine engine repair and overhaul demand. Thermocouple manufacturing in Osaka consumes lower-purity grades for industrial furnace instrumentation.
Rhenium Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the rhenium value chain. Integrated mining conglomerates with captive molybdenum-rhenium byproduct streams hold structural cost advantages in primary extraction. Independent refiners and specialty metal traders occupy mid-stream positions dependent on concentrate sourcing relationships. Strategic moves concentrate on long-term offtake contracting and closed-loop recycling partnerships.
Among diversified mining conglomerates, Freeport-McMoRan and KAZ Minerals represent integrated extraction archetypes with captive byproduct recovery economics. Umicore exemplifies the closed-loop recycling tier through European catalyst reclamation infrastructure. MOLYMET S.A. anchors South American refining capacity with geographic concentration in Chilean smelter networks.
| Leading Market Players |
|---|
| American Elements |
| Umicore |
| Freeport-McMoRan |
| KAZ Minerals |
| Jiangxi Copper |
| MOLYMET S.A. |
| Heraeus Holding |
| LS-Nikko |
| KGHM Polska Miedz |
| Others |
Supply Flow & Price Mechanics
Captive molybdenum-rhenium byproduct recovery at integrated mining conglomerates anchors both supply positioning and pricing power, with Freeport-McMoRan's integrated streams sustaining cost advantages that independent refiners cannot replicate. This structural asymmetry concentrates margin capture upstream while forcing mid-stream processors into concentrate sourcing dependencies that amplify price volatility during supply disruptions.
Pricing Analysis
Yield-linked pricing anchors aerospace superalloy contracts, with rhenium metal premiums tied directly to turbine blade thermal fatigue performance thresholds certified under FAA protocols. Three-tier pricing structure across aerospace-grade ingots, catalyst-grade compounds, and electrical contact powder reflects purity certification levels and volume commitment scales. Cost compression in electrical contact powder is intensifying because platinum-group metal substitution pressures persist in mature switching applications. Catalyst processors exhibit highest price sensitivity due to regeneration cycle economics, while single-crystal blade foundries accept premium positioning for certified traceability.
Supply Chain Analysis
Reverse-logistics catalyst regeneration flows from European petrochemical plants are displacing primary extraction volumes, with Umicore's closed-loop infrastructure capturing recoverable rhenium streams that bypass Chile-China concentrate chokepoints. Primary supply concentrates in Chile, the United States, and Kazakhstan, with MOLYMET S.A. and KAZ Minerals feeding global hydrometallurgical refineries. Molybdenum roaster off-gas, copper sulfide leach solutions, and spent catalyst residues constitute the three critical input streams. Single-source vulnerability at South American smelter partnerships creates structural exposure to logistics disruption. Distribution runs through long-term offtake contracts rather than spot markets, with tier-one turbine manufacturers consolidating supplier panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive byproduct recovery and closed-loop recycling infrastructure constitutes the decisive competitive race, with upstream control over molybdenum-rhenium ore streams and downstream catalyst regeneration capabilities representing the twin levers separating price-takers from margin capturers.
For Market Incumbents: Anchor supply security through multi-year offtake extensions with United States defense aerospace programs and accelerate closed-loop recycling partnerships with European petrochemical refiners facing EPA and REACH disposal compliance burdens. Threats from hydrometallurgical solvent extraction advances at low-grade concentrate processors demand capacity investments in process intensification technologies. Certification investment in EU Green Deal traceability systems represents the critical defensive lever. For New Entrants and Emerging Players: Capture white-space in additive manufacturing feedstock preparation for directed energy deposition blade restoration systems, where aerospace MRO facilities are modularizing repair economics away from foundry recasting. The penetrable segment sits with rhenium powder specifications for localized superalloy rebuilding. Go-to-market positioning through metallurgical tracking software partnerships offers differentiation against established powder suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated mining conglomerates seeking captive byproduct diversification or specialty materials platforms building circular economy credentials. Long-term viability hinges on exposure to next-generation propulsion system qualification timelines rather than spot metal trading. The signal to watch is FAA engine certification protocol compression accelerating single-crystal blade formulation commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molybdenum Concentrate Supply | Freeport-McMoRan's captive ore streams eliminate third-party concentrate dependency and sustain extraction cost advantages. |
| Closed-Loop Catalyst Recovery Infrastructure | Umicore's European reclamation networks bypass primary extraction bottlenecks while satisfying REACH substance registration mandates. |
| Long-Term Defense Aerospace Offtake Agreements | United States superalloy foundries anchor premium metal consumption through multi-year program funding cycles. |
| Additive Manufacturing Feedstock Certification | Directed energy deposition specifications for blade restoration create new powder demand outside traditional foundry channels. |
| Hydrometallurgical Process Intensification Investment | Advanced solvent extraction technologies unlock rhenium recovery from previously uneconomic low-grade molybdenum concentrates. |
Methodological Framework
Multi-period observation of molybdenum roaster throughput, superalloy foundry order backlogs, and catalyst regeneration cycle frequencies anchored the trend analysis, supplemented by interviews with plant managers at sulfide ore processing facilities, procurement leads at turbine engine OEMs, technical R&D directors in petrochemical catalyst divisions, and distribution channel partners in specialty metals trading. Secondary validation drew from SEC 10-K filings by integrated mining conglomerates, ECHA REACH substance registration databases, FAA engine certification bulletins, and customs trade data tracking concentrate flows from Chile and Kazakhstan. Bottom-up volume modeling triangulated against top-down expenditure analysis across aerospace and chemical processing end-uses.
Input-output matrices mapped rhenium flows from molybdenum-copper ore extraction through hydrometallurgical refining to final superalloy casting and catalyst formulation, with segmentation dimensions spanning product type, end-use industry, and regional production hub. CAGRs were derived from regression analysis against aerospace procurement cycle indicators and petrochemical capacity expansion plans. Industry-specific forecast inputs included single-crystal turbine blade qualification timelines under FAA protocols and MIIT dual carbon policy implementation trajectories affecting Chinese domestic superalloy production.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to molybdenum-copper ore grade degradation, REACH registration compliance cost escalation, and platinum-group metal substitution breakthroughs in electrical contact applications. Forecasts reflect documented assumptions about defense aerospace program funding continuity and catalyst regeneration technology diffusion rates. Practitioners should monitor FAA certification timeline compression announcements, Chilean smelter partnership restructurings, and European traceability system technical capacity buildouts for early signals of supply-demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market