
 Tellurium Market | 2026-2036
Tellurium Market Size, Share, and Industry Trends Forecast 2026-2036
Tellurium Market Analysis
Capital-intensity divergence between electrolytic refining and solvent-extraction specialists is collapsing as tellurium recovery from copper anode slimes becomes the dominant cost benchmark. Aurubis AG leverages its European smelter network to sustain captive tellurium output from integrated copper refining. JX Nippon Mining & Metals Corporation anchors its position through advanced hydrometallurgical separation technology developed at Japanese refining complexes. Teck Resources Limited competes via bulk concentrate handling capacity at Canadian base-metal operations.
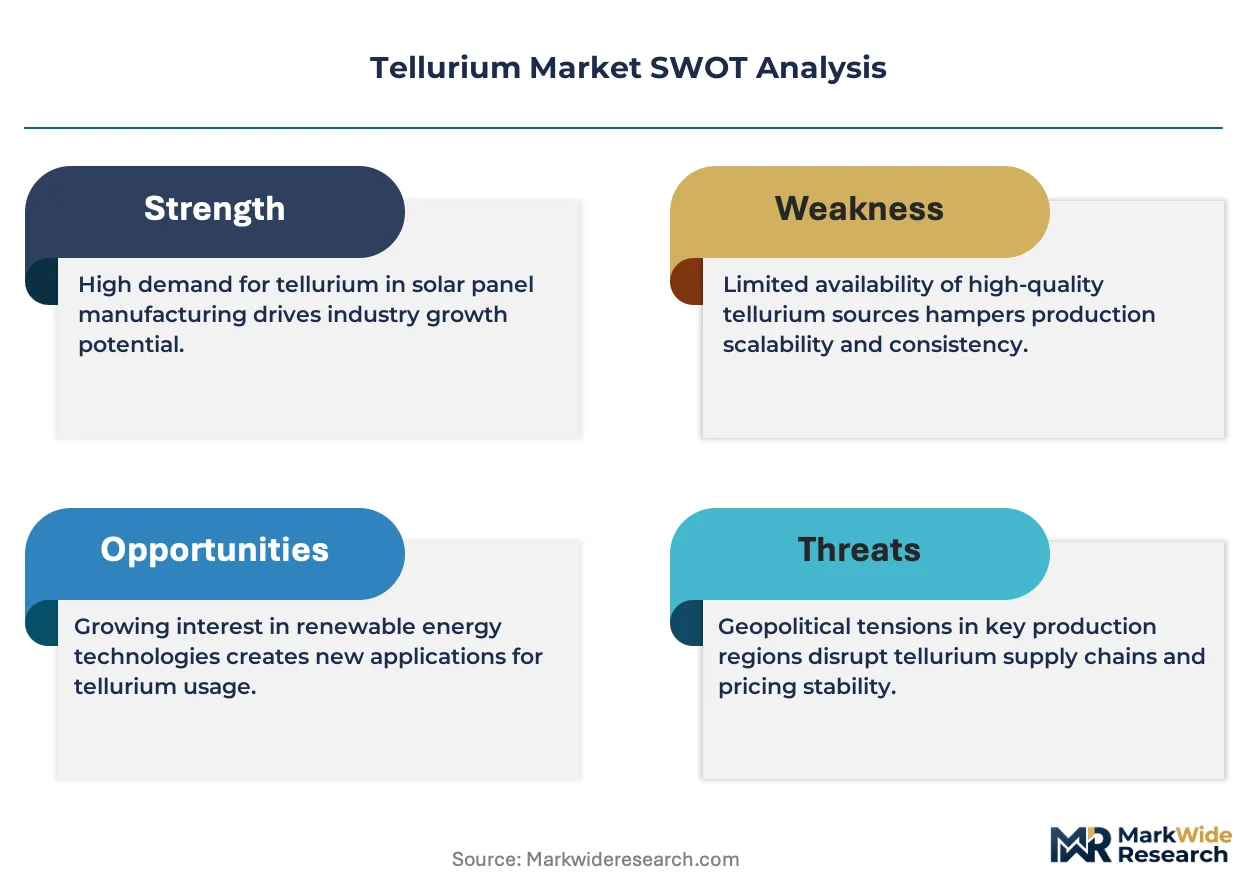
Tellurium is a brittle, silvery-white metalloid with atomic number 52, typically recovered as a byproduct of copper and lead refining; it melts at 449.5 degrees Celsius and exhibits semiconducting properties that enable infrared photodetection and thermoelectric conversion. Primary commercial purpose centers on alloying with cadmium for photovoltaic absorber layers and with bismuth or antimony for thermoelectric modules. Telluride compounds now lead product-type demand as cadmium telluride solar cell manufacturing scales in North American and Asian module factories. Semiconductor-grade metallic tellurium sustains premium pricing due to stringent purity thresholds for infrared optical coating applications. Photovoltaics application segments are attracting the fastest capacity investments, while optical coatings retain concentrated margin pools from defense and aerospace qualification requirements.
The EPA regulates tellurium compound emissions under the Toxic Substances Control Act, while REACH mandates supply chain registration for European importers of tellurium dioxide and alloys. China's MEE enforces discharge limits on selenium-tellurium separation facilities under national pollutant standards. Japan's METI coordinates strategic stockpiling of refined tellurium through designated rare-metal reserves. Stakeholders must monitor how critical raw materials legislation in multiple jurisdictions reshapes offtake contracting terms and refinery investment timelines.
Market Dynamics
Cadmium telluride photovoltaic manufacturing is compressing traditional tellurium offtake patterns as thin-film solar deployment accelerates, forcing refiners to reconfigure copper anode slime processing priorities.
Growth Catalysts
- EU Green Deal Critical Raw Materials classification:Mandatory supply chain disclosure requirements for European importers of tellurium dioxide and alloys are accelerating traceability investments across the value chain.
- Thin-film solar deployment:Cadmium telluride photovoltaic manufacturers now account for the fastest-growing buyer segment as module factories scale in North America and Asia.
- Japan and South Korea refining clusters:East Asian semiconductor-grade purification capabilities are anchoring regional supply security and concentrating demand visibility.
Market Restraints
- Copper anode slime dependency:Tellurium recovery remains tethered to base-metal mining economics, constraining primary supply expansion independent of copper demand cycles.
- Chinese smelter concentration:Dual carbon goals and MEE discharge limits on selenium-tellurium separation facilities are tightening environmental compliance costs for dominant producers.
- Selenium-tellurium separation technical ceiling:Hydrometallurgical purification yields plateau at semiconductor-grade thresholds, limiting high-purity output scaling.
Strategic Opportunities
- Japan METI strategic stockpiling:Designated rare-metal reserves create offtake certainty for refiners meeting national purity standards.
- Thermoelectric module convergence:Bismuth telluride and antimony telluride compounds are opening adjacent demand channels beyond photovoltaics.
- Infrared optical coating qualification:Defense and aerospace certification requirements sustain premium pricing pools for ultra-high-purity metallic tellurium.
Industry Challenges
- Semiconductor-grade purification talent scarcity:Advanced hydrometallurgical separation expertise concentrates at Japanese refining complexes, limiting workforce mobility.
- REACH registration timeline compression:European importers face supply chain registration deadlines for tellurium dioxide that compress contracting windows.
- Copper smelter feedstock reconfiguration:Anode slime processing retrofits require capital deployment that conflicts with base-metal margin pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tellurium Market |
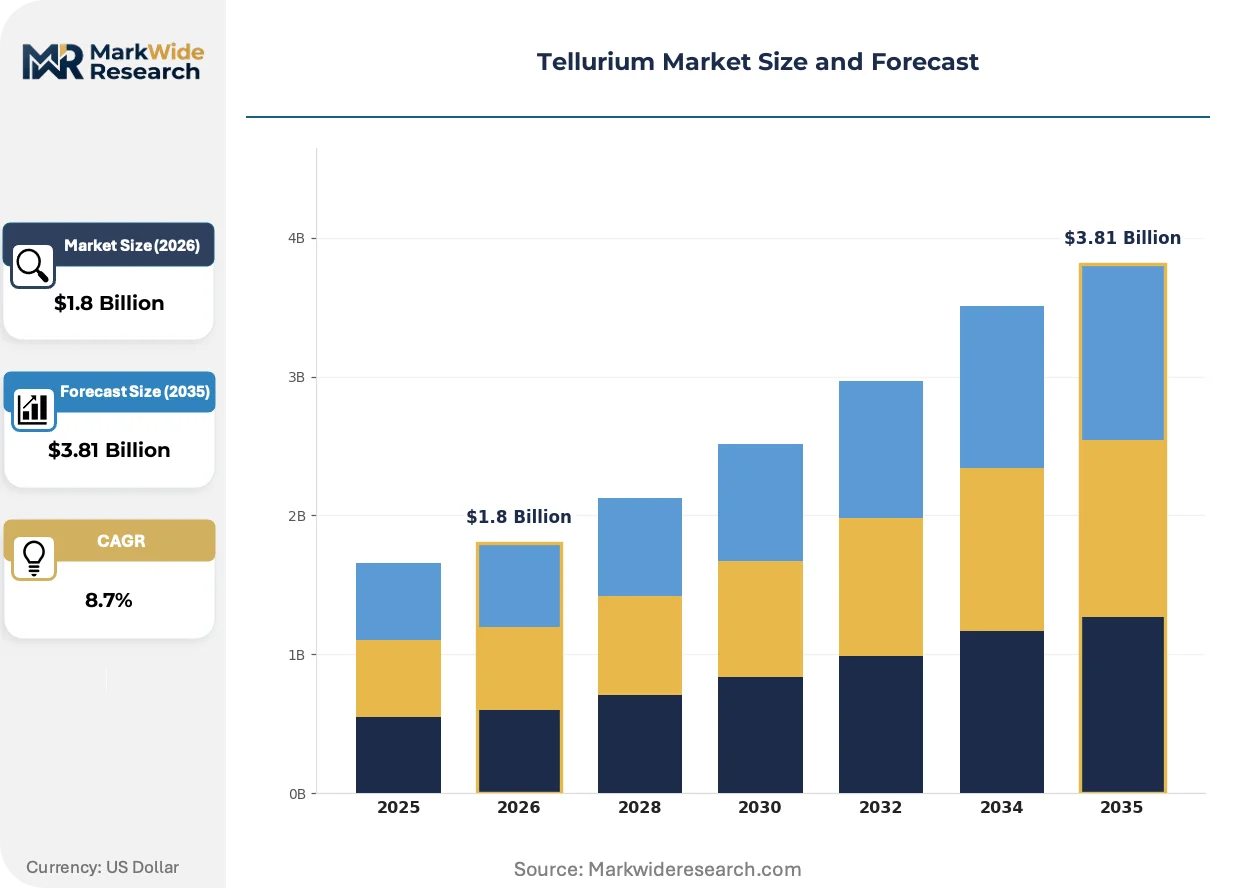
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Tellurium, Tellurium Dioxide, Telluride Compounds, Tellurium Alloys End User: Solar Cells, Electronics, Metallurgy, Thermoelectric Devices Application: Semiconductors, Photovoltaics, Optical Coatings, Electronics Manufacturing Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | Mitsubishi Materials Corporation, JX Nippon Mining & Metals Corporation, Aurubis AG, Teck Resources Limited, Umicore, Rio Tinto, Zhuzhou Keneng New Material, Vital Materials, 5N Plus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tellurium Market Emerging Trajectories
Refining technology and regulatory disclosure mandates are actively restructuring how tellurium moves from copper byproduct to qualified solar and semiconductor feedstock.
Zone-refined tellurium ingot production is supplanting conventional electrolytic refining for photovoltaic-grade material. Cadmium telluride solar cell manufacturers in North American module factories are adopting zone-refined feedstock at accelerating rates. This technology shift is compressing electrolytic specialists' margin structures while elevating purification technology licensors.
REACH supply chain registration mandates for European importers of tellurium dioxide and alloys are forcing documentation system investments. The regulation requires full substance dossiers that extend contracting timelines and favor incumbent refiners with established compliance infrastructure. Cadmium telluride photovoltaic manufacturers sourcing for EU module assembly are prioritizing pre-registered suppliers.
Long-term offtake contracting is displacing spot market purchasing among cadmium telluride solar cell manufacturers. Thin-film solar developers in North America are locking multi-year supply agreements directly with copper smelter affiliates. This procurement evolution is visible most acutely in module factories securing tellurium volumes ahead of capacity expansion commissioning.
Tellurium Market Segmentation
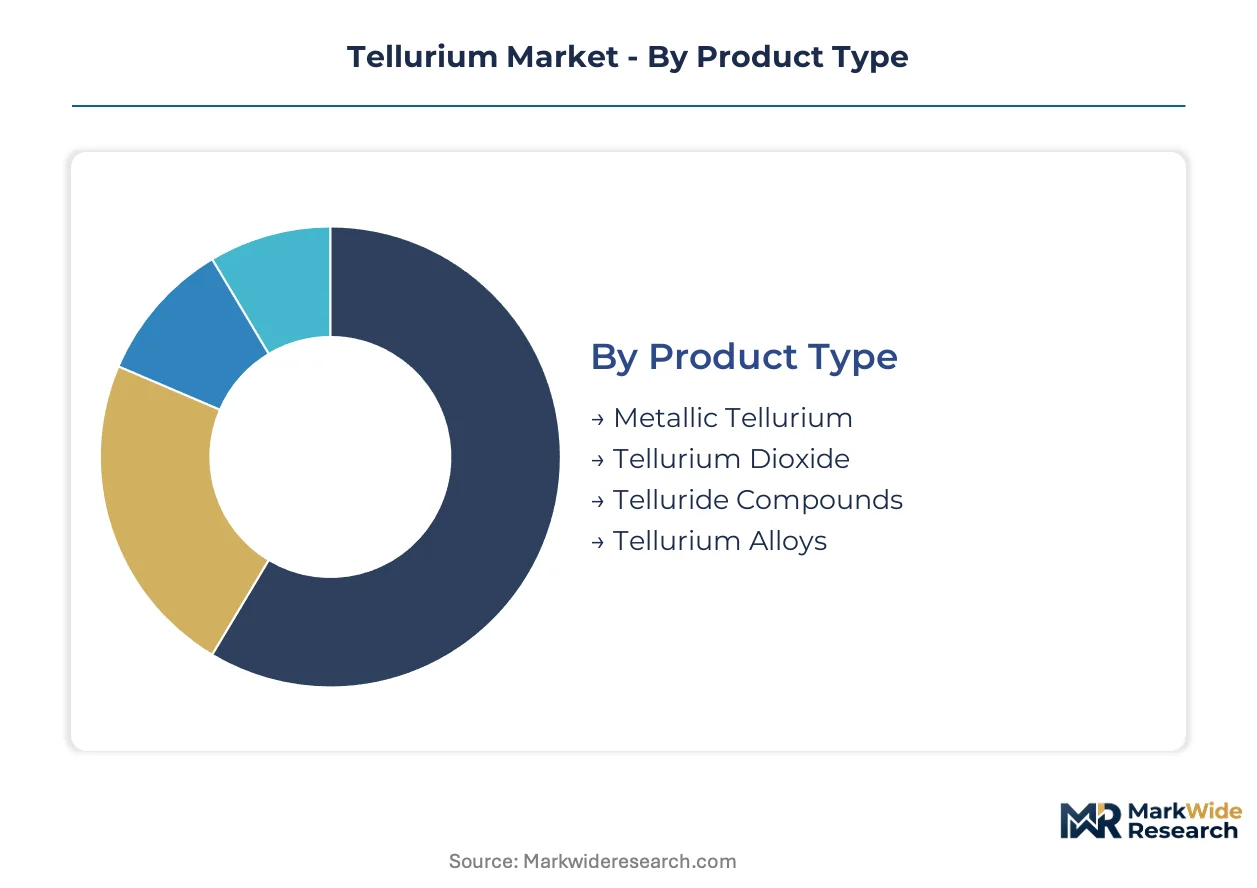
Tellurium's byproduct recovery economics fragment supply across four distinct chemical forms, each facing divergent purity requirements and end-use qualification barriers. Segmentation clarity determines which product streams merit capital-intensive purification investments versus commodity alloying sales.
Product Type:
Substitution pressure from zone-refined alternatives is compressing margins for traditional electrolytic grades, forcing product-level differentiation around purification methodology.
- Telluride Compounds:Cadmium telluride and bismuth telluride represent the dominant molecular configurations for photovoltaic absorber layers and thermoelectric conversion modules. North American thin-film solar factories are locking multi-year offtake agreements directly with copper smelter affiliates to secure these volumes ahead of capacity commissioning.
- Metallic Tellurium:Refined ingot and powder forms span semiconductor-grade specifications down to commercial-grade alloying feedstock. Japanese refining complexes at JX Nippon Mining & Metals concentrate advanced hydrometallurgical separation expertise for infrared optical coating applications that sustain premium pricing pools.
- Tellurium Dioxide:White crystalline oxide serves as precursor material for specialty glass and catalyst manufacturing. REACH registration mandates for European importers are forcing documentation system investments that extend contracting timelines.
- Tellurium Alloys:Binary and ternary combinations with lead, copper, or stainless steel enhance machinability and corrosion resistance. Metallurgical applications in free-machining steels face demand headwinds from alternative additive technologies.
Telluride compounds retain volume leadership; metallic tellurium holds the steepest expansion curve as zone-refined purification displaces electrolytic methods.
End User:
Cost tier stratification separates qualified solar and semiconductor buyers from price-sensitive metallurgical processors.
- Solar Cells:Cadmium telluride photovoltaic manufacturers constitute the fastest-growing buyer segment as module factories scale production across North America and Asia. Long-term offtake contracting is displacing spot market purchasing among developers securing volumes ahead of expansion commissioning.
- Thermoelectric Devices:Bismuth telluride and antimony telluride compounds enable solid-state refrigeration and waste-heat recovery systems. Japan's METI coordinates strategic stockpiling of refined material through designated rare-metal reserves that create offtake certainty for qualified refiners.
- Electronics:Infrared photodetection and radiation shielding applications demand stringent purity thresholds. Defense and aerospace certification requirements sustain concentrated margin pools for ultra-high-purity metallic tellurium.
- Metallurgy:Free-machining steel additives and lead alloying represent legacy demand channels facing substitution from alternative metallurgical technologies. Copper anode slime dependency constrains primary supply expansion independent of these demand cycles.
Solar cells command the dominant procurement volume; thermoelectric devices are gaining share fastest as solid-state cooling applications proliferate.
Application:
Application-level margin pools concentrate where qualification requirements create supply scarcity.
- Photovoltaics:Cadmium telluride absorber layers in thin-film solar modules absorb the majority of refined telluride compound output. Zone-refined feedstock adoption is compressing electrolytic specialists' margin structures while elevating purification technology licensors.
- Optical Coatings:Infrared-transparent thin films for thermal imaging and aerospace systems require 6N+ purity metallic tellurium. Semiconductor-grade purification talent scarcity at Japanese refining complexes limits workforce mobility and output scaling.
- Semiconductors:Thermoelectric cooling substrates and radiation detectors utilize both metallic and compound forms. China's MEE discharge limits on selenium-tellurium separation facilities tighten environmental compliance costs for dominant producers serving this channel.
- Electronics Manufacturing:Phase-change memory alloys and rewritable optical media represent emerging applications with unproven volume trajectories.
Photovoltaics absorbs the largest volume share; optical coatings sustain the highest margin per kilogram.
Distribution Channel:
Channel selection reflects customer scale and qualification burden.
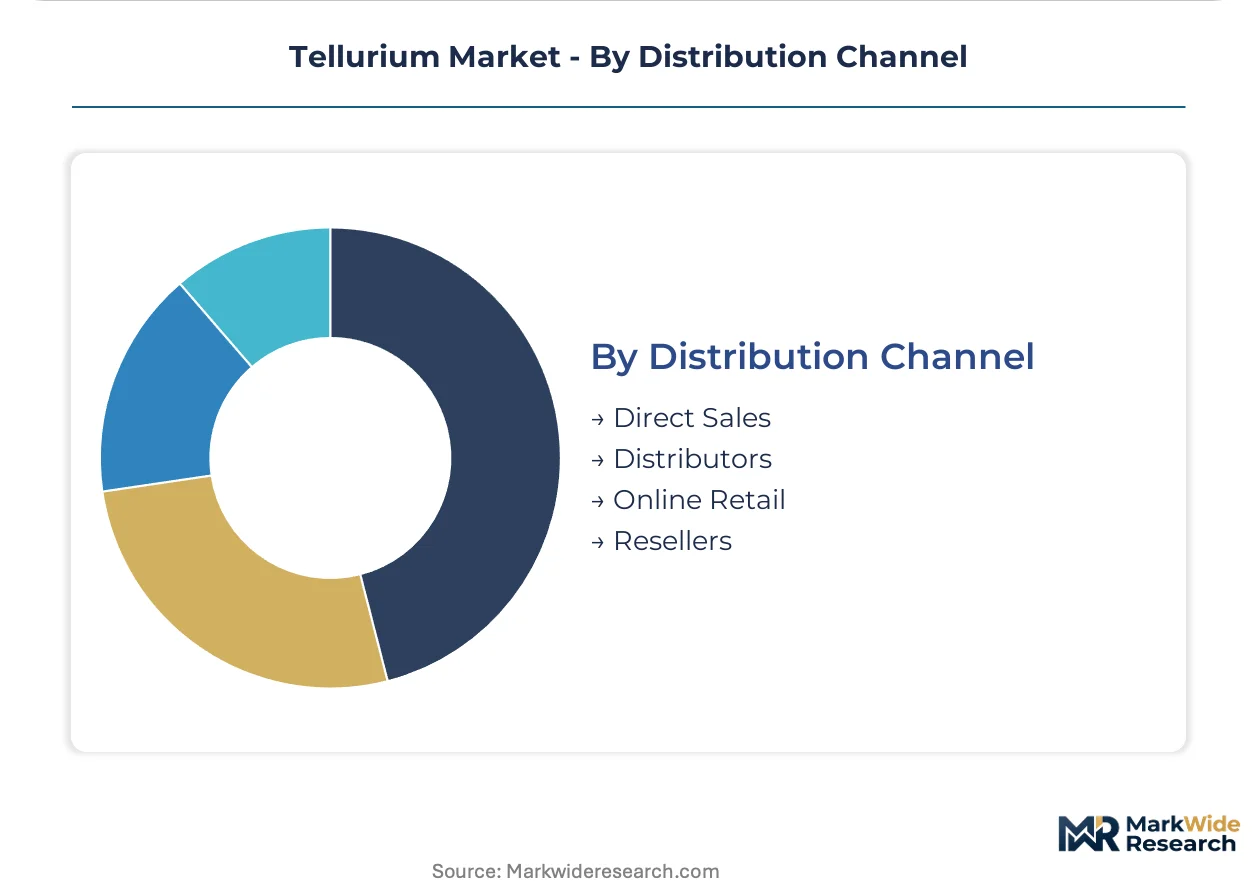
- Direct Sales:Long-term supply agreements between copper smelter affiliates and cadmium telluride solar cell manufacturers dominate volume flows. Thin-film solar developers in North America are locking multi-year contracts ahead of capacity expansion commissioning.
- Distributors:Regional chemical and specialty metal distributors serve smaller-scale electronics and metallurgical processors. REACH supply chain registration mandates favor incumbent distributors with established compliance infrastructure.
- Resellers:Secondary market participants handle spot volumes and inventory redistribution for qualified material.
- Online Retail:Limited to laboratory quantities and research-grade specifications with minimal commercial relevance.
Direct sales channels retain volume leadership; distributor networks are expanding fastest as mid-scale buyers seek pre-registered European suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers exhibit the highest price elasticity as domestic smelter output fluctuates under environmental compliance costs, while Japanese semiconductor-grade purchasers maintain inelastic demand through METI-coordinated strategic reserves.
China
Domestic cadmium telluride photovoltaic manufacturing scales rapidly in Jiangsu and Zhejiang provinces. MEE discharge limits on selenium-tellurium separation facilities tighten environmental compliance costs for dominant producers. The Yangtze River Delta refining cluster concentrates hydrometallurgical capacity serving both solar and electronics sectors.
Japan
Infrared optical coating applications and thermoelectric device manufacturing anchor demand for 6N+ purity metallic tellurium. METI coordinates strategic stockpiling through designated rare-metal reserves that create offtake certainty for qualified refiners. The Kanto region around Tokyo hosts JX Nippon Mining & Metals Corporation's advanced separation technology complexes.
United States
Thin-film solar developers in Ohio and Colorado are locking multi-year supply agreements directly with copper smelter affiliates. EPA regulations under the Toxic Substances Control Act govern tellurium compound emissions from refining operations. The Southwest region concentrates cadmium telluride module factory capacity scaling ahead of domestic content requirements.
Germany
REACH supply chain registration mandates for tellurium dioxide importers extend contracting timelines and favor established compliance infrastructure. Aurubis AG leverages its European smelter network to sustain captive tellurium output from integrated copper refining. The Hamburg refining complex anchors regional supply security for photovoltaic and thermoelectric buyers.
South Korea
Semiconductor-grade purification capabilities in Gyeonggi Province concentrate demand visibility for electronics and optical coating applications. National industrial policy supports rare metal stockpiling programs modeled on Japanese strategic reserves. The Seoul Capital Area hosts refining clusters serving both domestic solar cell manufacturing and export markets.
Tellurium Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with copper smelter affiliates controlling captive byproduct flows while independent refiners compete on purification technology. The market structure concentrates around base-metal mining economics that constrain tellurium supply expansion independent of copper demand cycles. Three archetypes dominate: integrated copper refiners with captive slime processing, independent hydrometallurgical specialists, and photovoltaic-integrated compound manufacturers. Competitive moves center on long-term offtake contracting with solar developers and zone-refining technology licensing to displace electrolytic methods.
Among integrated copper refiners, Aurubis AG exemplifies the European smelter-network archetype, while JX Nippon Mining & Metals Corporation occupies a position within the advanced hydrometallurgical separation tier. Teck Resources Limited represents the bulk concentrate-handling capacity archetype at Canadian base-metal operations. These three companies anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Mitsubishi Materials Corporation |
| JX Nippon Mining & Metals Corporation |
| Aurubis AG |
| Teck Resources Limited |
| Umicore |
| Rio Tinto |
| Zhuzhou Keneng New Material |
| Vital Materials |
| 5N Plus |
| Others |
Supply Flow & Price Mechanics
Multi-month lead times for semiconductor-grade tellurium ingots concentrate pricing power with Japanese and South Korean refiners possessing zone-refining capabilities, while copper anode slime availability constrains volume expansion regardless of cadmium telluride solar manufacturer procurement urgency.
Pricing Analysis
Extended service contracts for zone-refining technology licensing now capture lifetime value exceeding raw material sales. Contract-based long-term offtake dominates cadmium telluride photovoltaic procurement, with price differentiation driven by 6N+ purity certification and volume scale commitments. Cost compression in electrolytic grades is intensifying because zone-refined feedstock adoption accelerates in North American module factories. Metallurgical buyers exhibit highest price sensitivity; defense-qualified optical coating purchasers remain least elastic.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan container terminals fluctuate with selenium-tellurium separation facility discharge compliance timelines. Primary supply concentrates in China, Japan, and Canada as copper anode slime processing anchors extraction economics. Raw material flows draw from copper concentrate imports, sulfuric acid leaching reagents, and cadmium metal for compound synthesis. Single-source vulnerability persists at Japanese hydrometallurgical purification complexes. Distribution runs through direct sales agreements between copper smelter affiliates and thin-film solar developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cadmium telluride photovoltaic manufacturing is disrupting traditional tellurium offtake patterns as thin-film solar deployment accelerates, with EU Green Deal critical raw materials classification mandating supply chain disclosure that reconfigures refiner-customer contracting.
For Market Incumbents: Shield margin position by securing backward integration into copper anode slime processing at European smelter networks before REACH registration deadlines compress qualified supplier pools. Accelerate zone-refining capacity licensing to capture technology royalties as electrolytic refining margins erode.
For New Entrants and Emerging Players: Anchor in thermoelectric module manufacturing for solid-state cooling applications, where bismuth telluride compound demand outpaces established purification capacity. Target South Korean rare metal stockpiling programs as the most penetrable procurement channel. Pursue joint development agreements with infrared optical coating qualification labs to bypass semiconductor-grade talent scarcity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hydrometallurgical separation technology licensing as zone-refining equipment standardizes. Long-term viability favors acquiring advanced purification specialists with established METI reserve qualification rather than greenfield copper slime processing investments. Watch cadmium telluride solar cell manufacturer vertical integration announcements as the signal for refiner margin compression inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Zone-Refining Technology Licensing | JX Nippon Mining & Metals leverages advanced separation expertise to capture recurring royalty streams from North American solar feedstock producers. |
| Long-term Supply Agreement | Thin-film solar developers in Ohio and Colorado lock multi-year tellurium volumes directly with copper smelter affiliates ahead of capacity commissioning. |
| Backward Integration into Anode Slime Processing | Aurubis AG sustains captive tellurium output from integrated European copper refining networks under tightening REACH disclosure mandates. |
| Strategic Stockpiling Program Participation | Qualified refiners secure offtake certainty through Japan METI and South Korean national rare-metal reserve designations. |
| Green Manufacturing Transition | Chinese producers face MEE discharge limit compliance costs that reshape selenium-tellurium separation facility economics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with copper smelter technical directors, cadmium telluride solar cell procurement managers, semiconductor-grade refinery plant engineers, and rare metal strategic reserve coordinators. Secondary validation drew from customs trade data, EPA Toxic Substances Control Act filings, ECHA REACH registration databases, and METI rare metal stockpile disclosures. Bottom-up volume modeling triangulated against top-down copper anode slime generation estimates.
Across the analysis window, the forecasting framework modeled product type segmentation by purification methodology, end user segmentation by qualification tier, and application segmentation by margin pool concentration. CAGRs were derived from weighted capacity expansion announcements and offtake contracting velocity. Key inputs included thin-film solar deployment pipelines, zone-refining technology adoption curves, and critical raw materials legislation implementation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained copper mining economics and cadmium telluride photovoltaic manufacturing scale-up; material deviation in base-metal demand cycles or thin-film solar technology substitution would warrant model refresh. Specific risks include selenium-tellurium separation yield plateaus, semiconductor-grade purification talent scarcity, and REACH registration timeline compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
LED Materials Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Quartz Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Synthetic Single Crystal Diamond Market