
 Terbium Oxide Market | 2026-2036
Terbium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Terbium Oxide Market Outlook
China's rare earth refining expansion is rewriting terbium oxide availability assumptions for non-Chinese downstream consumers. Lynas Rare Earths operates the only significant ex-China separation capacity at its Malaysian facility, positioning the company as a strategic alternative for Western defense and clean technology supply chains. MP Materials Corp. leverages its Mountain Pass, California, mining complex to sustain a fully integrated domestic feedstock pipeline once its Texas separation facility reaches commercial operation. Energy Fuels Inc. anchors North American rare earth recovery through its Utah uranium mill's emerging rare earth oxide circuit, competing on regulatory compliance and proximity to end-users.
Terbium oxide is a sesquioxide of the lanthanide element terbium with the chemical formula Tb4O7, typically appearing as a dark brown-black powder that serves as the primary commercial precursor for terbium metal, alloys, and phosphor compounds. Its dominant industrial purpose centers on activating green-emitting phosphors in fluorescent lamps, cathode ray tubes, and solid-state lighting systems, where terbium's 4f electron transitions yield precise emission wavelengths. Phosphors command the largest application share due to entrenched demand from display backlighting and general illumination, while electronics represents the fastest-expanding segment as terbium-doped materials penetrate magnetostrictive sensors and high-temperature superconductor research. Powder form dominates product type volumes because of its versatility in ceramic sintering and chemical vapor deposition processes, whereas pellet and granule formats capture premium pricing from specialty glass and aerospace alloy manufacturers requiring controlled stoichiometry.
China's Ministry of Industry and Information Technology administers production and export quotas that directly constrain global terbium oxide flow, while the EU Critical Raw Materials Act mandates domestic processing targets and stockpile minimums for strategic elements including heavy rare earths. The US Department of Defense and Department of Energy coordinate offtake agreements and loan guarantees under Defense Production Act authorities to accelerate non-Chinese separation and metal reduction capacity. Stakeholders must monitor quota announcement timing, processing subsidy disbursement rates, and magnet recycling technology maturation as the primary variables determining feedstock cost trajectories and supply chain reconfiguration speed.
Market Dynamics
China's export quota regime for heavy rare earths is compressing available terbium oxide tonnage for non-Chinese phosphor and magnet manufacturers, forcing procurement departments to accelerate alternative sourcing strategies and inventory buffers.
Growth Catalysts
- EU Critical Raw Materials Act stockpile mandates:Brussels requires member states to hold strategic reserves of heavy rare earths including terbium, creating guaranteed offtake volume for qualified suppliers.
- Mini-LED backlighting diffusion:Display manufacturers in Japan and South Korea are tightening phosphor specifications for next-generation panels, amplifying terbium-doped compound demand.
- Automotive electrification targets:Terbium-iron-cobalt alloys enable high-temperature magnet performance in traction motors, with Germany's KBA certifying new drivetrain designs incorporating these materials.
Market Restraints
- Input cost volatility:Solvent extraction reagent prices fluctuate with petrochemical feedstock markets, squeezing separation margins at Malaysian and prospective North American facilities.
- Supply concentration risk:China's Ministry of Industry and Information Technology controls approximately 90% of global heavy rare earth separation capacity, creating single-point vulnerability.
- Substitution threat:Europium-doped alternatives and quantum dot phosphors are capturing share in general illumination applications where color precision requirements permit trade-offs.
Strategic Opportunities
- Underpenetrated defense applications:The US Department of Defense's Defense Production Act loan guarantees are funding domestic terbium metal reduction capacity for guidance system magnets.
- Magnet recycling technology maturation:Hydrometallurgical recovery from end-of-life hard disk drives and wind turbine generators is opening secondary terbium feedstock channels.
- Japan METI stockpiling programs:Tokyo's state-sponsored inventory builds for economic security are creating premium-priced contract windows for qualified ex-China suppliers.
Industry Challenges
- Specialized metallurgical skill scarcity:Rare earth metal reduction and alloy formulation require expertise concentrated in Chinese and Japanese technical institutes, constraining Western capacity scaling.
- Permitting timeline compression:Environmental review processes for new separation facilities in the US and Australia extend project schedules, delaying commercial output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terbium Oxide Market |
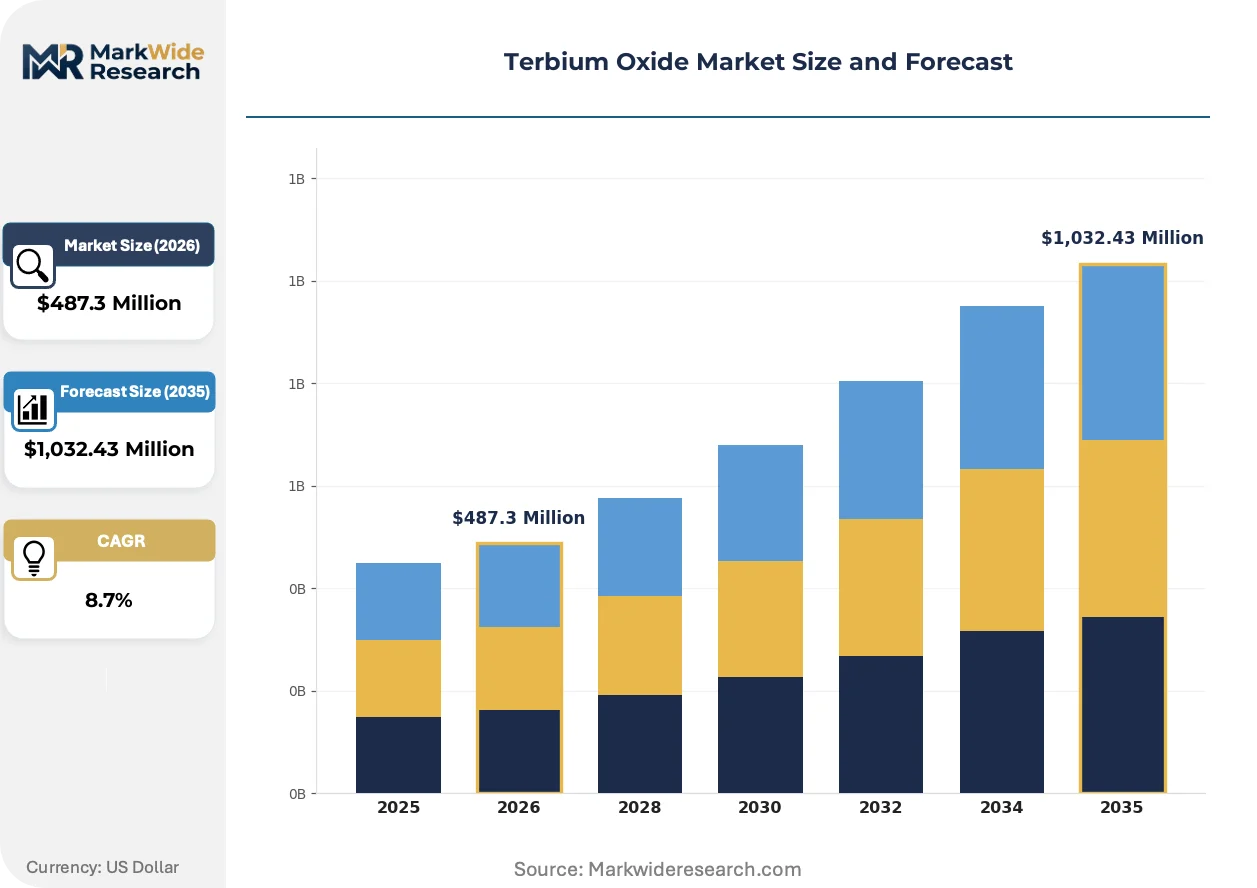
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Pellet, Solution, Granule Application: Phosphors, Electronics, Glass, Ceramics End User: Consumer Electronics, Healthcare, Automotive, Aerospace Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | NioCorp Developments Ltd., Arafura Rare Earths, Energy Fuels Inc., Rare Element Resources Ltd., Tactical Resources Corp., Lynas Rare Earths, Aclara Resources, Australian Strategic Materials, MP Materials Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terbium Oxide Market Strategic Shifts
Process intensification in rare earth separation and phosphor formulation is compressing cost structures while regulatory pressure accelerates supply chain regionalization. Three developments are reshaping competitive positioning.
Solvent extraction circuit optimization is collapsing energy and reagent consumption per kilogram of terbium oxide produced. Lynas Rare Earths' Malaysian facility is deploying continuous counter-current extraction columns that reduce organic phase inventory by 40% versus traditional mixer-settler arrangements. This process architecture is collapsing the operating cost gap between Chinese and non-Chinese separation economics.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon coolants is intersecting with terbium oxide demand through magnetostrictive refrigeration research. ECHA's authorization requirements for fluorinated greenhouse gases are redirecting appliance manufacturer R&D budgets toward solid-state cooling technologies. German and French industrial gas suppliers are responding with pilot terbium-dysprosium alloy programs for magnetocaloric heat pump prototypes.
Long-term offtake contracting is displacing spot market purchasing among Japanese magnet manufacturers. Procurement departments at Tokyo-based automotive suppliers are locking three to five year supply agreements directly with Australian and US mining ventures, bypassing traditional Chinese trading company intermediaries. This behavior is most visible in the neodymium-terbium co-purchase agreements signed since 2023.
Terbium Oxide Market Segmentation
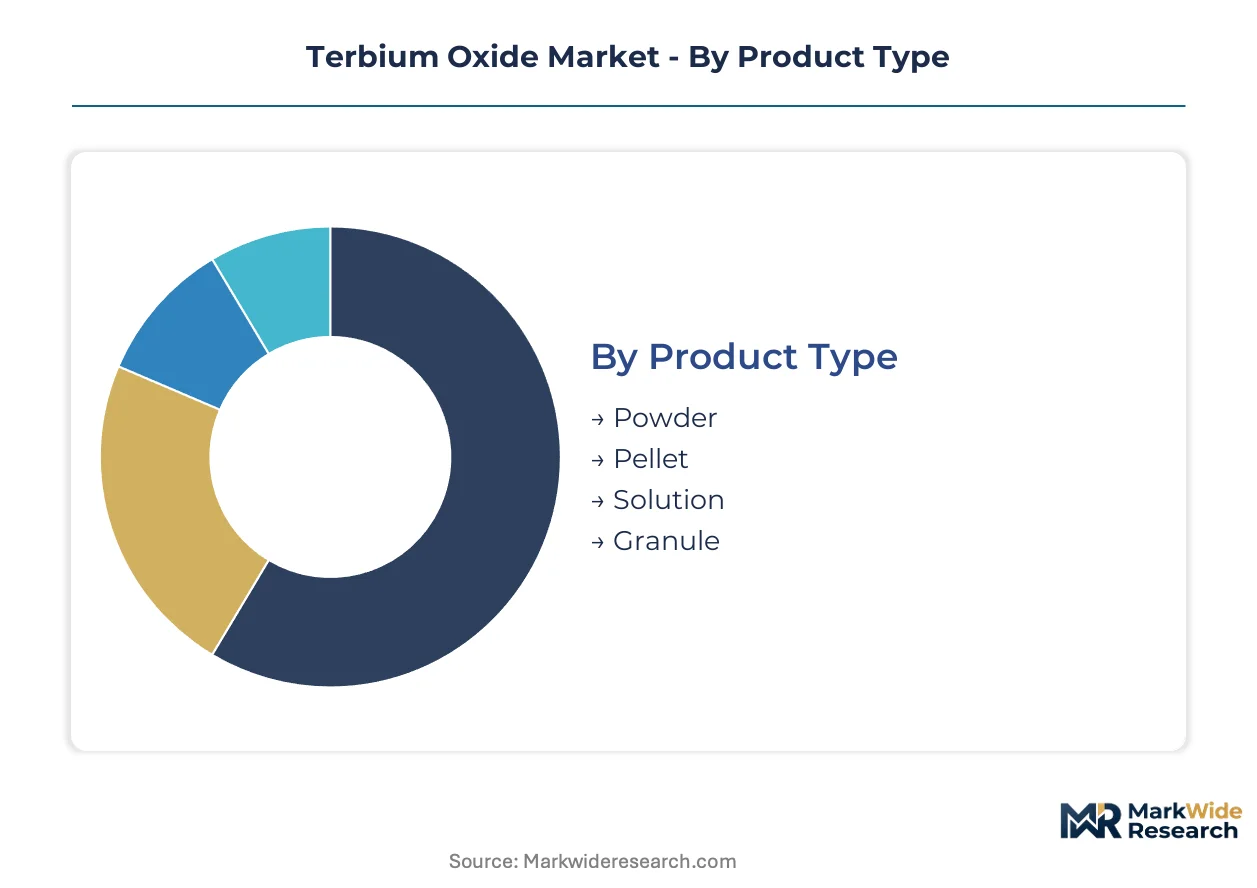
Terbium oxide procurement patterns diverge sharply across product formats and end-use specifications, with phosphor manufacturers and magnet alloy producers imposing incompatible purity and morphology requirements. Understanding these segment boundaries enables suppliers to align separation investments with actual contract economics rather than assumed commodity demand.
Product Type:
Powder specifications span the widest use-case spectrum from bulk phosphor activation to precision ceramic sintering, with each format commanding distinct logistics and quality assurance protocols.
- Powder:Dark brown-black particulate with typical particle sizes between 1-10 micrometers serves as the feedstock for terbium metal reduction and phosphor precursor synthesis. Display backlighting manufacturers in Japan and South Korea consume the largest powder volumes for terbium-doped garnet phosphors, though automotive magnet producers are tightening particle distribution specifications for alloy homogeneity.
- Pellet:Pressed cylindrical forms with controlled density enable direct furnace loading in specialty glass melting and aerospace alloy production, eliminating dust handling hazards. German optical glass manufacturers and French aerospace suppliers pay premium pricing for pellet formats that guarantee stoichiometric consistency in high-temperature processes.
- Solution:Acid-dissolved terbium oxide in nitrate or chloride form supports chemical vapor deposition and thin-film coating applications where precise dopant layering is required. Semiconductor fabrication facilities in Taiwan and South Korea source solution formats for magnetostrictive sensor deposition.
- Granule:Agglomerated particles with intermediate flow properties bridge powder handling convenience and pellet density control, finding niche adoption in research institutions and pilot-scale ceramic processing. US national laboratories specify granule formats for superconductor precursor batching.
Established volume favors Powder; emerging adoption favors Pellet.
Application:
Cost tier differentiation separates commodity phosphor activation from premium electronics and specialty glass formulations, with purity premiums widening at each step.
- Phosphors:Green-emitting terbium-doped compounds dominate fluorescent lamp and LED backlighting applications, where 4f electron transitions deliver precise 545 nm emission. Mini-LED diffusion in Japanese and South Korean display fabs is amplifying demand for ultra-high-purity phosphor precursors with sub-ppm rare earth contamination limits.
- Electronics:Magnetostrictive Terfenol-D alloys and high-temperature superconductor research represent the steepest expansion trajectory, though from a smaller base. US Department of Defense offtake agreements for guidance system magnet materials are accelerating terbium-iron-cobalt alloy qualification programs.
- Glass:Specialty optical glass and radiation-shielding formulations incorporate terbium oxide for refractive index modification and X-ray absorption. German and French industrial gas suppliers are piloting terbium-doped glass for magnetocaloric refrigeration prototypes under EU F-Gas Regulation pressure.
- Ceramics:High-temperature structural ceramics and electronic substrates utilize terbium oxide for sintering aid and dielectric property tuning. Japanese ceramic component manufacturers for automotive sensors represent the primary demand concentration.
Phosphors anchor current revenue; Electronics climbs the fastest.
End User:
Customer type fragmentation splits procurement between high-volume contract manufacturers and specification-intensive specialty producers, with divergent supplier qualification timelines.
- Consumer Electronics:Display panel and solid-state lighting manufacturers drive the largest absolute terbium oxide consumption through phosphor precursor demand. South Korean and Japanese consumer electronics conglomerates are consolidating supplier bases to three-year direct contracts with Australian and US mining ventures.
- Healthcare:Medical imaging equipment and radiation shielding applications require certified purity documentation for regulatory submission. MRI magnet manufacturers in Germany and the US are qualifying terbium-doped superconductor materials for next-generation imaging systems.
- Automotive:Traction motor and sensor manufacturers are expanding terbium-iron-cobalt alloy adoption for high-temperature magnet performance. Germany's KBA certification of new drivetrain designs incorporating these materials is creating qualified supplier windows.
- Aerospace:Guidance systems and satellite components utilize terbium alloys for magnetostrictive precision positioning. US defense prime contractors are securing Defense Production Act-funded domestic metal reduction capacity.
Consumer Electronics dominates contract volume; Automotive gains share fastest.
Distribution Channel:
Supply concentration shapes channel selection, with direct relationships displacing intermediaries as non-Chinese separation capacity expands.
- Direct Sales:Long-term offtake agreements between mining ventures and magnet or phosphor manufacturers are capturing share from trading company intermediaries. Japanese automotive suppliers have pioneered five-year direct contracts with Lynas Rare Earths and prospective US producers.
- Distributors:Specialty chemical distributors maintain inventory buffers for research institutions and mid-tier ceramic processors requiring smaller lot sizes. European distributors are building heavy rare earth stockpiles to service EU Critical Raw Materials Act compliance demand.
- Online:E-commerce platforms serve laboratory and pilot-scale buyers requiring rapid procurement of gram-to-kilogram quantities. US and European research supply platforms are expanding rare earth oxide catalog depth.
- Retail:Minimal adoption limited to educational and hobbyist markets with negligible commercial significance.
Direct Sales captures premium contract growth; Distributors sustain fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT production quotas constrain global terbium oxide availability, while Japan's METI stockpiling and the EU Critical Raw Materials Act reshape procurement geography for Western and Asian downstream users.
China
Phosphor precursor demand from display manufacturers in Guangdong and Fujian provinces absorbs the largest domestic terbium oxide volumes. MIIT export quota announcements trigger immediate price volatility for non-Chinese magnet and lighting producers. Separation capacity concentrates in Jiangxi and Inner Mongolia, where state-owned enterprises coordinate annual production targets with strategic reserve accumulation.
Japan
Automotive electrification targets at Toyota and Honda drive terbium-iron-cobalt alloy qualification for traction motor magnets. METI's economic security stockpiling program guarantees offtake for qualified ex-China suppliers through 2028. Osaka-based magnet manufacturers are signing five-year direct contracts with Australian mining ventures, bypassing traditional Chinese trading intermediaries.
United States
Defense Production Act loan guarantees from the Department of Defense accelerate domestic metal reduction capacity for guidance system magnets. MP Materials Corp.'s Mountain Pass mining complex in California feeds a Texas separation facility scheduled for commercial operation. The Department of Energy coordinates rare earth recovery from coal waste streams in Appalachia and the Mountain West.
Germany
KBA certification of terbium-doped drivetrain designs creates qualified supplier windows for automotive magnet producers. ECHA's F-Gas Regulation redirects appliance R&D toward magnetocaloric refrigeration prototypes using terbium-dysprosium alloys. Industrial gas suppliers in the Ruhr region pilot solid-state cooling systems for heat pump applications.
Australia
Lynas Rare Earths operates the only significant ex-China heavy rare earth separation capacity at its Malaysian facility, with Australian feedstock from the Mount Weld mine. The Critical Minerals Facility under Export Finance Australia provides debt financing for downstream processing investments. Perth-based exploration ventures advance heavy rare earth projects in Western Australia targeting Japanese and US offtake agreements.
Terbium Oxide Market Competitive Environment
State-affiliated Chinese refiners and Western mining ventures split the market into quota-constrained supply and security-of-supply premiums. The structure concentrates upstream separation in state-controlled entities while downstream magnet and phosphor manufacturers scramble for qualified alternative feedstock. Three archetypes dominate: vertically integrated rare earth miners with separation ambitions, pure-play exploration companies holding heavy rare earth deposits, and government-backed strategic stockpilers securing long-term offtake. Capacity expansion and direct contracting with end-users represent the dominant competitive moves as trading company intermediaries lose share.
Among North American mining ventures, Energy Fuels Inc., MP Materials Corp., and Rare Element Resources Ltd. exemplify the integrated-miner archetype pursuing domestic separation and metal reduction capacity. Lynas Rare Earths anchors the ex-China separation specialist tier with its Malaysian facility serving Japanese and Western defense supply chains. Arafura Rare Earths and Australian Strategic Materials occupy positions within the heavy rare earth development cohort targeting 2025-2027 production timelines.
| Leading Market Players |
|---|
| NioCorp Developments Ltd. |
| Arafura Rare Earths |
| Energy Fuels Inc. |
| Rare Element Resources Ltd. |
| Tactical Resources Corp. |
| Lynas Rare Earths |
| Aclara Resources |
| Australian Strategic Materials |
| MP Materials Corp. |
| Others |
Value Chain & Pricing Dynamics
MIIT export quota announcements compress available tonnage for non-Chinese buyers, widening the price spread between contract and spot purchases while forcing procurement departments to build inventory buffers and accelerate alternative sourcing. This regulatory chokepoint stratifies the market into quota-constrained Chinese supply and security-of-supply premiums for ex-China material.
Pricing Analysis
Chinese-origin terbium oxide trades at a discount to Malaysian and prospective North American supply, with the geographic price spread reflecting purity certification tiers and long-term offtake commitment depth. Contract-based long-term offtake agreements dominate volume transactions, though spot purchases persist for research institutions and pilot-scale processors. Price differentiation rests on 99.99% versus 99.999% purity grades and Defense Production Act qualification status. Cost compression in phosphor-grade material is intensifying as solvent extraction reagent prices fluctuate with petrochemical feedstock markets. Consumer electronics manufacturers exhibit highest price sensitivity due to volume scale and substitution alternatives, while aerospace and defense buyers accept premiums for qualified supply assurance.
Supply Chain Analysis
Contract manufacturing concentration sits with state-affiliated Chinese refiners in Jiangxi and Inner Mongolia, where annual production targets coordinate with strategic reserve accumulation. Geographic supply concentrates in China, Malaysia, and the United States, with Australian feedstock flowing to Southeast Asian separation facilities. Raw material dependencies draw from heavy rare earth concentrate, sulfuric acid leach circuits, and solvent extraction reagents. Single-source vulnerability pervades the upstream, as China's Ministry of Industry and Information Technology controls approximately 90% of global heavy rare earth separation capacity. Distribution runs through direct long-term offtake agreements displacing traditional trading company intermediaries, with Japanese automotive suppliers pioneering five-year contracts with Australian and US mining ventures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terbium oxide procurement is consolidating around platform-economics dynamics where qualified supplier status and interoperability with magnet and phosphor manufacturing systems determine contract access. The EU Critical Raw Materials Act's domestic processing targets and stockpile minimums are accelerating this ecosystem standardization.
For Market Incumbents: Insulate qualified supplier positioning through backward integration into heavy rare earth mining and separation capacity in Australia or North America. Secure Defense Production Act qualification for US defense offtake channels. Accelerate hydrometallurgical recycling technology maturation to capture secondary feedstock from end-of-life hard disk drives and wind turbine generators before emerging competitors scale comparable capabilities.
For New Entrants and Emerging Players: German automotive magnet supply chains offer underpenetrated entry points following KBA certification of terbium-doped drivetrain designs. Target the magnetocaloric refrigeration prototype segment where EU F-Gas Regulation pressure redirects appliance manufacturer R&D budgets toward solid-state cooling technologies. Pursue direct qualification with Japanese METI stockpiling programs as the go-to-market angle, bypassing Chinese trading intermediaries entirely.
For Investors and Strategic Acquirers: The market sits at a supply-security transition phase that favors ex-China separation specialists with proven metallurgical expertise. Long-term viability hinges on five-to-ten-year offtake contract depth with Japanese automotive or US defense prime contractors. Acquisition targets should display heavy rare earth deposit access plus separation facility permits in progress. Monitor Defense Production Act loan guarantee disbursement rates as the inflection indicator for domestic metal reduction capacity scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining | Captures heavy rare earth concentrate supply for Malaysian or US separation facilities. |
| Defense Production Act Qualification | Unlocks Department of Defense offtake agreements for guidance system magnet materials. |
| Long-term Supply Agreement | Secures three-to-five-year contracts with Toyota or Honda for traction motor alloy feedstock. |
| Magnet Recycling Scale-Up | Opens secondary terbium channels from end-of-life wind turbine generators and disk drives. |
| EU Critical Raw Materials Compliance | Positions suppliers for Brussels-mandated strategic reserves and domestic processing targets. |
Study Parameters
A spread of perspectives from phosphor manufacturing executives, rare earth separation plant managers, automotive procurement leads, defense supply chain officers, and MIIT policy researchers converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, SEC 10-K filings, EU Critical Raw Materials Act implementation documents, and Japanese METI stockpiling program announcements. Bottom-up segment sizing across powder, pellet, solution, and granule formats triangulated with top-down market reconstruction from mining venture production disclosures.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning product type, application, end user, and distribution channel. Phosphor purity specifications, magnet alloy terbium content per traction motor, and Defense Production Act funding velocity served as industry-specific forecast inputs. CAGRs derived from annualized growth rate convergence between historical volume trends and projected end-use demand elasticity.
Practitioners should monitor MIIT quota announcement timing, Defense Production Act loan guarantee disbursement rates, and magnet recycling technology maturation for early signals of supply chain reconfiguration speed. Forecasts reflect assumptions regarding regulatory continuity and separation facility permitting timelines. Quarterly review of EU Critical Raw Materials Act stockpile accumulation rates and Japanese METI contract award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Germanium Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Semiconductor Glass Wafer Market