
 Silicon Carbide Semiconductor Devices Market | 2026-2036
Silicon Carbide Semiconductor Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Carbide Semiconductor Devices Market Intelligence
Wide-bandgap material substitution is tilting power electronics architectures away from silicon toward silicon carbide across voltage classes above 600V. STMicroelectronics N.V. anchors European automotive supply chains through its integrated SiC substrate and module production in Catania. Wolfspeed, Inc. dominates North American wafer supply with its vertically integrated 200mm fabrication complex in New York. Infineon Technologies AG extends its industrial power portfolio through SiC MOSFET designs optimized for traction inverters and renewable energy converters.
Silicon carbide semiconductor devices are wide-bandgap electronic components fabricated from crystalline SiC, offering breakdown electric fields roughly ten times higher than silicon and thermal conductivity exceeding threefold, enabling operation above 175°C with reduced switching losses. Their primary commercial purpose centers on high-efficiency power conversion in electric vehicle drivetrains, grid-tied inverters, and industrial motor drives where minimizing energy dissipation determines system economics. MOSFETs command the dominant product position due to their gate-controlled switching suitability for traction inverter topologies, while power modules aggregate multiple die into thermally optimized packages for automotive OEM assembly lines. Electric Vehicles represent the fastest-expanding application segment as 800V architectures proliferate, though industrial appliances sustain stable replacement demand across welding and induction heating equipment.
The U.S. EPA tailpipe standards and the EU Green Deal framework compel automakers to adopt SiC devices for efficiency gains that extend electric range without battery cost escalation. China's MIIT dual carbon goals and GB standards for new energy vehicles mandate domestic SiC supply chain development, reshaping where manufacturers qualify production. Japan's METI supports SiC R&D through national consortium funding tied to next-generation power electronics roadmaps. Stakeholders must monitor wafer substrate yield improvements and automotive qualification timelines as the decisive variables separating volume suppliers from niche participants.
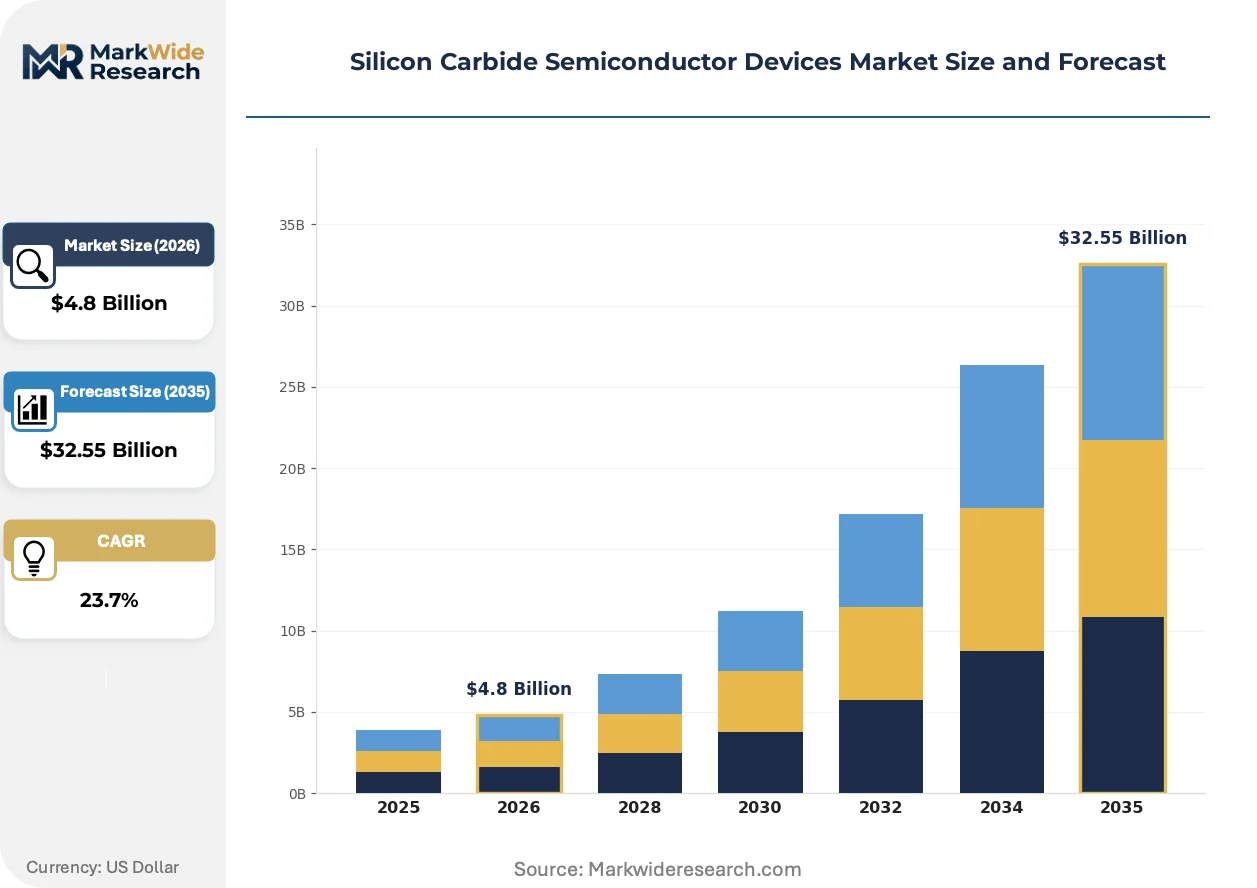
Market Dynamics
800V electric vehicle architectures are forcing a wholesale replacement of silicon IGBTs with silicon carbide MOSFETs, compressing automotive qualification timelines and concentrating wafer demand among vertically integrated substrate suppliers.
Growth Catalysts
- EPA Tailpipe Standards:The U.S. EPA's tightened emission mandates compel automakers to abandon silicon power devices for SiC-based traction inverters that extend electric range without battery cost escalation.
- EV Powertrain Electrification:Battery electric vehicle platforms above 400kW motor output now specify SiC modules as standard, pulling module procurement volumes upward across German, Japanese, and Chinese OEM assembly lines.
- China's MIIT Dual Carbon Goals:Beijing's domestic content mandates under GB standards for new energy vehicles accelerate 6-inch and 8-inch SiC wafer capacity buildout in Ningbo and Shenzhen manufacturing corridors.
Market Restraints
- Substrate Yield Volatility:Crystalline SiC boule growth defects limit usable wafer area, keeping substrate costs elevated relative to silicon and constraining margin expansion for device fabricators.
- Geographic Supply Concentration:High-purity SiC substrate production clusters in limited foundry locations, exposing automotive supply chains to single-source disruption risk during qualification transitions.
- Technical Limitation:Gate oxide reliability challenges at junction temperatures above 175°C restrict SiC MOSFET deployment in aerospace and deep-well drilling applications where silicon carbide would otherwise displace silicon.
Strategic Opportunities
- Grid-Scale Energy Storage:Utility-scale battery inverters represent an underpenetrated application where SiC's switching efficiency advantages remain commercially unexploited relative to automotive traction systems.
- EU Green Deal Carbon Neutrality Mandates:The European Commission's binding 2035 ICE phase-out creates regulatory pull for SiC device qualification across French, Italian, and German automotive supply chains.
- Renewable Energy Convergence:SiC MOSFET integration with gallium nitride gate drivers enables next-generation solar inverters and wind converters operating above 99% conversion efficiency.
Industry Challenges
- Power Electronics Talent Scarcity:The specialized skill set combining wide-bandgap device physics with thermal packaging engineering remains concentrated among a limited pool of experienced practitioners.
- Automotive Qualification Timelines:AEC-Q101 certification cycles for SiC devices extend 18-24 months, compressing product development windows and delaying revenue recognition for new device introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Carbide Semiconductor Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $32.55 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diodes, MOSFETs, Power Modules, Transistors Application: Electric Vehicles, Industrial Appliances, Renewable Energy, Power Supplies End User: Aerospace, Automotive, Telecommunication, Consumer Electronics Technology: SiC Schottky, SiC JFET, SiC BJT, SiC SBD |
| Companies Covered | STMicroelectronics N.V., Infineon Technologies AG, Wolfspeed, Inc., ON SEMICONDUCTOR CORPORATION, ROHM Co., Ltd., Mitsubishi Electric Corporation, Toshiba Corporation, Fuji Electric Co., Ltd., Allegro Microsystems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Carbide Semiconductor Devices Market Strategic Shifts & Innovations
Wafer fabrication technology and automotive system architecture are co-evolving, with substrate scaling and packaging innovation converging to collapse cost barriers that previously constrained SiC to premium vehicle segments.
200mm SiC wafer processing is collapsing the manufacturing cost structure that confined silicon carbide to luxury electric vehicles. Automotive tier-one suppliers in Germany and Japan are now qualifying 8-inch device lots for mass-market BEV platforms launching in 2026-2027. This substrate transition enables die-per-wafer economics that compress module pricing toward silicon IGBT parity.
The EU Green Deal's binding carbon neutrality framework is mandating SiC adoption across European automotive supply chains. Germany's KBA and France's DGEC are aligning type-approval procedures with EU battery regulations that penalize energy inefficiency. French and Italian OEMs are responding by specifying SiC traction inverters as standard equipment across their 800V vehicle architectures.
Long-term supply agreements are displacing spot-market wafer purchasing among automotive power module manufacturers. German and Japanese OEMs now contract directly with substrate foundries for multi-year die allocations, bypassing traditional distributor channels. This procurement consolidation is most visible in China's Ningbo corridor, where domestic foundries capture binding volume commitments from European and Asian automakers simultaneously.
Silicon Carbide Semiconductor Devices Market Segmentation
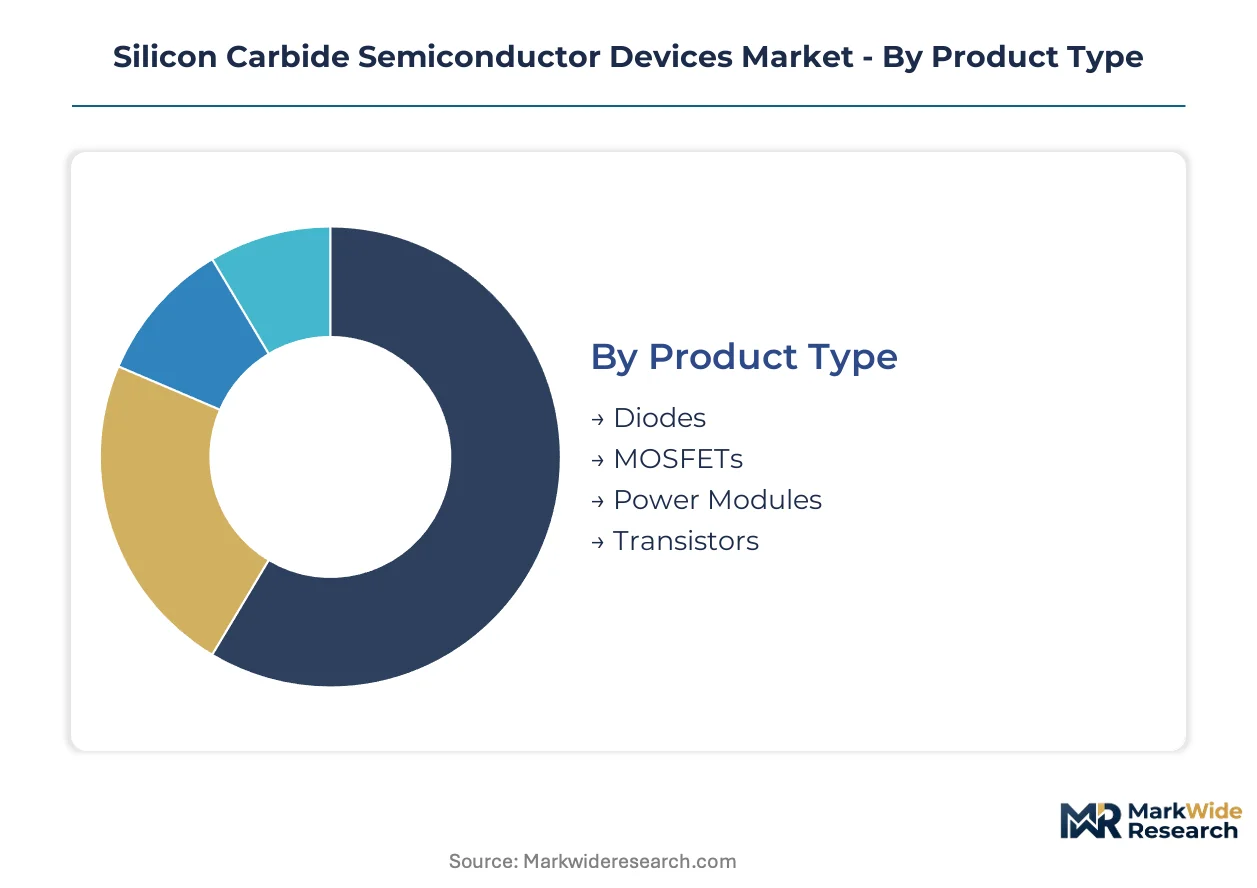
Silicon carbide device procurement patterns diverge sharply across voltage ratings, thermal requirements, and qualification standards. Understanding these segment boundaries reveals where margin pools concentrate and which technology transitions will reshape competitive positioning.
Product Type:
Mature planar technologies coexist with emerging trench-gate architectures, creating a bifurcated supply base serving distinct customer risk tolerances.
- MOSFETs:Trench-gate SiC MOSFETs deliver sub-10mΩ specific on-resistance at 650V-1200V ratings, enabling traction inverter efficiencies above 98%. Demand concentrates in German and Japanese automotive OEM assembly lines where 800V architectures now specify SiC as standard equipment. EPA tailpipe standards and EU Green Deal mandates are accelerating displacement of silicon IGBTs.
- Power Modules:Multi-die packages with silver-sintered thermal interfaces and copper wire bonds aggregate switching devices for motor drive integration. Procurement volumes are climbing fastest in China's Ningbo manufacturing corridor where domestic foundries supply European and Asian automakers under long-term die allocation contracts.
- Diodes:SiC Schottky barrier diodes eliminate reverse recovery losses in power factor correction circuits.
- Transistors:Discrete switching devices serve lower-power industrial motor drives and welding equipment.
MOSFETs retain volume leadership; power modules hold the steepest expansion curve.
Application:
Cost tier stratification separates premium electrified transport from price-sensitive industrial replacement cycles.
- Electric Vehicles:Battery electric platforms above 400kW motor output require SiC traction inverters to extend range without battery cost escalation. China's MIIT dual carbon goals and GB standards for new energy vehicles mandate domestic supply chain development, reshaping where manufacturers qualify production.
- Renewable Energy:Grid-tied solar inverters and wind converters above 99% efficiency targets specify SiC MOSFETs combined with gallium nitride gate drivers. Utility-scale battery inverters represent underpenetrated demand where switching efficiency advantages remain commercially unexploited relative to automotive systems.
- Industrial Appliances:Welding and induction heating equipment sustain stable replacement demand across voltage classes.
- Power Supplies:Server and telecom rectifiers adopt SiC diodes for power factor correction stages.
Electric vehicles dominate revenue concentration; renewable energy is gaining share fastest.
End User:
Customer type determines qualification burden, with automotive AEC-Q101 certification creating the highest barriers to supply entry.
- Automotive:OEMs in Germany, Japan, and China now contract directly with substrate foundries for multi-year die allocations, bypassing traditional distributor channels. Japan's METI supports SiC R&D through national consortium funding tied to next-generation power electronics roadmaps.
- Aerospace:Gate oxide reliability challenges above 175°C restrict SiC MOSFET deployment despite thermal advantages over silicon.
- Telecommunication:Base station power supplies adopt SiC diodes for efficiency gains in cooling-constrained installations.
- Consumer Electronics:Premium laptop adapters specify SiC devices for compact form factors.
Automotive commands the steepest expansion trajectory; industrial segments retain stable replacement volumes.
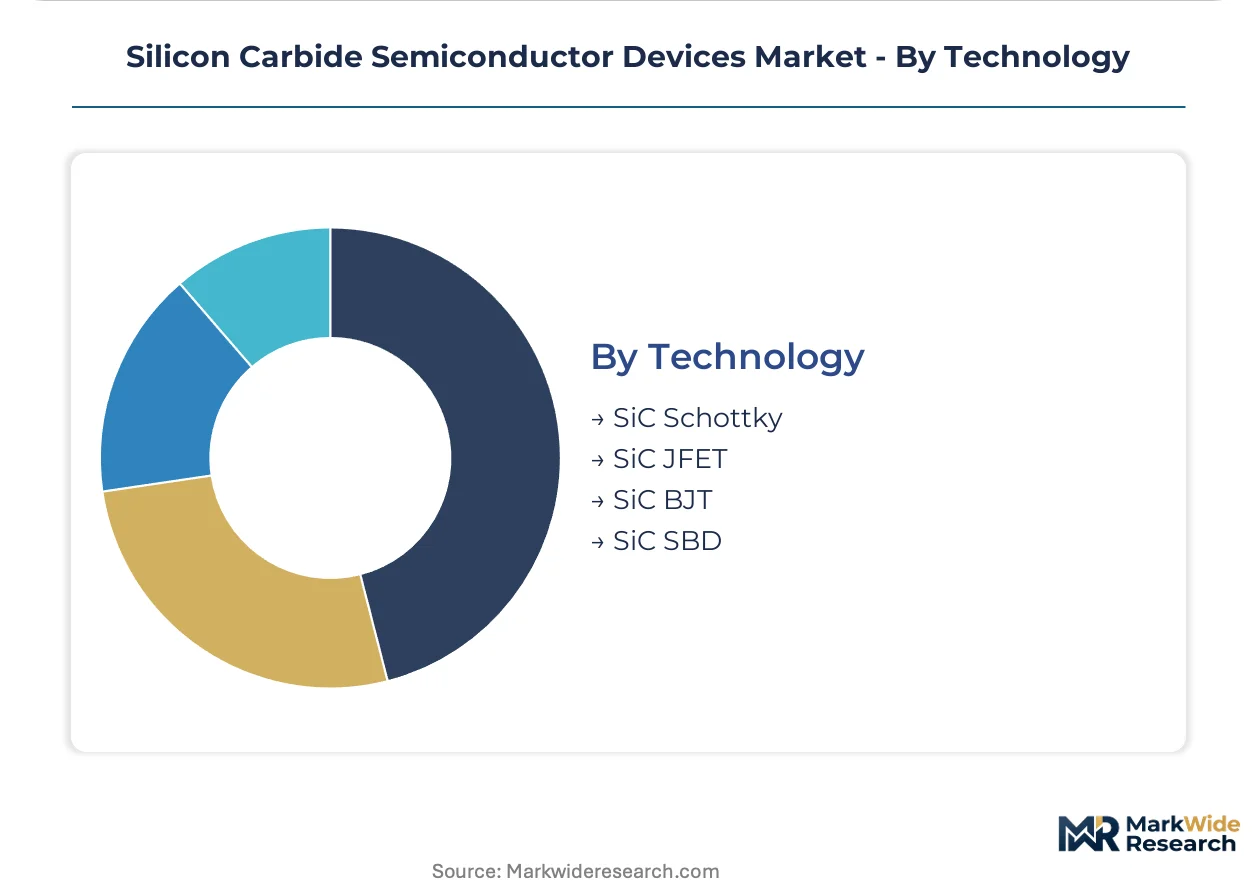
Technology:
Device architecture selection trades off switching speed, gate drive complexity, and manufacturing maturity.
- SiC Schottky:Zero reverse recovery charge enables hard-switching topologies at frequencies above 100kHz, collapsing magnetic component size in power supplies.
- SiC SBD:Schottky barrier diodes serve as freewheeling devices in inverter bridges.
- SiC JFET:Normally-off operation requires complex gate drive circuits limiting commercial penetration.
- SiC BJT:Current-controlled operation demands continuous base current, constraining efficiency in high-frequency applications.
SiC Schottky retains installed base leadership; SiC SBD is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese substrate foundries in Ningbo and Shenzhen now supply die allocations directly to German and Japanese automotive OEMs, compressing traditional procurement channels that once routed through European distributors. This trade-flow reconfiguration concentrates wafer demand in East Asian manufacturing corridors while pulling qualification timelines westward toward Stuttgart and Nagoya assembly lines.
United States
EPA tailpipe emission standards are forcing domestic automakers to abandon silicon IGBTs for SiC traction inverters that extend electric range without battery cost escalation. Wolfspeed's vertically integrated 200mm fabrication complex in New York anchors North American wafer supply. Detroit-based OEMs now contract directly for multi-year die allocations, bypassing traditional semiconductor distribution channels.
Germany
German automotive OEMs above 400kW motor output now specify SiC modules as standard equipment across 800V architectures launching in 2026-2027. The KBA aligns type-approval procedures with EU battery regulations that penalize energy inefficiency. Bavarian and Baden-Württemberg assembly lines are qualifying 8-inch device lots for mass-market BEV platforms.
China
MIIT dual carbon goals and GB standards for new energy vehicles mandate domestic SiC supply chain development, reshaping where manufacturers qualify production. Domestic foundries in Ningbo and Shenzhen manufacturing corridors are scaling 6-inch and 8-inch SiC wafer capacity. Beijing's domestic content requirements accelerate backward integration into substrate production.
Japan
METI supports SiC R&D through national consortium funding tied to next-generation power electronics roadmaps. Japanese automotive OEMs contract directly with substrate foundries for multi-year die allocations. Nagoya and Tokyo manufacturing clusters concentrate module assembly for export to European and North American vehicle platforms.
Silicon Carbide Semiconductor Devices Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure consolidating around vertically integrated substrate suppliers and automotive-qualified module fabricators. The vendor base separates into three strategic archetypes: captive substrate producers with in-house wafer growth, fabless device designers reliant on external foundry capacity, and automotive tier-one suppliers aggregating die into thermally optimized packages. Dominant competitive moves include long-term supply agreements displacing spot-market purchasing and 200mm wafer process transitions collapsing die-per-wafer economics.
Among European-integrated suppliers, STMicroelectronics N.V. and Infineon Technologies AG exemplify the captive-production archetype with combined substrate and module operations. Wolfspeed, Inc. anchors North American supply as a vertically integrated wafer specialist. These three entities occupy positions that determine qualification timelines and pricing formation across automotive supply chains.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Infineon Technologies AG |
| Wolfspeed, Inc. |
| ON SEMICONDUCTOR CORPORATION |
| ROHM Co., Ltd. |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Fuji Electric Co., Ltd. |
| Allegro Microsystems, Inc. |
| Others |
Cost & Logistics Intelligence
Single-source substrate dependency in high-purity SiC boule production determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of automotive module assembly. Chinese foundries in Ningbo and Shenzhen now bypass traditional distributor channels to contract directly with German and Japanese OEMs, collapsing historical margin capture by European intermediaries.
Pricing Analysis
The 150mm-to-200mm wafer generation gap separates mature planar MOSFETs at commodity-equivalent pricing from trench-gate architectures commanding certification premiums. AEC-Q101 automotive qualification tier and volume scale drive price differentiation, with unqualified industrial-grade devices facing the steepest cost compression from Chinese domestic foundry expansion. Tier-one automotive buyers exhibit lowest price sensitivity due to range-extension mandates under EPA tailpipe standards, while industrial welding equipment purchasers prioritize unit economics over efficiency gains.
Supply Chain Analysis
X-FAB, GlobalFoundries, and domestic Chinese foundries hold the majority of external SiC device fabrication capacity, though vertically integrated players retain captive substrate supply. The supply chain draws from the United States, China, and Japan for SiC boule growth equipment and high-purity source materials including graphite crucibles and argon gas. Single-source vulnerability concentrates in 200mm wafer processing equipment where European and Japanese toolmakers dominate. Distribution runs through direct long-term die allocation contracts rather than spot-market purchasing, with automotive OEMs now contracting three-to-five year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
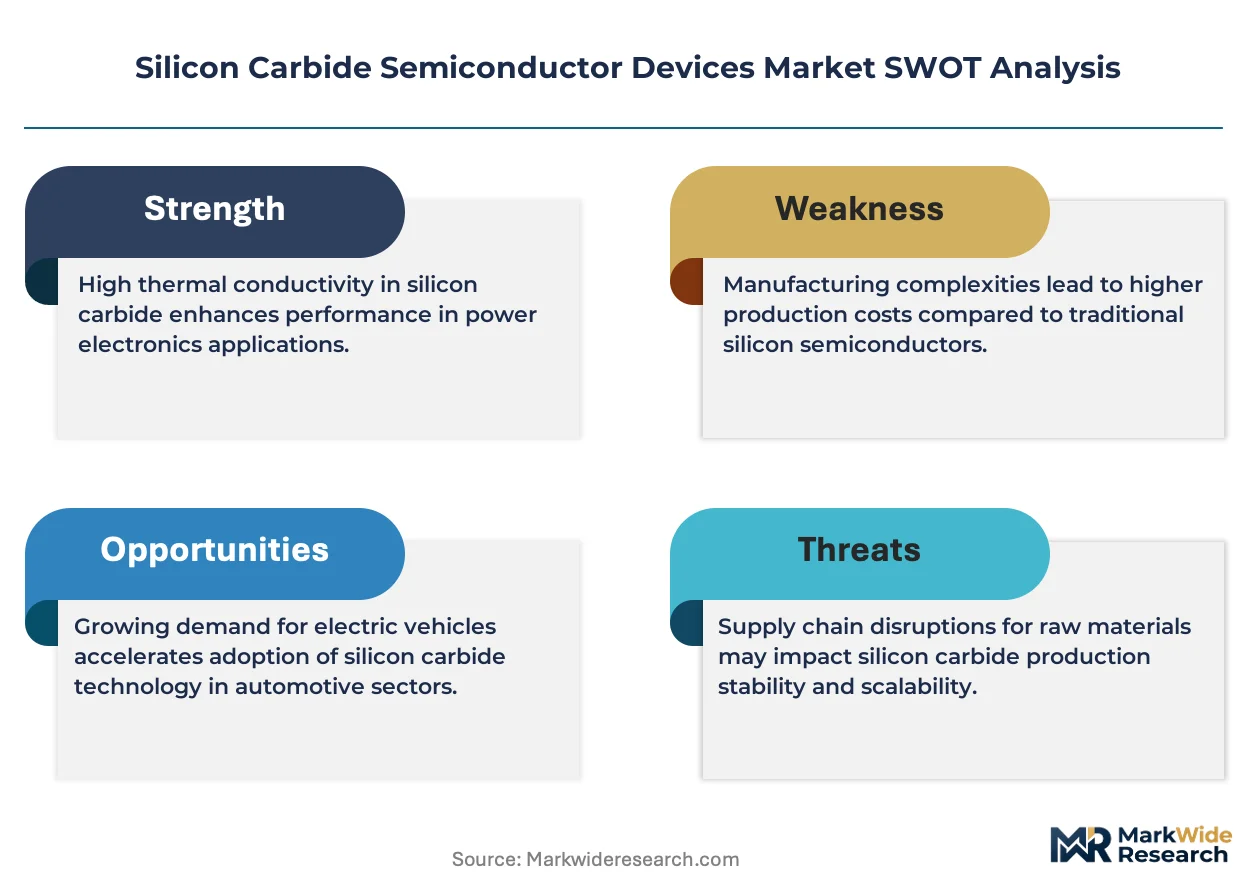
This market requires substitution defense against gallium nitride power devices encroaching below 650V applications. Incumbents must navigate the threat while securing substrate supply for 800V automotive traction inverters.
For Market Incumbents: Insulate module pricing power by securing captive 200mm wafer capacity in Catania or New York before Chinese foundries achieve automotive qualification parity. Accelerate AEC-Q101 certification cycles for trench-gate architectures to outpace GaN gate-driver integration in sub-800V inverters. Prioritize backward integration into SiC boule growth equipment to reduce dependency on Japanese and European toolmakers. For New Entrants and Emerging Players: Utility-scale battery inverters in North American ISO markets represent the most penetrable entry point given underexploited SiC switching efficiency relative to automotive saturation. Grid-tied solar installations above 100MW capacity in Texas ERCOT and California CAISO zones offer qualification pathways without AEC-Q101 burden. Pursue power purchase agreement-linked inverter supply contracts that bundle efficiency guarantees with hardware procurement. For Investors and Strategic Acquirers: The market sits at a substrate-scaling phase that favors vertically integrated device fabricators with in-house boule growth over fabless designers. Long-term viability across the next decade hinges on 200mm process yield achievement and automotive qualification timeline compression. Monitor Wolfspeed's Mohawk Valley utilization rates and STMicroelectronics' Catania expansion cadence as inflection indicators for supply-demand balance.| Strategic Initiative | Industry Significance |
|---|---|
| 200mm Wafer Process Transition | Die-per-wafer economics compress module pricing toward silicon IGBT parity in mass-market BEVs. |
| Long-term Die Allocation Contracts | German and Japanese OEMs bypass distributors to secure multi-year supply from Ningbo foundries. |
| Trench-gate Architecture Qualification | Sub-10mΩ specific on-resistance enables traction inverter efficiencies above 98% under EPA mandates. |
| Captive SiC Boule Growth Investment | Substrate yield volatility limits usable wafer area and constrains margin expansion for external foundry users. |
| GaN Gate Driver Integration | Renewable energy converters achieve 99% efficiency targets through complementary wide-bandgap pairing. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with SiC device engineering directors, automotive Tier 1 procurement managers, substrate foundry operations heads, and power electronics packaging specialists; and secondary validation through SEC 10-K filings, MIIT GB standard publications, EPA regulatory dockets, and IHS Markit vehicle production databases. Bottom-up triangulation across wafer capacity announcements and top-down reconciliation against OEM platform electrification timelines anchored volume estimates.
Forecast inputs considered product type segmentation by voltage rating and gate architecture, application segmentation across EV powertrain and renewable energy converter classes, and end-user segmentation by automotive qualification tier. CAGRs were derived from automotive platform launch schedules and substrate capacity buildout announcements across the analysis window. Modeled inputs included AEC-Q101 certification cycle durations, 150mm-to-200mm wafer transition curves, and China domestic content mandate implementation timelines.
Practitioners should monitor 200mm wafer yield achievement rates and automotive qualification backlog durations for early signals of supply constraint or pricing inflection. Forecasts reflect assumptions regarding substrate defect density improvements and foundry equipment lead times. Quarterly review of MIIT capacity license approvals and KBA type-approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Global Automotive Mosfets Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
MBE Components Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
Chip Equalizers Market