
 AIN DBC Ceramic Substrate Market | 2026-2036
AIN DBC Ceramic Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
AIN DBC Ceramic Substrate Market Insights
Silicon nitride is repositioning alumina in high-reliability power modules where thermal cycling resistance determines module lifetime. Rogers/Curamik leverages its European metallization infrastructure to supply insulated-gate bipolar transistor substrates for rail and wind converters. Ferrotec anchors Asian supply through direct-bond-copper processing lines in Japan and China. KCC competes on ceramic powder backward integration, controlling aluminum nitride synthesis from nitridation through sintering.
An aluminum nitride direct-bonded-copper (AIN DBC) ceramic substrate consists of a thermally conductive AlN ceramic base layer metallized with oxygen-free copper foil through a high-temperature eutectic bonding process, yielding thermal conductivity above 170 W/mK and a coefficient of thermal expansion matched to silicon carbide dies. This architecture enables heat dissipation and electrical isolation in power semiconductor modules operating above 175°C junction temperatures. High-power substrates lead product-type revenue due to EV inverter and charging infrastructure procurement, while multilayer substrates represent the fastest-growing category as integrated gate drivers and sensors merge with power stages. Flip chip technology commands premium positioning in RF and millimeter-wave applications where interconnect inductance limits performance.
The EU F-Gas Regulation and REACH chemical restrictions constrain fluorinated coolant use in power module assembly, pushing manufacturers toward AIN DBC solutions that enable air or water cooling without perfluorinated compounds. China's GB standards for new energy vehicle powertrain efficiency, enforced by MIIT homologation rules, mandate higher switching frequencies that SiC-AIN module pairings satisfy. Japan's METI carbon-neutrality roadmap for industrial equipment accelerates replacement cycles in motor drives and welding power supplies. Stakeholders must track how EPA efficiency standards for data center power supplies and India's PLI scheme for semiconductor packaging reshape procurement geography for ceramic substrate fabricators.
Market Dynamics
Silicon carbide power modules are displacing silicon IGBTs in EV traction inverters, forcing substrate suppliers to reconfigure metallization lines for AlN-copper thermal expansion matching. This material transition concentrates procurement among automotive electronics clusters in Germany, Japan, and China.
Growth Catalysts
- EU F-Gas Regulation:The ban on perfluorinated coolants in power module assembly pushes manufacturers toward AlN DBC substrates that enable air or water cooling without fluorinated compounds.
- China's dual carbon goals:MIIT homologation rules enforcing GB standards for new energy vehicle powertrain efficiency mandate higher switching frequencies that SiC-AIN module pairings satisfy.
- EV charging infrastructure buildout:DC fast-charging stations above 350kW require substrates handling junction temperatures exceeding 175°C, driving specification upgrades across European and Asian procurement offices.
Market Restraints
- Aluminum nitride powder supply concentration:Ceramic powder synthesis capabilities cluster in Japanese and Chinese chemical processors, creating input bottlenecks during demand surges.
- Direct-bond-copper process yield sensitivity:Eutectic bonding temperatures above 1065°C generate copper oxidation defects that scrap 8-12% of metallized substrates at current line configurations.
- Silver-sintered die-attach substitution:Emerging silver-sinter paste technologies reduce thermal interface resistance without requiring AlN substrates, threatening displacement in cost-sensitive industrial drives.
Strategic Opportunities
- India's PLI scheme for semiconductor packaging:Production-linked incentives for domestic substrate fabrication attract module assemblers seeking tariff-advantaged supply chains for Southeast Asian EV markets.
- Multilayer substrate integration:Embedding gate drivers and current sensors within power stage substrates reduces module footprint and parasitic inductance for 800V EV architectures.
- Japan's METI carbon-neutrality roadmap:Accelerated replacement cycles in industrial motor drives and welding power supplies create aftermarket demand for high-reliability substrates with extended thermal cycling lifetimes.
Industry Challenges
- Copper foil thickness uniformity control:Maintaining 0.3mm ±5% tolerances across 138mm × 190mm bonding areas requires capital-intensive rolling mill upgrades that strain mid-tier fabricator balance sheets.
- REACH chemical compliance documentation:ECHA substance-of-very-high-concern screening for nitridation process byproducts extends qualification timelines for new European substrate suppliers by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AIN DBC Ceramic Substrate Market |
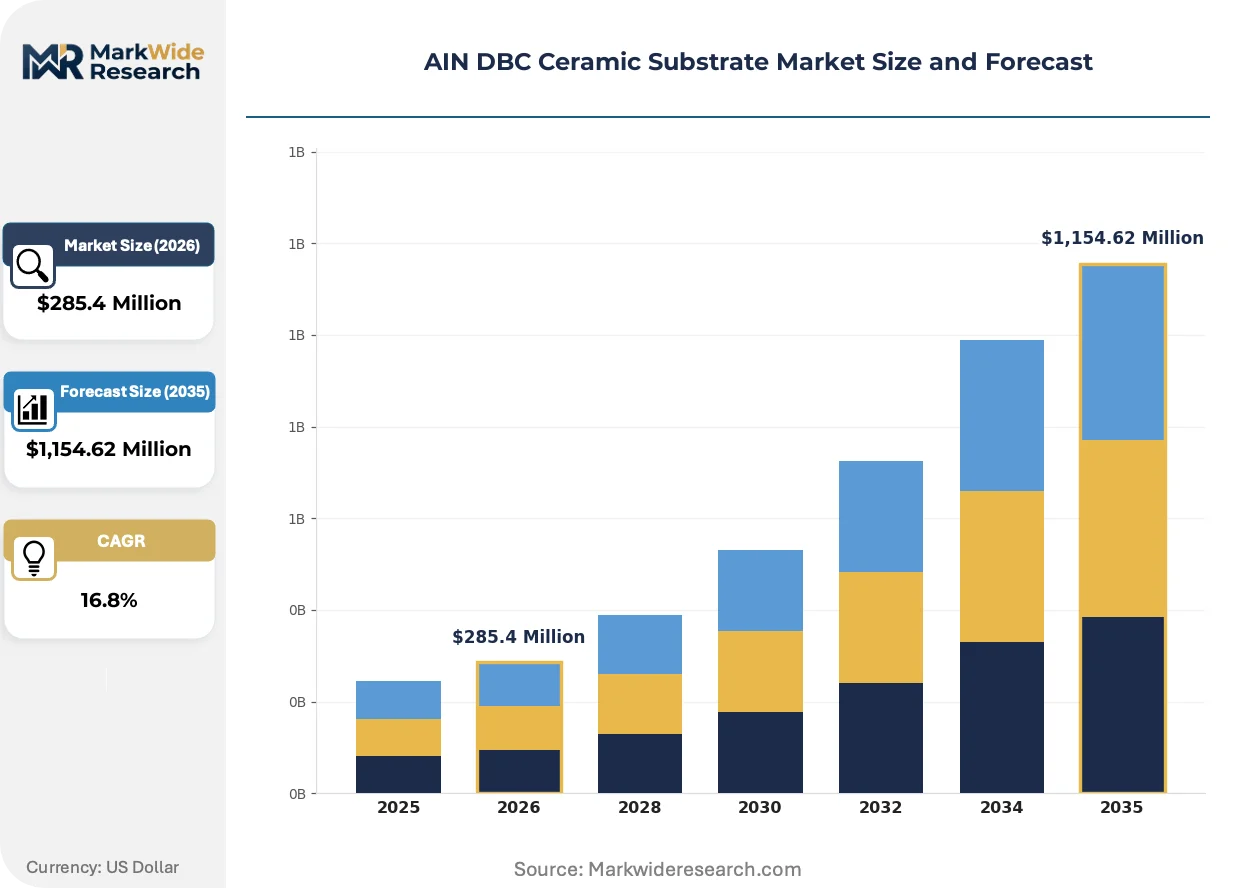
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Substrates, High-Power Substrates, Multilayer Substrates, Thin Film Substrates End User: Consumer Electronics, Automotive Electronics, Industrial Equipment, Telecommunications Technology: Surface Mount Technology, Through-Hole Technology, Flip Chip Technology, Wire Bond Technology Application: Power Electronics, LED Lighting, RF Devices, Heat Management Solutions |
| Companies Covered | Rogers/Curamik, KCC, Ferrotec, Nanjing Zhongjiang New Material Science & Technology, Littelfuse IXYS, Remtec, Stellar Industries Corp, BYD, Shengda Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AIN DBC Ceramic Substrate Market Trends and Innovations
Active metal brazing and transient liquid phase bonding are reshaping how copper metallizes ceramic cores, compressing thermal resistance while expanding design freedom for non-planar geometries. These metallurgical advances intersect with regulatory pressure on fluorinated materials and automotive electrification timelines.
Embedded temperature sensing through thin-film platinum resistors is integrating directly into AlN DBC active layers, enabling real-time junction temperature monitoring without external thermocouples. Tier-1 automotive suppliers in Stuttgart and Munich are qualifying these smart substrates for 800V silicon carbide inverters. The technology is integrating condition-based maintenance protocols into warranty structures, shifting failure-mode analysis from catastrophic to predictive.
REACH chemical restrictions and the EU F-Gas Regulation are eliminating perfluorinated thermal interface materials from power module assembly lines. Manufacturers are responding by specifying AlN DBC substrates with enhanced surface roughness profiles that improve mechanical contact with air-cooled heat sinks. Germany's KBA type-approval process for traction inverters now references substrate thermal impedance as a homologation parameter, embedding material specifications into vehicle certification.
Automotive OEMs are consolidating substrate procurement through direct long-term agreements with ceramic metallizers, bypassing traditional module assembler intermediaries. Volkswagen, BMW, and Hyundai Motor Group have established dedicated supplier development programs for AlN DBC qualification in Korea and Germany. This disintermediation concentrates technical dialogue between vehicle engineering teams and substrate process engineers, compressing design iteration cycles from 18 months to 9 months for new inverter platforms.
AIN DBC Ceramic Substrate Market Segmentation
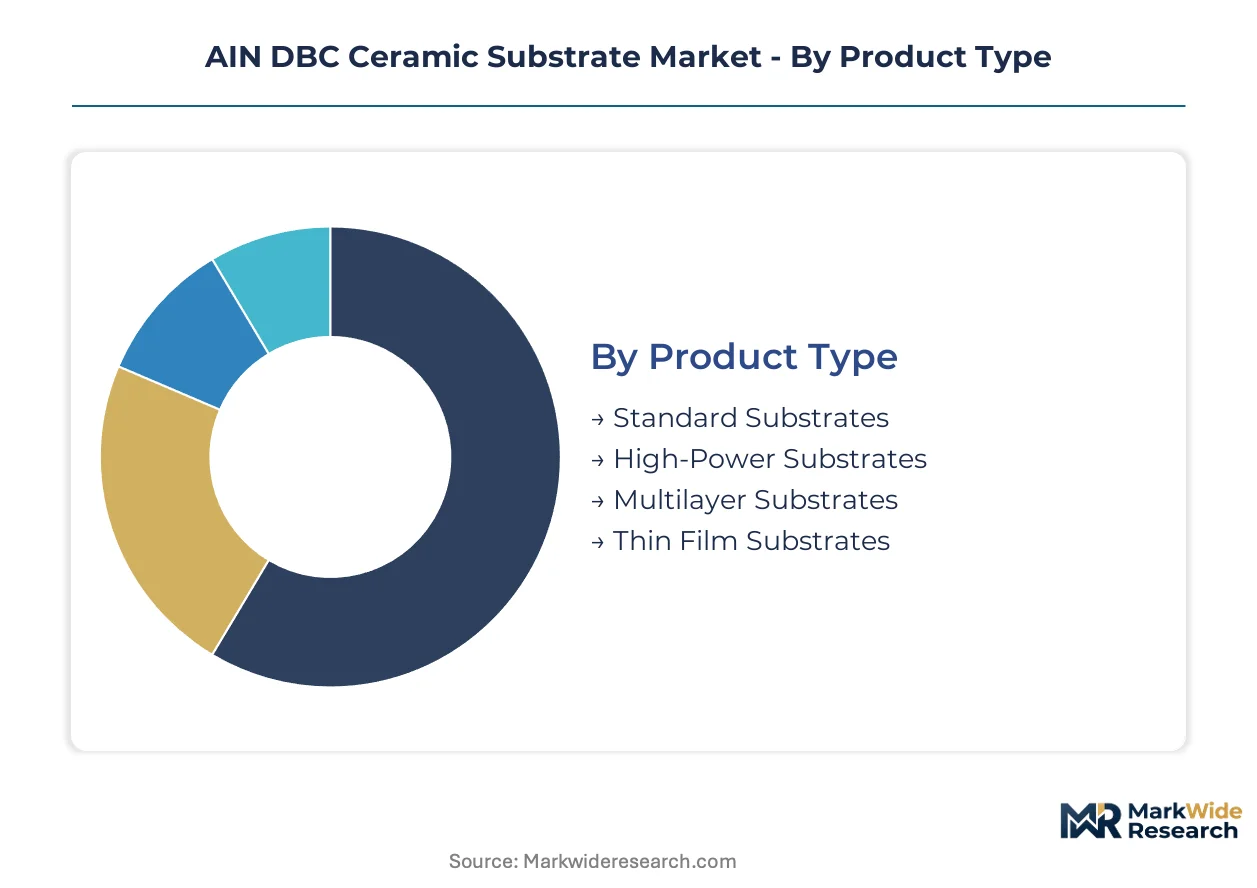
AIN DBC substrate procurement splits sharply between cost-optimized consumer tiers and performance-driven automotive specifications. Each segmentation dimension reveals distinct margin structures and qualification barriers that reshape supplier portfolio priorities across metallization technologies and end-use verticals.
Product Type:
Volume concentration versus premium positioning determines metallization complexity and thermal specification thresholds.
- High-Power Substrates:These substrates deploy 0.3mm oxygen-free copper foils bonded to 170 W/mK AlN ceramic cores for junction temperatures exceeding 175°C. Procurement concentrates around Stuttgart and Munich automotive electronics corridors where 800V EV inverter programs drive specification upgrades.
- Multilayer Substrates:Embedded gate drivers and current sensors merge with power stages through sequential lamination of metallized ceramic layers. Demand is climbing the fastest in Korean and German EV architectures seeking footprint reduction for integrated traction inverters.
- Standard Substrates:Conventional single-layer AlN DBC for industrial motor drives and lower-power conversion modules.
- Thin Film Substrates:Sputtered metallization for RF and millimeter-wave applications where interconnect inductance limits performance.
Mature deployment sits with Standard Substrates. Newer deployment is concentrated in Multilayer Substrates.
End User:
Automotive qualification timelines stretch 18-24 months versus industrial equipment's 6-9 month cycles, creating divergent revenue recognition patterns.
- Automotive Electronics:Silicon carbide traction inverters and onboard chargers mandate thermal expansion matching between AlN substrates and SiC dies. Volkswagen, BMW, and Hyundai Motor Group have established dedicated supplier development programs in Korea and Germany.
- Industrial Equipment:Motor drives, welding power supplies, and uninterruptible power supplies form the installed base replacement market. Japan's METI carbon-neutrality roadmap accelerates retrofit demand for extended thermal cycling lifetimes.
- Consumer Electronics:Premium smartphone chargers and laptop adapters specify AlN DBC for compact thermal management.
- Telecommunications:Base station power amplifiers and data center power supplies drive medium-volume procurement with efficiency-focused specifications.
Procurement volume leadership belongs to Automotive Electronics. Margin expansion concentrates in Industrial Equipment aftermarket programs.
Technology:
Interconnect density requirements and parasitic inductance tolerances determine bonding methodology selection.
- Flip Chip Technology:Direct die attachment to substrate metallization eliminates wire bond inductance for RF and millimeter-wave power amplifiers. Premium positioning in 5G base station and radar applications commands price multiples over conventional approaches.
- Wire Bond Technology:Aluminum wedge bonding remains dominant for IGBT and SiC power modules in cost-sensitive industrial drives.
- Surface Mount Technology:Standard solder reflow attachment for passive components and lower-power discrete devices.
- Through-Hole Technology:Legacy insertion mounting for high-reliability aerospace and military qualification programs.
Flip Chip Technology is gaining share fastest in telecommunications infrastructure. Wire Bond Technology retains volume leadership across power module assembly.
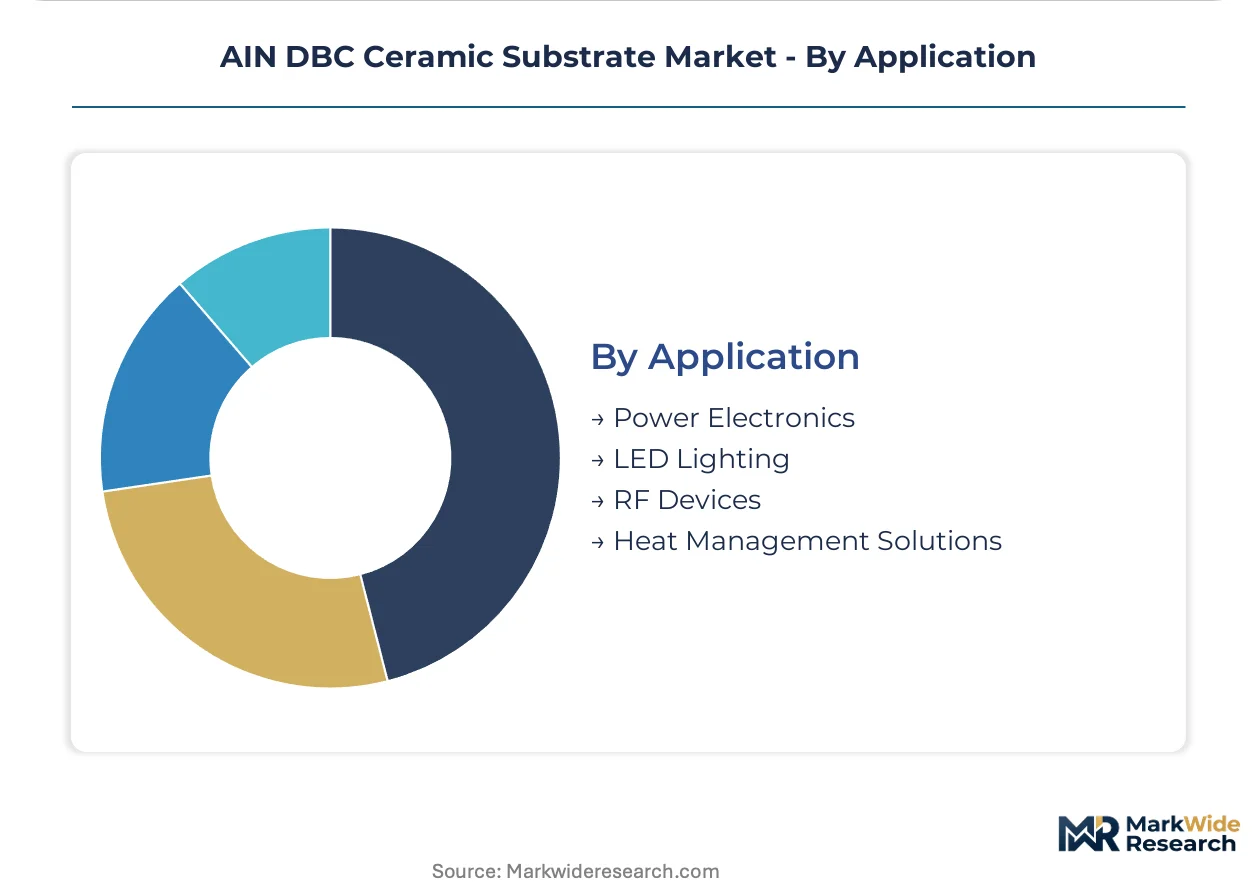
Application:
Thermal management intensity and electrical isolation requirements vary dramatically across power conversion versus optoelectronic use cases.
- Power Electronics:Traction inverters, DC fast chargers, and renewable energy converters represent the core demand cluster. EU F-Gas Regulation and China's MIIT homologation rules mandate substrate specifications that enable fluorinated-coolant-free thermal management.
- Heat Management Solutions:Air-cooled and liquid-cooled heat spreaders for high-performance computing and LED thermal management.
- RF Devices:Power amplifiers and filters for radar and communication systems requiring controlled dielectric properties.
- LED Lighting:High-brightness automotive and horticultural lighting modules with moderate thermal loads.
Power Electronics dominates current procurement volumes. Heat Management Solutions are expanding most quickly in data center liquid cooling retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's automotive electronics corridor, China's EV manufacturing belt, and Japan's precision ceramics clusters. These three countries account for the majority of substrate procurement volume and qualification activity. Procurement offices in Stuttgart, Shenzhen, and Nagoya coordinate specification upgrades across tier-1 module assemblers.
Germany
Stuttgart and Munich anchor European demand through Volkswagen and BMW 800V inverter programs. The EU F-Gas Regulation eliminates fluorinated coolants from power module assembly, mandating air-cooled AlN DBC architectures. KBA type-approval now references substrate thermal impedance as a homologation parameter, embedding material specifications into vehicle certification.
China
MIIT homologation rules enforce GB standards for new energy vehicle powertrain efficiency, requiring higher switching frequencies that SiC-AlN pairings satisfy. Shenzhen and Shanghai module assemblers source from domestic powder synthesis capabilities clustered in Jiangsu and Zhejiang provinces. The dual carbon goals tighten efficiency mandates for power conversion systems across charging infrastructure and traction inverters.
Japan
METI's carbon-neutrality roadmap accelerates replacement cycles in industrial motor drives and welding power supplies. Nagoya and Osaka house precision ceramics fabricators with captive aluminum nitride synthesis from nitridation through sintering. Ferrotec anchors Asian supply through direct-bond-copper processing lines serving both domestic and export markets.
United States
EPA efficiency standards for data center power supplies reshape procurement geography for substrate fabricators targeting telecommunications infrastructure. The Inflation Reduction Act incentives concentrate EV supply chain investment in the Midwest and Southeast, pulling qualification activity toward Detroit and Atlanta automotive electronics corridors.
South Korea
Hyundai Motor Group operates dedicated supplier development programs for AlN DBC qualification in Seoul and Ulsan. Domestic module assemblers specify multilayer substrates for integrated traction inverters on 800V EV architectures. Korean procurement offices compress design iteration cycles through direct technical dialogue with metallization process engineers.
AIN DBC Ceramic Substrate Market Competitive Landscape
Capacity expansion dominates the current landscape as substrate fabricators reconfigure metallization lines for AlN-copper thermal expansion matching. The vendor base stratifies across three tiers: integrated ceramics-to-metallization specialists, pure-play DBC processors, and captive automotive electronics divisions. Japanese and Chinese chemical processors control aluminum nitride powder synthesis, creating upstream bottlenecks during demand surges. Strategic partnerships between ceramic powder suppliers and metallization houses accelerate qualification timelines for new EV platforms.
Among Asian fabricators, Ferrotec and KCC occupy distinct positions within the supply architecture. Ferrotec exemplifies the integrated metallization model with processing capabilities spanning Japan and China. KCC represents backward integration into ceramic powder synthesis, controlling aluminum nitride production from raw material through finished substrate. Rogers/Curamik anchors European supply through its metallization infrastructure serving rail and wind converter markets. These three companies illustrate the geographic and structural segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Rogers/Curamik |
| KCC |
| Ferrotec |
| Nanjing Zhongjiang New Material Science & Technology |
| Littelfuse IXYS |
| Remtec |
| Stellar Industries Corp |
| BYD |
| Shengda Tech |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM consolidation of substrate procurement through direct long-term agreements with ceramic metallizers is compressing margins for module assembler intermediaries and forcing fabricators to absorb yield-loss costs from copper oxidation defects. This buyer-side restructuring concentrates pricing power among tier-1 vehicle engineering teams while squeezing mid-tier DBC processors who lack captive aluminum nitride synthesis.
Pricing Analysis
Volume concentration in standard single-layer substrates for industrial motor drives runs on thin margins, while automotive-qualified high-power substrates for 800V EV inverters command significant premiums. Pricing stratifies across automotive-grade, industrial-grade, and consumer-grade tiers, with MIIT homologation requirements in China and KBA type-approval in Germany adding certification costs that widen spreads. Cost compression in standard substrates is intensifying as silver-sintered die-attach technologies threaten displacement in cost-sensitive industrial drives. Industrial equipment buyers exhibit highest price sensitivity, while automotive electronics procurement prioritizes thermal cycling reliability over unit cost.
Supply Chain Analysis
Aluminum nitride powder synthesis rests on Japanese and Chinese chemical processors, with Tokuyama and Toyo Aluminium K.K. alongside Jiangsu and Zhejiang province producers controlling nitridation through sintering. Direct-bond-copper processing lines draw from oxygen-free copper foil rolling mills in Germany and Japan, while eutectic bonding equipment concentrates among specialized metallization houses. Single-source vulnerability in ceramic powder supply creates input bottlenecks during EV platform ramp cycles. Distribution runs through module assembler procurement offices in Stuttgart, Shenzhen, and Nagoya coordinating specification upgrades with substrate fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
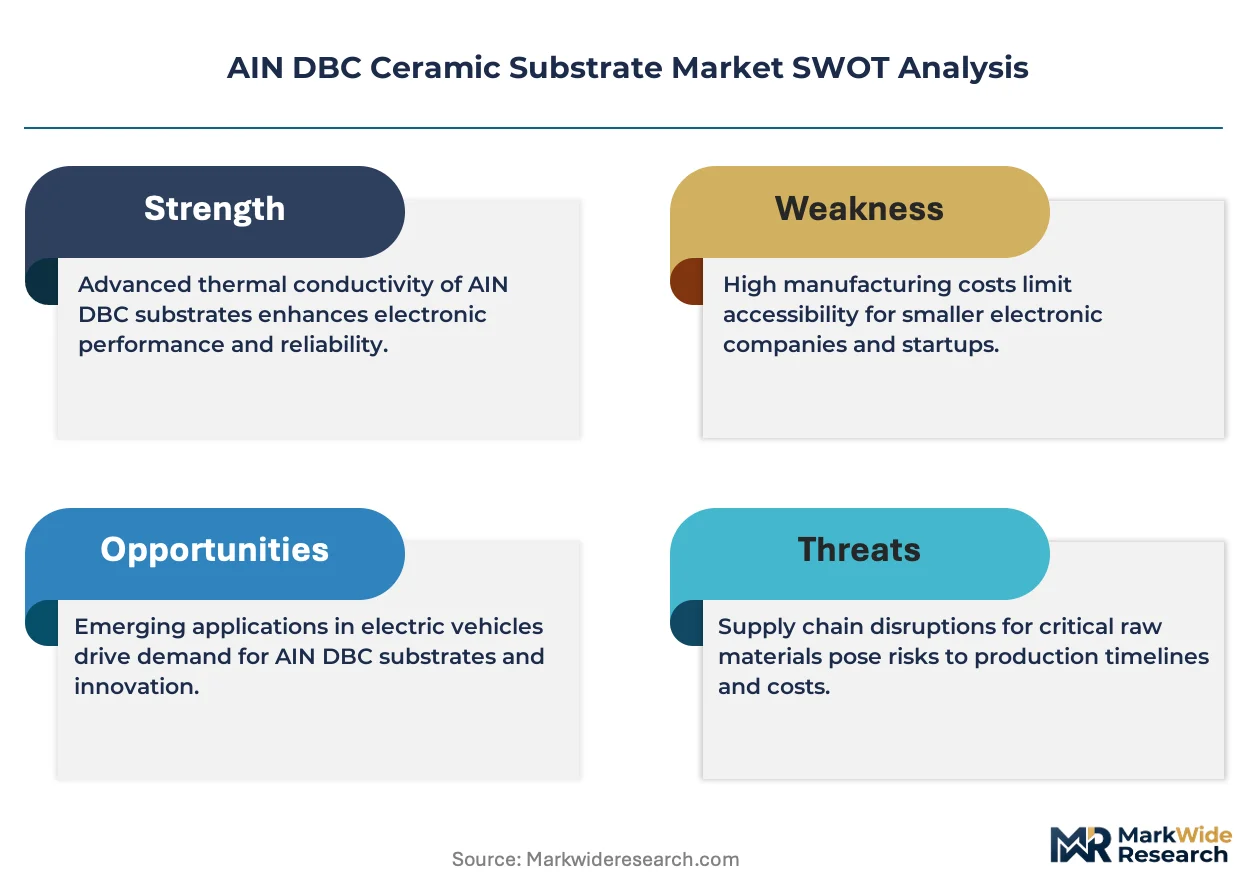
Yield sensitivity in direct-bond-copper processing and REACH chemical compliance documentation are forcing consolidation among mid-tier fabricators lacking capital reserves for rolling mill upgrades and ECHA qualification timelines. This pressure eliminates weaker players and concentrates market share among integrated ceramics-to-metallization specialists.
For Market Incumbents: Deepen backward integration into aluminum nitride powder synthesis to secure input supply during demand surges and reduce exposure to Japanese and Chinese chemical processor bottlenecks. Expand direct-bond-copper processing capacity in Germany's automotive electronics corridor to capture Volkswagen and BMW 800V inverter procurement. Silver-sintered die-attach substitution in industrial drives demands defensive certification investment in extended thermal cycling lifetime specifications. For New Entrants and Emerging Players: India's PLI scheme for semiconductor packaging represents the most penetrable geography, with production-linked incentives attracting module assemblers seeking tariff-advantaged supply chains for Southeast Asian EV markets. Target aftermarket industrial equipment retrofit demand accelerated by Japan's METI carbon-neutrality roadmap, where extended thermal cycling lifetimes command premium positioning. A qualification-fast go-to-market angle emphasizes REACH compliance documentation completion ahead of ECHA substance-of-very-high-concern screening timelines. For Investors and Strategic Acquirers: The window for entry favors integrated ceramics-to-metallization specialists with captive aluminum nitride synthesis and established automotive qualification records. Long-term viability over the next decade hinges on positioning for multilayer substrate integration as 800V EV architectures embed gate drivers and current sensors within power stages. Watch for EPA efficiency standards for data center power supplies as an inflection indicator reshaping procurement geography toward telecommunications infrastructure substrate fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Synthesis | KCC's control of aluminum nitride production from nitridation through sintering insulates margins from input bottlenecks. |
| Multilayer Substrate Capacity Expansion | Hyundai Motor Group's integrated traction inverter programs in Seoul and Ulsan drive fastest-growing product category demand. |
| Automotive Qualification Fast-Track | Direct OEM supplier development programs compress design iteration cycles from eighteen months to nine months for new platforms. |
| REACH Compliance Documentation Investment | ECHA substance-of-very-high-concern screening extends European supplier qualification timelines by fourteen to eighteen months. |
| India PLI Scheme Manufacturing Footprint | Domestic substrate fabrication attracts module assemblers seeking tariff-advantaged supply chains for Southeast Asian EV markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ceramic substrate procurement managers at tier-1 automotive module assemblers, direct-bond-copper process engineers at metallization houses, and aluminum nitride powder synthesis specialists at Japanese and Chinese chemical processors. ECHA REACH documentation, MIIT homologation records, and KBA type-approval filings provided regulatory validation. Bottom-up substrate shipment data triangulated against top-down EV inverter production forecasts and power module assembly capacity announcements.
Granularity-level modeling deployed product-type splits across high-power, multilayer, standard, and thin-film substrates; end-user segmentation across automotive electronics, industrial equipment, consumer electronics, and telecommunications; and technology differentiation across flip chip, wire bond, surface mount, and through-hole attachment methods. CAGRs derived from slope-log regression across the analysis window, with SiC penetration curves and EV charging infrastructure buildout schedules as primary demand-side inputs. Regional production cluster data and powder synthesis capacity utilization informed supply-side constraints.
Revisions become necessary when EPA efficiency standards for data center power supplies accelerate faster than projected, when silver-sintered die-attach technologies achieve cost parity in industrial drives, or when EU F-Gas Regulation enforcement tightens fluorinated coolant bans beyond current timelines. Forecasts reflect documented assumptions about automotive qualification cycle durations and eutectic bonding yield improvement trajectories. A small set of regulatory enforcement intensity, substitute technology cost curves, and automotive platform ramp schedules warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Underfill Market