
 Chip Crusher Market | 2026-2036
Chip Crusher Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Crusher Market Intelligence
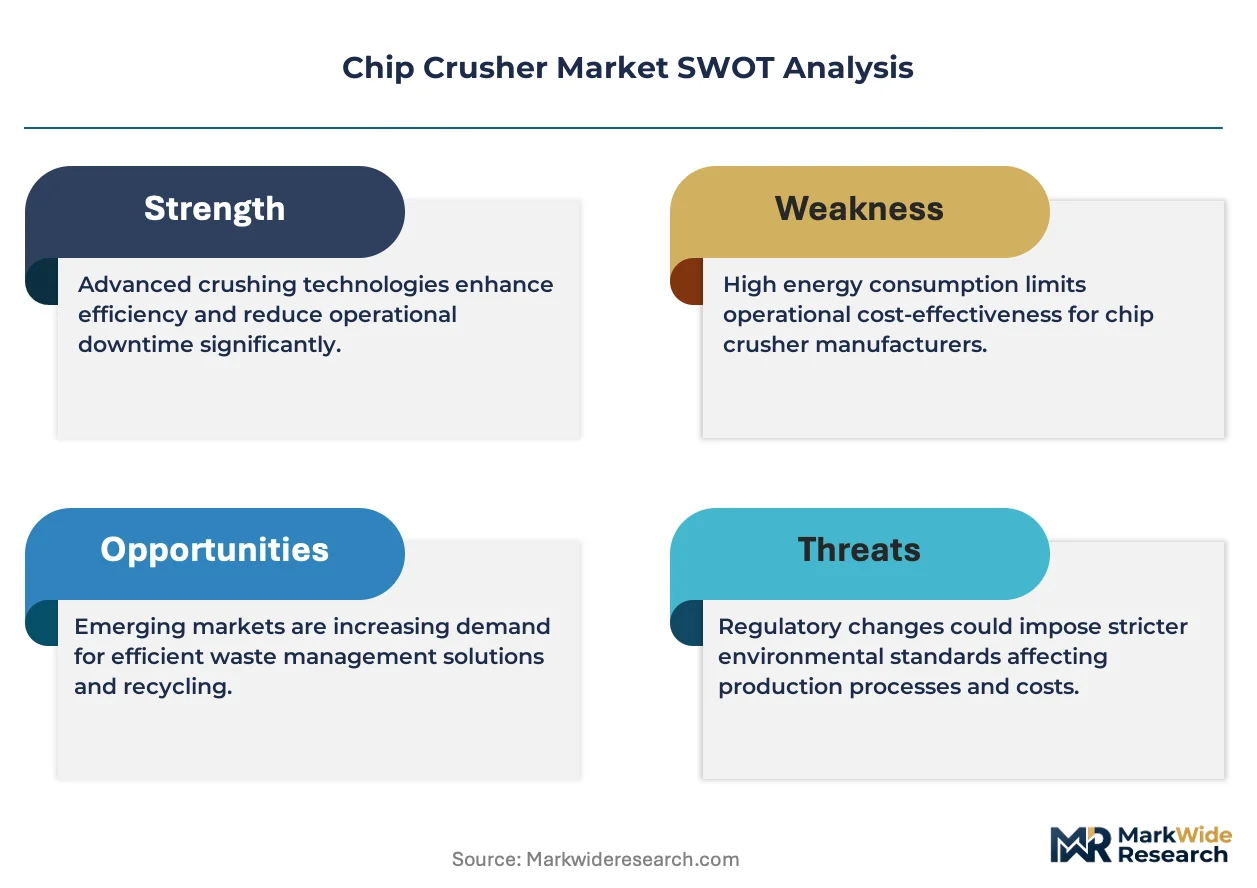
The substitution of traditional steel with lightweight aluminum alloys in automotive manufacturing is restructuring chip crusher design and material handling requirements. This change necessitates equipment that can efficiently process more abrasive and varied metal swarf. Mayfran International leverages its integrated conveyor and processing systems to manage these complex material flows. PRAB competes by offering customized solutions for specific alloy scrap, while Stedman Machine Company specializes in high-capacity crushers for large-scale recycling facilities.
A chip crusher is an industrial machine that reduces the volume of metal shavings and swarf from machining processes. By applying mechanical force, these units break down tangled metal into smaller, denser pieces for easier handling and recycling, often reclaiming cutting fluids. Electric crushers are displacing older hydraulic models in manufacturing plants due to superior energy efficiency and integration with automated systems. While metal recycling constitutes the largest application, electronic waste management represents the fastest-growing segment, driven by component recovery mandates.
Regulations such as the US EPA's rules on solid waste management and the EU's Waste Framework Directive compel manufacturers to process scrap metal responsibly. In parallel, China's MEE enforces standards that encourage metal recycling to meet industrial efficiency targets under its "dual carbon" policy. These frameworks directly influence equipment purchasing decisions in manufacturing plants and recycling facilities. Future competitiveness hinges on developing crushers that can adapt to a more diverse and complex mix of recyclable materials.
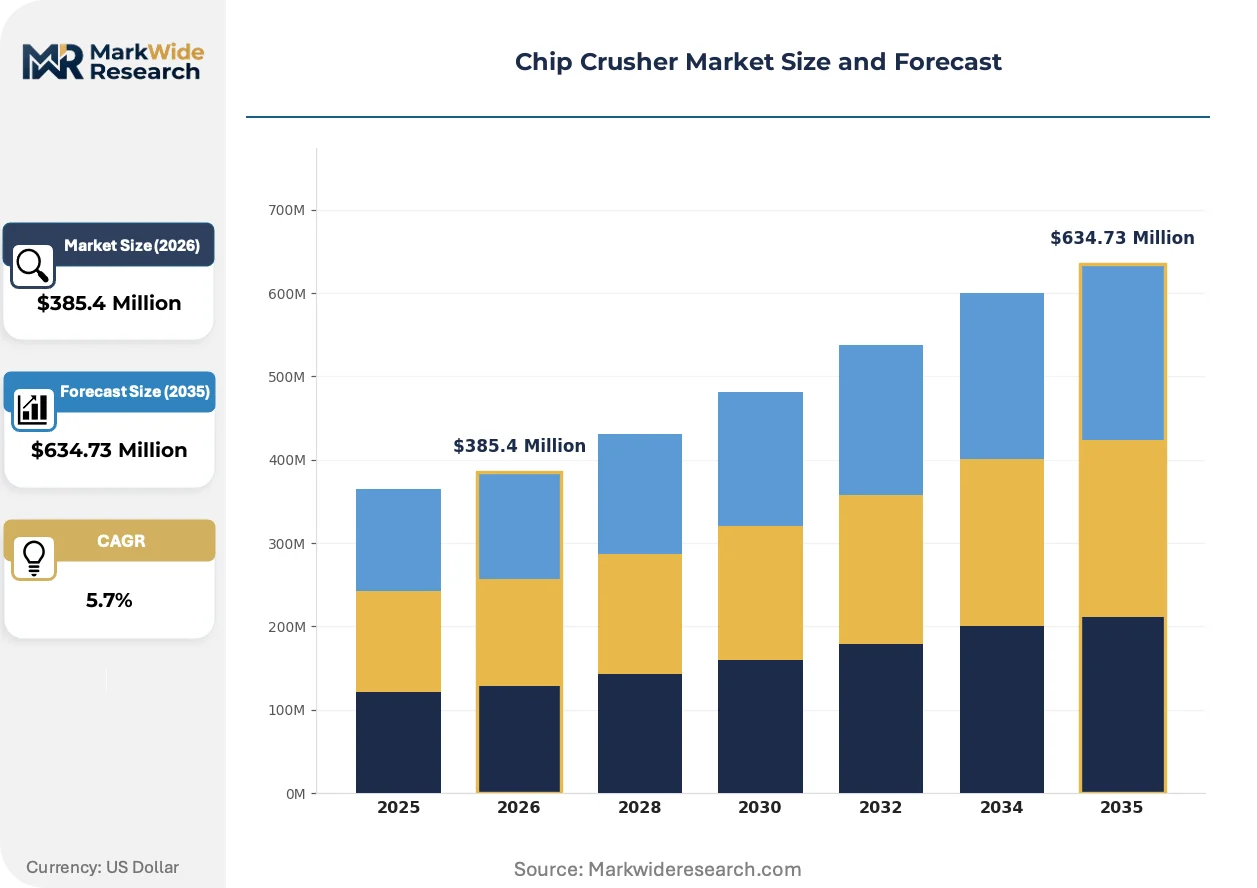
Market Dynamics
The fundamental shift from processing homogenous steel scrap to managing a diverse mix of lightweight aluminum, titanium, and composite materials is the central force shaping the chip crusher market. This material evolution demands more sophisticated, adaptable equipment capable of handling varied abrasiveness and chip geometries.
Growth Catalysts
- Regulatory Frameworks:The EU's Circular Economy Action Plan and China's MEE industrial efficiency standards create direct investment incentives for advanced scrap processing equipment to meet mandated recycling and waste reduction targets.
- Material Value Reclamation:Rising commodity prices for industrial metals, especially aluminum alloys used in automotive manufacturing, make efficient swarf crushing and cutting fluid recovery an economic necessity for fabricators.
- Industrial Automation:The adoption of fully automated production lines, particularly in Germany's automotive sector, requires integrated chip crushing systems that minimize manual labor and maintain continuous material flow from CNC machines.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of purchasing and installing high-capacity, automated chip crusher systems serves as a major barrier for small and medium-sized machine shops and metal recyclers.
- Alloy Cross-Contamination:The challenge of keeping different metal alloy swarf segregated throughout the collection and crushing process can degrade scrap value, limiting the return on investment for crushing equipment.
- Volatile Energy Costs:While more efficient than older models, modern electric crushers still represent a significant energy load, exposing operators in heavy industrial zones to fluctuating and high electricity prices.
Strategic Opportunities
- Electronic Waste Stream:A significant opportunity exists in designing specialized crushers for e-waste, capable of liberating precious metals and other valuable components from circuit boards and electronic assemblies.
- Integrated Fluid Management:Developing crushers with built-in, advanced centrifugation and filtration systems offers a path to capture a higher share of the value chain by providing closed-loop cutting fluid reclamation.
- Service and Modernization:Offering retrofitting packages to upgrade legacy hydraulic crushers with energy-efficient electric drives and IoT-based condition monitoring presents a lucrative service-based revenue stream.
Industry Challenges
- Wear Component Engineering:A primary challenge is the development of hammers, cutters, and liners made from materials that can endure the high abrasiveness of superalloys and titanium swarf without premature failure and costly downtime.
- System Integration Complexity:Ensuring seamless communication and physical interoperability between diverse brands of CNC machines, conveyors, and central crushing systems remains a significant technical hurdle in smart factory implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Crusher Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $634.73 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Crushers, Pneumatic Crushers, Electric Crushers, Manual Crushers Technology: Centrifugal, Jaw, Hammer, Roller Application: Metal Recycling, Plastic Recycling, Wood Processing, Electronic Waste Management End User: Manufacturing Plants, Recycling Facilities, Construction Sites, Scrap Processors |
| Companies Covered | ARS Corporation, Mayfran International, PRAB, Hammermills International, Stedman Machine Company, Endo Kogyo Co., Ltd., Cometel Co., Ltd., Lubriserv Solutions Pvt. Ltd., MGS Technologies Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Crusher Market Strategic Shifts & Innovations
The convergence of material science and digital technology is transforming chip crushers from standalone machines into intelligent nodes within a connected manufacturing ecosystem. This evolution prioritizes data generation, process automation, and adaptability to complex new material streams.
Sensor-based intelligence is a defining feature of modern chip crushers. These systems use integrated sensors to monitor vibration, motor load, and throughput, enabling real-time process optimization. Advanced manufacturing and aerospace facilities are rapidly adopting this technology for predictive maintenance. This data-centric management of scrap processing is overtaking traditional reactive repair schedules, maximizing equipment uptime.
Regulatory frameworks are directly influencing equipment design and purchasing criteria. The EU Waste Framework Directive, with its stringent material recovery targets, pressures manufacturers to improve scrap quality at the source. This requirement favors crushers that produce a consistent, clean, and high-density chip, which is more valuable for recycling. German and Italian manufacturers are leading the response to this directive.
A notable behavioral shift is occurring as large-scale manufacturers increasingly seek comprehensive, turnkey scrap management solutions instead of buying standalone machines. This trend favors system integrators who can design and install a complete package of conveyors, crushers, and fluid reclamation units. The preference is most visible in new automotive plants across the southern United States and Mexico.
Chip Crusher Market Segmentation
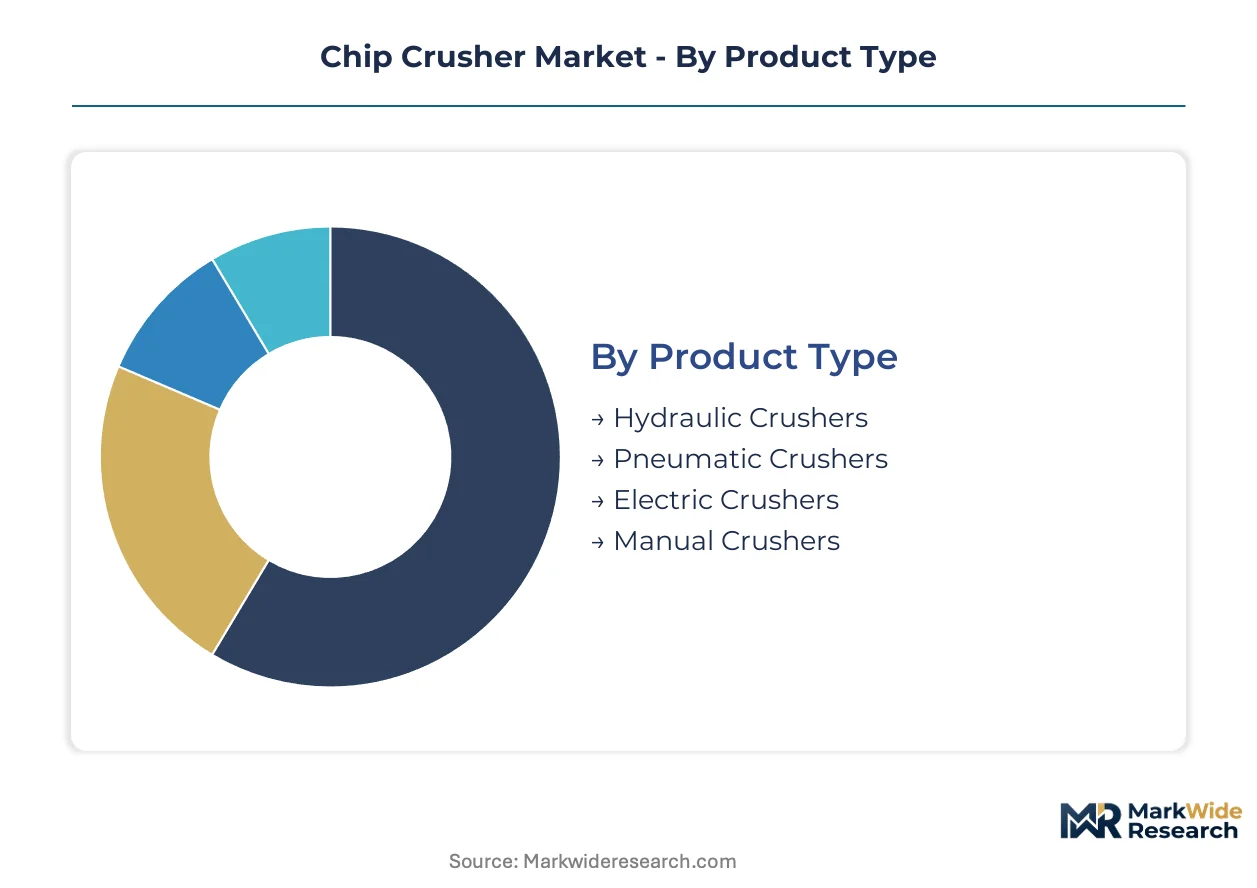
Understanding the distinct segments within the chip crusher market is crucial for identifying targeted growth avenues and evolving technological demands. This analysis dissects the market by product type, technology, application, and end-user, revealing how varying operational requirements and material characteristics influence equipment design and procurement decisions across industries.
Product Type:
The market for chip crushers often splits between high-volume, automated solutions and more specialized, lower-capacity systems. This differentiation impacts investment priorities for manufacturers and recyclers.
- Electric Crushers:These units utilize electric motors for power, offering superior energy efficiency and seamless integration with automated production lines in modern manufacturing facilities. Demand concentrates within Germany's automotive sector, driven by a focus on continuous operation and reduced energy consumption.
- Hydraulic Crushers:Traditional hydraulic systems employ fluid pressure to power crushing mechanisms, known for their robust force and durability in demanding industrial environments. Their presence is still significant in legacy recycling facilities across Eastern Europe, where initial capital outlay remains a key purchasing factor.
- Pneumatic Crushers:These crushers operate using compressed air, often favored for smaller-scale operations or in environments where electric power might be hazardous.
- Manual Crushers:Simple, hand-operated devices provide basic volume reduction for very low-throughput or intermittent scrap generation.
Today's leader: Electric Crushers. Tomorrow's challenger: Pneumatic Crushers.
Technology:
Application versatility and material characteristics heavily influence the selection of crushing technology, dictating efficiency and the quality of the processed output.
- Hammer:Hammer crushers employ swinging or fixed hammers to shatter and reduce material, excelling in processing various metal types, including brittle swarf and light gauge scrap. Demand for hammer crushers is strong in large-scale metal recycling yards across the United States, managing diverse ferrous and non-ferrous inputs.
- Jaw:Jaw crushers utilize compressive force between a fixed and a movable jaw to break down larger, more abrasive pieces of metal, serving as primary crushers in heavy industrial settings. Their robust design makes them indispensable in mining and primary metal processing facilities in Australia.
- Centrifugal:Centrifugal crushers use high-speed rotation to impact and break material, often used for fine reduction and achieving consistent chip sizes.
- Roller:Roller crushers employ rotating rollers to compress and shear material, suitable for processing softer metals or achieving specific particle size distributions.
The segment expanding most quickly is Hammer, driven by the need to process diverse scrap streams efficiently.
Application:
Customer type requirements define the specialized features and capacities demanded from chip crushing equipment across different industrial uses.
- Metal Recycling:This segment involves crushing metal swarf, turnings, and other scrap from machining operations to facilitate efficient melting and material recovery. The largest application demand comes from automotive manufacturing plants in Mexico, which generate vast quantities of aluminum and steel scrap.
- Electronic Waste Management:Chip crushers in this application are designed to liberate valuable metals and components from discarded electronic devices, supporting urban mining initiatives. This segment represents the fastest-growing trajectory, driven by component recovery mandates under the EU Waste Framework Directive.
- Plastic Recycling:Crushers in this area process plastic waste into smaller flakes or granules for reprocessing, contributing to circular economy efforts.
- Wood Processing:These crushers reduce wood waste, such as chips and sawdust, for biomass fuel or composite material production.
Growth is primarily concentrated in Metal Recycling, while Electronic Waste Management shows significant potential.
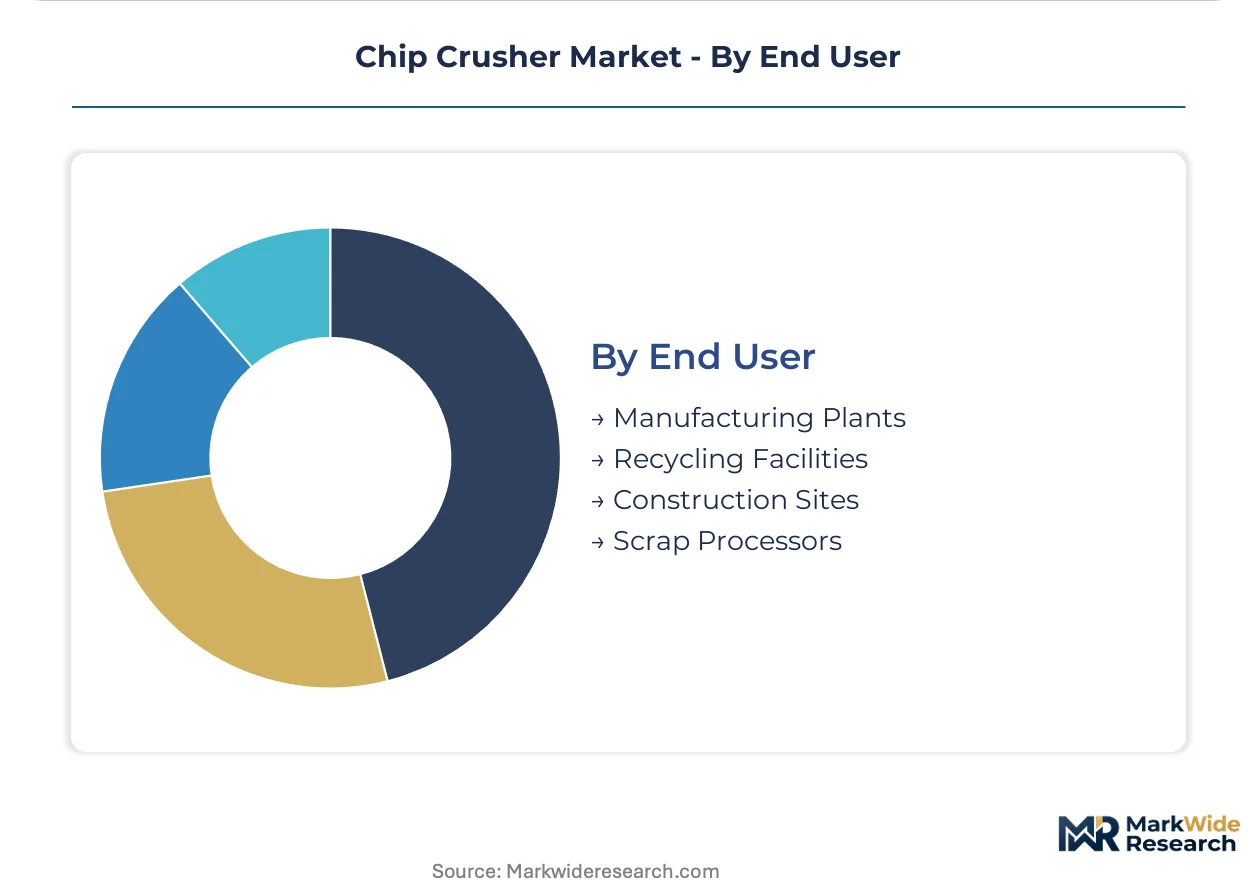
End User:
Margin sensitivity and operational scale dictate the type and sophistication of chip crushing systems adopted by various end-user categories.
- Manufacturing Plants:These facilities integrate chip crushers directly into their production lines to manage metal swarf generated by CNC machines, prioritizing automation and fluid reclamation. Large aerospace manufacturers in France utilize integrated systems to process high-value titanium and superalloy swarf.
- Recycling Facilities:Operating on a larger scale, these facilities process diverse scrap materials from multiple sources, requiring high-capacity and adaptable crushing solutions. Commercial recycling centers in China deploy robust crushers to meet national MEE industrial efficiency targets.
- Scrap Processors:These entities collect and pre-process various metal scraps before sending them to larger recycling facilities or smelters.
- Construction Sites:Chip crushers on construction sites primarily handle metal waste generated during demolition or fabrication, often requiring mobile or semi-mobile units.
The dominant end-user segment remains Manufacturing Plants, with Recycling Facilities demonstrating emerging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced manufacturing and automotive sectors drive significant demand for advanced chip crushing equipment. This region leads in adopting integrated scrap management systems, prioritizing both material recovery and energy efficiency. Regulatory frameworks across Europe further compel investment in sophisticated recycling technologies.
Germany
The German automotive industry requires continuous operation and reduced energy consumption from chip crushers. The EU's Circular Economy Action Plan directly influences equipment purchasing decisions for higher recycling rates. Stuttgart and Bavaria's industrial clusters heavily invest in electric crushers for efficient scrap management.
United States
Large-scale metal recycling operations and diverse ferrous and non-ferrous inputs define demand in the United States. US EPA's rules on solid waste management compel manufacturers to process scrap metal responsibly. Automotive plants across the Southern United States and Midwest industrial zones integrate advanced crushing systems.
China
Industrial efficiency targets and ambitious metal recycling goals propel the chip crusher market in China. China's MEE enforces standards that encourage metal recycling under its "dual carbon" policy. Major industrial cities within the Yangtze River Delta deploy robust crushers to meet these national objectives.
Mexico
Automotive manufacturing plants generate vast quantities of aluminum and steel scrap, creating substantial demand in Mexico. Environmental regulations for industrial waste management increasingly shape equipment procurement in the country. Central Mexico and northern border states see significant investment in integrated chip crushing systems.
Japan
Advanced manufacturing and a focus on high-value material recovery, including e-waste, characterize the Japanese market. METI initiatives for resource recycling and waste reduction influence the adoption of specialized crushing technologies. The Tokyo metropolitan area and other industrial regions prioritize crushers with consistent chip size output.
Chip Crusher Market Key Industry Players
Strategic specialization dominates the current landscape, as companies differentiate through integrated solutions or high-capacity offerings. The market structure features a mix of established industrial equipment manufacturers and niche technology providers. Strategic partnerships and continuous technology development represent dominant competitive moves among market participants.
Among leading equipment providers, Mayfran International leverages its integrated conveyor and processing systems, exemplifying a comprehensive solutions approach. PRAB occupies a position focused on customized solutions tailored for specific alloy scrap types. Stedman Machine Company anchors the high-capacity segment, providing crushers for large-scale recycling facilities.
| Leading Market Players |
|---|
| ARS Corporation |
| Mayfran International |
| PRAB |
| Hammermills International |
| Stedman Machine Company |
| Endo Kogyo Co., Ltd. |
| Cometel Co., Ltd. |
| Lubriserv Solutions Pvt. Ltd. |
| MGS Technologies Pty Ltd |
| Others |
Cost & Logistics Intelligence
Vertical integration into component manufacturing anchors both the supply position for specialized chip crusher parts and the pricing power for leading equipment providers. This integration allows manufacturers to control critical input costs and maintain competitive pricing.
Pricing Analysis
Input cost pass-through for wear components significantly impacts chip crusher pricing. The dominant pricing structure is contract-based long-term offtake for large recycling facilities. Price differentiation stems from customization levels for specific alloy processing and after-sales service bundles. Volatile energy costs drive pricing pressure for electric crushers. Small and medium-sized machine shops exhibit the highest price sensitivity for basic models.
Supply Chain Analysis
Domestic content mandates in Germany reshape sourcing for specialized components in electric crushers. Geographic supply concentrates in Germany, Japan, and China for high-precision parts. Raw material dependencies include specialized alloys for wear components and electronic control units. Single-source vulnerability for advanced sensor technology represents a structural risk. Downstream distribution runs through direct sales channels to large manufacturers and specialized distributors for smaller operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a stable compounder, driven by continuous material recovery efforts across industrial sectors. Mandated recycling targets ensure steady demand for advanced processing equipment.
For Market Incumbents: Anchor market share by investing in predictive maintenance solutions for existing installed bases. Develop modular crusher designs that adapt to new alloy compositions, mitigating the threat from specialized niche entrants. Leverage vertical integration into wear component manufacturing to control material costs. Expand service agreements to capture recurring revenue streams.
For New Entrants and Emerging Players: Enter via specialized electronic waste processing solutions, targeting component recovery mandates under the EU Waste Framework Directive. Focus on developing pneumatic crushers for hazardous or smaller-scale operations in emerging markets. A go-to-market angle involves offering integrated fluid reclamation systems as a bundled solution. The e-waste management segment represents the most penetrable application area.
For Investors and Strategic Acquirers: Roll-up economics work for regional recycling facility operators because structural fragmentation exists in local scrap collection. Long-term viability rests on the increasing value of recovered materials and stringent environmental regulations. Acquisition targets include specialized manufacturers of advanced filtration systems. The signal to watch is the consistent adoption rate of IoT-enabled crushers in new industrial plants.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop E-waste Specific Crushers | This initiative captures new revenue streams from component recovery mandates in Europe. |
| Integrated Fluid Reclamation Systems | This enhances product value by offering closed-loop cutting fluid management to automotive plants. |
| Modular Crusher Design | This increases adaptability to diverse material streams like aluminum and titanium alloys. |
| IoT-Enabled Predictive Maintenance | This reduces costly downtime for manufacturing plants and recycling facilities. |
| Strategic Partnerships with System Integrators | This expands market reach by offering comprehensive, turnkey scrap management solutions. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and internal database cross-referencing — were reconciled for comprehensive market understanding. Industry stakeholders, including plant managers, recycling facility operators, and equipment procurement leads, provided critical insights. Secondary data sources encompassed regulatory reports from the US EPA and China's MEE, along with academic studies on material science. Bottom-up and top-down triangulation validated all market figures.
Data-stream reconciliation informed the analytical framework, modeling market dynamics across the projection horizon. Segmentation dimensions included product type, technology, application, end-user, and geographic region. Compound annual growth rates were derived from historical data analysis and projected future demand. Key industry-specific forecast inputs included automotive production forecasts and metal commodity price trends.
Inputs from industry reports and regulatory documents were available through the study window; gaps in emerging alloy processing data introduce uncertainty bands. Forecasts reflect assumptions concerning technological advancements and global economic stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market