
 Thick Film Devices Market | 2026-2036
Thick Film Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Thick Film Devices Market Analytics
East Asian substrate producers is recalibrating output schedules to match automotive order backlogs. Panasonic Corporation leverages vertical integration across ceramic powder and fired resistor operations. Samsung Electronics Co. Ltd anchors high-volume consumer electronics demand through captive display and memory module supply chains. Vishay Intertechnology Inc. competes on precision tolerance bands for aerospace and military specifications.
Thick film devices are electronic components manufactured by screen-printing conductive, resistive, or dielectric pastes onto ceramic substrates, followed by firing at temperatures typically exceeding 850°C to form stable, hermetic circuit elements. These devices serve primarily as passive components and sensor platforms in circuits requiring thermal stability, mechanical durability, and cost-efficient miniaturization. Resistors command the largest product volume due to universal deployment across voltage-divider and current-sensing functions, while sensors represent the fastest-expanding category as exhaust-gas and battery-temperature monitoring requirements multiply. Surface mount technology dominates assembly flows in consumer electronics and automotive control modules, though through-hole formats persist in industrial power equipment where solder-joint mechanical strength remains critical.
FCC equipment authorization rules constrain electromagnetic interference thresholds for thick film components in US telecommunications hardware. REACH substance restrictions in Europe limit cadmium and lead content in conductive pastes, compelling reformulation investments. Japan's METI energy-efficiency benchmarks for industrial drives shape resistor thermal-performance specifications. Stakeholders must monitor evolving automotive functional-safety standards and substrate material qualification timelines to secure design-in positions before platform lock-in solidifies.
Market Dynamics
Automotive electrification is compressing qualification timelines for thick film resistors as OEMs consolidate supplier bases around vertically integrated ceramic substrate manufacturers capable of meeting AEC-Q200 stress-test requirements.
Growth Catalysts
- EV Battery Thermal Monitoring:Cell-level temperature sensing in lithium-ion packs drives sensor demand. Automotive OEMs specify thick film thermistors for cascade failure prevention.
- MIIT Domestic Sourcing Mandates:China's Ministry of Industry and Information Technology standards concentrate procurement within Asia-Pacific manufacturing clusters, accelerating local capacity expansion.
- High-Temperature Resistor Formulations:Ruthenium oxide pastes fired above 850°C enable operation at 200°C ambient. Powertrain electrification multiplies deployment points.
Market Restraints
- Palladium Price Volatility:Conductive paste formulations depend on palladium-silver alloys. Precious metal cost swings compress resistor margin structures unpredictably.
- Substrate Supply Concentration:Alumina ceramic substrate production clusters in Japan and Germany. Single-source dependencies create vulnerability to seismic or energy disruption.
- REACH Cadmium Restrictions:ECHA substance restrictions force paste reformulation. Compliance investments delay new product introductions by 12-18 months.
Strategic Opportunities
- India Automotive Component Localization:PLI scheme incentives for domestic electronics manufacturing attract thick film device investment. OEMs seek qualified second-source suppliers outside China.
- Hydrogen Fuel Cell Stack Monitoring:Proton exchange membrane systems require humidity and temperature sensors. Thick film platforms adapt to corrosive operating environments.
- Aviation Electrification:More Electric Aircraft initiatives specify high-reliability resistors for power distribution. DO-160 qualification opens aerospace aftermarket channels.
Industry Challenges
- Screen-Printing Process Expertise Scarcity:Fired resistor tolerance control requires 10+ year operator experience. Workforce aging out in Japan and Germany threatens yield consistency.
- Automotive Functional Safety Certification:ISO 26262 ASIL compliance for battery management systems demands fault-mode analysis. Documentation burden extends design-in cycles.
- Legacy Through-Hole Equipment Obsolescence:Industrial power equipment maintains solder-joint strength requirements. Supporting aging assembly infrastructure strains maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thick Film Devices Market |
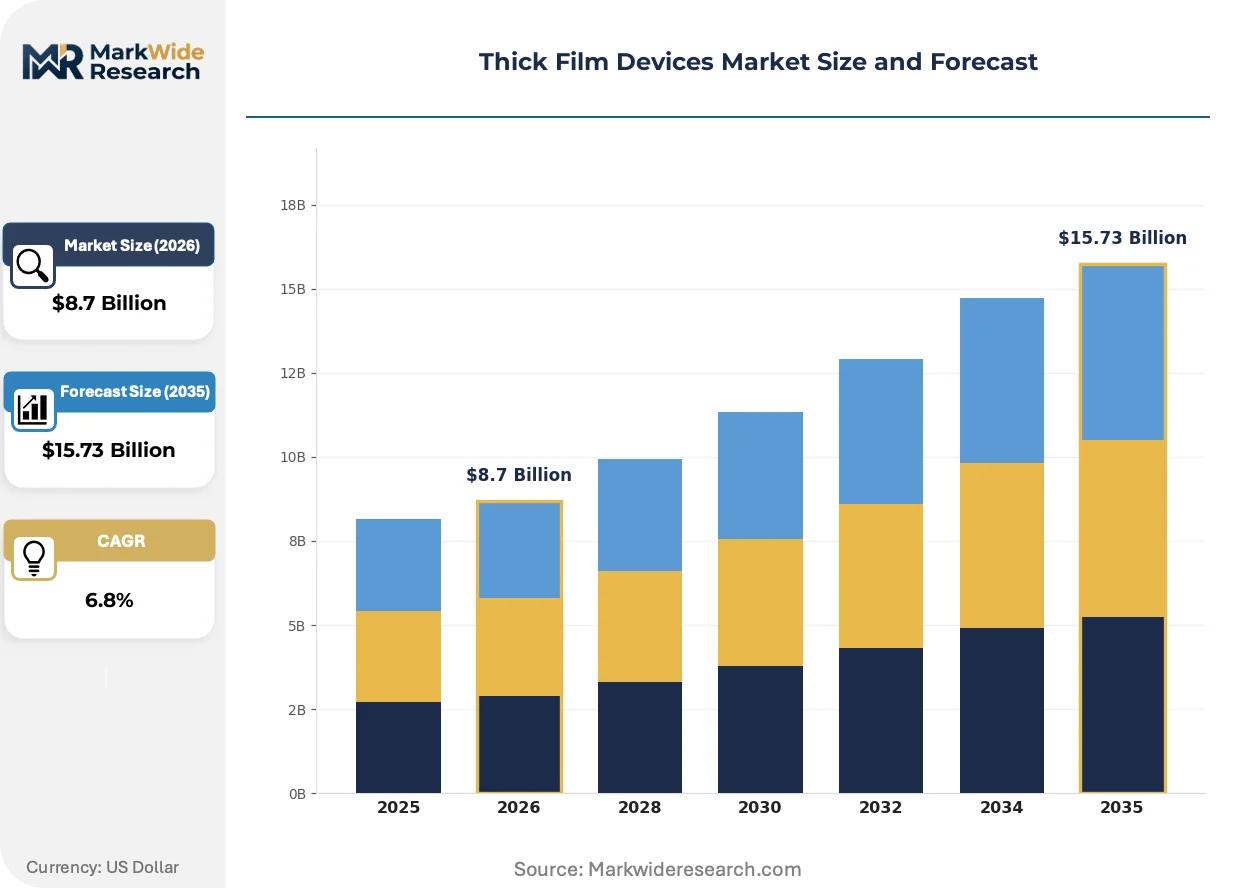
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistors, Capacitors, Inductors, Sensors Application: Consumer Electronics, Automotive, Industrial Equipment, Aerospace Technology: Surface Mount, Through Hole, Hybrid, MEMS End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors |
| Companies Covered | Panasonic Corporation, Samsung Electronics Co. Ltd, TE Connectivity Ltd, Vishay Intertechnology Inc., Rohm Semiconductor GmbH, KOA Speer Electronics Inc., AVX Corporation, Aragonesa de Componentes Pasivos SA, Bourns Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thick Film Devices Market Evolving Landscape
Thick film manufacturing is pivoting toward additive processing techniques that reduce precious metal consumption while expanding substrate material options beyond traditional alumina ceramics.
Copper-nickel alloy pastes are integrating into low-ohmic current-sensing resistor designs. Automotive inverter manufacturers specify these formulations for 150°C continuous operation. The technology is integrating shunt resistors directly into busbar assemblies, eliminating separate component mounting and reducing system inductance.
Japan's METI energy-efficiency benchmarks for industrial motor drives now mandate thermal-loss reduction in power electronics. Manufacturers reformulate resistor pastes to minimize self-heating at full load. Drive OEMs in Osaka and Nagoya prefectures accelerate qualification of next-generation components.
Consolidated procurement by tier-one automotive electronics suppliers is compressing vendor lists. Buyers now require single-source accountability for resistor-sensor combinations. German and Japanese OEMs enforce this preference most strictly, driving mid-tier suppliers toward captive substrate partnerships or exit.
Thick Film Devices Market Segmentation
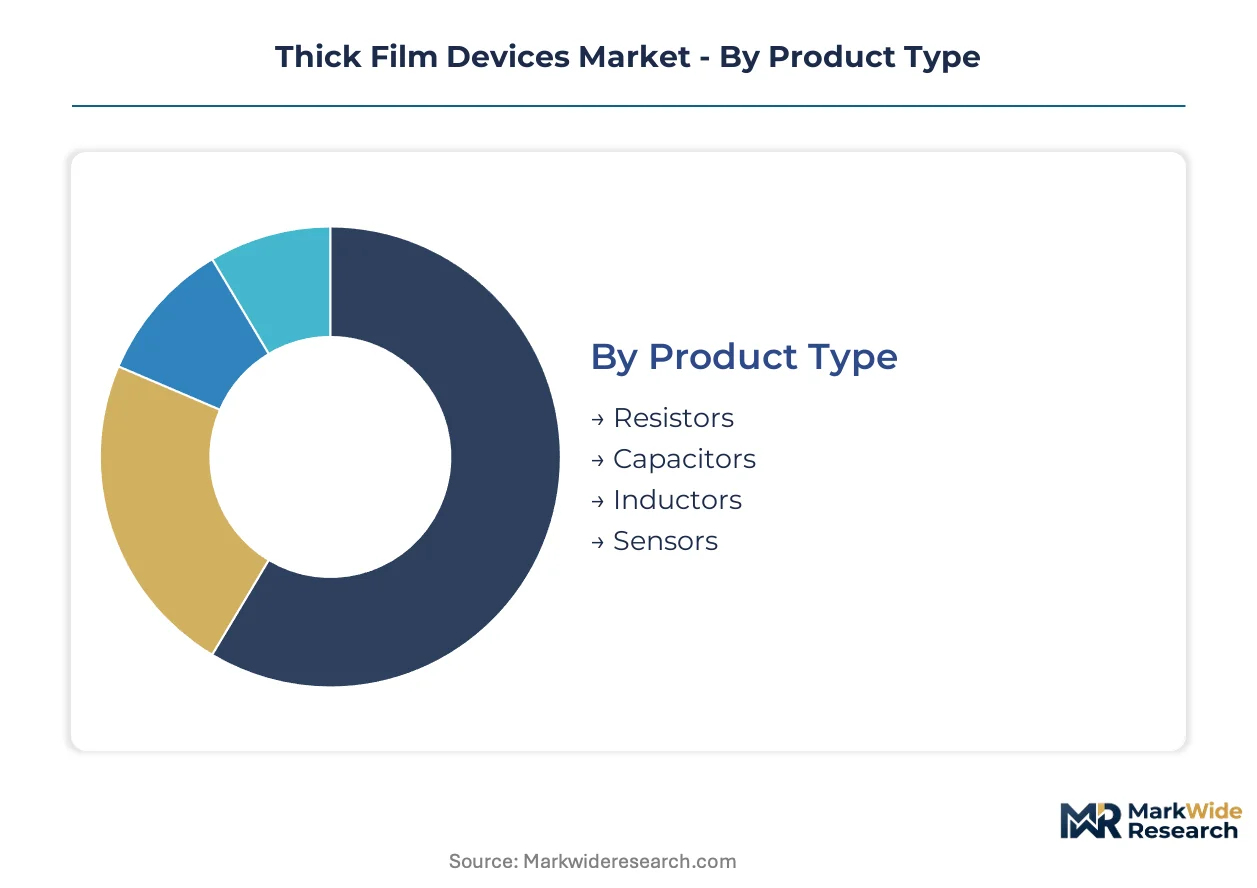
Segmentation in thick film devices reveals how manufacturing capabilities align with divergent thermal, precision, and volume requirements across end-use verticals. Supply chain positioning varies dramatically by segment, with captive substrate production determining competitive access in automotive and aerospace tiers.
Product Type:
Supply concentration in fired resistor operations has consolidated around Japanese and German ceramic substrate producers, creating asymmetric access for capacitor and sensor specialists lacking backward integration.
- Resistors:Ruthenium oxide and palladium-silver pastes screen-printed onto alumina substrates deliver temperature-stable resistance values for voltage division and current sensing. Automotive battery management systems in Germany and Japan specify these components for 200°C ambient operation, with AEC-Q200 qualification timelines compressing to 18 months.
- Sensors:Thermistor and humidity-sensing elements exploit thick film's compatibility with corrosive exhaust and fuel cell environments. Cell-level temperature monitoring in lithium-ion EV packs drives the steepest expansion trajectory, with Chinese MIIT standards accelerating local procurement.
- Capacitors:Dielectric pastes form high-voltage energy storage elements for industrial motor drives. METI efficiency benchmarks in Japan mandate thermal-loss reductions that favor reformulated dielectric compositions.
- Inductors:Ferrite-loaded conductive traces create magnetic components for power filtering. Consumer electronics volume in South Korea sustains high-throughput manufacturing lines.
Today's leader: Resistors. Tomorrow's challenger: Sensors.
Application:
Cost tier stratification separates premium qualification requirements in aerospace from high-volume, price-sensitive procurement in consumer electronics.
- Automotive:Powertrain electrification multiplies resistor deployment points across inverters, DC-DC converters, and battery management systems. OEM consolidation around vertically integrated suppliers in Germany and Japan limits second-source access.
- Consumer Electronics:Display modules and memory subsystems drive surface-mount resistor consumption at extreme scale. Samsung Electronics anchors demand through captive supply chains in South Korea.
- Industrial Equipment:Through-hole formats persist in motor drives and power supplies where solder-joint mechanical strength resists thermal cycling. Aging assembly infrastructure strains maintenance budgets.
- Aerospace:DO-160 environmental qualification and MIL-PRF-55342 precision tolerances command premium pricing. Vishay Intertechnology competes on military-grade reliability bands.
Volume concentrates in Consumer Electronics. Margin concentrates in Aerospace.
Technology:
Customer type determines assembly format, with OEMs enforcing surface-mount standardization while industrial aftermarket procurement sustains through-hole legacy.
- Surface Mount:Miniaturized components attach directly to PCB pads without lead wires, enabling high-density consumer and automotive module assembly. Panasonic Corporation integrates screen-printing through final test for cost control.
- Through Hole:Wire leads insert through drilled holes and solder on opposite sides, delivering mechanical robustness for industrial power equipment. Workforce expertise scarcity in Japan and Germany threatens yield consistency.
- Hybrid:Combinations of thick film passive elements with semiconductor die achieve functional integration. Automotive tier-one suppliers specify these for space-constrained control modules.
- MEMS:Micro-electromechanical structures leverage thick film processing for sensor membranes and heater elements. Hydrogen fuel cell humidity monitoring represents an emerging application vector.
Maturity favors Surface Mount. Innovation investment flows to MEMS.
End User:
Geographic procurement patterns concentrate OEM and tier-one sourcing within Asia-Pacific manufacturing clusters, while distributor channels fragment aftermarket access.
- OEMs:Automotive and aerospace original equipment manufacturers enforce single-source accountability for resistor-sensor combinations. German and Japanese OEMs apply this preference most strictly.
- Tier-1 Suppliers:Delphi, Bosch, and Denso consolidate procurement across multiple resistor specifications, compressing vendor lists to qualified substrate-integrated producers.
- Aftermarket Providers:Repair and replacement demand for industrial equipment sustains through-hole component availability. Inventory carrying costs pressure margin structures.
- Distributors:Arrow Electronics and Avnet buffer volume volatility between manufacturers and fragmented industrial customers. REACH compliance documentation adds administrative burden.
Procurement power consolidates with OEMs. Channel access fragments through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive resistor qualification timelines while Japan sustains ceramic substrate supply chains; both markets enforce stricter vendor consolidation than North American procurement patterns.
United States
Aerospace electrification and telecommunications hardware drive thick film resistor specifications. FCC equipment authorization rules constrain electromagnetic interference thresholds for components in 5G infrastructure. Dallas-Fort Worth and Phoenix manufacturing clusters qualify high-reliability resistors for defense and satellite applications.
Germany
Automotive OEMs consolidate supplier bases around vertically integrated ceramic substrate manufacturers for EV powertrain modules. KBA vehicle-type approval processes enforce AEC-Q200 stress-test compliance for battery management systems. Stuttgart and Munich industrial corridors compress qualification timelines to eighteen months.
China
Domestic EV component sourcing mandates from MIIT concentrate procurement within Asia-Pacific manufacturing clusters. Local capacity expansion accelerates for cell-level temperature sensing in lithium-ion packs. Shenzhen and Suzhou substrate producers recalibrate output schedules to match automotive order backlogs.
Japan
METI energy-efficiency benchmarks for industrial motor drives shape resistor thermal-performance specifications. Screen-printing process expertise scarcity threatens yield consistency as veteran operators age out. Osaka and Nagoya prefectures anchor high-temperature ruthenium oxide paste formulation development.
South Korea
Display modules and memory subsystems drive surface-mount resistor consumption at extreme scale. Captive supply chains integrate screen-printing through final test for cost control. Seoul Capital Area manufacturing lines sustain high-throughput consumer electronics volume.
Thick Film Devices Market Competitive Landscape
Japanese producers anchor one tier; German specialists hold qualification-intensive automotive positions. The vendor base separates into substrate-integrated manufacturers, precision-tolerance specialists, and high-volume consumer electronics suppliers. Three strategic archetypes dominate: vertically integrated ceramic powder-to-resistor operators, precision aerospace-grade fabricators, and scale-driven display module suppliers. Competitive moves concentrate on captive substrate partnerships and automotive functional-safety certification acceleration.
Among Japan-based fabricators, Panasonic Corporation and KOA Speer Electronics Inc. occupy positions within the substrate-integrated tier, exemplifying backward integration from ceramic powder through fired resistor operations. Vishay Intertechnology Inc. represents the precision-specialist archetype, sitting within qualification-intensive segments where tolerance bands command premium positioning. Samsung Electronics Co. Ltd anchors the scale-driven vector, its captive display and memory supply chains absorbing high-volume resistor throughput.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Samsung Electronics Co. Ltd |
| TE Connectivity Ltd |
| Vishay Intertechnology Inc. |
| Rohm Semiconductor GmbH |
| KOA Speer Electronics Inc. |
| AVX Corporation |
| Aragonesa de Componentes Pasivos SA |
| Bourns Inc. |
| Others |
Value Network & Pricing Analysis
Palladium spot price volatility cascades through thick film resistor manufacturing into three distinct procurement tiers. Automotive OEMs absorb premium pricing for AEC-Q200 qualified components while industrial buyers face commodity-grade cost compression, with distributor markups widening spreads between captive substrate-integrated suppliers and merchant resistor fabricators.
Pricing Analysis
Distributor margins compress the effective price realization for mid-tier resistor manufacturers serving fragmented industrial accounts. Three-tier pricing structure across aerospace-grade precision, automotive-qualified standard, and consumer-economy bulk separates Vishay's military tolerance bands from Panasonic's captive automotive flows and Samsung's display module scale. Cost compression in consumer electronics reflects Samsung's vertical integration, while pricing pressure in automotive stems from OEM consolidation around substrate-integrated suppliers. Tier-one automotive electronics buyers exhibit lowest price sensitivity due to single-source accountability requirements; aftermarket distributors face highest sensitivity from inventory carrying cost burdens.
Supply Chain Analysis
Screen-printing operator scarcity in Osaka and Nagoya prefectures threatens yield consistency for ruthenium oxide paste formulations. Alumina ceramic substrate production clusters in Japan and Germany, with Shenzhen and Suzhou capacity expanding under MIIT domestic sourcing mandates. Conductive paste formulations draw from palladium-silver alloys, ruthenium oxide powders, and copper-nickel alternatives. Single-source vulnerability concentrates in Japanese ceramic powder suppliers. Distribution runs through Arrow Electronics and Avnet for fragmented industrial demand, while automotive OEMs enforce direct procurement with substrate-integrated manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thick film devices represent a late-cycle quality story as automotive electrification shifts procurement toward AEC-Q200 qualified components with compressed eighteen-month qualification timelines. Premium specifications now dominate design-in decisions over pure cost optimization.
For Market Incumbents: Acquire ceramic substrate fabrication assets to secure captive supply for automotive resistor-sensor combinations. Consolidate around vertically integrated operations in Germany and Japan before OEM vendor lists lock. Screen-printing workforce aging in Osaka threatens yield consistency; automated inspection systems offset expertise scarcity. METI efficiency benchmarks and REACH cadmium restrictions demand paste reformulation R&D investment to maintain qualification positions.
For New Entrants and Emerging Players: India's PLI scheme for domestic electronics manufacturing opens a window for qualified second-source positioning outside China. Target hydrogen fuel cell humidity sensor applications where thick film platforms adapt to corrosive environments without entrenched incumbent relationships. Pursue DO-160 qualification for aviation electrification aftermarket channels as More Electric Aircraft initiatives multiply resistor deployment points.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision-tolerance specialists holding aerospace and military qualification bands. Five-to-ten year viability hinges on automotive functional-safety certification acceleration and substrate material qualification timelines. Watch for OEM consolidation announcements compressing vendor lists to three qualified suppliers per resistor specification as the inflection signal for portfolio rebalancing toward substrate-integrated archetypes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive alumina supply secures AEC-Q200 qualification timelines for German and Japanese OEMs. |
| Copper-Nickel Paste Formulation Development | Low-ohmic current-sensing designs meet 150°C automotive inverter specifications. |
| Hydrogen Fuel Cell Sensor Platform Launch | Thick film humidity monitoring captures proton exchange membrane system demand. |
| Automotive Functional Safety Certification Acceleration | ISO 26262 ASIL compliance compresses design-in cycles before platform lock-in solidifies. |
| India Manufacturing Footprint Establishment | PLI scheme incentives attract second-source qualification for EV component procurement. |
Research Methodology
Coverage spans Germany, Japan, China, South Korea, and the United States, with primary inputs from each regional manufacturing cluster. The analysis combines structured interviews with thick film device procurement managers at Tier 1 automotive suppliers, ceramic substrate plant managers in Osaka and Nagoya, resistor R&D directors, and distributor inventory planners at Arrow Electronics and Avnet. Secondary validation draws from METI energy-efficiency filings, ECHA REACH substance restriction updates, MIIT domestic sourcing mandate documentation, and AEC-Q200 stress-test qualification records. Bottom-up segment sizing triangulates against top-down OEM procurement budget allocations.
Product-level granularity models resistors, sensors, capacitors, and inductors across surface mount, through-hole, hybrid, and MEMS technology formats. Application segmentation captures automotive powertrain electrification, consumer electronics display modules, industrial motor drives, and aerospace power distribution. End-user archetypes include OEMs, Tier 1 suppliers, aftermarket providers, and distributors. CAGRs derive from automotive EV production forecasts, cell-level temperature sensor penetration rates, and substrate capacity expansion announcements. Palladium price trajectory assumptions and REACH compliance timeline estimates inform margin sensitivity analysis.
Revisions become necessary when palladium price volatility exceeds historical bands, automotive OEM vendor consolidation accelerates beyond modeled timelines, or substrate supply disruptions in Japan and Germany materialize. Forecasts reflect documented assumptions regarding MIIT domestic sourcing enforcement and METI efficiency benchmark adoption rates. Material deviation in precious metal costs, qualification timeline compression, or regulatory restriction scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
North America Silicon Carbide Wafers Market