
 COF (Chip-On-Film) Market | 2026-2036
COF (Chip-On-Film) Market Size, Share, and Industry Trends Forecast 2026-2036
COF (Chip-On-Film) Market Insights
Subscription-based yield-analytics software is recalibrating how COF suppliers monetize production lines beyond unit sales. Samsung Electronics leverages in-house semiconductor and display integration to control captive COF demand. Fujikura anchors its position through specialized fine-pitch interconnect R&D for high-resolution panels. Chipbond Technology differentiates via concentrated capacity in Taiwan's flexible circuit ecosystem.
Chip-on-film denotes an advanced packaging method where bare integrated circuits mount directly onto flexible polyimide film substrates, typically achieving trace pitches below 20 micrometers through roll-to-roll photolithography and electroplating processes. The technique enables dynamic folding in smartphones, foldable tablets, and curved automotive instrument clusters by replacing rigid PCB interconnects with compliant film carriers. Display driver ICs represent the dominant product category, with hybrid bonding technology commanding premium positioning due to its superior thermal and electrical performance at sub-10-micron pitches. Consumer electronics absorbs the largest application volume, though automotive displays exhibit the steepest trajectory as cabin digitization accelerates across OEM specifications.
South Korea's Ministry of Trade, Industry and Energy enforces domestic content requirements that shape local COF procurement patterns for national display champions. Japan's Ministry of Economy, Trade and Industry administers JIS standards governing flexible circuit reliability, directly affecting export eligibility for regional suppliers. China's SAMR implements GB standards on electronics materials that constrain film chemistry and bonding adhesive formulations for products entering its domestic market. Stakeholders must track how divergent national certification regimes fragment qualification timelines and determine where to stage pilot production capacity.
Market Dynamics
Bezel-less display architectures in smartphones and foldable devices are compressing interconnect margins while demanding finer pitch capabilities, forcing COF suppliers to reconfigure capital allocation toward roll-to-roll photolithography scale-up.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement of electronics waste rules is accelerating adoption of material-efficient bonding processes that reduce polyimide film waste in high-volume manufacturing.
- Automotive cabin digitization:Curved instrument clusters and head-up displays are absorbing COF interconnects at steeper rates than traditional flat panels, with tier-one automotive suppliers qualifying flexible film carriers for vibration-resistant applications.
- Hybrid bonding maturation:Sub-10-micron pitch interconnect technology is displacing wire-bonded alternatives in high-resolution OLED panels through superior thermal dissipation and signal integrity.
Market Restraints
- Copper and polyimide cost volatility:Raw material price swings for electroplated copper traces and high-temperature polyimide substrates compress gross margins during contract renegotiation cycles.
- East Asian supply concentration:Over 80 percent of qualified COF capacity sits within South Korea's Gyeonggi Province and Taiwan's flexible circuit corridor, creating geographic risk exposure for display OEMs.
- Rigid PCB substitution in cost-sensitive segments:Mid-tier television and monitor manufacturers retain wire-bonded or rigid-flex alternatives where bezel reduction delivers insufficient consumer price premium.
Strategic Opportunities
- India display manufacturing incentives:The country's PLI scheme for semiconductor and display fabrication is attracting COF qualification programs for domestic panel assembly lines.
- Medical imaging displays:Diagnostic monitors requiring extreme color accuracy and long flex-cycles present premium positioning for fine-pitch COF interconnects with extended reliability certification.
- EU Green Deal alignment:REACH-compliant adhesive formulations and halogen-free polyimide substrates open qualification pathways for European automotive display suppliers.
Industry Challenges
- Roll-to-roll photolithography talent scarcity:Process engineers with expertise in continuous-web patterning for sub-20-micron features command premium compensation and limited geographic mobility.
- Multi-regional certification timelines:Simultaneous qualification against South Korea's domestic content requirements, Japan's JIS reliability standards, and China's GB material specifications fragments pilot production staging.
- Legacy wire-bonding equipment stranding:Display driver IC houses face capital write-down pressure where COF conversion outpaces depreciation schedules for existing thermosonic bonding lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | COF (Chip-On-Film) Market |
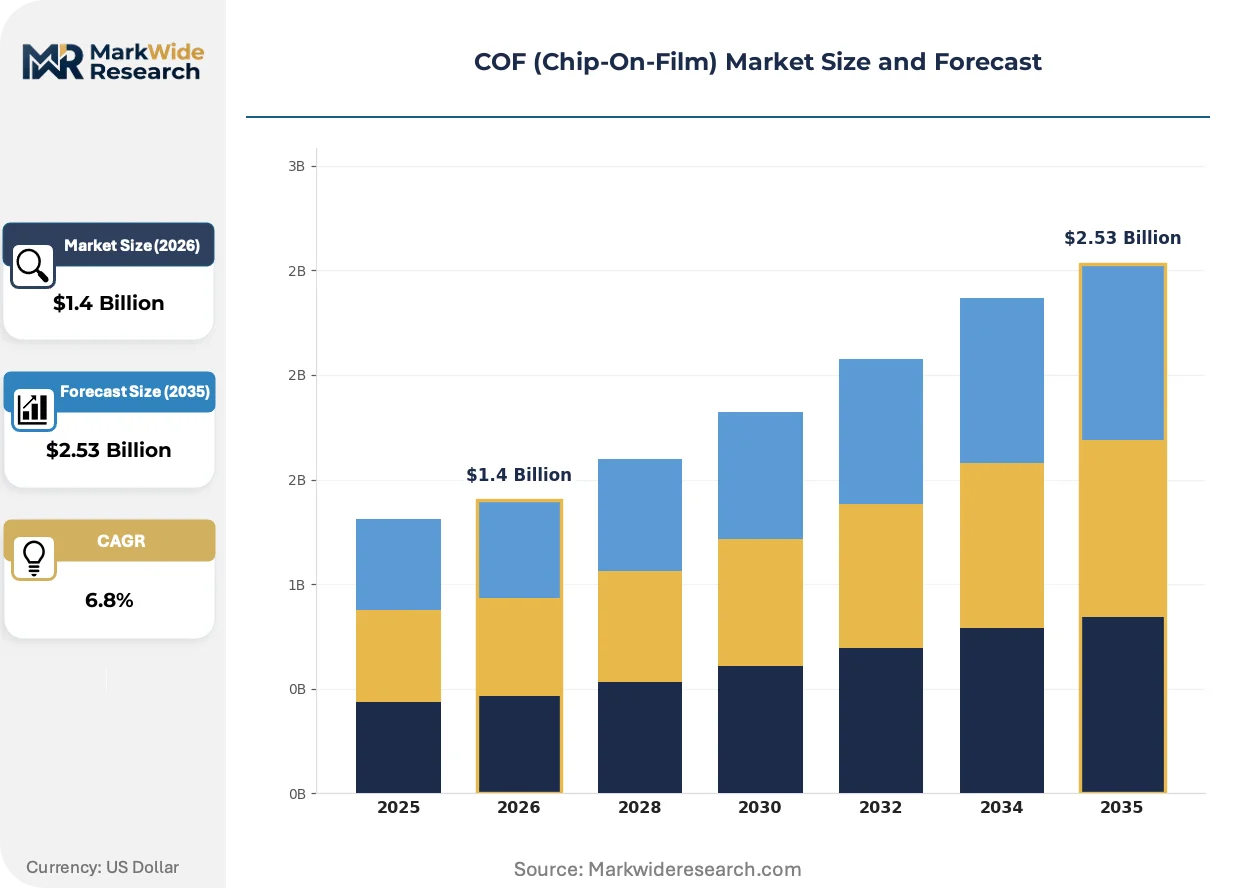
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Circuits, Sensors, Display Drivers, Other Technology: Hybrid Bonding, Thermal Compression, Laser Bonding, Other Application: Consumer Electronics, Automotive Displays, Medical Devices, Industrial Equipment End User: OEMs, Contract Manufacturers, Technology Firms, Others |
| Companies Covered | Samsung Electronics, LG Display, Stemco, Flexium Interconnect, Chipbond Technology, Fujikura, Toppan Printing, Sumitomo Bakelite, Nitto Denko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
COF (Chip-On-Film) Market Trends and Innovations
Process automation and materials science advances are compressing development cycles for next-generation flexible interconnects, with supplier R&D priorities diverging between consumer electronics miniaturization and automotive reliability demands.
Anisotropic conductive film bonding is absorbing thermal compression bonding market share in smartphone display assembly. Tier-one panel manufacturers in South Korea and China are converting high-volume lines to ACF processes for sub-35-micron pad pitches. The technology is absorbing equipment investment that previously targeted thermosonic wire bonding, compressing qualification timelines for new display driver IC packages.
Japan's METI has tightened JIS C 5016 flexible circuit reliability standards to include accelerated flex-cycle testing under combined thermal and humidity stress. The revision disqualifies legacy polyimide formulations for automotive export eligibility. European automotive display suppliers are responding by dual-qualifying Japanese and domestic adhesive systems against the updated specification.
Subscription-based yield analytics software is displacing perpetual licensing in COF manufacturing equipment sales. Display panel OEMs in Taiwan and South Korea now demand real-time defect prediction bundled with bonding machine contracts. This shift concentrates procurement authority within semiconductor process engineering teams rather than traditional capital equipment purchasing functions.
COF (Chip-On-Film) Market Segmentation
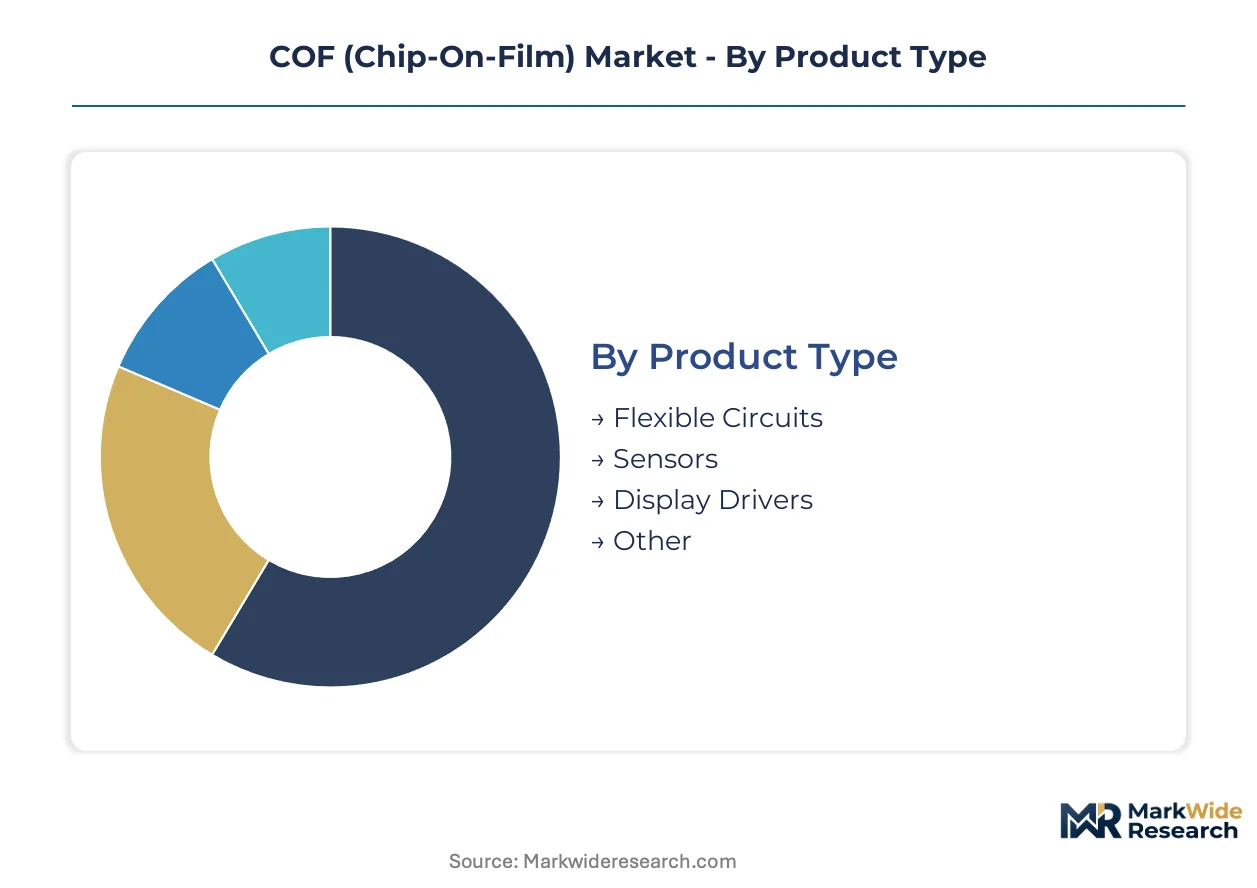
COF segmentation reflects divergent technical requirements across display resolution tiers, bonding precision thresholds, and regulatory compliance burdens. Buyers select product categories and technologies based on pitch specifications, thermal performance, and qualification timelines rather than unit cost alone.
Product Type:
Procurement patterns in this category track directly to panel resolution roadmaps and flex-cycle durability requirements.
- Display Drivers:These integrated circuits manage pixel activation timing and voltage distribution for LCD and OLED panels, achieving trace pitches below 20 micrometers through roll-to-roll photolithography. Samsung Electronics and LG Display in South Korea's Gyeonggi Province anchor captive demand for high-density interconnects as bezel-less smartphone designs compress driver IC mounting margins.
- Flexible Circuits:Polyimide film substrates with electroplated copper traces enable dynamic folding in foldable tablets and curved automotive instrument clusters. China's SAMR enforcement of GB material specifications constrains adhesive chemistry for products entering domestic assembly lines, lengthening qualification cycles for foreign suppliers.
- Sensors:Capacitive and biometric sensing elements mount on compliant film carriers for touch-responsive interfaces in medical imaging equipment.
- Other:Specialized interconnects for niche applications including RF antenna modules and power management distribution.
Volume sits with Display Drivers; growth tilts toward Flexible Circuits.
Technology:
Capital allocation across bonding methods reflects the trade-off between pitch resolution and throughput speed in high-volume manufacturing.
- Hybrid Bonding:Direct copper-to-copper interconnects at sub-10-micron pitches deliver superior thermal dissipation and signal integrity for high-resolution OLED panels. South Korean panel manufacturers are displacing wire-bonded alternatives in premium smartphone lines, though equipment costs and process control complexity limit adoption to flagship tier production.
- Thermal Compression:Heat-activated adhesive bonding dominates mid-tier display assembly with established equipment depreciation schedules and broader process windows. Taiwan's flexible circuit corridor retains concentrated capacity for this mature technology, serving cost-sensitive monitor and television applications where bezel reduction delivers insufficient consumer price premium.
- Laser Bonding:Non-contact energy delivery enables selective heating for temperature-sensitive film substrates in medical device interconnects.
- Other:Emerging techniques including ultrasonic and plasma-activated bonding for experimental form factors.
Revenue concentrates with Hybrid Bonding; expansion accelerates fastest in Thermal Compression retrofit programs.
Application:
End-use selection criteria diverge sharply between consumer electronics prioritizing miniaturization and automotive segments demanding vibration resistance.
- Consumer Electronics:Smartphones, foldable tablets, and wearable devices absorb the largest application volume, with OEMs in East Asia specifying finer pitch capabilities for bezel-less display architectures. Japan's METI-administered JIS C 5016 reliability standards govern flex-cycle performance under combined thermal and humidity stress, directly affecting export eligibility for regional suppliers.
- Automotive Displays:Curved instrument clusters and head-up displays are climbing the fastest as cabin digitization accelerates across OEM specifications. Tier-one automotive suppliers in Europe are dual-qualifying adhesive systems against REACH-compliant formulations and updated JIS standards for vibration-resistant flexible film carriers.
- Medical Devices:Diagnostic monitors requiring extreme color accuracy and extended flex-cycles present premium positioning for fine-pitch interconnects with specialized reliability certification.
- Industrial Equipment:Harsh-environment displays for manufacturing automation and outdoor signage applications.
Shipment volume favors Consumer Electronics; steepest expansion trajectory belongs to Automotive Displays.
End User:
Procurement authority concentration varies with integration depth and captive manufacturing scale.
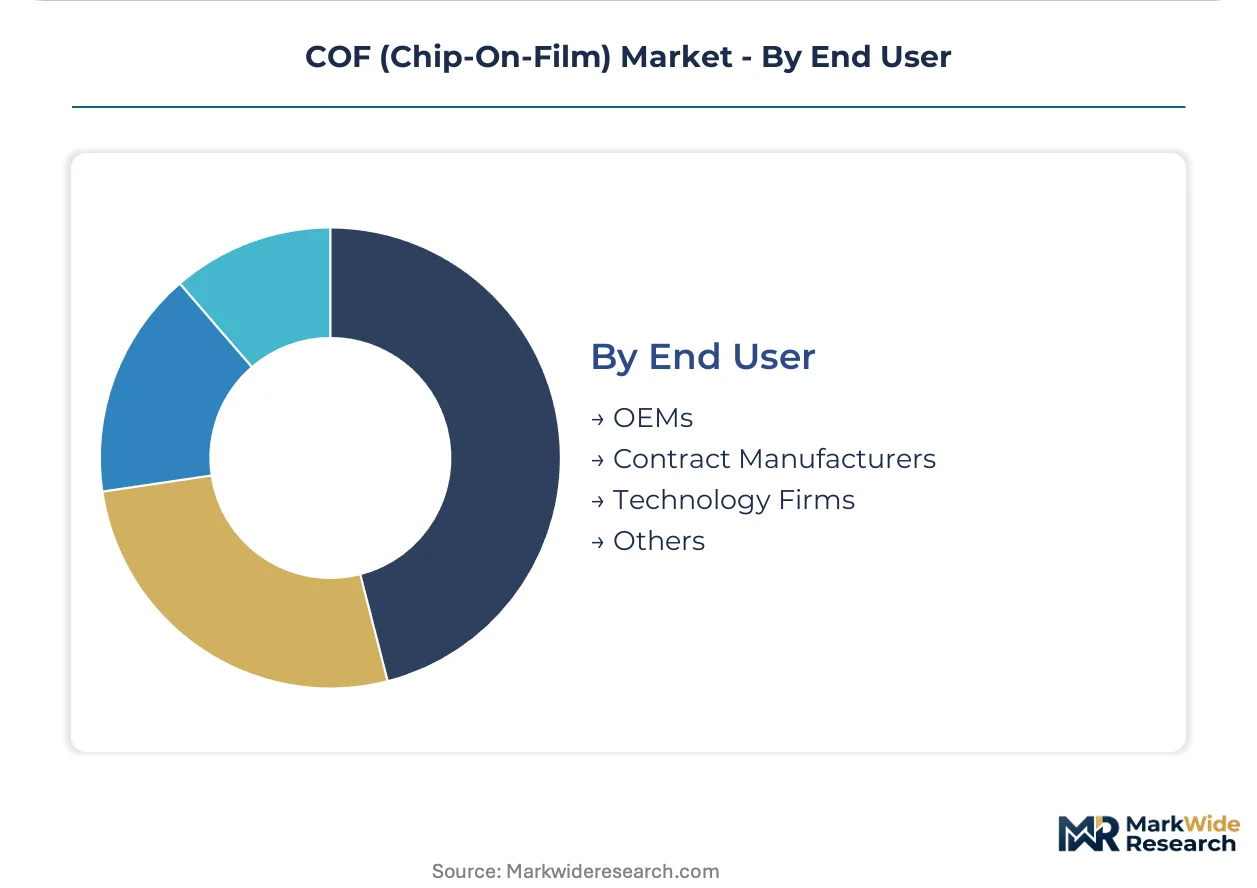
- OEMs:Vertically integrated display manufacturers including Samsung Electronics and LG Display control captive COF demand through in-house semiconductor and display integration, bypassing merchant market suppliers for high-volume smartphone and television programs.
- Contract Manufacturers:EMS providers in Taiwan and China manage COF procurement for mid-tier panel assemblers without internal bonding capability, consolidating purchasing authority within semiconductor process engineering teams rather than traditional capital equipment functions.
- Technology Firms:Specialized developers of foldable devices and experimental form factors sourcing limited volumes for prototype qualification.
- Others:Research institutions and niche equipment builders with irregular procurement patterns.
Transaction volume rests with OEMs; merchant market expansion tilts toward Contract Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi Province anchors global COF manufacturing concentration, with Samsung Electronics and LG Display driving captive demand for high-density interconnects in bezel-less display production.
South Korea
Seoul Capital Area display fabs consume the majority of fine-pitch COF output for smartphone OLED panels. The Ministry of Trade, Industry and Energy enforces domestic content requirements that shape procurement patterns for national display champions. Gyeonggi Province hosts concentrated bonding capacity serving Samsung Electronics' vertical integration strategy.
China
Panel manufacturers in the Yangtze River Delta are expanding COF qualification for domestic television and automotive display lines. SAMR-administered GB standards constrain film chemistry and adhesive formulations for products entering the domestic market. Shenzhen and Dongguan clusters are attracting regional substrate suppliers to reduce import dependency.
Japan
Specialized fine-pitch interconnect R&D concentrates in Tokyo and Osaka metropolitan areas for high-resolution panel applications. METI tightened JIS C 5016 reliability standards to include accelerated flex-cycle testing under combined thermal and humidity stress. Nagoya-based material suppliers are reformulating polyimide substrates to meet updated automotive export eligibility.
Taiwan
Chipbond Technology anchors concentrated capacity in the Hsinchu Science Park flexible circuit ecosystem. The island's semiconductor process engineering talent pool supports roll-to-roll photolithography scale-up for sub-20-micron features. Taichung and Tainan are emerging as secondary clusters for thermal compression bonding serving mid-tier display assembly.
India
Display panel OEMs are initiating COF qualification programs under the PLI scheme for semiconductor and display fabrication. The country's national electronics regulator is aligning certification timelines with import substitution targets for domestic panel assembly lines. Maharashtra and Karnataka are staging pilot production capacity for tier-one automotive display suppliers.
COF (Chip-On-Film) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across bonding equipment and substrate fabrication tiers. The structure consolidates around captive display manufacturer demand in South Korea and merchant supplier networks in Taiwan and Japan. Three archetypes dominate: vertically integrated display OEMs controlling in-house semiconductor bonding, specialized flexible circuit fabricators with concentrated roll-to-roll capacity, and diversified materials conglomerates supplying polyimide films and adhesive systems. Competitive moves center on hybrid bonding technology licensing and geographic capacity expansion into India under production-linked incentive schemes.
Among Korea-based integrated manufacturers, Samsung Electronics and LG Display exemplify the captive-demand archetype through in-house semiconductor and display integration. Fujikura occupies a position within the specialized interconnect tier, representing Japanese fine-pitch R&D concentration for high-resolution panel applications. Chipbond Technology anchors the Taiwan-based merchant supplier segment, sitting within the flexible circuit ecosystem that serves contract manufacturers without internal bonding capability.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| Stemco |
| Flexium Interconnect |
| Chipbond Technology |
| Fujikura |
| Toppan Printing |
| Sumitomo Bakelite |
| Nitto Denko |
| Others |
Pricing and Supply Chain Analysis
Roll-to-roll photolithography scale-up for sub-20-micron trace pitches is simultaneously elevating capital intensity and concentrating procurement leverage among South Korean and Taiwanese display manufacturers with qualified bonding capacity. China's SAMR-enforced GB material specifications and Japan's METI-administered JIS reliability standards are fragmenting qualification timelines, forcing buyers to absorb premium pricing for multi-regional certified substrates.
Pricing Analysis
Yield-analytics software subscriptions tied to real-time defect prediction anchor value-based pricing for COF bonding equipment, displacing perpetual licensing models. Three-tier pricing structure across premium hybrid-bonding systems, standard thermal-compression lines, and economy-grade legacy equipment reflects certification grade and after-sales service bundling. Cost compression in mid-tier thermal compression segments is intensifying because Taiwan's flexible circuit corridor retains depreciated capacity serving cost-sensitive monitor applications. Contract manufacturers exhibit highest price sensitivity; vertically integrated OEMs like Samsung Electronics demonstrate lowest sensitivity due to captive demand absorption.
Supply Chain Analysis
Dual-sourcing requirements mandated by European automotive display suppliers and South Korean panel OEMs are compelling qualification programs across Japanese polyimide substrate providers and Taiwanese flexible circuit fabricators. Geographic supply concentration centers on South Korea's Gyeonggi Province, Taiwan's Hsinchu Science Park, and Japan's Nagoya metropolitan area. Raw material dependencies draw from electroplated copper trace suppliers, high-temperature polyimide film producers, and anisotropic conductive adhesive formulators. Single-source vulnerability persists for sub-10-micron hybrid bonding equipment. Distribution runs through direct procurement relationships between bonding equipment OEMs and display panel manufacturers, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around hybrid bonding technology licensing and captive capacity expansion, with raw material cost volatility and multi-regional certification complexity forcing sub-scale wire-bonding equipment holders toward exit.
For Market Incumbents: Deploy hybrid bonding technology licensing as a defensive lever against emerging Chinese panel manufacturers developing in-house bonding capability. Samsung Electronics and LG Display should deepen upstream control over polyimide substrate supply through qualified Japanese material partnerships, insulating margins from copper and film cost volatility. METI's tightened JIS C 5016 standards present certification investment opportunities that smaller Taiwanese competitors cannot match. For New Entrants and Emerging Players: The premium-economy price-point gap in India's PLI-driven display manufacturing incentives offers white-space entry for COF qualification programs targeting domestic panel assembly lines. Maharashtra and Karnataka pilot production clusters represent the most penetrable geography, with tier-one automotive display suppliers seeking REACH-compliant adhesive alternatives to Japanese formulations. A go-to-market angle centered on halogen-free polyimide substrates for EU Green Deal alignment bypasses incumbent certification advantages in East Asian consumer electronics. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of specialized fine-pitch interconnect R&D assets by diversified materials conglomerates seeking display vertical exposure. Long-term viability over a 5-10 year window favors merchant suppliers with qualified capacity outside South Korea's Gyeonggi concentration. The signal to watch is India's PLI scheme disbursement velocity as an inflection indicator for geographic diversification beyond East Asian supply concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Licensing | South Korean panel manufacturers displace wire-bonded alternatives through sub-10-micron pitch copper interconnects. |
| India PLI Scheme Capacity Qualification | Maharashtra and Karnataka clusters attract COF bonding programs for domestic automotive display assembly. |
| REACH-Compliant Adhesive Reformulation | Nagoya-based material suppliers enable European automotive tier-one qualification against updated JIS standards. |
| Subscription Yield-Analytics Bundling | Taiwanese contract manufacturers shift procurement authority to semiconductor process engineering teams. |
| Roll-to-Roll Photolithography Scale-Up | Hsinchu Science Park ecosystem expands sub-20-micron feature capacity for foldable tablet applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this COF market analysis, combined with primary interviews across display panel procurement directors, semiconductor bonding equipment engineers, flexible circuit plant managers, and polyimide substrate R&D leads. Secondary validation drew from METI JIS standard revision documents, SAMR GB specification releases, South Korean Ministry of Trade domestic content requirement circulars, and Taiwan's Hsinchu Science Park industrial cluster reports. Bottom-up unit shipment estimates and top-down value reconciliation triangulated market sizing across the analysis window.
Data-stream reconciliation across equipment shipment databases, substrate material trade flows, and panel manufacturer capex disclosures informed the analytical framework. Segmentation dimensions modeled include bonding technology tier, application end-use, and regional regulatory cluster. CAGRs were derived from slope analysis of qualified capacity expansion against display resolution roadmaps. Industry-specific forecast inputs incorporated OLED panel production schedules and automotive display digitization specifications from tier-one supplier qualification programs.
Inputs from South Korean and Taiwanese trade associations were available through the study window; gaps in India's emerging PLI scheme disbursement data introduce uncertainty bands for geographic diversification assumptions. Forecasts reflect documented assumptions regarding hybrid bonding adoption curves and raw material cost stabilization. A model refresh is warranted upon material change in China's dual carbon goal enforcement intensity or Japan's JIS reliability standard revision timeline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market