
 Amorphous-Semiconductor Devices Market | 2026-2036
Amorphous-Semiconductor Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Amorphous-Semiconductor Devices Market Outlook
A shortage of thin-film deposition engineers is unwinding capacity expansion timelines at multiple foundries. VACUUMSCHMELZE leverages its European magnetics heritage to anchor amorphous alloy supply for power electronics. Toshiba Materials specializes in high-purity sputtering targets that dominate Japanese display supply chains. China Amorphous Technology competes on scale by operating integrated melt-spinning and annealing lines serving domestic photovoltaic manufacturers.
Amorphous-semiconductor devices are non-crystalline solid-state components fabricated from silicon, germanium, or compound alloys deposited at temperatures below crystallization thresholds, typically achieving hydrogen content of 8-15 atomic percent to passivate dangling bonds and enable field-effect mobility exceeding 1 cm²/Vs for switching applications. Their primary commercial purpose centers on large-area electronic surfaces where crystalline silicon wafer economics fail, enabling flexible substrates and uniform properties across meter-scale dimensions. Thin-film transistors occupy the dominant revenue position due to irreplaceable roles in active-matrix addressing for OLED and LCD panels, while photovoltaic cells capture the fastest expansion trajectory as building-integrated solar architectures multiply. Sensors targeting healthcare imaging devices concentrate margin pools where amorphous selenium's high dark resistivity and stable avalanche gain justify premium positioning against crystalline alternatives.
Japan's METI enforces JIS standards for amorphous alloy magnetic cores in power distribution, while China's MIIT mandates GB certification for semiconductor materials used in state-backed display fab projects. The EU's RoHS and REACH frameworks restrict cadmium and certain dopants in deposited layers, forcing reformulation of chalcogenide compositions for infrared sensor applications. South Korea's MFDS and KATS coordinate medical device approvals where amorphous selenium flat-panel detectors compete for digital radiography tenders. Stakeholders must monitor which regulatory bloc first mandates recyclability standards for amorphous silicon photovoltaic modules, as this will reshape end-of-life collection infrastructure and material recovery economics.
Market Dynamics
Thin-film transistor deployment in automotive display panels is compressing qualification timelines as OEMs electrify cabin electronics, forcing foundries to accelerate hydrogen-passivation process validation while maintaining field-effect mobility thresholds above 1 cm²/Vs.
Growth Catalysts
- REACH material purity mandates:Europe's tightening restrictions on cadmium and heavy-metal dopants in deposited layers are pulling high-purity sputtering target demand from display manufacturers seeking compliant supply chains.
- Building-integrated photovoltaics:Meter-scale flexible substrate architectures are expanding addressable surface area for amorphous silicon cells in commercial glazing systems.
- South Korea's display foundry corridor:Concentrated OEM panel procurement from Seoul-Incheon manufacturing clusters is anchoring active-matrix addressing volume for OLED production ramps.
Market Restraints
- Hydrogen feedstock volatility:Silane gas pricing swings and regional supply interruptions are destabilizing hydrogen-passivation cost structures for dangling-bond termination.
- Japanese sputtering target concentration:Three precision materials suppliers control high-purity chalcogenide deposition sources, creating single-source vulnerability for infrared sensor fabricators.
- Crystalline silicon substitution in utility-scale solar:Perovskite tandem architectures and conventional wafer economics are capping amorphous silicon penetration in ground-mounted installations.
Strategic Opportunities
- India's medical imaging tender pipeline:Digital radiography procurement under CDSCO device classification is opening flat-panel detector deployment for amorphous selenium avalanche-gain applications.
- Dual carbon policy alignment:China's MIIT semiconductor material certification for state-backed display fabs is channeling domestic melt-spinning capacity toward photovoltaic annealing lines.
- Flexible substrate convergence with printed electronics:Roll-to-roll deposition integration with inkjet-patterned interconnects is enabling sub-50-micron bend-radius devices for wearable health monitors.
Industry Challenges
- Thin-film deposition engineer scarcity:Specialized vacuum-process expertise required for plasma-enhanced chemical vapor deposition is extending foundry qualification timelines by 8-14 months.
- JIS-METI certification synchronization:Divergent magnetic core testing protocols between Japan's METI and international IEC standards are fragmenting amorphous alloy power electronics approval pathways.
- Legacy LCD fab retooling complexity:Converting Gen 8.5 crystalline silicon lines to amorphous-semiconductor hydrogen-passivation chambers requires complete vacuum-system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amorphous-Semiconductor Devices Market |
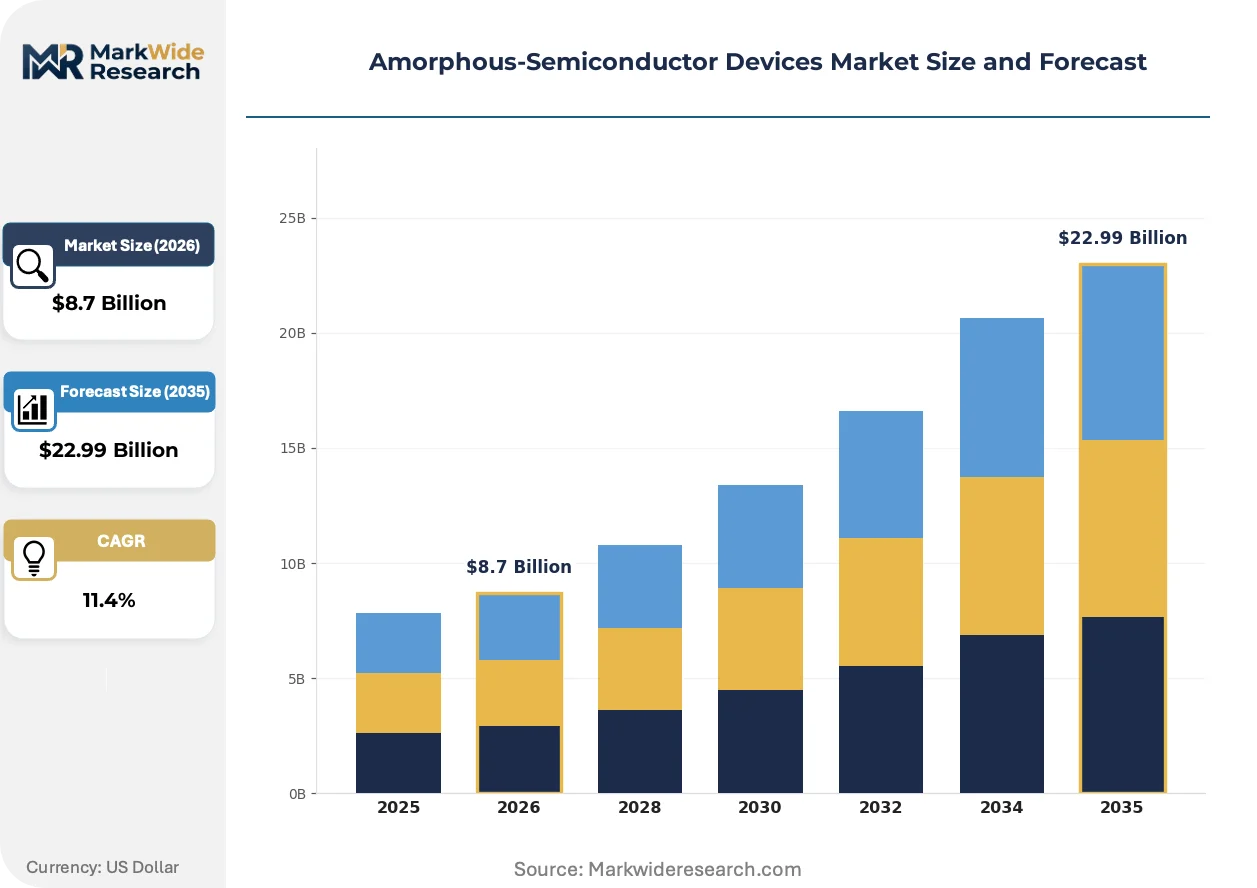
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film Transistor, Photovoltaic Cells, LCDs, Sensors Technology: Chemical Vapor Deposition, Physical Vapor Deposition, Printing Technology, Laser Processing End User: Consumer Electronics, Automotive, Renewable Energy, Healthcare Application: Display Panels, Solar Energy Generation, Imaging Devices, Smart Labels |
| Companies Covered | Hitachi Metals, VACUUMSCHMELZE, Toshiba Materials, Advanced Technology & Materials, China Amorphous Technology, BOMATECH, AMES SA, MK Magnetics, Shin-Etsu Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amorphous-Semiconductor Devices Market Strategic Shifts
Process architecture decisions in display manufacturing are pivoting toward low-temperature deposition compatibility, reframing equipment vendor selection criteria and materials qualification protocols across panel supply chains.
Oxide-semiconductor thin-film transistors employing indium-gallium-zinc oxide active layers are displacing hydrogenated amorphous silicon in smartphone OLED backplanes. Samsung Display and LG Display have completed qualification of IGZO-based variable refresh-rate drivers. This displacement is compressing addressable volume for traditional a-Si:H deposition equipment in premium mobile panels.
Europe's F-Gas Regulation phasedown of hydrofluorocarbon etching chemistries is forcing plasma-process reoptimization for chalcogenide layer patterning. Equipment vendors are retrofitting remote plasma sources to accommodate fluorine-free radical generation. Infrared sensor foundries in Germany and France face the steepest compliance cost escalation due to legacy sulfur-hexafluoride process dependencies.
Automotive OEMs are consolidating display procurement under single-source panel contracts with captive semiconductor-grade material specifications. Tier-1 suppliers lose direct sputtering target negotiation leverage as Hyundai, BMW, and Mercedes-Benz centralize amorphous-alloy magnetic core sourcing for in-cabin power conversion. This concentration is most visible in South Korea and Germany, where electrified vehicle platforms specify integrated cockpit display-electronics packages.
Amorphous-Semiconductor Devices Market Segmentation
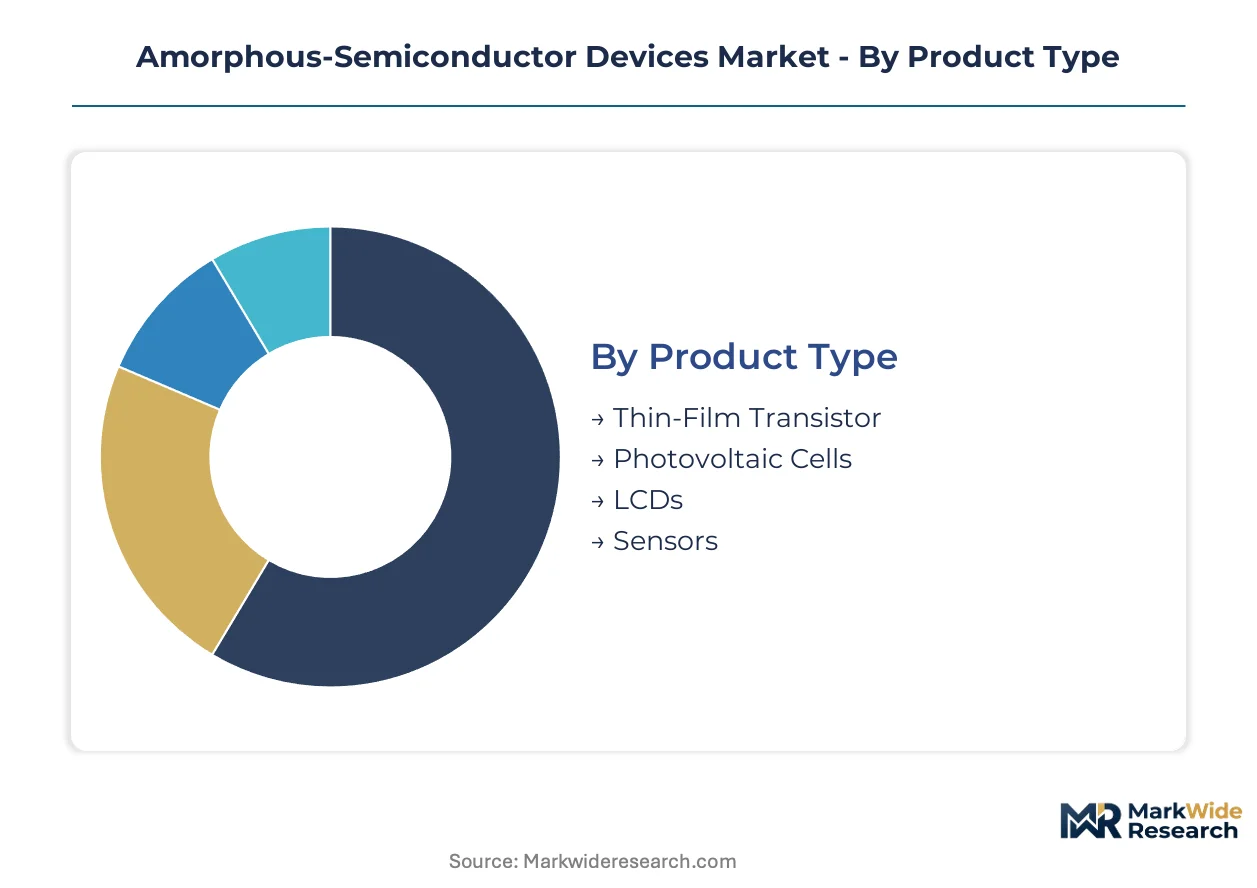
Segmentation in amorphous-semiconductor devices reveals distinct procurement patterns across deposition technologies and end-use verticals. Product type and application dimensions expose where hydrogen-passivation economics dominate versus where oxide-semiconductor alternatives are compressing addressable volume.
Product Type:
Domestic production clusters in South Korea and Japan anchor thin-film transistor supply for display backplanes, while photovoltaic cell manufacturing spreads across export-led installations in European building-integrated architectures.
- Thin-Film Transistor:Hydrogenated amorphous silicon active layers deposited below crystallization thresholds enable field-effect mobility exceeding 1 cm²/Vs. Seoul-Incheon foundry corridors concentrate procurement for OLED active-matrix addressing as automotive OEMs electrify cabin electronics. Thin-film transistors command the established base. The steepest expansion runs through photovoltaic cells.
- Photovoltaic Cells:Meter-scale flexible substrates achieve 8-15 atomic percent hydrogen content for dangling-bond passivation. Building-integrated commercial glazing in Germany and France multiplies addressable surface area where crystalline silicon wafer economics fail. Thin-film transistors command the established base. The steepest expansion runs through photovoltaic cells.
- LCDs:Legacy Gen 8.5 crystalline silicon lines face retooling complexity for hydrogen-passivation chamber conversion.
- Sensors:Amorphous selenium flat-panel detectors target digital radiography tenders under South Korea's MFDS and India's CDSCO device classifications.
Thin-film transistors absorb the dominant revenue position. Photovoltaic cells capture the steepest volume trajectory as dual carbon policies accelerate building-integrated deployment.
Technology:
Cost tier stratification separates high-throughput vacuum deposition from emerging roll-to-roll printing, with plasma-enhanced chemical vapor deposition commanding premium positioning for display-grade material purity.
- Chemical Vapor Deposition:Plasma-enhanced processes deposit hydrogenated amorphous silicon at temperatures below crystallization thresholds. Silane gas feedstock volatility destabilizes cost structures for dangling-bond termination. Chemical vapor deposition anchors the mature installed base. Laser processing shows the most rapid qualification activity.
- Physical Vapor Deposition:Sputtering targets from Japanese precision materials suppliers dominate high-purity chalcogenide deposition for infrared sensor fabricators. Three suppliers control critical supply creating single-source vulnerability. Physical vapor deposition anchors the mature installed base. Laser processing shows the most rapid qualification activity.
- Printing Technology:Inkjet-patterned interconnects enable sub-50-micron bend-radius integration with roll-to-roll deposition for wearable health monitors.
- Laser Processing:Remote plasma source retrofits accommodate fluorine-free radical generation under Europe's F-Gas Regulation phasedown. Chemical vapor deposition anchors the mature installed base. Laser processing shows the most rapid qualification activity.
Chemical vapor deposition retains the largest installed equipment base. Laser processing gains share fastest as etching chemistry regulations tighten across European infrared sensor foundries.
End User:
Customer type concentration shifts procurement leverage toward automotive OEMs consolidating single-source panel contracts, while renewable energy developers fragment across distributed generation project finance structures.
- Consumer Electronics:Smartphone OLED backplane displacement by indium-gallium-zinc oxide semiconductors compresses hydrogenated amorphous silicon deposition equipment demand. Samsung Display and LG Display have completed IGZO qualification for variable refresh-rate drivers. Consumer electronics maintains the largest addressable volume. Healthcare delivers the fastest margin expansion.
- Automotive:BMW, Mercedes-Benz, and Hyundai centralize amorphous-alloy magnetic core sourcing for integrated cockpit display-electronics packages. Tier-1 suppliers lose direct sputtering target negotiation leverage under captive semiconductor-grade specifications. Consumer electronics maintains the largest addressable volume. Healthcare delivers the fastest margin expansion.
- Renewable Energy:Utility-scale ground-mounted installations face crystalline silicon substitution from perovskite tandem architectures.
- Healthcare:Amorphous selenium avalanche-gain applications justify premium positioning against crystalline alternatives in digital radiography procurement. Consumer electronics maintains the largest addressable volume. Healthcare delivers the fastest margin expansion.
Consumer electronics retains the broadest addressable volume despite oxide-semiconductor displacement at the premium tier. Healthcare concentrates margin pools where imaging device certifications create specialist vendor lock-in.
Application:
Application maturity diverges sharply between display panels with decades of active-matrix addressing deployment and smart labels where printed electronics convergence remains pre-commercial.
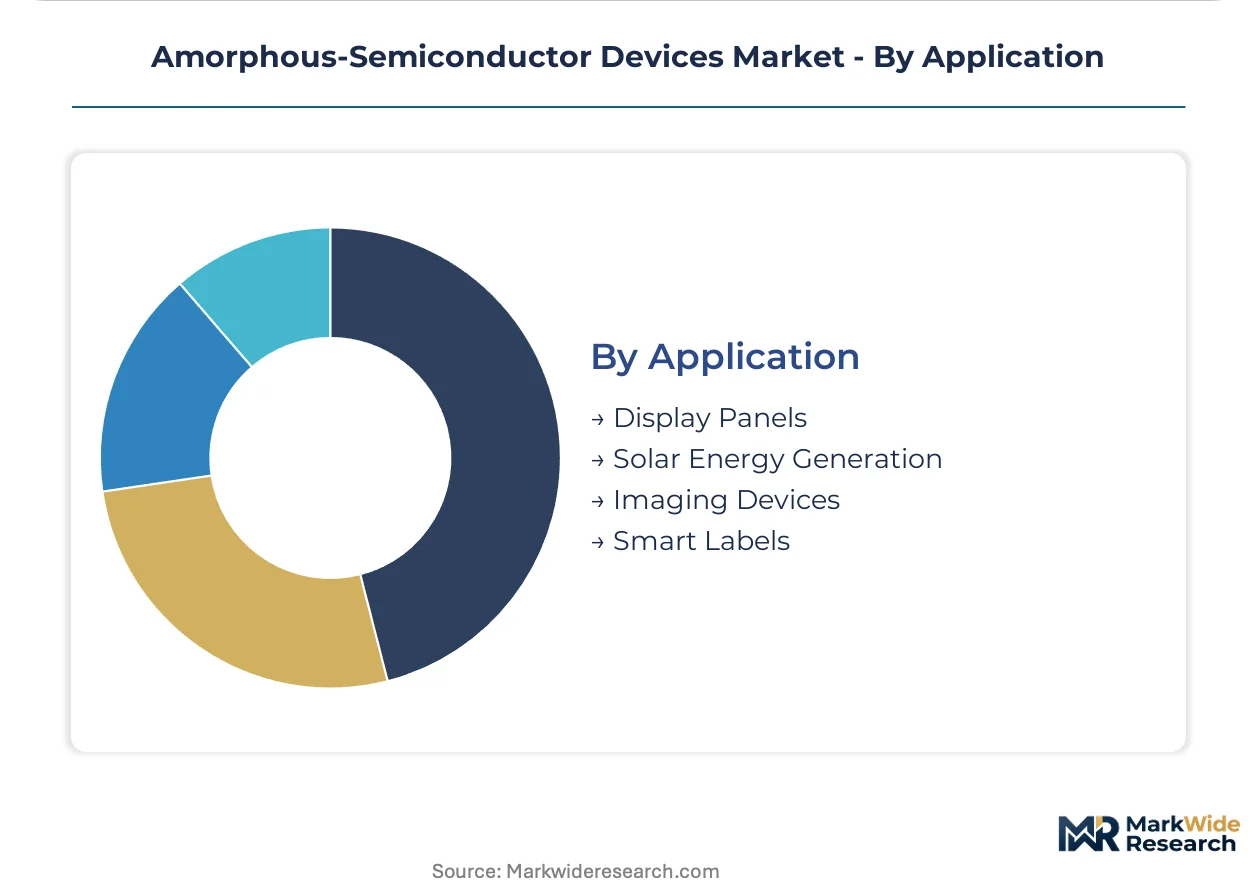
- Display Panels:Active-matrix addressing for OLED and LCD production concentrates in South Korea's display foundry corridor. Low-temperature deposition compatibility reframes equipment vendor selection criteria across panel supply chains. Display panels dominate current revenue contribution. Smart labels present the longest development runway.
- Solar Energy Generation:Flexible substrate architectures enable meter-scale uniform properties where crystalline silicon wafer economics fail. China's MIIT semiconductor material certification channels domestic melt-spinning capacity toward photovoltaic annealing lines. Display panels dominate current revenue contribution. Smart labels present the longest development runway.
- Imaging Devices:Flat-panel detector deployment targets India's CDSCO-classified medical imaging tender pipeline.
- Smart Labels:Roll-to-roll deposition integration with printed electronics remains pre-commercial for sub-50-micron bend-radius wearable applications. Display panels dominate current revenue contribution. Smart labels present the longest development runway.
Display panels absorb the dominant revenue position. Smart labels require the longest development runway as printed electronics convergence matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea's display foundry corridor while Germany's precision materials sector commands magnetics premiums, creating a transcontinental asymmetry that shapes procurement leverage across the value chain.
South Korea
Seoul-Incheon manufacturing clusters anchor OLED active-matrix addressing volume as Hyundai electrifies cabin electronics. MFDS coordinates with KATS on medical device approvals for amorphous selenium flat-panel detectors. Samsung Display and LG Display dominate backplane procurement, compressing qualification timelines for hydrogen-passivation process validation.
Japan
Precision materials suppliers control high-purity sputtering target supply for infrared sensor fabricators. METI enforces JIS standards for amorphous alloy magnetic cores in power distribution. Toshiba's materials division and Shin-Etsu Chemical concentrate deposition source production in the Chubu/Nagoya industrial zone.
Germany
VACUUMSCHMELZE leverages European magnetics heritage for amorphous alloy power electronics supply. ECHA's REACH restrictions on cadmium and heavy-metal dopants pull compliant sputtering target demand from display manufacturers. Infrared sensor foundries face F-Gas Regulation compliance cost escalation due to legacy sulfur-hexafluoride process dependencies.
China
MIIT mandates GB certification for semiconductor materials used in state-backed display fab projects. China Amorphous Technology operates integrated melt-spinning and annealing lines serving domestic photovoltaic manufacturers. Dual carbon policy alignment channels domestic capacity toward building-integrated solar architectures.
India
CDSCO-classified medical imaging tenders open flat-panel detector deployment for digital radiography. Domestic procurement under government health schemes multiplies addressable surface area for amorphous selenium avalanche-gain applications. Maharashtra and Karnataka host emerging diagnostic equipment assembly clusters.
Amorphous-Semiconductor Devices Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision materials specialists commanding premium positioning while integrated melt-spinning operators compete on scale. The vendor base stratifies across three tiers: European magnetics heritage houses, Japanese deposition source specialists, and Chinese volume manufacturers. Consolidation pressure concentrates in sputtering target supply where three Japanese suppliers create single-source vulnerability. Competitive moves center on captive semiconductor-grade specifications and backward integration into hydrogen feedstock security.
Among Japanese precision materials specialists, Toshiba Materials and Shin-Etsu Chemical exemplify the deposition source archetype that dominates high-purity chalcogenide supply chains. VACUUMSCHMELZE represents the European magnetics heritage position anchoring amorphous alloy supply for power electronics. China Amorphous Technology occupies the scale-driven tier, operating integrated production lines that serve domestic photovoltaic demand under state-backed certification requirements.
| Leading Market Players |
|---|
| Hitachi Metals |
| VACUUMSCHMELZE |
| Toshiba Materials |
| Advanced Technology & Materials |
| China Amorphous Technology |
| BOMATECH |
| AMES SA |
| MK Magnetics |
| Shin-Etsu Chemical |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for silane gas feedstock lock in hydrogen-passivation cost visibility for Seoul-Incheon display foundries while insulating procurement teams from spot-market volatility. These contracts tether pricing power to feedstock security, compressing margin exposure for thin-film transistor manufacturers against regional supply interruptions.
Pricing Analysis
Price spreads between South Korean display-grade sputtering targets and Chinese photovoltaic annealing lines exceed three-to-one, reflecting certification-grade differentiation. Pricing stratifies across semiconductor-grade, industrial-grade, and commodity-grade tiers, with JIS-METI magnetic core specifications commanding substantial premiums. Cost compression in standard-grade hydrogenated amorphous silicon intensifies as China Amorphous Technology scales melt-spinning capacity. Automotive OEMs exhibit the lowest price sensitivity due to captive semiconductor-grade specifications, while distributed solar developers face acute margin pressure from crystalline silicon substitution.
Supply Chain Analysis
Japanese precision materials suppliers in the Chubu/Nagoya industrial zone constitute a critical chokepoint for high-purity chalcogenide deposition sources. Manufacturing draws from South Korea's display foundry corridor, Japan's sputtering target specialists, and China's integrated melt-spinning operators. Raw material dependencies center on silane gas, amorphous alloy feedstock, and selenium ingots. Single-source vulnerability pervades infrared sensor fabrication due to three-supplier concentration. Distribution runs through direct OEM contracts for automotive display panels and project-finance structures for building-integrated photovoltaics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in amorphous-semiconductor devices pivot on deposition equipment interoperability, as oxide-semiconductor backplanes force hydrogen-passivation process vendors toward multi-technology chamber compatibility.
For Market Incumbents: Secure hydrogen feedstock offtake agreements before silane gas volatility escalates, and accelerate JIS-IEC certification synchronization to fragment approval pathways less. IGZO displacement in smartphone OLED backplanes threatens volume concentration; vertical integration into laser processing equipment preserves service revenue as deposition technology shifts. For New Entrants and Emerging Players: Post-warranty technical service for legacy LCD hydrogen-passivation chambers represents an underserved layer where incumbents retreat from maintenance commitments. India's CDSCO-classified medical imaging tenders offer the most penetrable geography for amorphous selenium flat-panel detectors. A go-to-market partnership with Maharashtra diagnostic equipment assemblers bypasses established channel control. For Investors and Strategic Acquirers: Capital is best deployed toward precision materials specialists with captive semiconductor-grade certification and backward integration into sputtering target recycling. Long-term viability hinges on regulatory bloc leadership in photovoltaic module recyclability mandates. Watch for MIIT announcements on GB standard updates for state-backed display fabs as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Feedstock | VACUUMSCHMELZE and China Amorphous Technology anchor supply security against regional gas interruptions. |
| JIS-IEC Certification Harmonization | Toshiba Materials reduces fragmentation costs for amorphous alloy magnetic core power electronics approvals. |
| Multi-Technology Deposition Chamber Development | Equipment vendors reframe selection criteria as IGZO displaces hydrogenated amorphous silicon in premium mobile panels. |
| Medical Imaging Tender Partnership | Amorphous selenium flat-panel detector suppliers target India's CDSCO procurement pipeline under government health schemes. |
| Photovoltaic Module Recycling Infrastructure | Stakeholders anticipate which regulatory bloc first mandates recyclability standards for end-of-life material recovery economics. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with thin-film deposition engineers, display panel procurement managers, sputtering target technical directors, and photovoltaic project finance leads; and secondary validation through MIIT GB certification databases, ECHA REACH restriction filings, customs trade data for amorphous alloy imports, and SEC filings from precision materials suppliers. Bottom-up equipment installation counts and top-down display panel production forecasts were triangulated against hydrogen-passivation process validation timelines.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deposition technology, end-use vertical, application maturity, and regional regulatory cluster. CAGRs were derived from equipment vendor order backlogs and foundry capacity expansion announcements. Forecast inputs incorporated silane gas pricing volatility indices and automotive OEM single-source contract consolidation patterns.
Forecasts assume regulatory continuity in ECHA REACH, MIIT GB standards, and METI JIS enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as F-Gas Regulation phasedown timelines and perovskite tandem solar efficiency thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Gallium Oxide Transistor Market