
 Global Automotive Mosfets Market | 2026-2036
Global Automotive Mosfets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Mosfets Market Analysis
The direct-to-Tier-1 supplier channel is rewriting procurement patterns for power semiconductors. Infineon Technologies leverages its captive fab capacity in Austria and Malaysia to sustain supply commitments to German OEMs. Nexperia anchors its automotive MOSFET portfolio through discrete packaging specialization, while STMicroelectronics competes via vertically integrated silicon carbide substrate production.
Automotive MOSFETs are metal-oxide-semiconductor field-effect transistors engineered for switching and amplification in vehicle electrical systems, typically rated from 40V to over 1,000V with on-resistance specifications below 1 milliohm for traction applications. N-Channel devices dominate high-current power management segments due to superior electron mobility, while silicon carbide technology commands the fastest expansion trajectory as OEMs push inverter efficiencies above 97 percent. Gallium nitride variants remain niche but occupy emerging 48V mild-hybrid architectures where switching frequency requirements exceed silicon limits.
The EPA tailpipe emissions framework and the EU Green Deal vehicle CO2 mandates are forcing powertrain electrification timelines that directly inflate MOSFET content per vehicle. China's MIIT new energy vehicle credit system and GB/T charging standards shape domestic procurement specifications that foreign suppliers must navigate for market access. Stakeholders must monitor substrate supply bottlenecks and qualification timelines for wide-bandgap technologies as OEMs consolidate inverter platform designs.
Market Dynamics
The transition from silicon to wide-bandgap semiconductors is compressing inverter design cycles and forcing Tier-1 suppliers to requalify entire component portfolios. Silicon carbide substrate availability and gallium nitride epitaxy capacity now constrain how quickly OEMs can scale 800V architectures.
Growth Catalysts
- EPA tailpipe emissions framework:The US regulatory pressure is forcing passenger vehicle OEMs to accelerate battery-electric powertrain deployment, directly inflating MOSFET content per vehicle across traction inverters and DC-DC converters.
- Silicon carbide trench MOSFET designs:These architectures are achieving on-resistance below 1 milliohm, enabling inverter efficiencies above 97 percent and reducing thermal management system mass.
- China's MIIT new energy vehicle credit system:Domestic production quotas are concentrating demand for automotive-grade power semiconductors within Chinese battery-electric vehicle manufacturing clusters.
Market Restraints
- Silicon carbide substrate cost structure:150mm wafer pricing remains elevated due to limited crystal growth furnace capacity, compressing gross margins for discrete device manufacturers.
- Substrate supply concentration:Wolfspeed, Coherent, and SiCrystal control the majority of merchant SiC substrate supply, creating single-source vulnerability for qualified automotive programs.
- Copper clip packaging technical limitation:High-current interconnect reliability under thermal cycling stress restricts current density scaling in discrete packages above 300A continuous operation.
Strategic Opportunities
- 48V mild-hybrid architectures:Gallium nitride HEMT devices are penetrating belt-driven starter-generator and electric turbocharger applications where switching frequencies exceed silicon MOSFET limits.
- EU Green Deal vehicle CO2 mandates:The 2035 internal combustion engine phase-out timeline is creating guaranteed demand pull for power semiconductor content across European OEM electrification roadmaps.
- Direct-to-fab procurement channels:OEMs are bypassing traditional distribution to secure captive wafer capacity, reshaping how automotive MOSFET supply agreements are structured.
Industry Challenges
- Wide-bandgap device qualification timelines:AEC-Q101 Rev-F testing for silicon carbide MOSFETs requires extended high-temperature gate bias validation, stretching new product introduction cycles to 24-36 months.
- Power module integration complexity:Combining SiC MOSFETs with silicon IGBT antiparallel diodes in hybrid inverter designs creates gate drive synchronization challenges that delay platform consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Mosfets Market |
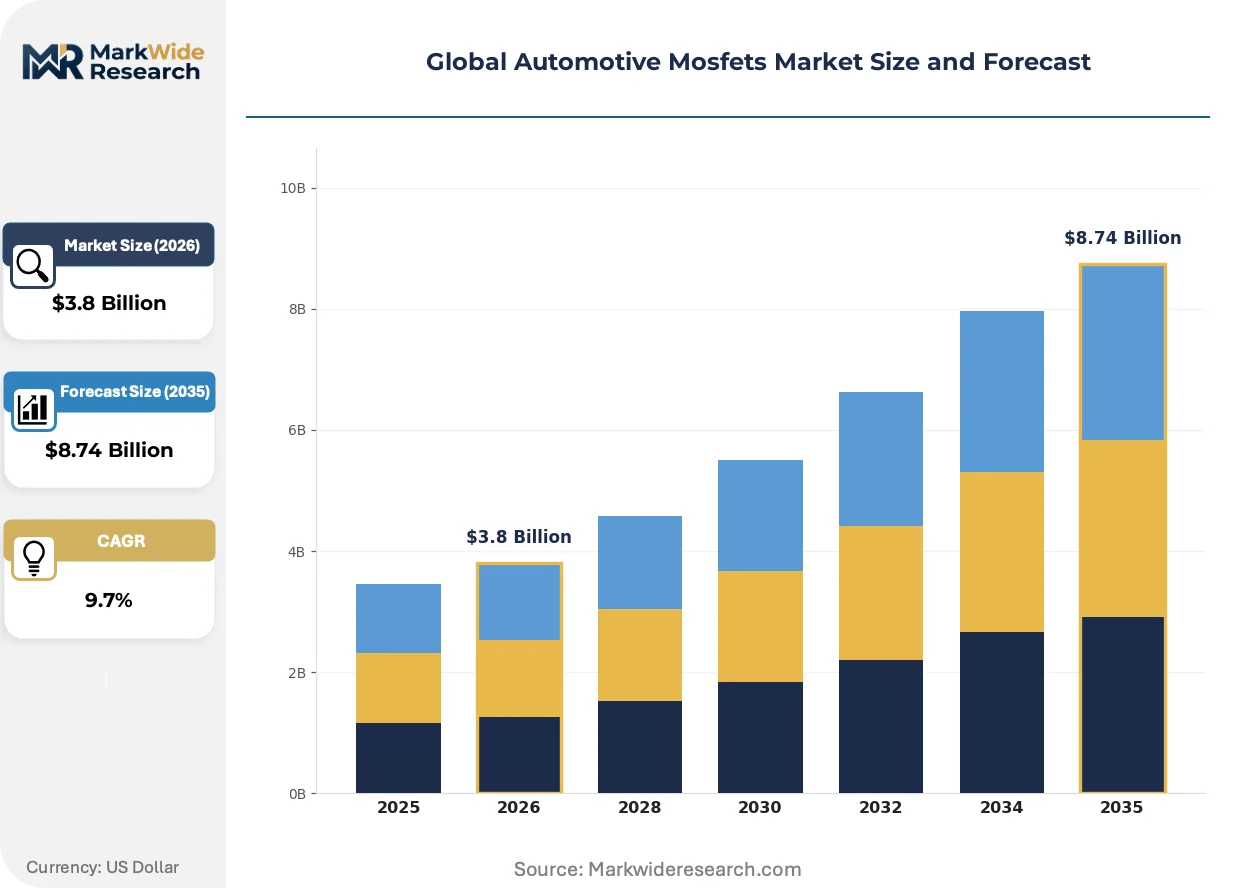
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
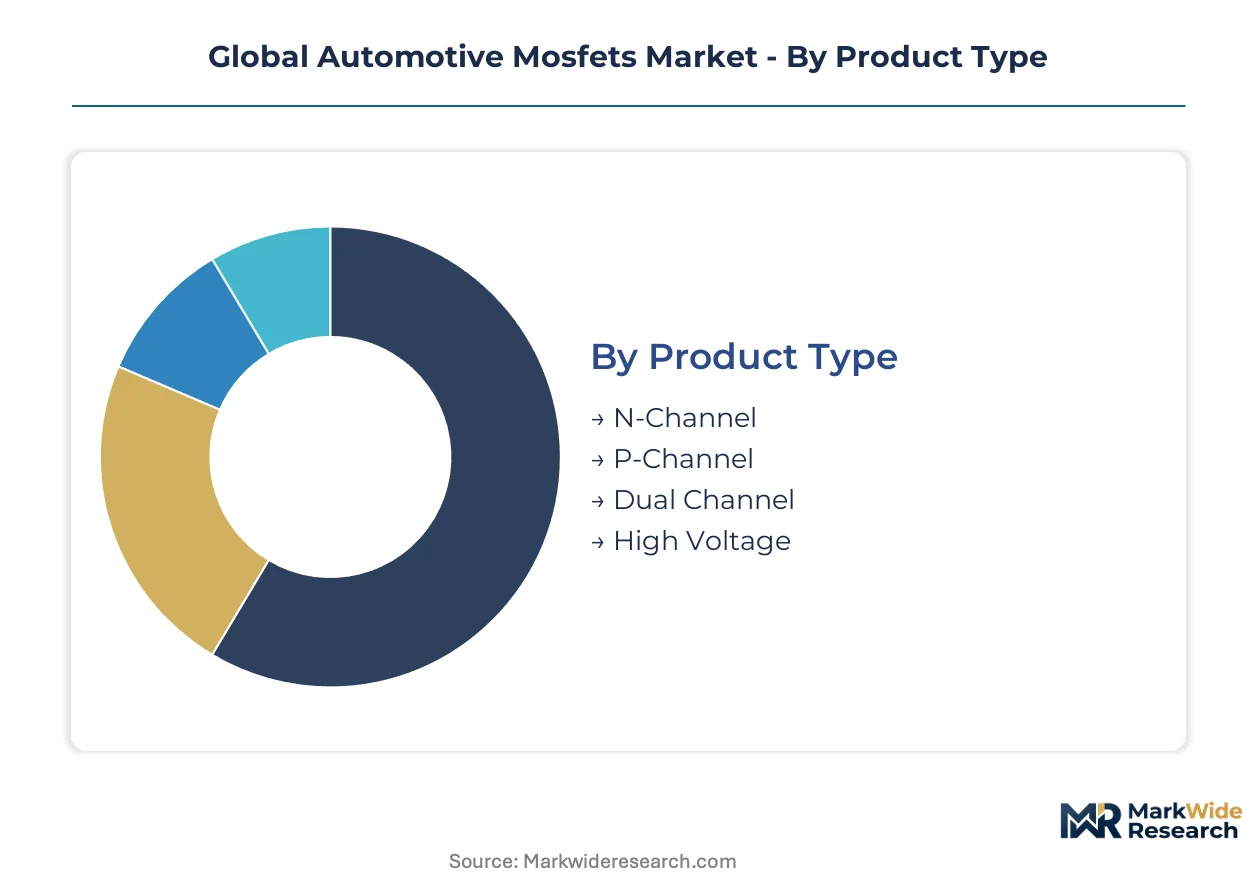
| Segmentation | Product Type: N-Channel, P-Channel, Dual Channel, High Voltage Application: Power Management, Motor Control, Voltage Regulation, Signal Amplification End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Technology: Silicon, Silicon Carbide, Gallium Nitride, Others |
| Companies Covered | Infineon Technologies, Nexperia, Texas Instruments, STMicroelectronics, ON Semiconductor, Toshiba, Renesas Electronics, Vishay Intertechnology, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Mosfets Market Emerging Trajectories
Process node migration and packaging innovation are converging to redefine automotive power semiconductor performance benchmarks. Wide-bandgap materials are enabling topological advances that silicon devices cannot support.
Silicon carbide MOSFETs with planar gate structures are replacing silicon superjunction devices in 400V and 800V traction inverters. European and Chinese OEMs are adopting these devices at scale for 2025-2027 vehicle platforms. This transition is rendering obsolete the discrete silicon IGBT modules that dominated prior-generation electric powertrains.
The EU Green Deal vehicle CO2 mandates are accelerating powertrain electrification timelines across German, French, and Italian OEM portfolios. These regulations compress supplier qualification windows and force concurrent engineering of inverter platforms. High-voltage traction applications are absorbing the majority of engineering resources as OEMs consolidate on 800V architectures.
Automotive procurement teams are consolidating supplier panels to secure dedicated fab capacity. Tier-1 power module manufacturers are signing multi-year wafer supply agreements directly with substrate and epitaxy providers. This pattern is most pronounced in China and Germany, where battery-electric vehicle production scaling has created acute competition for qualified semiconductor supply.
Global Automotive Mosfets Market Segmentation
Automotive MOSFET procurement patterns diverge sharply across application voltage tiers and end-user channels. Power semiconductor suppliers must align wafer capacity and packaging roadmaps with distinct technical specifications and qualification timelines that each segment imposes.
Product Type:
After-sales service intensity varies dramatically across channel architectures, with discrete device replacement cycles driving inventory positioning strategies at distributors.
- N-Channel:These devices leverage superior electron mobility to handle high-current switching in traction inverters and DC-DC converters. Demand concentrates in 800V battery-electric vehicle platforms from German and Chinese OEMs where on-resistance specifications below 1 milliohm are mandatory.
- P-Channel:Complementary switching configurations in H-bridge motor drives utilize these devices for high-side load control. Procurement from Tier-1 suppliers accelerates for 48V mild-hybrid starter-generator systems where bidirectional current flow is required.
- Dual Channel:Integrated half-bridge packages reduce PCB footprint in space-constrained auxiliary power modules.
- High Voltage:Ratings exceeding 650V serve traction inverter bus architectures and onboard charger front-ends.
By volume, N-Channel leads. By growth pace, High Voltage is ahead.
Application:
Cost tier differentiation separates commodity voltage regulation from premium traction inverter content where silicon carbide commands price multiples.
- Power Management:Battery management system balancing circuits and thermal runaway protection rely on low-RDS(on) switching for energy efficiency. Chinese battery-electric vehicle manufacturing clusters absorb the majority of procurement volume as domestic OEMs scale cell-to-pack architectures.
- Motor Control:Traction inverter gate drives and electric power steering modules demand switching frequencies above 20kHz. European OEM electrification roadmaps under EU Green Deal mandates are concentrating engineering resources here.
- Voltage Regulation:DC-DC converter stages for 12V accessory rails utilize standard silicon superjunction devices.
- Signal Amplification:Sensor interface circuits in advanced driver-assistance systems require low-noise switching characteristics.
Motor Control captures the highest absolute content per vehicle. Power Management is expanding most quickly.
End User:
Customer type determines contract structure, with direct OEM agreements locking capacity years ahead of spot aftermarket procurement.
- OEMs:Volkswagen, BYD, and Tesla negotiate multi-year wafer supply agreements directly with substrate manufacturers to secure silicon carbide allocation. These arrangements bypass traditional distribution and force component suppliers to qualify at platform design inception.
- Tier-1 Suppliers:Bosch, Continental, and Denso consolidate inverter platform designs and drive qualification timelines for discrete device portfolios. Their procurement specifications determine which process technologies achieve automotive AEC-Q101 certification.
- Aftermarket:Replacement demand for legacy internal combustion engine powertrain modules persists in service networks.
- Vehicle Assemblers:Contract manufacturers in emerging production regions source through authorized distribution channels.
OEMs dominate absolute procurement value. Tier-1 Suppliers are gaining share fastest as platform consolidation accelerates.
Technology:
Supply concentration in substrate manufacturing constrains how quickly emerging wide-bandgap materials can displace incumbent silicon architectures.
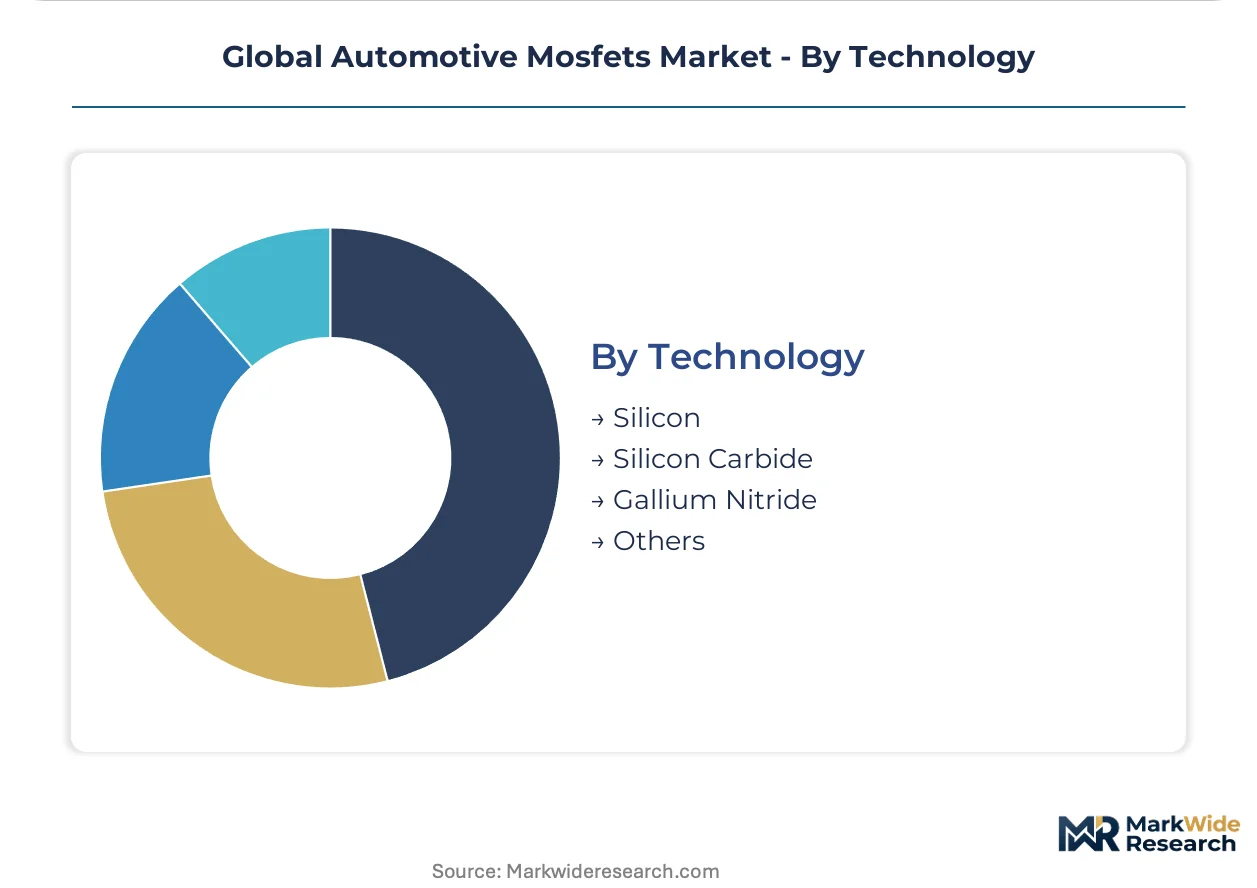
- Silicon Carbide:Trench MOSFET designs on 150mm substrates achieve inverter efficiencies above 97 percent. Wolfspeed, Coherent, and SiCrystal control merchant substrate supply, creating qualification bottlenecks for automotive programs targeting 800V architectures.
- Gallium Nitride:HEMT devices penetrate 48V mild-hybrid applications where switching frequencies exceed silicon limits. Belt-driven starter-generator and electric turbocharger designs from European OEMs are driving initial adoption curves.
- Silicon:Superjunction MOSFETs retain cost advantage in 400V architectures and auxiliary power modules.
- Others:Experimental gallium oxide and diamond substrates remain pre-qualification for automotive voltage ratings.
Silicon leads by installed base. Silicon Carbide shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port and Ningbo-Zhoushan container complex underwrite China's semiconductor import throughput. German automotive MOSFET demand flows through Hamburg's port infrastructure and the Rhine-Main-Danube inland waterway network.
China
BYD and CATL battery manufacturing clusters in Shenzhen and Ningbo drive silicon carbide procurement volumes. MIIT new energy vehicle credit quotas mandate minimum domestic production thresholds for foreign suppliers. Shanghai's Lingang New Area hosts concentrated wafer fab capacity expansion for 800V traction inverter programs.
Germany
Volkswagen Group and BMW electrification roadmaps concentrate engineering resources in Munich and Stuttgart engineering centers. EU Green Deal vehicle CO2 mandates enforce 2035 internal combustion engine phase-out timelines. Dresden's semiconductor manufacturing corridor anchors Infineon Technologies' captive fab supply commitments to domestic OEMs.
United States
Tesla's Gigafactory network in Nevada and Texas scales 4680 cell production requiring matched power semiconductor content. EPA tailpipe emissions framework accelerates battery-electric powertrain deployment timelines for Detroit Three OEMs. Arizona's Phoenix semiconductor corridor attracts substrate and epitaxy capacity investments for wide-bandgap device manufacturing.
Japan
Toyota and Honda hybrid platform consolidation sustains demand for 48V mild-hybrid MOSFET specifications. METI carbon neutrality roadmaps shape domestic supplier qualification requirements for silicon carbide traction inverters. Kyushu's Kumamoto region hosts concentrated power semiconductor packaging capacity for automotive Tier-1 supply.
South Korea
Hyundai Motor Group and LG Energy Solution joint ventures in Seoul and Incheon drive high-voltage inverter platform development. K-RE100 renewable energy mandates indirectly pressure automotive supply chain decarbonization timelines. Gyeonggi Province's Pangyo Techno Valley clusters fabless power semiconductor design houses serving domestic battery-electric vehicle programs.
Global Automotive Mosfets Market Vendor Landscape
On the supply side, the industry is consolidating around captive substrate capacity and direct OEM procurement channels. Merchant substrate availability constraints favor players with backward integration into silicon carbide crystal growth or gallium nitride epitaxy. Three strategic archetypes dominate: integrated device manufacturers with captive fabs, fabless specialists with packaging differentiation, and substrate-integrated power semiconductor divisions. Competitive moves center on multi-year wafer supply agreements and AEC-Q101 qualification acceleration.
Among European integrated device manufacturers, Infineon Technologies and STMicroelectronics occupy positions defined by substrate access and vertical manufacturing depth. Nexperia anchors the discrete packaging specialist archetype through automotive-qualified portfolio breadth. These three entities exemplify how supply security and qualification speed now determine competitive positioning more than unit cost optimization.
| Leading Market Players |
|---|
| Infineon Technologies |
| Nexperia |
| Texas Instruments |
| STMicroelectronics |
| ON Semiconductor |
| Toshiba |
| Renesas Electronics |
| Vishay Intertechnology |
| Microchip Technology |
| Others |
Supply Flow & Price Mechanics
The Shanghai Yangshan deep-water port and Ningbo-Zhoushan container complex handle silicon carbide substrate and epitaxy equipment imports that feed China's 800V traction inverter manufacturing clusters. Freight cost volatility from these corridors directly compresses gross margins for discrete device manufacturers while amplifying price differentiation between captive-fab suppliers and merchant substrate buyers.
Pricing Analysis
Volume-discount tiering structures separate multi-year wafer supply agreements negotiated by Volkswagen and BYD from spot procurement through authorized distribution. Price differentiation rests on AEC-Q101 certification grade and captive substrate access, with silicon carbide trench MOSFETs commanding multiples over silicon superjunction equivalents. Cost compression in standard silicon devices is intensifying because Chinese battery-electric vehicle OEMs consolidate supplier panels. Aftermarket distributors exhibit highest price sensitivity, while German OEMs prioritize supply security over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Wolfspeed, Coherent, and SiCrystal anchor merchant silicon carbide substrate availability for automotive qualification programs. Raw material dependencies draw from high-purity silicon metal, copper interconnects, and ceramic substrate carriers. Single-source vulnerability concentrates around 150mm SiC wafer supply from the three dominant substrate manufacturers. Distribution runs through direct-to-fab procurement channels that bypass traditional Tier-1 supplier intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM procurement consolidation around 800V platform standardization has shifted bargaining power toward vehicle manufacturers and away from component suppliers. This concentration forces suppliers to lock capacity years ahead of production ramp.
For Market Incumbents: Entrench silicon carbide substrate access through multi-year crystal growth furnace offtake agreements or backward integration into epitaxy capacity. Infineon Technologies and STMicroelectronics demonstrate how captive fab supply commitments to German OEMs defend against pricing pressure from Chinese competitors. Accelerate AEC-Q101 Rev-F qualification timelines to match compressed inverter design cycles from Tier-1 suppliers. For New Entrants and Emerging Players: Establish a beachhead in 48V mild-hybrid gallium nitride HEMT applications where switching frequency requirements exceed silicon MOSFET limits. European belt-driven starter-generator and electric turbocharger designs offer lower qualification barriers than 800V traction inverters. Partner with fabless power semiconductor design houses in South Korea's Pangyo Techno Valley to access packaging specialization without substrate manufacturing investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized automotive power semiconductor divisions. Long-term viability hinges on substrate supply security rather than discrete device design differentiation. Monitor silicon carbide substrate spot pricing and qualification backlog durations as inflection indicators for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Supply Agreement | Direct wafer offtake from Wolfspeed or Coherent secures allocation for 800V inverter programs. |
| AEC-Q101 Qualification Acceleration | Compressed validation cycles match EU Green Deal timeline pressures from German OEMs. |
| Gallium Nitride Packaging Specialization | Higher switching frequency support captures 48V mild-hybrid content from European suppliers. |
| Direct-to-OEM Channel Development | Bypassing Tier-1 intermediaries reshapes contract structures for high-voltage traction applications. |
| Copper Clip Interconnect R&D Investment | Thermal cycling reliability improvements enable current density scaling above 300A continuous operation. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, semiconductor fab operations managers, and aftermarket distributors converged on the working assumptions. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC semiconductor manufacturer filings, and MIIT new energy vehicle credit disclosures. Bottom-up content-per-vehicle estimates triangulated against top-down wafer supply allocation data across the analysis window.
Demand-supply-balance framing anchored the analytical framework across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from production volume trajectories and technology penetration curves without year-specific anchoring. Silicon carbide substrate availability constraints and AEC-Q101 qualification timelines served as critical forecast inputs throughout the modeling period.
Sensitivities concentrate around silicon carbide crystal growth furnace capacity expansion, gallium nitride epitaxy yield improvements, and EPA or EU Green Deal regulatory timeline adjustments. Forecasts reflect documented assumptions about OEM electrification roadmaps and Tier-1 supplier consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
SLD Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Global Semiconductor Device Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Silicon Epitaxial Wafer Market