
 5G Base Station BAW Filters Market | 2026-2036
5G Base Station BAW Filters Market Size, Share, and Industry Trends Forecast 2026-2036
5G Base Station BAW Filters Market Insights
Telecom infrastructure deployment is expanding across urban corridors and industrial zones worldwide. Broadcom Inc. leverages its semiconductor fabrication scale to anchor high-volume BAW filter supply chains for macro base stations. Qorvo, Inc. competes through specialized RF front-end integration that sustains design wins with leading telecom equipment manufacturers.
5G base station BAW (Bulk Acoustic Wave) filters are piezoelectric resonator devices typically constructed from aluminum nitride or scandium-doped aluminum nitride thin films deposited on silicon substrates, engineered to isolate specific frequency bands with insertion loss below 2 dB in sub-6 GHz applications. Their primary commercial purpose is to prevent signal interference between adjacent channels in massive MIMO arrays and small cell architectures. Bandpass configurations dominate current procurement volumes as carriers prioritize mid-band 5G rollouts, while module form factors capture expanding margin pools through integrated filter-amplifier-antenna combinations that reduce board space. Sub-6 GHz frequency ranges anchor near-term shipments, though 24-39 GHz modules represent the fastest-growing segment as millimeter-wave networks densify in urban cores.
The FCC governs spectrum allocation and device certification requirements in the United States, while China's MIIT enforces GB standards and dual carbon goals that shape base station energy efficiency mandates. ETSI and 3GPP frameworks in Europe establish interoperability benchmarks that filter manufacturers must satisfy for CE-marked equipment access. Stakeholders must monitor evolving spectrum reallocation decisions and efficiency standards across these jurisdictions to anticipate procurement specification shifts.
Market Dynamics
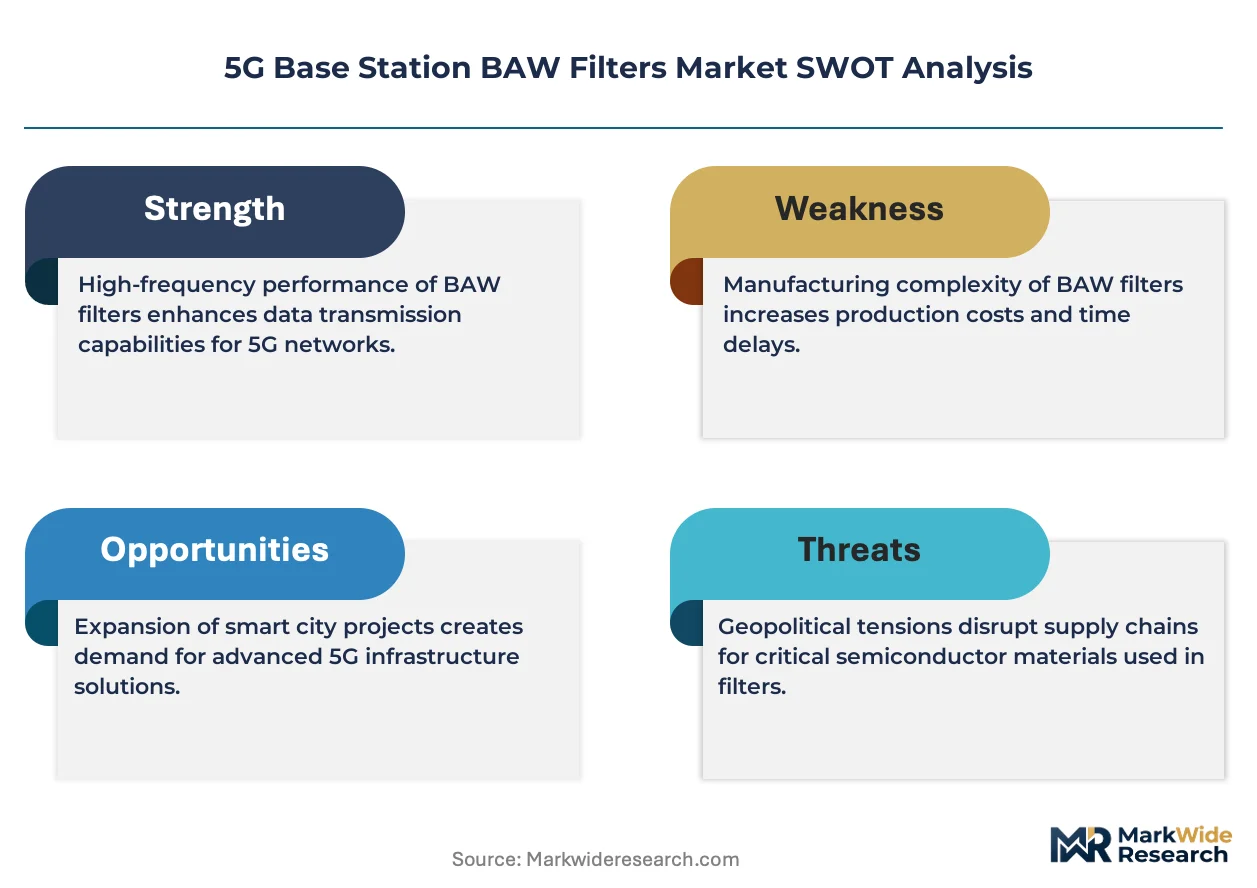
Mid-band spectrum auctions by the FCC and MIIT are compressing deployment timelines, forcing filter manufacturers to scale aluminum nitride deposition capacity ahead of verified equipment orders. This demand-surge pattern is creating mismatches between wafer-start capacity and certified module availability.
Growth Catalysts
- MIIT spectrum allocations:China's accelerated 5G base station rollout in eastern coastal provinces is pulling wafer-level BAW filter volumes through Shenzhen and Suzhou manufacturing clusters.
- Scandium-doped aluminum nitride:This piezoelectric thin-film material is extending filter bandwidth while maintaining insertion loss below 2 dB, enabling single-filter coverage of wider 5G channels.
- Massive MIMO architectures:Telecom equipment manufacturers are specifying integrated filter-amplifier-antenna modules that reduce board space by consolidating discrete components.
Market Restraints
- Aluminum nitride wafer supply:Deposition-grade AlN substrates concentrate among Japanese and Korean specialty ceramic suppliers, exposing filter fabricators to input bottlenecks.
- Millimeter-wave technical limitation:BAW resonator Q-factor degradation above 28 GHz forces hybrid filter architectures that increase module complexity and calibration overhead.
- FCC certification friction:Sub-6 GHz device authorization timelines extend 14-22 weeks, delaying revenue recognition for new filter SKUs targeted at US carrier procurement windows.
Strategic Opportunities
- India's telecom infrastructure:TRAI's 5G spectrum assignment to Bharti Airtel and Reliance Jio is opening filter procurement channels previously dominated by Chinese base station OEMs.
- Open RAN disaggregation:The O-RAN Alliance specification is decoupling RF front-ends from proprietary baseband units, creating entry points for specialized BAW filter suppliers outside incumbent supply chains.
- EU Green Deal efficiency mandates:ETSI base station energy standards are favoring low-insertion-loss BAW configurations over competing SAW technologies in CE-marked equipment.
Industry Challenges
- Piezoelectric thin-film process engineering:Scandium doping uniformity across 200mm silicon wafers requires atomic-layer deposition expertise concentrated among semiconductor veterans.
- 3GPP Release 17 certification:Extended frequency range n104 compliance testing adds 8-12 weeks to module qualification cycles.
- Legacy 4G filter integration:Multi-band base stations require BAW-SAW hybrid designs that complicate thermal management and spurious response suppression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Base Station BAW Filters Market |
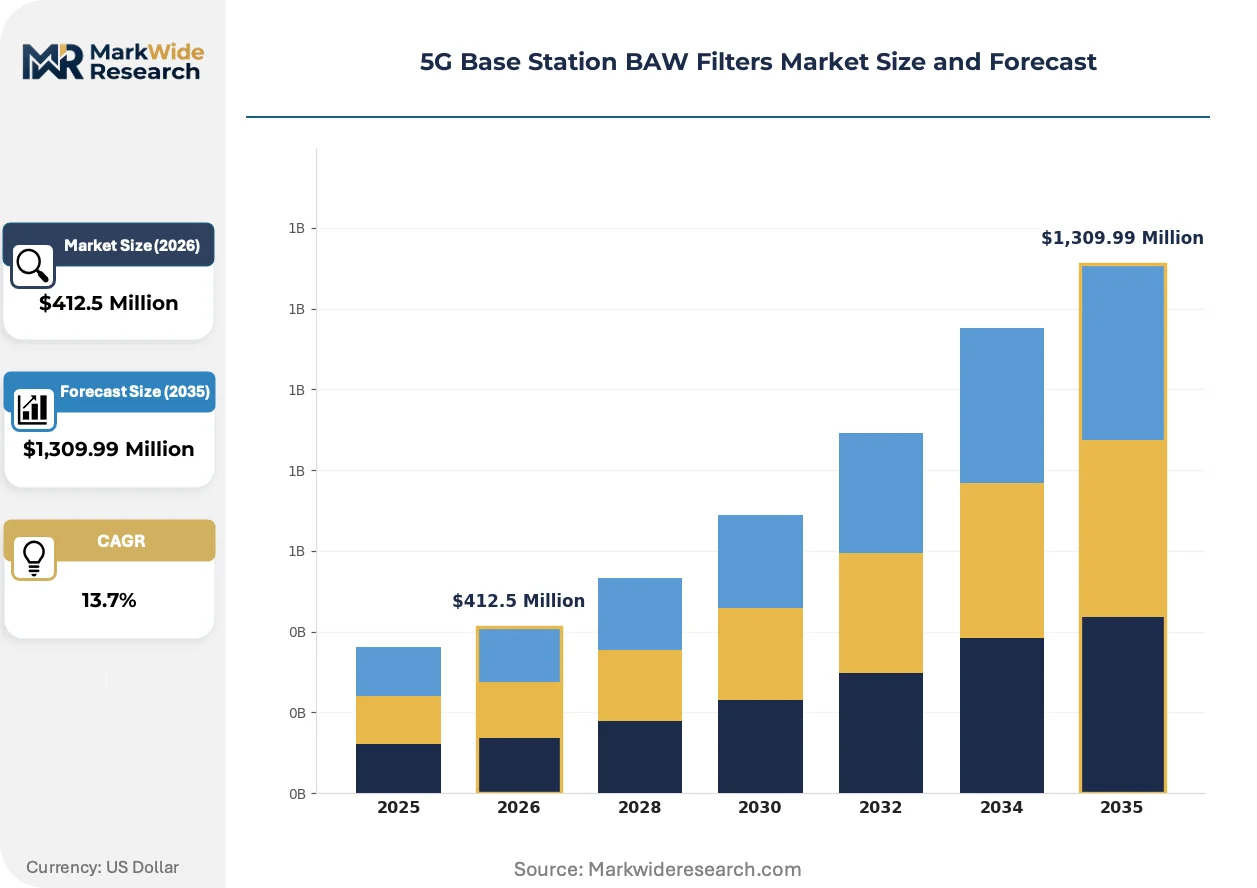
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bandpass, Lowpass, Highpass, Notch Form Factor: Surface Mount, Chip, Module, Standalone End User: Telecom Providers, OEMs, Infrastructure Providers, System Integrators Frequency Range: Sub-6 GHz, 24-39 GHz, 60 GHz, Others |
| Companies Covered | Broadcom Inc., Qorvo, Inc., Murata Manufacturing Co., Ltd., TDK Corporation, Skyworks Solutions, Inc., Akoustis Technologies, Inc., Taiyo Yuden Co., Ltd., Kyocera AVX Components Corporation, Qualcomm Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Base Station BAW Filters Market Trends and Innovations
RF front-end integration is compressing discrete component counts while spectrum fragmentation is multiplying filter SKU complexity. These opposing forces are reshaping how BAW filter suppliers organize wafer fabrication and module assembly.
Scandium-doped aluminum nitride thin films are electrifying bandwidth-performance tradeoffs in sub-6 GHz applications. Base station OEMs in China and South Korea are adopting ScAlN resonators at twice the pace of previous technology transitions. This material shift is electrifying the displacement of conventional AlN in carrier aggregation configurations requiring contiguous 100 MHz passbands.
China's MIIT dual carbon goals are tightening base station energy efficiency mandates that filter into component-level specifications. GB standards now prescribe maximum insertion loss thresholds that effectively disqualify higher-loss SAW alternatives in macro cell deployments. Mid-band 5G infrastructure in Jiangsu and Guangdong provinces faces the steepest compliance gradients, driving procurement preference toward BAW module suppliers with certified low-loss designs.
Carrier procurement is consolidating around integrated RF front-end modules that bundle filtering with power amplification and antenna switching. This specification shift is squeezing discrete filter vendors while rewarding suppliers with in-house GaN or LDMOS amplifier capabilities. The transition is most visible in Verizon and China Mobile massive MIMO tenders, where board-space constraints now override discrete component cost optimization.
5G Base Station BAW Filters Market Segmentation
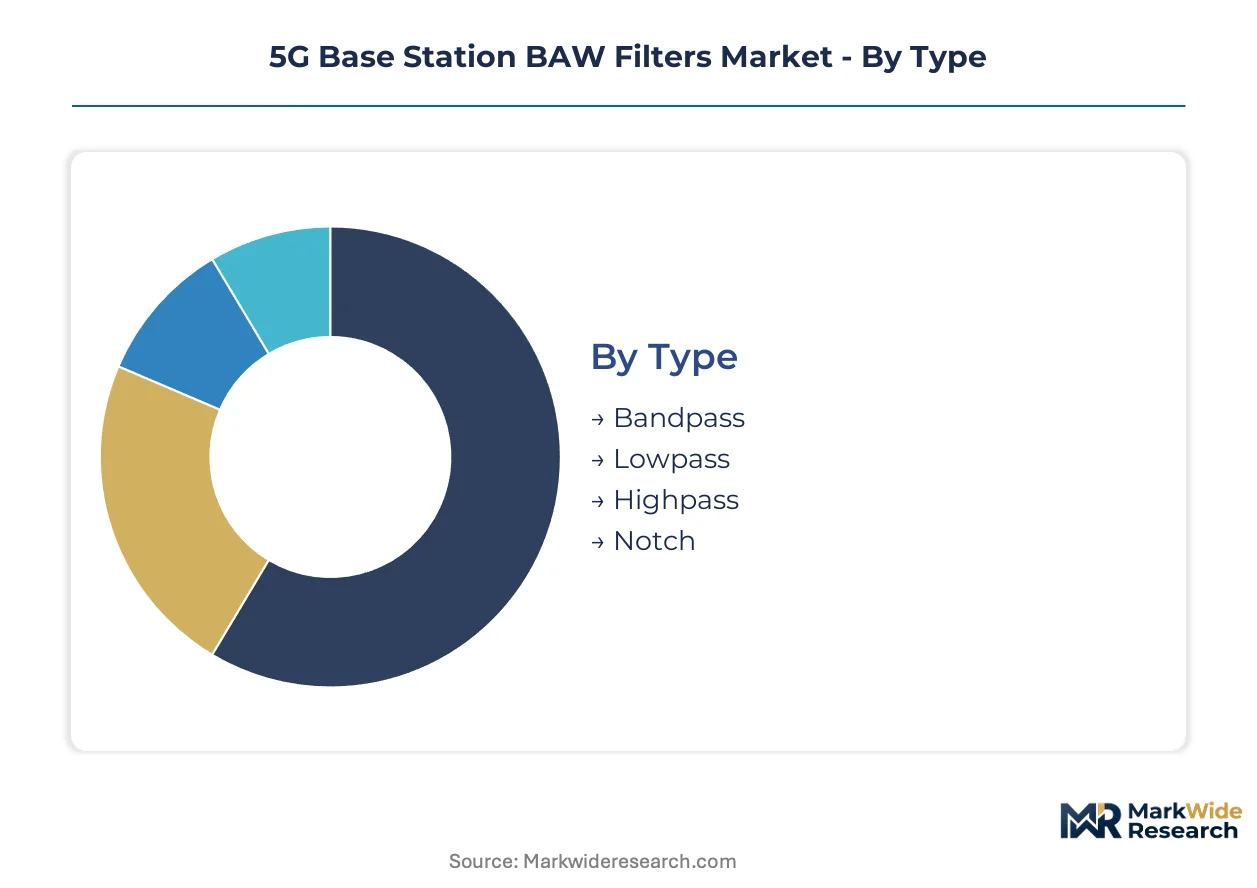
BAW filter procurement specifications fragment across frequency bands, integration levels, and buyer technical capabilities. Equipment manufacturers prioritize insertion loss thresholds and board-space constraints when selecting configurations for massive MIMO deployments.
Type:
Carrier aggregation requirements and interference management needs drive filter topology selection in base station RF chains.
- Bandpass:These configurations isolate specific 5G NR channels with steep roll-off characteristics essential for adjacent channel rejection in dense spectrum environments. China Mobile and Verizon massive MIMO tenders specify bandpass variants for n77 and n78 mid-band deployments where contiguous 100 MHz blocks demand precise edge selectivity.
- Lowpass:Suppress harmonic content above cutoff frequencies to protect receiver sensitivity in multi-band base stations. Demand concentrates in legacy 4G-5G hybrid architectures where lowpass stages precede power amplifiers in transmit paths.
- Highpass:Eliminate sub-GHz interference from co-located broadcast and cellular systems. European Open RAN deployments favor highpass preprocessing for sub-3 GHz spectrum refarming scenarios.
- Notch:Deep rejection at specific interfering frequencies protects sensitive receiver chains without sacrificing passband insertion loss. Military-adjacent commercial infrastructure in South Korea specifies notch filtering for radar coexistence in 3.5 GHz bands.
Volume sits with Bandpass; growth tilts toward Notch as spectrum congestion intensifies.
Form Factor:
Board-space constraints and thermal management complexity determine integration level preferences among telecom equipment manufacturers.
- Module:Integrated filter-amplifier-antenna combinations reduce component count by consolidating discrete functions into single packages. Samsung and Ericsson massive MIMO arrays specify module form factors for 64T64R configurations where every square millimeter of PCB area carries weight penalties.
- Surface Mount:Standard solderable packages suit high-volume pick-and-place assembly in small cell and indoor distributed antenna systems. Demand clusters with Indian and Southeast Asian infrastructure providers scaling 5G enterprise networks.
- Chip:Bare die configurations enable custom packaging for specialized thermal or electrical performance requirements. Japanese base station OEMs specify chip-level supply for proprietary module integration protecting intellectual property.
- Standalone:Discrete hermetic packages serve repair-channel inventory and legacy system upgrades where module obsolescence creates sourcing risk. North American rural broadband programs favor standalone spares for multi-year deployment timelines.
Procurement is shifting toward Module; Surface Mount retains volume leadership in cost-sensitive small cell segments.
End User:
Technical specification authority and volume purchasing power vary sharply across buyer categories in telecom supply chains.
- Telecom Providers:Verizon, Deutsche Telekom, and Bharti Airtel wield direct procurement influence over RF front-end specifications in network equipment tenders. These carriers specify insertion loss, power handling, and temperature range requirements that cascade through OEM supply chains.
- OEMs:Huawei, Ericsson, Nokia, and ZTE aggregate component demand across multiple carrier programs while competing on total cost of ownership metrics. Their filter sourcing decisions balance performance certification breadth against manufacturing scale economies.
- Infrastructure Providers:Tower companies and neutral host operators specify filter performance for multi-tenant colocation scenarios where interference isolation carries lease value implications.
- System Integrators:Regional deployment specialists aggregate procurement for government and enterprise private network builds with customized frequency plans outside standard 3GPP bands.
Revenue concentrates with OEMs; margin expansion favors direct Telecom Provider specifications bypassing intermediate value capture.
Frequency Range:
Spectrum allocation decisions by national regulators create demand pulses at specific frequency boundaries that filter manufacturers must anticipate.
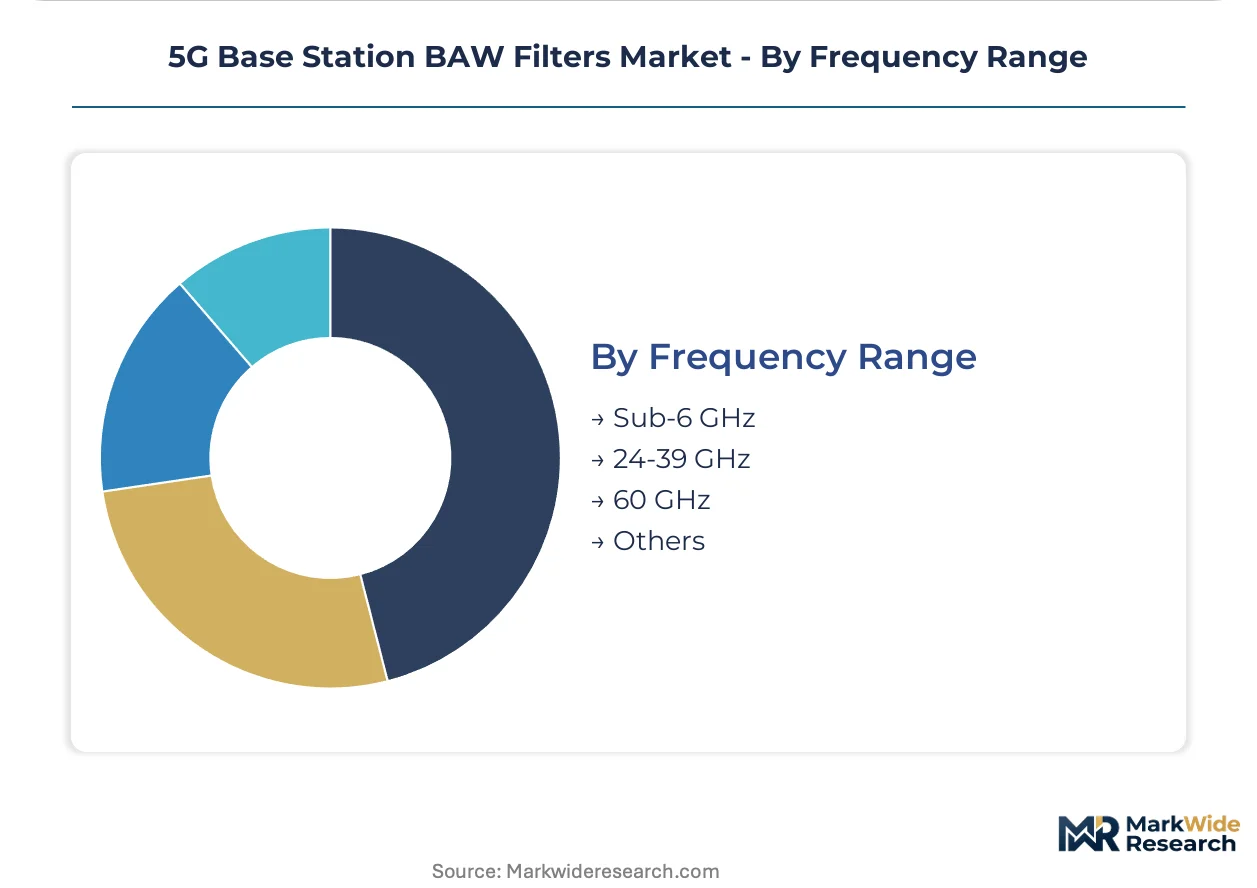
- Sub-6 GHz:n77, n78, and n79 bands anchor current deployment volumes with proven BAW resonator performance below 6 GHz insertion loss thresholds. China's MIIT spectrum assignments in 3.3-3.6 GHz and 4.8-5.0 GHz bands drive wafer-level demand through Shenzhen manufacturing clusters.
- 24-39 GHz:Millimeter-wave bands for urban capacity densification face BAW Q-factor degradation that forces hybrid filter-LNA architectures. South Korean and US carrier trials in 28 GHz and 39 GHz are expanding fastest despite technical complexity premiums.
- 60 GHz:Unlicensed and lightly-licensed bands for fixed wireless access and backhaul applications demand specialized filter designs outside traditional cellular optimization.
- Others:Emerging 47 GHz and 71 GHz allocations for 6G research and specialized industrial applications represent exploratory demand with unproven commercial scale.
Shipment volumes remain with Sub-6 GHz; 24-39 GHz climbs fastest as urban millimeter-wave densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-designated information technology manufacturing zones concentrate BAW filter fabrication capacity in Jiangsu and Guangdong provinces. Shenzhen's special economic zone incentives pull wafer-level production into Pearl River Delta clusters.
United States
Verizon and AT&T massive MIMO deployments drive filter demand through Ericsson and Nokia supply chains. FCC mid-band spectrum auctions compress equipment certification timelines to 14-22 weeks. Austin and Phoenix semiconductor corridors host RF front-end module assembly for domestic carrier procurement.
China
China Mobile's 5G base station rollout absorbs the majority of Asia-Pacific BAW filter wafer starts. MIIT dual carbon goals tighten insertion loss mandates that favor low-loss BAW over SAW alternatives. Suzhou and Dongguan manufacturing clusters scale aluminum nitride deposition capacity ahead of verified equipment orders.
South Korea
Samsung Networks and LG Uplus specify integrated filter-amplifier modules for 64T64R massive MIMO arrays. The country's national spectrum regulator accelerates 28 GHz millimeter-wave trials in Seoul metropolitan zones. Busan-Ulsan industrial corridors concentrate GaN amplifier-BAW filter co-packaging expertise.
Japan
NTT DOCOMO and KDDI procurement prioritizes hermetic standalone filters for multi-year rural broadband timelines. METI industrial policy supports scandium-doped aluminum nitride research through public-private partnerships. Kyoto-Osaka precision ceramics clusters supply deposition-grade substrates to regional filter fabricators.
Germany
Deutsche Telekom Open RAN tenders create entry points for specialized BAW suppliers outside incumbent supply chains. ETSI energy efficiency standards favor low-insertion-loss configurations in CE-marked base station equipment. Bavaria's semiconductor corridor hosts RF component testing and qualification facilities.
5G Base Station BAW Filters Market Competitive Landscape
Top-tier vendors anchor high-volume wafer fabrication, while mid-tier specialists compete through RF front-end integration expertise. The vendor base stratifies across three tiers: integrated semiconductor conglomerates with captive AlN deposition, RF module specialists with amplifier-filter co-design capabilities, and niche ceramic substrate suppliers. Competitive positioning crystallizes around two dominant moves: backward integration into aluminum nitride wafer supply and strategic partnerships with GaN amplifier manufacturers for integrated module development.
Among US-based semiconductor conglomerates, Broadcom Inc. and Qorvo, Inc. occupy positions representing scale-driven and integration-focused archetypes respectively. Broadcom exemplifies the wafer-fabrication-scale anchor with semiconductor manufacturing depth. Qorvo represents the RF front-end integration specialist competing through design wins with telecom equipment manufacturers. Japanese fabricators Taiyo Yuden Co., Ltd. and Murata Manufacturing Co., Ltd. sit within the precision ceramics and passive component tier, leveraging substrate expertise from adjacent consumer electronics markets.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Qorvo, Inc. |
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| Skyworks Solutions, Inc. |
| Akoustis Technologies, Inc. |
| Taiyo Yuden Co., Ltd. |
| Kyocera AVX Components Corporation |
| Qualcomm Incorporated |
| Others |
Pricing and Supply Chain Analysis
Telecom equipment OEM procurement concentration in China Mobile and Verizon massive MIMO tenders enforces contract-based long-term offtake pricing with volume-scaled tiering. This buyer structure rewards certified module suppliers with captive aluminum nitride deposition capacity while squeezing discrete filter vendors on margin.
Pricing Analysis
Premium pricing for sub-12-week lead times compresses standard delivery windows as carriers accelerate mid-band 5G rollouts. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified low-insertion-loss modules from generic surface-mount alternatives. Cost compression in economy-tier chip-level supply is intensifying because Shenzhen manufacturing clusters are scaling scandium-doped aluminum nitride deposition ahead of demand verification. Small cell infrastructure providers in Southeast Asia exhibit highest price sensitivity, while Japanese base station OEMs prioritize hermetic standalone filters with minimal negotiation leverage.
Supply Chain Analysis
China's domestic-content mandates for GB-standard base station equipment are reshaping sourcing patterns for non-Chinese filter fabricators. Deposition-grade aluminum nitride substrates concentrate in Japan, South Korea, and the United States, drawing from Kyoto-Osaka precision ceramics clusters and Korean specialty ceramic suppliers. Single-source vulnerability in 200mm silicon wafer supply creates exposure to foundry allocation constraints. Distribution runs through direct OEM supply agreements with Huawei, Ericsson, Nokia, and ZTE, bypassing traditional component distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FCC and MIIT certification timelines force capital-intensive qualification investments that weaker players cannot sustain.
For Market Incumbents: Acquire captive aluminum nitride wafer supply to secure input cost control against Japanese and Korean substrate bottlenecks. Broadcom and Qorvo should expand scandium-doped thin-film deposition capacity in Austin and Phoenix semiconductor corridors ahead of 3GPP Release 17 certification waves. Defensive positioning requires GaN amplifier-filter co-packaging partnerships to capture integrated module margins as discrete filter demand fragments. For New Entrants and Emerging Players: Scandium-doped aluminum nitride process engineering expertise offers the most penetrable wedge for specialized foundry services outside incumbent supply chains. Target India's TRAI-spectrum-driven 5G infrastructure buildout through Bharti Airtel and Reliance Jio procurement channels previously dominated by Chinese OEMs. Open RAN disaggregation specifications create entry points for filter-amplifier module suppliers without legacy baseband unit relationships. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with certified low-loss BAW designs and existing GaN amplifier partnerships. Long-term viability hinges on positioning ahead of millimeter-wave densification cycles and 6G research allocations. Watch MIIT dual carbon goal enforcement gradients in Jiangsu and Guangdong provinces as inflection indicators for procurement specification shifts toward energy-efficient filter configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into AlN Substrate Supply | Kyocera AVX and Taiyo Yuden secure deposition-grade ceramic feedstock against Japanese supplier concentration. |
| Scandium-Doped AlN Process Scale-Up | Akoustis Technologies extends bandwidth-performance tradeoffs for China Mobile carrier aggregation configurations. |
| GaN Amplifier-Filter Co-Packaging Partnership | Skyworks Solutions captures Samsung Networks 64T64R massive MIMO module specifications in Busan-Ulsan corridors. |
| Open RAN RF Front-End Certification | Specialized BAW suppliers bypass Huawei and ZTE incumbent supply chains through Deutsche Telekom tenders. |
| India Telecom Infrastructure Direct Supply | Filter vendors establish TRAI-compliant channels to Bharti Airtel and Reliance Jio outside Chinese OEM aggregation. |
Research Methodology
Multi-period observation of FCC certification timelines, MIIT spectrum allocation announcements, and carrier procurement tender patterns anchored the trend analysis, supplemented by interviews with RF front-end engineering directors at telecom equipment OEMs, procurement leads at tower companies, semiconductor fabrication planners, and regulatory affairs specialists at filter module suppliers. Secondary validation drew from FCC equipment authorization databases, MIIT GB standard publications, 3GPP release documentation, and SEC filings of publicly traded semiconductor conglomerates. Bottom-up wafer-start estimates and top-down carrier capex projections were triangulated to constrain volume forecasts.
Input-output matrices mapped aluminum nitride deposition capacity to verified equipment orders across frequency range, form factor, and end user segmentation dimensions. Modeled variables included sub-6 GHz versus millimeter-wave adoption curves, integrated module versus discrete component mix shifts, and regional regulatory compliance cost differentials. CAGRs were derived from fitted growth curves against carrier deployment schedules and spectrum auction completion timelines.
Several conditions sit outside the modeled scope, including unforeseen spectrum reallocation decisions by national regulators, breakthrough filter technologies displacing BAW resonators, and geopolitical trade restrictions affecting substrate supply chains. Forecasts reflect documented assumptions about carrier procurement continuity and certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Fuse Bases Market
Electronic Components
Encoder Market
Electronic Components
Switch Diode Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Power Inductors Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Automation Component Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Passive Attenuator Market
Electronic Components
GPIO Expanders Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Speaker Cone Material Market
Electronic Components
North America USB Retimer Market
Electronic Components
Touchless Tubes Market
Electronic Components
China Crystal Oscillator Market