
 Dual Voltage Comparator Market | 2026-2036
Dual Voltage Comparator Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Voltage Comparator Market Intelligence
The EU's RoHS directive is recalibrating the cost-of-entry calculus for component suppliers. This regulation necessitates investments in lead-free manufacturing processes and materials science. Texas Instruments leverages its vast portfolio to offer compliant solutions across multiple price points. STMicroelectronics differentiates through its focus on automotive-grade comparators that meet stringent reliability standards.
A dual voltage comparator is an integrated circuit with two independent comparators designed to contrast analog voltage inputs and produce a digital output. Performance is defined by parameters such as low propagation delay and minimal input offset voltage. Automotive Systems represent the fastest-growing application segment, requiring high-reliability components. Within technology, CMOS-based comparators dominate due to their low power consumption, while BiCMOS technology is preferred for high-performance applications.
Compliance frameworks like the FCC Part 15 rules in the United States and CE marking requirements in Europe govern electromagnetic compatibility. In China, adherence to GB standards is mandatory for market access, influencing component design and testing protocols. Ultimately, vendor success depends on balancing the trade-offs between speed, power consumption, and package size to meet diverse end-user requirements.
Market Dynamics
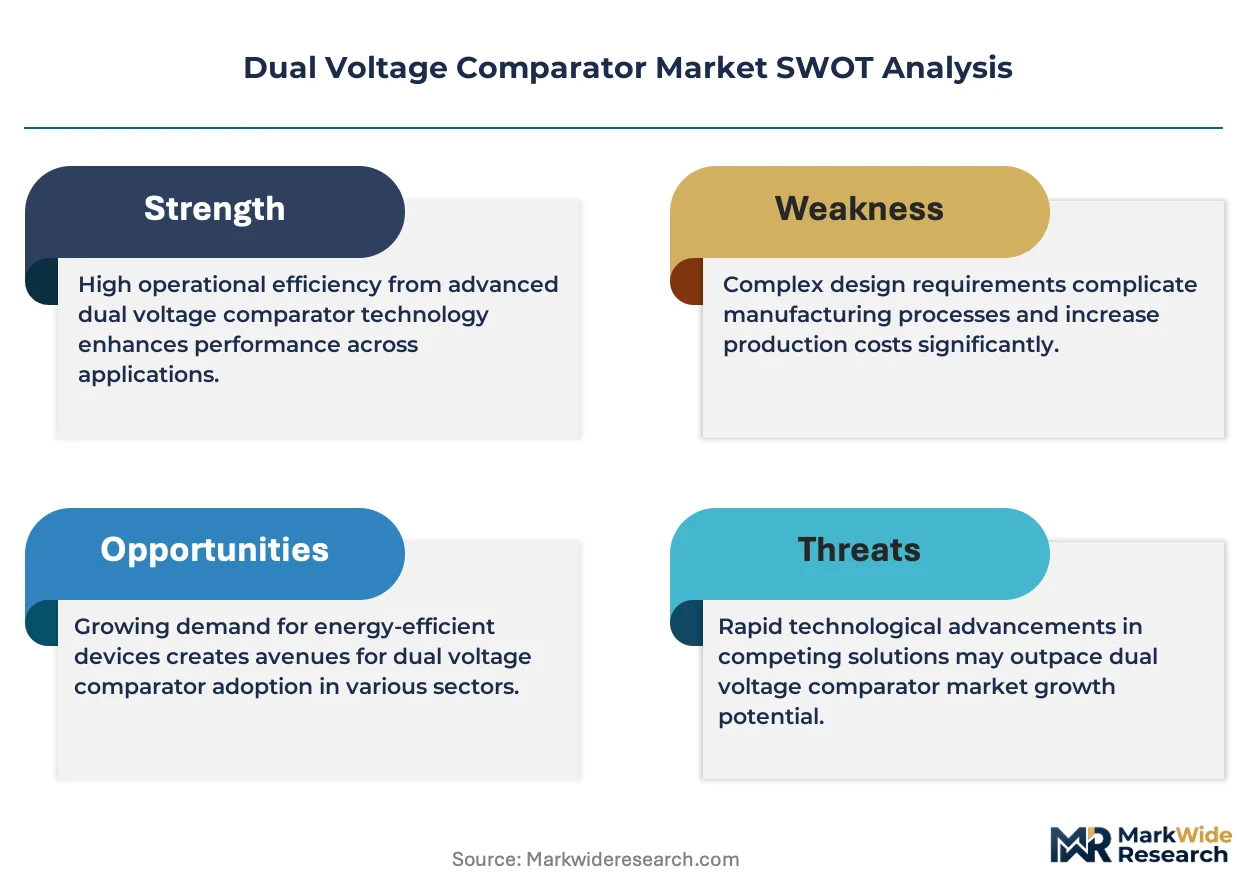
The dual voltage comparator market is shaped by the fundamental tension between the demand for higher performance metrics, such as reduced propagation delay, and the stringent material and manufacturing constraints imposed by global environmental regulations like the EU's RoHS directive.
Growth Catalysts
- Automotive Electrification:The expansion of advanced driver-assistance systems (ADAS) and electric vehicle (EV) battery management systems creates substantial demand for high-reliability comparators that can operate in harsh automotive environments.
- Industrial Automation in China:China's focus on upgrading its industrial base, part of its national strategy, accelerates the adoption of comparators in factory automation, robotics, and process control systems.
- CMOS Technology Adoption:The widespread integration of low-power CMOS-based comparators in battery-operated consumer electronics, from smartphones to wearables, provides a consistent volume driver for the market.
Market Restraints
- Input Cost Volatility:The shift to lead-free manufacturing processes, mandated by the RoHS directive, introduces higher costs and supply chain volatility for specialized solders and substrate materials.
- Performance Trade-Offs:A persistent technical restraint is the inherent trade-off between comparator speed (propagation delay) and power consumption, forcing design compromises for different end-use applications.
- Functional Integration:The increasing integration of comparator functionalities into more complex System-on-Chip (SoC) and microcontroller (MCU) solutions poses a substitution threat, particularly in high-volume consumer devices.
Strategic Opportunities
- High-Frequency Applications:Development of BiCMOS comparators tailored for high-speed data communications and 5G infrastructure presents a high-margin growth opportunity beyond traditional industrial uses.
- Medical Device Miniaturization:The need for smaller, lower-power components in portable and implantable medical devices, such as glucose monitors and diagnostic tools, opens a new application frontier.
- Emerging Electronics Hubs:Expanding manufacturing operations into developing electronics hubs in Southeast Asia, including Vietnam and Malaysia, allows for diversification and access to new regional demand.
Industry Challenges
- Regulatory Compliance Overhead:Navigating a fragmented landscape of compliance standards, including FCC Part 15 in the US, CE marking in Europe, and GB standards in China, adds significant testing and certification costs.
- Shrinking Form Factors:Intense pressure from mobile and wearable device manufacturers to reduce component package size challenges thermal management and signal integrity, demanding advanced packaging innovations.
- Supply Chain Transparency:Ensuring end-to-end compliance with conflict minerals regulations and environmental directives requires greater visibility and control over raw material sourcing, adding complexity for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Voltage Comparator Market |
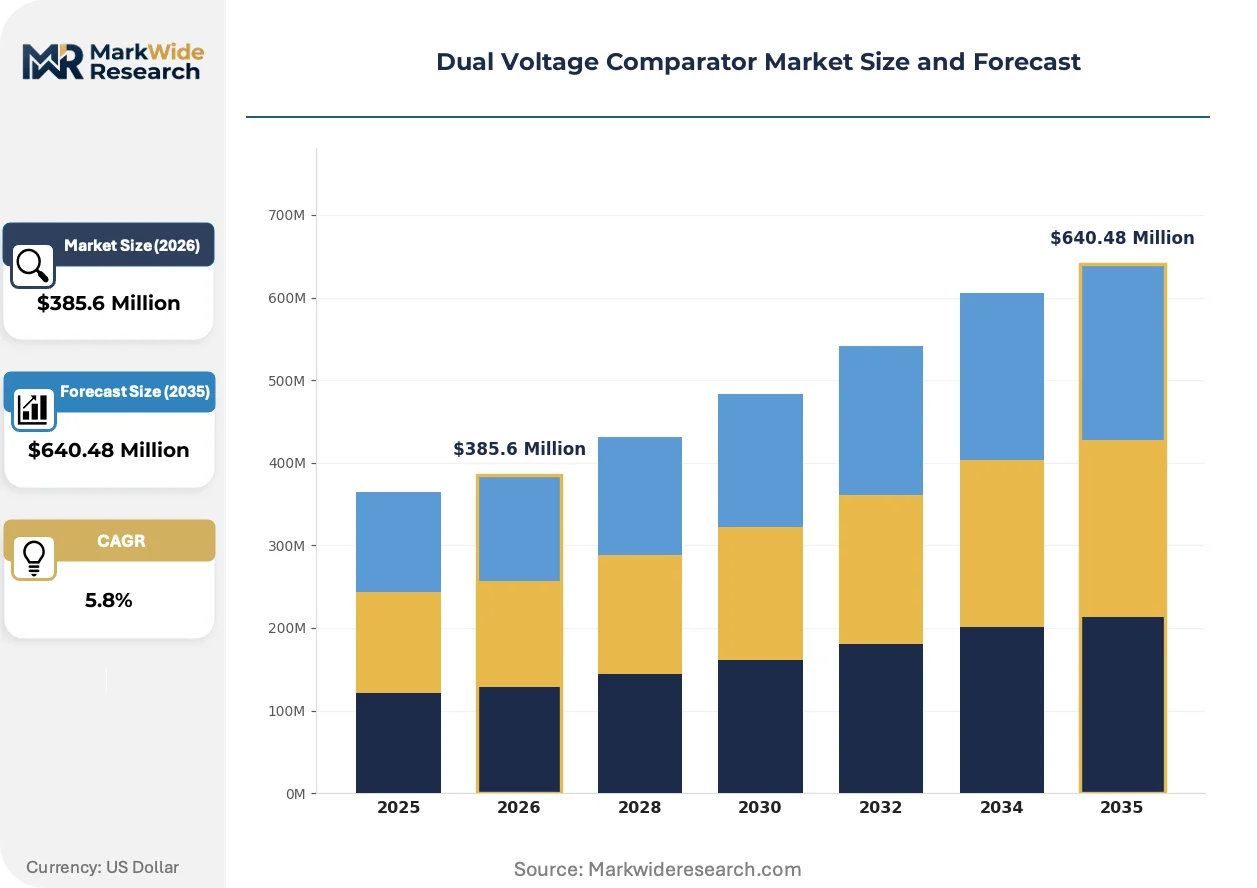
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Comparators, Window Comparators, High-Speed Comparators, Precision Comparators Technology: CMOS, Bipolar, BiCMOS, Low-Voltage Application: Consumer Electronics, Automotive Systems, Industrial Automation, Medical Devices End User: OEMs, Device Manufacturers, Research Institutions, Aftermarket Providers |
| Companies Covered | NXP Semiconductors, Microchip Technology Inc., Texas Instruments, Advanced Linear Devices, Inc., Renesas Electronics, Analog Devices Inc., ON Semiconductor, New Japan Radio Co., Ltd., STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Voltage Comparator Market Strategic Shifts & Innovations
Component-level intelligence and application-specific designs are defining the next generation of dual voltage comparators. This evolution is driven by end-system demands for greater reliability and efficiency, pushing innovation beyond simple voltage comparison into more integrated functional roles.
Integrated self-calibration features represent a significant product evolution. These circuits allow the comparator to automatically correct for input offset voltage drift caused by temperature changes or aging. Automotive and industrial control sectors are rapidly adopting these intelligent components for safety-critical systems, where long-term stability is paramount. This integration of on-chip diagnostics is decentralizing system-level health monitoring to the individual component, creating more resilient and fail-safe electronic designs.
Global electromagnetic compatibility (EMC) regulations are tightening design parameters. Mandates like the FCC Part 15 rules in the United States and Europe's CE marking requirements compel manufacturers to minimize electromagnetic interference. This forces significant investment in advanced circuit layouts, internal shielding, and filtering techniques to ensure components do not disrupt adjacent electronics. High-frequency comparators used in telecommunications and automotive sensor interfaces are the most affected segment, undergoing rigorous testing to achieve certification.
A clear behavioral shift is visible as original equipment manufacturers (OEMs) increasingly favor application-specific comparators over general-purpose parts. This trend disrupts the broad-line distribution model, creating an advantage for suppliers who can offer optimized solutions for niche tasks like overcurrent detection or window comparison. The preference for specialized components is most pronounced in the high-volume consumer electronics industry in Asia and the automotive systems sector in Germany, where performance optimization is critical.
Dual Voltage Comparator Market Segmentation
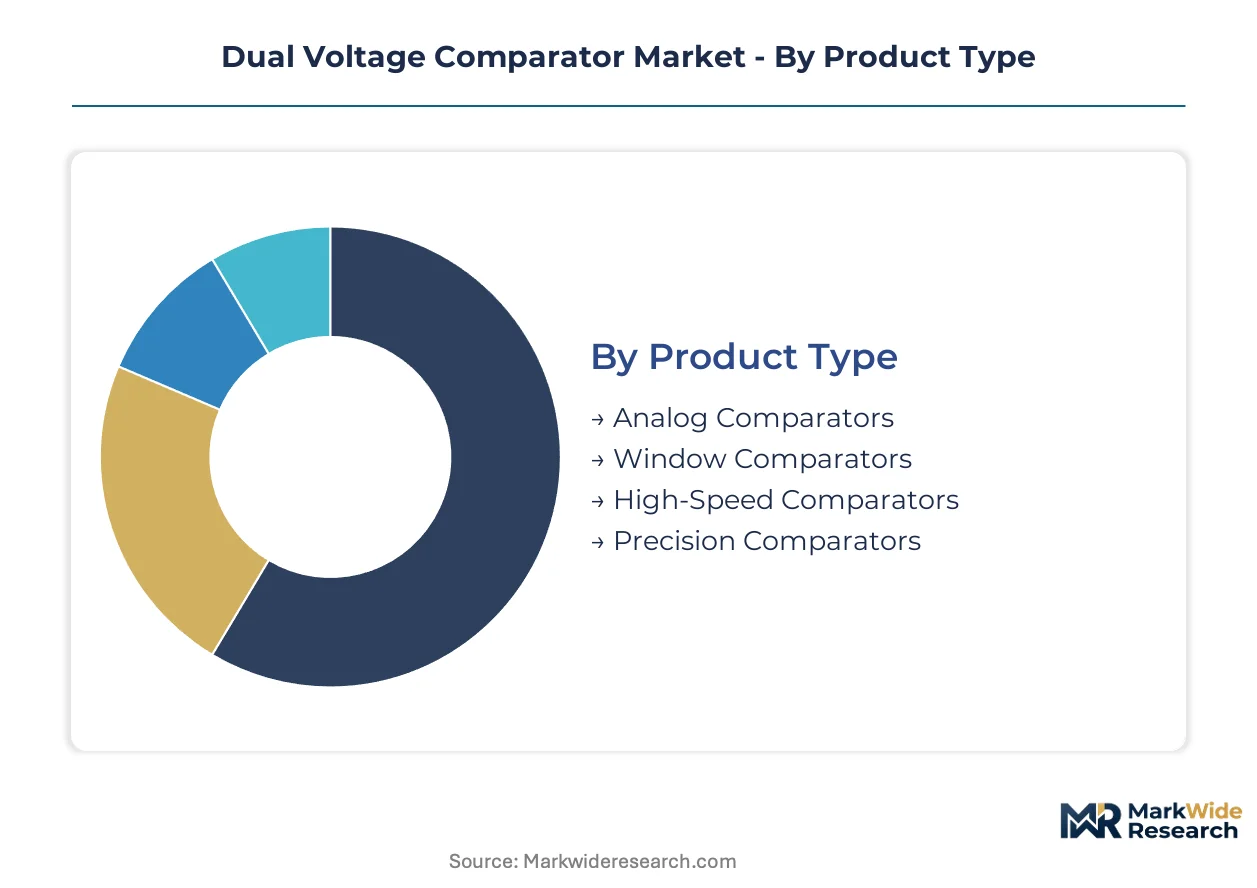
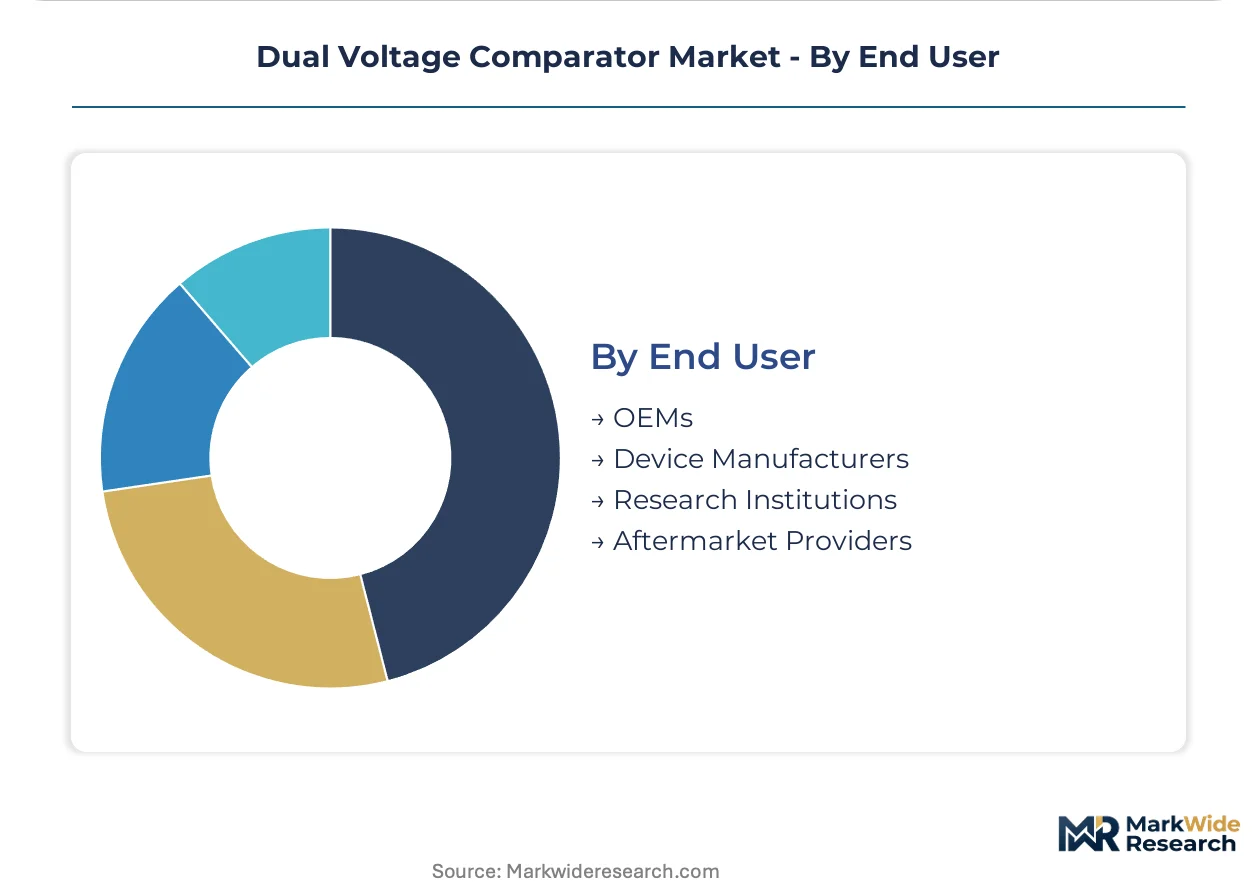
Understanding the dual voltage comparator market through segmentation reveals how diverse end-user demands shape product development and technology adoption. Each segment reflects distinct performance needs, cost sensitivities, and regulatory compliance requirements across various industrial and consumer applications.
Product Type:
The selection of dual voltage comparators by product type is primarily driven by the specific performance requirements of the target application.
- High-Speed Comparators:These components are engineered for applications demanding rapid signal processing, characterized by extremely low propagation delays. Demand concentrates in telecommunications infrastructure and high-frequency data acquisition systems, where swift decision-making is critical for system integrity.
- Precision Comparators:Designed to offer minimal input offset voltage and hysteresis, these comparators ensure accurate voltage threshold detection. Their demand is particularly strong in medical diagnostic equipment and industrial process control, where measurement fidelity directly impacts operational safety and quality.
- Analog Comparators:These general-purpose devices provide basic voltage comparison functions for a broad range of cost-sensitive applications.
- Window Comparators:These comparators determine if an input voltage falls within a predefined upper and lower threshold, commonly used in battery monitoring.
High-Speed Comparators lead on scale; Precision Comparators exhibit the fastest-growing trajectory.
Technology:
Technology choices for dual voltage comparators are often dictated by the balance between power efficiency and processing speed demanded by the end-system.
- CMOS:Complementary Metal-Oxide-Semiconductor comparators are favored for their ultra-low power consumption, making them dominant in battery-operated consumer electronics. Their widespread integration in smartphones and wearables provides a consistent volume driver for manufacturers.
- BiCMOS:This technology combines the high input impedance of CMOS with the high current drive capability of bipolar transistors, delivering superior performance. BiCMOS solutions are preferred for high-performance applications in automotive systems and 5G infrastructure, where both speed and robust output are essential.
- Bipolar:Known for their high speed and robust output drive, bipolar comparators find use in older designs or specific industrial applications requiring higher voltage tolerance.
- Low-Voltage:These comparators are optimized to operate efficiently with minimal supply voltages, crucial for portable devices and energy-efficient designs.
CMOS technology gains share fastest; BiCMOS technology demonstrates the steepest expansion trajectory.
Application:
The volume of dual voltage comparator deployment is heavily influenced by the expansion of specific end-use sectors requiring reliable analog-to-digital conversion.
- Automotive Systems:This segment includes advanced driver-assistance systems (ADAS) and electric vehicle battery management systems, demanding high-reliability components. Stringent operational parameters and safety certifications, such as AEC-Q100, drive specialized product development for this sector.
- Consumer Electronics:From smartphones to home appliances, this sector represents a significant volume driver for dual voltage comparators due to pervasive demand for power management. The emphasis here is on miniaturization, low power, and cost-effectiveness for mass production.
- Industrial Automation:Comparators are integral to factory automation, robotics, and process control systems, especially in China's industrial upgrading initiatives.
- Medical Devices:The need for smaller, lower-power components in portable and implantable medical equipment, like glucose monitors, creates a niche for specialized comparators.
Automotive Systems are climbing the fastest; Consumer Electronics continue to drive substantial volumes.
End User:
Dual voltage comparator procurement patterns vary significantly across different end-user types, reflecting distinct purchasing power and integration needs.
- OEMs:Original Equipment Manufacturers integrate dual voltage comparators directly into their final products, driving demand for high-volume, application-specific components. Their purchasing decisions prioritize cost-effectiveness, supply chain reliability, and technical support.
- Device Manufacturers:These entities produce sub-assemblies or modules that incorporate comparators, serving as intermediaries before final product integration. They seek components that offer flexibility in design and adherence to specific module-level performance standards.
- Research Institutions:Academic and corporate research bodies utilize comparators for prototyping, experimental setups, and developing new electronic systems.
- Aftermarket Providers:These suppliers offer components for repair, maintenance, and upgrade of existing electronic systems, often requiring compatibility with legacy designs.
OEMs represent the largest purchasing segment; Device Manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global dual voltage comparator market finds significant talent concentrations anchoring its regional growth. Highly skilled engineering workforces in key technology hubs drive innovation and manufacturing capabilities. These specialized workforces underpin advanced product development and market expansion across several crucial geographies.
United States
Demand for high-speed comparators stems from data centers and 5G infrastructure expansion, requiring rapid signal processing. FCC Part 15 rules mandate strict electromagnetic compatibility for electronic devices, influencing design and testing protocols. Silicon Valley continues to innovate in advanced integrated circuit design, fostering next-generation comparator technologies.
China
Industrial automation initiatives and consumer electronics manufacturing drive substantial comparator volumes. Adherence to GB standards is mandatory for market access, influencing component design and testing protocols. The Yangtze River Delta region serves as a major production hub for electronics, consuming vast quantities of these components.
Germany
Automotive systems, particularly ADAS and EV battery management, create significant demand for high-reliability comparators. CE marking requirements in Europe compel manufacturers to minimize electromagnetic interference, impacting component design. Bavaria hosts major automotive and industrial electronics clusters, driving specialized comparator development for safety-critical applications.
Japan
Precision comparators are crucial for medical diagnostic equipment and industrial process control systems. METI policies support advanced manufacturing and semiconductor research, fostering domestic innovation. Tokyo and Osaka remain key centers for electronics manufacturing and R&D, focusing on high-fidelity measurement solutions.
South Korea
Consumer electronics, especially smartphones and wearables, provide a consistent volume driver for low-power CMOS comparators. The country's national regulatory bodies emphasize product safety and performance standards for electronics. Seoul and Gyeonggi Province house major electronics conglomerates, driving demand for miniaturized and energy-efficient comparator solutions.
Dual Voltage Comparator Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the dual voltage comparator market, creating a dynamic competitive environment. The market structure exhibits a tiered consolidation, with a few large integrated device manufacturers holding significant market share, particularly in high-volume segments. Strategic archetypes include broad-portfolio suppliers catering to diverse needs and niche technology innovators targeting specialized high-performance applications. Dominant competitive moves involve strategic partnerships for technology co-development and continuous portfolio diversification to meet evolving application needs across industrial and consumer sectors.
Among established semiconductor manufacturers, Texas Instruments, STMicroelectronics, and Analog Devices Inc. exemplify the broad-portfolio approach. These companies anchor the market with extensive product lines spanning various performance tiers and application segments, including automotive, industrial, and consumer electronics. Their market position often reflects a strategy of offering integrated solutions that incorporate comparator functionalities alongside other analog and mixed-signal components. This approach caters to OEMs seeking comprehensive component sourcing and technical support from a single, reliable vendor across multiple geographies, streamlining their supply chains.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Microchip Technology Inc. |
| Texas Instruments |
| Advanced Linear Devices, Inc. |
| Renesas Electronics |
| Analog Devices Inc. |
| ON Semiconductor |
| New Japan Radio Co., Ltd. |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
Silicon wafer prices, a fundamental commodity benchmark, directly cascade through the dual voltage comparator supply chain, impacting production costs and ultimately influencing pricing tiers for end products.
Pricing Analysis
Bundled solutions, which combine comparators with design-in support or additional integrated features, command higher price points than unbundled, bare ICs. Price differentiation stems from quality grade, particularly for AEC-Q100 certified automotive components, and the volume scale of procurement. Pricing pressure stems from the increasing functional integration of comparators into more complex System-on-Chip solutions. Consumer electronics OEMs exhibit the highest price sensitivity, while automotive systems buyers prioritize reliability and are less sensitive to incremental cost increases.
Supply Chain Analysis
Reverse logistics, primarily for managing defective components and ensuring end-of-life compliance with WEEE directives, adds a layer of complexity to the supply chain. Geographic supply concentrates in East Asia, with major foundries in Taiwan and specialized component manufacturing in China and South Korea. Raw material dependencies include high-purity silicon wafers and specialized metals for lead-free solder, mandated by the EU's RoHS directive. Geopolitical tensions affecting key manufacturing hubs present a structural supply chain risk. Distribution runs through a hybrid model of direct sales to large OEMs and broad-line distributors serving smaller device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dual voltage comparator market functions as a stable compounder, with sustained growth driven by the pervasive expansion of automotive electrification across vehicle platforms.
For Market Incumbents: Extend existing product lines into application-specific comparators that offer integrated self-calibration features. This addresses the substitution threat posed by highly integrated SoC solutions. Deepen partnerships with automotive OEMs for specialized, high-reliability components, leveraging AEC-Q100 certifications as a competitive lever. Invest in advanced packaging R&D to meet shrinking form factor demands from mobile device manufacturers.
For New Entrants and Emerging Players: Online design platforms, offering simulation tools and reference designs, provide a crucial digital channel for market entry. Target underpenetrated niche industrial automation segments in developing electronics hubs like Vietnam, which prioritize cost-effective, robust solutions. Focus on specialized BiCMOS comparators for high-frequency applications in 5G infrastructure, offering performance optimization as a key go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with niche specialists demonstrating expertise in advanced BiCMOS technology or innovative packaging solutions. The market exhibits long-term viability, driven by fundamental needs for analog-to-digital conversion in expanding electronic systems over the next decade. Practitioners should monitor the adoption rates of integrated self-calibration features in industrial and medical sectors for early signals of broader market acceptance beyond automotive.
| Strategic Initiative | Industry Significance |
|---|---|
| Application-Specific Product Development | Tailors components for critical functions like overcurrent detection, optimizing performance for consumer electronics. |
| Advanced Packaging Innovation | Addresses shrinking form factors and thermal management challenges for wearable device manufacturers. |
| Expanded Lead-Free Manufacturing Capacity | Ensures compliance with the EU's RoHS directive, reducing regulatory overhead for European market access. |
| Strategic Partnerships with Automotive Tier 1s | Secures long-term supply agreements for high-reliability components in ADAS systems. |
| Investment in BiCMOS Research | Captures high-margin growth opportunities in 5G infrastructure and high-speed data communications. |
Research Approach
Direct dialogue with R&D engineers, product managers, procurement leads at OEMs, and supply chain managers provided qualitative grounding for this analysis. Secondary validation drew from company financial reports, technical specifications from leading manufacturers, industry association publications, and regulatory body guidelines such as RoHS and FCC Part 15. This approach ensured a robust bottom-up and top-down triangulation of market insights.
A bottom-up approach modeled market volumes by product type, technology, application, and end user, while a top-down approach validated market value across the analysis window. Segmentation dimensions included high-speed versus precision comparators, CMOS versus BiCMOS technologies, and automotive versus consumer electronics applications. Compound annual growth rates were derived from historical trends and projected expansion in key application sectors, with ADAS penetration rates and EV production forecasts serving as critical industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for integrated SoC solutions would alter the outlook. Forecasts reflect assumptions concerning stable regulatory frameworks and continued investment in automotive electrification. Practitioners should monitor significant supply chain disruptions or rapid shifts in component integration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Global Probe Card Market