
 Semiconductor Tubular Heaters Market | 2026-2036
Semiconductor Tubular Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Tubular Heaters Market Insights
Preventive maintenance contracts and software-enabled thermal calibration services are repositioning vendor-customer relationships from equipment sales to uptime guarantees. Watlow leverages its global service infrastructure to anchor long-term semiconductor fab partnerships. Chromalox sustains R&D intensity in high-purity sheath materials for advanced node compatibility. Tempco Electric Heater Corporation specializes in rapid-response custom heating elements for legacy tool retrofits.
Semiconductor tubular heaters are cylindrical resistance heating elements, typically constructed from nickel-chromium or iron-chromium-aluminum alloys encased in magnesium oxide insulation and stainless steel or Incoloy sheaths, engineered to deliver precise, uniform thermal profiles in vacuum and controlled-atmosphere process chambers. Metal sheathed heaters dominate current procurement volumes due to their durability in corrosive chemical vapor deposition environments, while ceramic heaters command premium positioning in extreme-temperature rapid thermal processing applications where dielectric isolation proves critical. The power rating dimension reveals structural margin concentration at the ultra-high-power tier, where specialized alloys and advanced compaction techniques create meaningful barriers to competitive entry.
FDA device regulations indirectly shape heater material certifications for medical semiconductor applications, while REACH substance restrictions and RoHS hazardous material limits are forcing alloy reformulation across European supply chains. EPA emissions frameworks influence domestic manufacturing facility compliance investments, affecting heater specification requirements for abatement equipment. Semiconductor capital equipment buyers must monitor evolving thermal uniformity standards from ISO and SEMI as node transitions below 3nm redefine permissible temperature deviation thresholds.
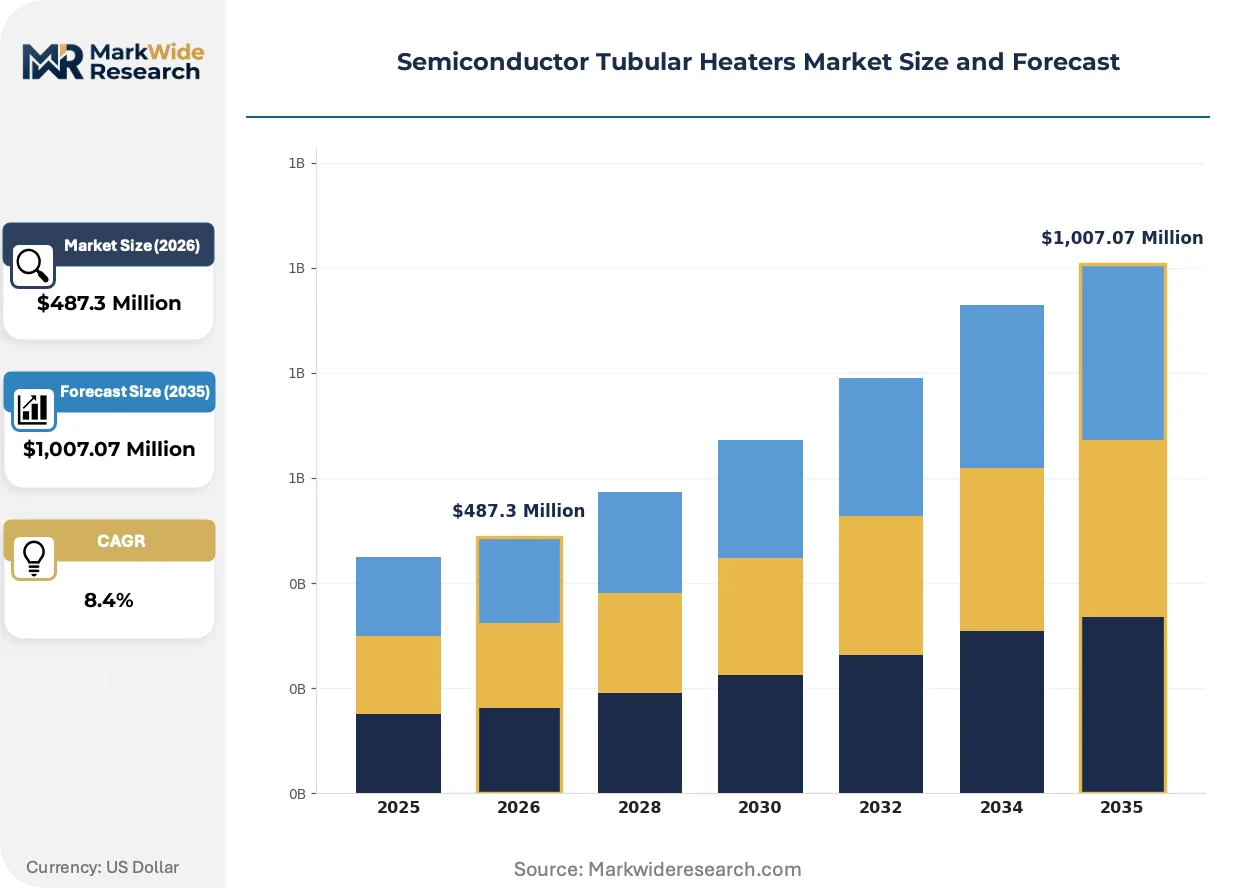
Market Dynamics
Wafer processing equipment OEMs are expanding thermal management procurement as EUV lithography nodes below 3nm demand tighter temperature control tolerances, fundamentally restructuring supplier-buyer relationships toward uptime guarantees rather than discrete equipment sales.
Growth Catalysts
- EUV Lithography Node Transition:Advanced semiconductor manufacturing below 3nm requires sub-degree thermal uniformity, forcing fab operators to upgrade legacy heating infrastructure and expand procurement of precision tubular heater systems.
- REACH and RoHS Compliance:European substance restrictions are accelerating ceramic-to-metal heater transitions across supply chains, creating replacement demand for compliant alloy formulations in magnesium oxide insulated systems.
- Pyeongtaek Cluster Expansion:South Korea's concentrated semiconductor manufacturing hub is driving localized thermal equipment procurement as foundries scale capacity for memory and logic device production.
Market Restraints
- Specialized Alloy Input Volatility:Nickel-chromium and iron-chromium-aluminum pricing fluctuations compress margins for heater manufacturers unable to pass through material cost swings to capital equipment buyers.
- Supply Concentration Risk:High-purity magnesium oxide insulation sourcing concentrates among limited suppliers, creating vulnerability for heater producers dependent on consistent dielectric performance specifications.
- Technical Limitation in Extreme Thermal Cycling:Metal-sheathed heaters face fatigue constraints in rapid thermal processing applications above 1,200°C, restricting penetration into advanced annealing equipment segments.
Strategic Opportunities
- Preventive Maintenance Service Contracts:Software-enabled thermal calibration services reposition vendor relationships toward recurring revenue models and long-term fab partnerships with guaranteed uptime commitments.
- Legacy Tool Retrofit Demand:Mature 200mm and 300mm fabrication lines require rapid-response custom heating elements to extend equipment lifecycles without full chamber replacement.
- Medical Semiconductor Certification Pathway:FDA device regulations create specialized heater material certification requirements for implantable and diagnostic chip applications, opening premium market tiers.
Industry Challenges
- Advanced Node Thermal Uniformity Standards:SEMI and ISO permissible temperature deviation thresholds below 3nm nodes require heater manufacturers to achieve precision engineering capabilities that strain existing quality systems and metrology investments.
- Integration Complexity with Legacy Abatement Systems:EPA emissions frameworks mandate heater specification alignment with exhaust treatment equipment, creating engineering friction during facility upgrades and retooling cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Tubular Heaters Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,007.07 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Heaters, Ceramic Heaters, Metal Sheathed Heaters, Flexible Heaters End User: Manufacturing Facilities, Electronics Industry, Research Laboratories, Aerospace Sector Installation: Wall-Mounted, Ceiling-Mounted, Portable, Embedded Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Watlow, Chromalox, Tempco Electric Heater Corporation, Industrial Heater Corporation, NIBE Industrier, Tutco Heating Solutions Group, Hotwatt, Zoppas Industries, Thermo Heating Element LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Tubular Heaters Market Trends and Innovations
Digital thermal management systems are displacing analog control architectures across semiconductor process chambers, compressing calibration cycles and enabling predictive maintenance models that reduce unplanned fab downtime.
Machine learning-enabled temperature profiling is automating real-time heater adjustment in chemical vapor deposition chambers. Memory foundries in South Korea are deploying these systems at scale. The technology is automating compensation for chamber-to-chamber thermal variation, reducing qualification time for new process recipes.
REACH substance restrictions are forcing alloy reformulation across European supply chains. Heater manufacturers must certify alternative nickel-chromium compositions that maintain resistivity stability while eliminating restricted substances. High-purity sheath material suppliers are accelerating R&D intensity to meet ECHA compliance deadlines without sacrificing dielectric isolation performance.
Equipment buyers are consolidating thermal component procurement through single-source agreements with uptime guarantee clauses. Wafer processing OEMs are displacing spot purchasing of discrete heaters with multi-year service contracts. South Korea's Pyeongtaek cluster exhibits the most concentrated adoption of this bundled procurement model, driven by foundry pressure to minimize chamber qualification delays.
Semiconductor Tubular Heaters Market Segmentation
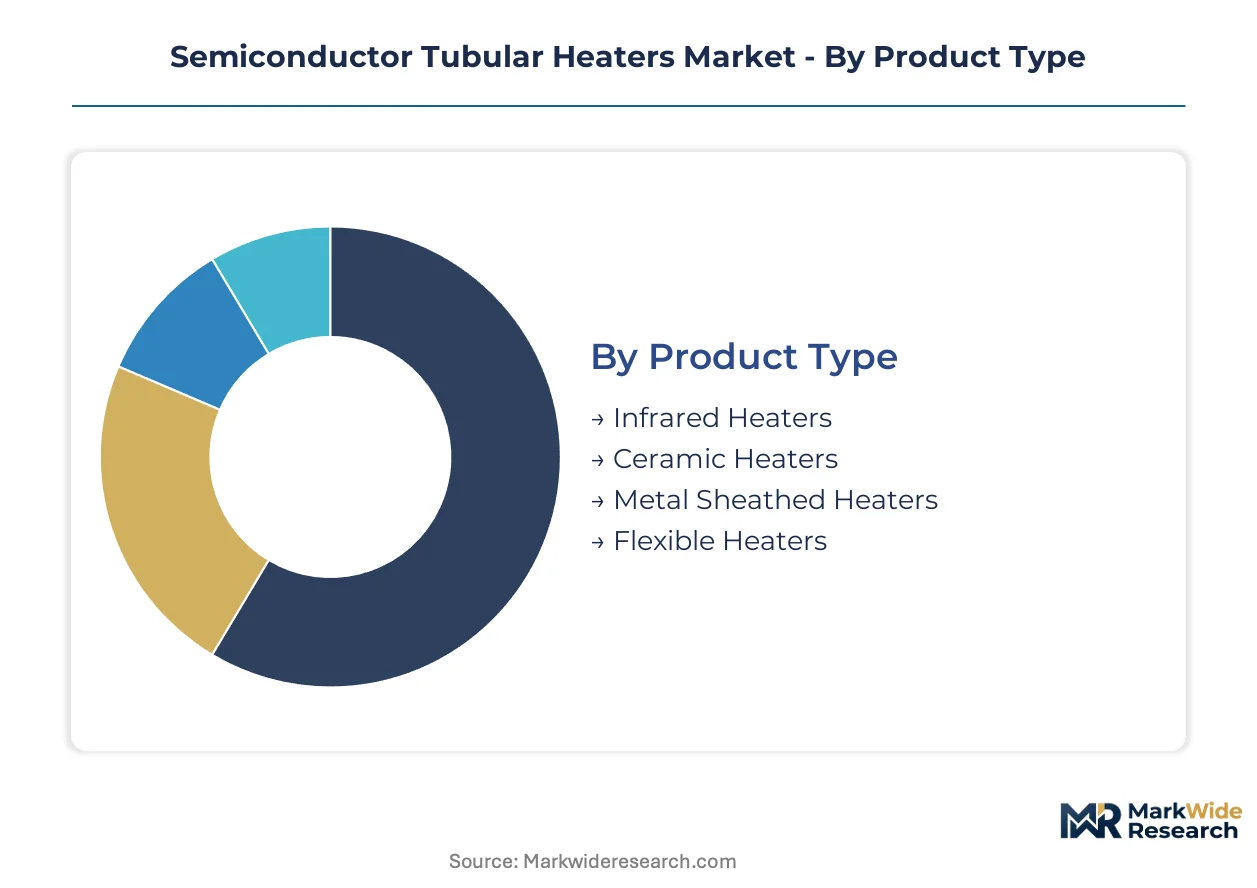
Semiconductor tubular heater procurement splits sharply between process-critical applications demanding extreme thermal precision and auxiliary heating where cost efficiency dominates. Equipment OEMs and fab operators evaluate segments through fundamentally different lenses—thermal uniformity specifications versus installation flexibility and lifecycle economics.
Product Type:
Buyers differentiate primarily by the trade-off between dielectric isolation performance and mechanical durability in corrosive process environments.
- Metal Sheathed Heaters:Constructed from nickel-chromium or iron-chromium-aluminum alloys encased in magnesium oxide insulation and stainless steel or Incoloy sheaths, these systems deliver the mechanical robustness required for chemical vapor deposition chambers. South Korea's Pyeongtaek cluster drives concentrated procurement volumes as memory foundries scale EUV lithography node production.
- Ceramic Heaters:Engineered from aluminum oxide or silicon nitride substrates with embedded resistance elements, ceramic systems provide superior dielectric isolation for rapid thermal processing above 1,000°C. Demand concentrates in advanced logic device manufacturing where sub-degree temperature uniformity proves critical for sub-3nm node yields.
- Infrared Heaters:Tungsten or carbon filament systems delivering radiant heat transfer for selective wafer surface processing.
- Flexible Heaters:Polyimide or silicone rubber substrates conforming to irregular chamber geometries for legacy tool retrofits.
Metal sheathed heaters lead volumes today; ceramic heaters are gaining share fastest in advanced node applications.
End User:
Volume concentration tracks capital expenditure cycles across semiconductor manufacturing geographies, with equipment intensity varying dramatically by fab maturity.
- Manufacturing Facilities:Wafer fabrication plants and foundries operating 200mm, 300mm, and emerging 450mm lines represent the dominant demand pool. South Korea's concentrated Pyeongtaek semiconductor cluster anchors global procurement volumes as Samsung and SK Hynix expand memory and logic capacity.
- Electronics Industry:Semiconductor packaging and test houses require precision thermal control for flip-chip and 3D integration processes. Procurement here emphasizes rapid thermal cycling durability and integration with automated handling systems.
- Research Laboratories:University and corporate R&D facilities driving early-stage process development for next-generation device architectures.
- Aerospace Sector:Specialized radiation-hardened and high-reliability chip applications requiring extended qualification protocols.
Manufacturing facilities absorb the largest absolute volumes; electronics industry procurement is climbing the fastest on advanced packaging expansion.
Installation:
Equipment architecture and chamber retrofit constraints determine installation modality selection, with embedded systems commanding premium positioning.
- Embedded:Heaters integrated directly into chamber walls or substrate susceptors deliver optimal thermal uniformity by eliminating air gaps. New EUV lithography tool installations specify embedded configurations exclusively to meet sub-degree temperature deviation thresholds.
- Portable:Modular systems enabling rapid reconfiguration for process development and legacy tool adaptation. Research laboratories and pilot lines favor portable installations to minimize chamber qualification delays between process recipes.
- Wall-Mounted:External chamber heating for auxiliary temperature maintenance and condensation prevention.
- Ceiling-Mounted:Overhead radiant configurations for specific chemical vapor deposition reactor geometries.
Embedded installations dominate new equipment specifications; portable systems show the steepest expansion trajectory on retrofit demand.
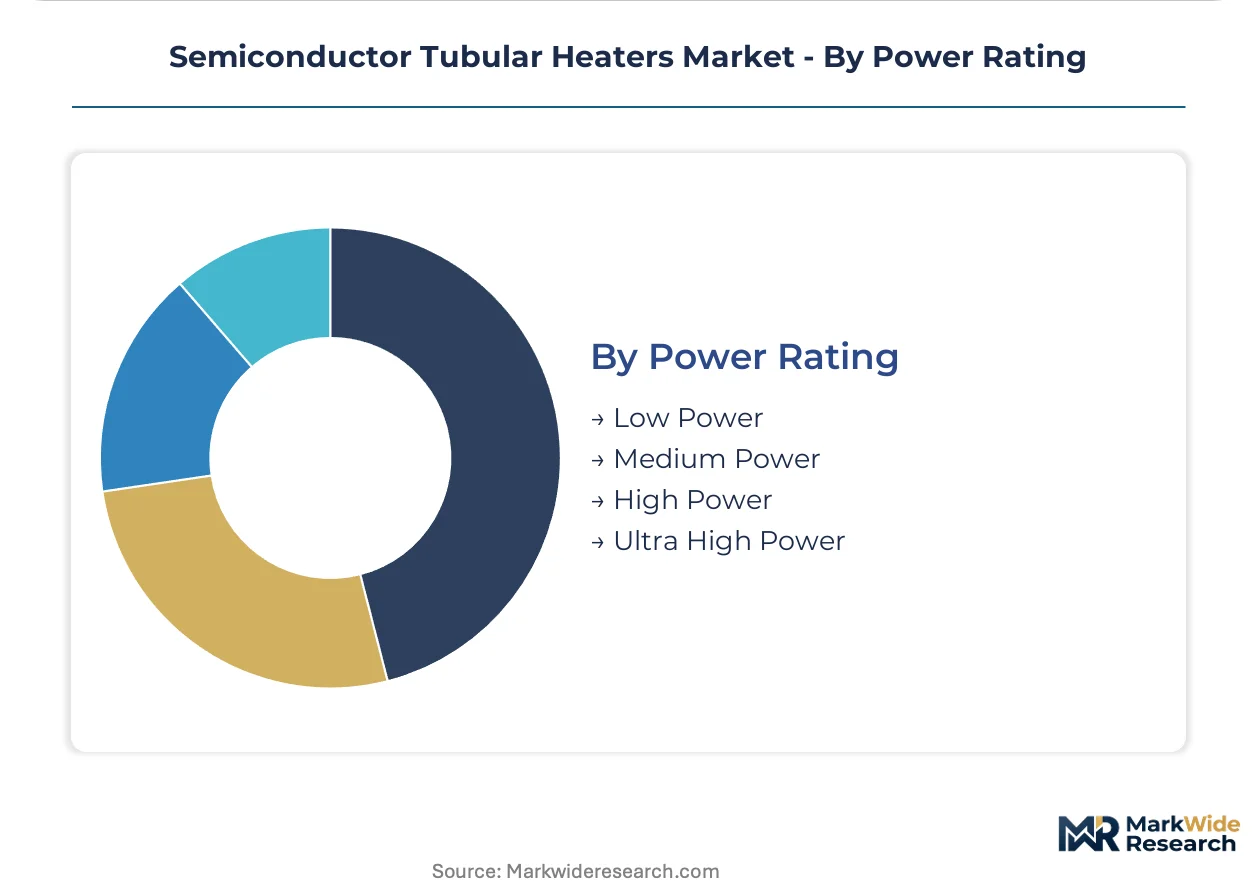
Power Rating:
Process thermal mass and ramp rate requirements stratify procurement, with ultra-high-power tiers creating meaningful supplier capability barriers.
- Ultra High Power:Systems exceeding 50 kW delivering the thermal flux density required for rapid thermal processing annealing and advanced chemical vapor deposition. Specialized alloy formulations and advanced magnesium oxide compaction techniques limit qualified supplier pools.
- High Power:20-50 kW configurations serving mainstream wafer processing equipment with balanced thermal response and energy efficiency. Foundry procurement concentrates here for 300mm production lines.
- Medium Power:5-20 kW systems for auxiliary chamber heating and legacy 200mm tool support.
- Low Power:Sub-5 kW configurations for research-scale equipment and specialized diagnostic applications.
High power ratings anchor current procurement volumes; ultra-high-power systems are expanding most quickly on advanced node thermal ramp requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Pyeongtaek cluster commands concentrated procurement volumes for EUV-grade thermal systems, while the United States sustains demand through legacy fab retrofits and advanced packaging expansion.
United States
Domestic demand splits between legacy 200mm fab retrofits and emerging advanced packaging facilities. EPA emissions frameworks mandate heater specification alignment with exhaust abatement equipment, complicating facility upgrades. The Southwest cluster—spanning Arizona and Texas—anchors procurement as Intel and TSMC expand greenfield capacity.
South Korea
Memory foundries at Samsung and SK Hynix drive ultra-high-power heater procurement for sub-3nm EUV nodes. MFDS medical device regulations create parallel certification pathways for diagnostic chip applications. Pyeongtaek's concentrated semiconductor hub exhibits the most aggressive adoption of bundled procurement models with uptime guarantees.
China
Domestic equipment localization programs accelerate ceramic-to-metal heater transitions in Yangtze River Delta fabs. MIIT industrial standards and GB certification requirements shape alloy formulation decisions. Shanghai and Hefei manufacturing clusters concentrate import substitution efforts for thermal management components.
Germany
Precision engineering heritage supports high-purity sheath material R&D for advanced node compatibility. REACH substance restrictions and RoHS hazardous material limits force systematic alloy reformulation across European supply chains. Dresden's Silicon Saxony cluster coordinates thermal equipment procurement for automotive semiconductor applications.
Japan
Materials science leadership in magnesium oxide insulation and specialized alloys sustains supplier capability barriers. METI industrial policy directs capital toward domestic thermal component resilience. Kyushu's Kumamoto and Hiroshima prefectures concentrate foundry expansion with embedded heater specifications for extreme thermal uniformity.
Semiconductor Tubular Heaters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier procurement consolidating around long-term service relationships while commoditized auxiliary heating fragments across regional fabricators. The vendor base organizes into three archetypes: integrated thermal solution providers with global service infrastructure, component specialists focused on high-purity materials, and rapid-response custom shops serving legacy tool retrofits. Dominant competitive moves include preventive maintenance contract expansion and strategic partnerships with wafer processing OEMs for embedded system co-development.
Among US-based thermal specialists, Watlow exemplifies the integrated solution archetype through its global service infrastructure, while Chromalox occupies a position representing high-purity sheath material specialization. Tempco Electric Heater Corporation anchors the rapid-response custom segment for legacy equipment adaptation. These three patterns—service-anchored, materials-focused, and retrofit-specialized—capture the competitive structure without exhaustively mapping every participant.
| Leading Market Players |
|---|
| Watlow |
| Chromalox |
| Tempco Electric Heater Corporation |
| Industrial Heater Corporation |
| NIBE Industrier |
| Tutco Heating Solutions Group |
| Hotwatt |
| Zoppas Industries |
| Thermo Heating Element LLC |
| Others |
Pricing and Supply Chain Analysis
Ultra-high-power heater certification tiers diverge sharply from commodity auxiliary heating segments, with REACH-compliant alloy formulations and embedded service contracts commanding substantial premiums while spot-market metal-sheathed units face relentless cost compression. This bifurcation maps directly onto supply chain architecture: premium tiers anchor in Japan's magnesium oxide insulation specialists and Germany's precision alloy formulators, whereas commoditized procurement flows through South Korean contract fabricators serving Pyeongtaek cluster volume buyers.
Pricing Analysis
Capacity additions in South Korea's Pyeongtaek cluster are reshaping price floors for high-power metal-sheathed heaters as Samsung and SK Hynix consolidate procurement through multi-year uptime guarantee contracts. Three-tier pricing structure across premium, standard, and economy levels separates EUV-grade embedded systems with ISO thermal uniformity certification from legacy 200mm retrofit portable units. Cost compression in the standard tier intensifies because nickel-chromium alloy input volatility passes through unevenly to smaller heater manufacturers. Memory foundries exhibit the lowest price sensitivity due to chamber qualification delays costing millions per day, while research laboratories and pilot lines show acute sensitivity to upfront capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from wafer processing equipment manufacturers, while specialized distributors serve legacy tool retrofit segments requiring rapid-response custom fabrication. Geographic supply concentration centers on Japan for high-purity magnesium oxide insulation, Germany for precision alloy R&D, and South Korea for volume metal-sheathed heater production. Raw material dependencies draw from nickel-chromium and iron-chromium-aluminum alloy suppliers, high-grade magnesium oxide miners, and Incoloy sheath processors. Single-source vulnerability in specialized dielectric materials creates supply chain risk, as limited qualified suppliers of compaction-grade magnesium oxide concentrate technical capability. Distribution runs through equipment OEM integration partnerships for new chamber builds, with aftermarket service contracts increasingly bundling heater replacement and thermal calibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between South Korea's concentrated foundry demand and Germany's regulatory-driven premium alloy development, with REACH compliance costs in Europe creating sustainable margin premiums unavailable to Asian volume producers.
For Market Incumbents: To counter ceramic heater penetration in rapid thermal processing above 1,200°C, metal-sheathed specialists must accelerate R&D in advanced magnesium oxide compaction techniques and secure captive supply of high-purity insulation materials through backward integration into Japanese or European sources. Incumbents should also anchor long-term fab partnerships through preventive maintenance software platforms that embed thermal calibration services into multi-year contracts, displacing spot purchasing relationships. For New Entrants and Emerging Players: Launch via rapid-response custom fabrication services targeting legacy 200mm and mature 300mm fab retrofits, where chamber qualification timelines favor agile suppliers over integrated thermal giants. The most penetrable white-space sits in medical semiconductor applications requiring FDA device regulation compliance, where specialized heater material certification creates barriers that favor focused entrants over commodity players. A direct-to-fab technical sales model with embedded application engineering support accelerates adoption in this segment. For Investors and Strategic Acquirers: Consolidation pressure builds where high-purity magnesium oxide insulation sourcing concentrates among limited qualified suppliers, creating acquisition opportunities for heater manufacturers with backward integration capabilities or exclusive supplier relationships. Long-term viability over the next decade hinges on exposure to EUV lithography node transitions below 3nm and embedded service contract recurring revenue streams. The signal to watch as inflection indicator is bundled procurement adoption rates across South Korea's Pyeongtaek cluster, where foundry concentration accelerates contractual restructuring toward uptime guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesium Oxide Supply | Secures dielectric isolation performance for EUV-grade heater certification against REACH reformulation deadlines. |
| Preventive Maintenance Platform Launch | Repositions vendor relationships from equipment sales to recurring uptime guarantee contracts at Pyeongtaek foundries. |
| Medical Semiconductor Certification Pathway | Opens premium market tiers through FDA device regulation compliance for implantable chip applications. |
| Legacy Tool Retrofit Service Expansion | Captures extended lifecycle demand from mature 200mm fabs delaying full chamber replacement investments. |
| Advanced Alloy R&D Partnership | Accelerates REACH-compliant nickel-chromium formulation development with German precision engineering specialists. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with wafer fab thermal engineering directors, OEM procurement leads, heater manufacturer R&D heads, and magnesium oxide insulation suppliers with secondary validation through SEMI equipment market data, EPA emissions framework filings, ECHA REACH substance restriction updates, and customs trade records for nickel-chromium alloy imports. Bottom-up heater unit demand modeling and top-down semiconductor capital expenditure triangulation anchored market sizing across the analysis window.
Segment-weighting approaches distributed value and volume across product type, end user, installation modality, and power rating dimensions, with particular analytical attention to the ultra-high-power tier where specialized alloy capabilities limit supplier pools. CAGRs derived from equipment intensity ratios tied to EUV lithography node transition timelines and foundry capacity expansion announcements, incorporating thermal uniformity specification evolution from ISO and SEMI standards as demand elasticity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance restriction acceleration or magnesium oxide supply disruption scenarios. Periodic stress-testing of base assumptions is recommended, particularly regarding alloy input cost pass-through elasticity and bundled procurement contract penetration rates at concentrated manufacturing clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Nanowires Market