
 Temperature-Controlled Semiconductor Market | 2026-2036
Temperature-Controlled Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature-Controlled Semiconductor Market Analytics
Silicon carbide is rebalancing thermal interface material economics as device power densities climb in next-generation chips. Infineon Technologies AG leverages its vertical integration into SiC substrates to control cost curves for high-performance cooling assemblies. Texas Instruments Inc. anchors its position through precision temperature sensor portfolios that serve automotive and industrial automation customers. STMicroelectronics NV differentiates via system-level thermal management solutions that combine sensors with active control circuitry.
Temperature-controlled semiconductors encompass active and passive components engineered to monitor, dissipate, or generate thermal energy within electronic systems, typically operating across junction temperature ranges from -40°C to 175°C depending on application grade and material platform. These devices prevent thermal runaway, maintain signal integrity, and enable sustained computational throughput in power-dense architectures. Cooling Solutions command the largest revenue share as liquid and two-phase systems displace air cooling in data center and automotive power electronics deployments, while Thermoelectric Cooling segments expand fastest in medical devices and aerospace where solid-state reliability outweighs efficiency penalties. Sensors represent a concentrated margin pool where precision calibration and integration with control loops sustain pricing power.
The EPA regulates refrigerant emissions under Section 608 of the Clean Air Act, constraining coolant selection for active thermal systems deployed in US facilities. The EU F-Gas Regulation and REACH framework compound compliance complexity for suppliers serving European data center and automotive electronics OEMs. FDA thermal stability requirements for medical devices add a third regulatory vector that shapes product validation cycles. Stakeholders must weigh refrigerant transition timelines against thermoelectric technology maturation when allocating R&D across cooling architectures.
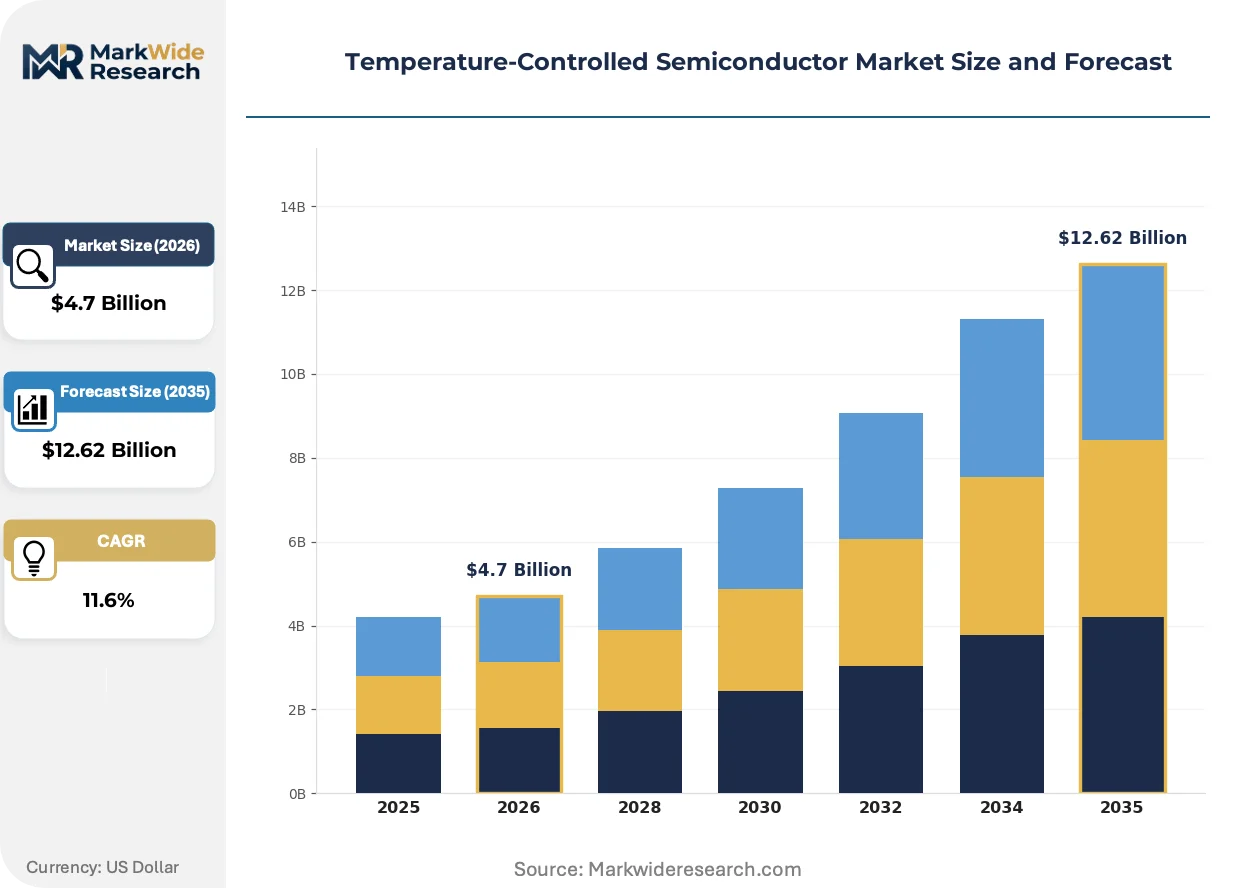
Market Dynamics
AI-driven power density escalation in data centers is forcing a wholesale architecture shift from air cooling to liquid and two-phase thermal systems, compressing deployment timelines and recalibrating supplier qualification criteria across the value chain.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating OEM investment in thermoelectric and natural refrigerant alternatives for European data center deployments.
- Silicon carbide substrate expansion:SiC power devices operating at higher junction temperatures are expanding the addressable market for advanced thermal interface materials in automotive traction inverters.
- Arizona-Texas fab concentration:Semiconductor manufacturing cluster buildouts in these states are generating localized demand spikes for precision cooling infrastructure and thermal sensing systems.
Market Restraints
- Indium price volatility:Thermoelectric cooler manufacturing depends on indium-tin solder and bismuth-telluride elements subject to supply constraints from Chinese rare earth processing.
- Refrigerant transition friction:The EPA Section 608 phasedown timeline creates inventory stranding risk for US-based cooling system OEMs with legacy R-134a and R-410A product lines.
- Metrology bottleneck:Precision temperature sensor calibration requires NIST-traceable standards with limited accredited laboratory capacity, extending validation cycles.
Strategic Opportunities
- Medical device thermal stability:FDA 21 CFR Part 820 quality system requirements for implantable electronics create premium pricing potential for validated solid-state cooling modules.
- Two-phase cooling convergence:Integration of pumped two-phase loops with embedded microchannel cold plates offers performance headroom for next-generation GPU clusters.
- Indian PLI scheme alignment:The country's production-linked incentive framework for semiconductor packaging is attracting thermal management component localization investments.
Industry Challenges
- Thermal-fluid engineering scarcity:Two-phase system design requires specialized expertise in nucleate boiling and flow instabilities that outpaces current university program output.
- Multi-regulatory certification stacking:Concurrent EPA refrigerant compliance, EU REACH substance restrictions, and FDA biocompatibility testing extends product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature-Controlled Semiconductor Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Management Systems, Cooling Solutions, Heating Solutions, Sensors Application: Data Centers, Automotive Electronics, Industrial Automation, Consumer Electronics Technology: Passive Cooling, Active Cooling, Thermoelectric Cooling, Phase Change Materials End User: Telecommunications, Aerospace, Medical Devices, Military |
| Companies Covered | Tempco Electric Heater Corporation, Backer AB, Thermocoax, Marumae Co., Ltd., NHK Spring Co., Ltd., Mecaro, Infineon Technologies AG, Texas Instruments Inc., STMicroelectronics NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature-Controlled Semiconductor Market Evolving Landscape
Active thermal management is migrating from discrete component protection toward system-level predictive control, with sensor fusion and edge-based thermal modeling compressing response latency in power-dense architectures.
Silicon carbide-based thermal interface materials are consolidating design authority in high-performance computing applications. Data center operators deploying NVIDIA and AMD accelerators are specifying SiC-enhanced greases and phase-change materials for junction-to-case thermal resistance below 0.1°C·cm²/W. This consolidation is compressing the market for legacy alumina-filled solutions and elevating material qualification thresholds for new supplier entry.
The EU F-Gas Regulation's 2030 phase-down targets for fluorinated gases are restructuring refrigerant selection across European cooling system supply chains. OEMs serving Frankfurt, Amsterdam, and Dublin data center markets are accelerating R-290 and R-744 system development to preempt compliance cliffs. Automotive electronics suppliers face parallel pressure as the same regulation constrains mobile air conditioning refrigerants in electric vehicle thermal loops.
Hyperscale procurement teams are unbundling thermal hardware from server OEM integrated contracts and establishing direct supplier relationships with cooling specialists. This disintermediation is visible in Microsoft and Amazon's direct qualification programs for liquid cooling manifolds and cold plate assemblies, bypassing traditional server vendor markups. The shift concentrates volume with specialized thermal engineering firms and compresses margins for generalist contract manufacturers.
Temperature-Controlled Semiconductor Market Segmentation
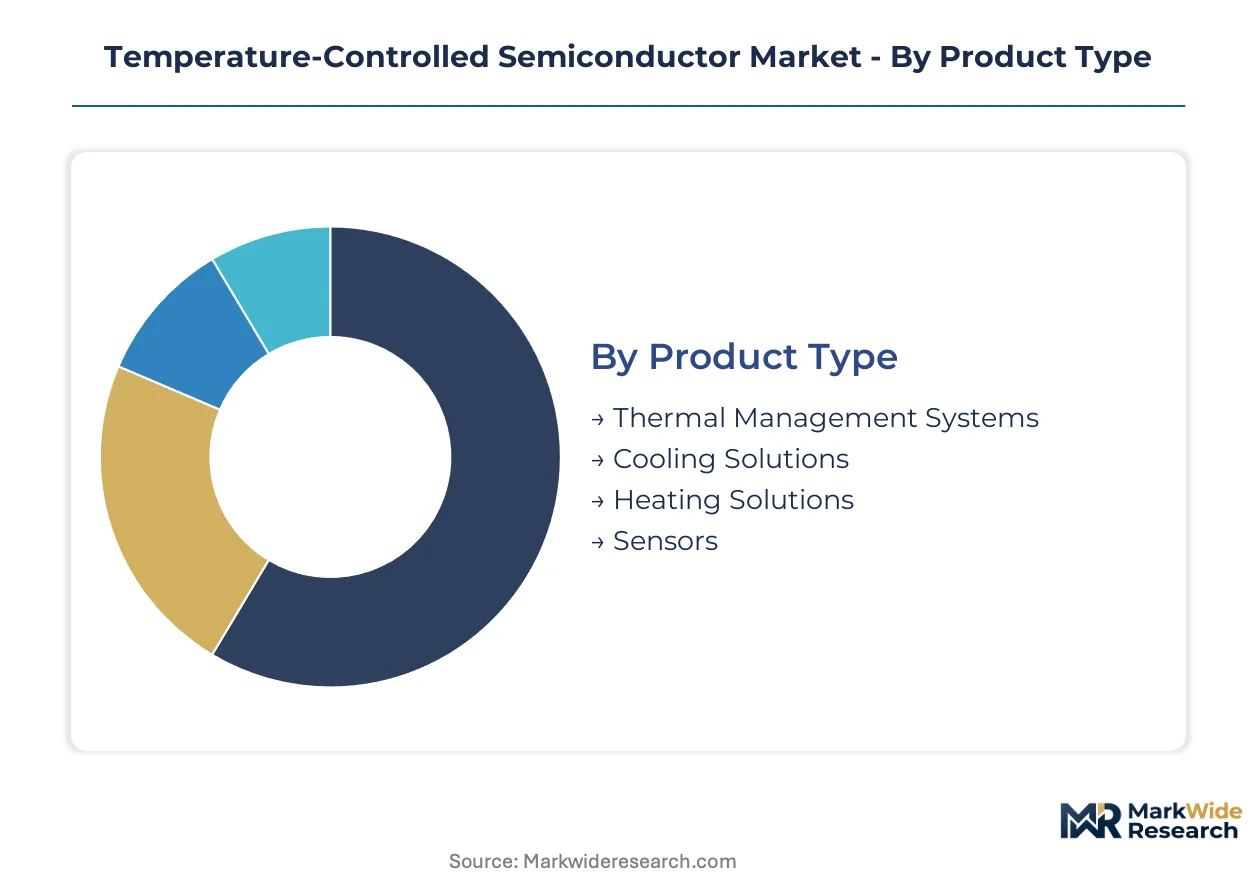
Temperature-controlled semiconductor procurement diverges sharply by thermal load density and regulatory exposure. Buyers prioritize liquid-based architectures for AI infrastructure while solid-state solutions dominate implantable medical applications where refrigerant compliance is prohibitive.
Product Type:
Cost tier separates buyers seeking capital-intensive liquid cooling infrastructure from those purchasing discrete sensor components for monitoring applications.
- Cooling Solutions:Liquid and two-phase systems incorporating cold plates, manifolds, and pump assemblies designed for junction-to-ambient thermal resistance below 0.3°C·cm²/W. Demand concentrates in Arizona and Texas data center clusters where NVIDIA GPU deployments are forcing displacement of legacy air-cooled architectures under EPA Section 608 refrigerant constraints.
- Sensors:Precision thermocouples, RTDs, and integrated CMOS temperature monitors with NIST-traceable calibration for ±0.1°C accuracy. Automotive electronics OEMs in Germany and Japan anchor procurement volumes as SiC traction inverters require multi-point junction monitoring for thermal runaway prevention.
- Thermal Management Systems:Integrated controller-sensor-actuator loops with predictive algorithms.
- Heating Solutions:Thin-film heaters and ceramic elements for cold-start thermal conditioning.
Cooling Solutions leads volumes today; Sensors is gaining share fastest.
Application:
Volume concentration tracks power density escalation, with AI training clusters consuming thermal hardware at 5-10x the rate of conventional server farms.
- Data Centers:Hyperscale facilities deploying direct-to-chip liquid cooling for GPU accelerators operating above 700W TDP. Frankfurt and Amsterdam operators are accelerating R-290 and R-744 system adoption to preempt EU F-Gas Regulation phase-down cliffs.
- Automotive Electronics:Traction inverters, onboard chargers, and battery management systems requiring -40°C to 150°C operational range. Infineon's vertical integration into SiC substrates is compressing thermal interface material costs for 800V architectures.
- Industrial Automation:Motor drives and power supplies with moderate thermal loads.
- Consumer Electronics:Smartphones and laptops with vapor chamber and graphite sheet solutions.
Data Centers commands the largest revenue pool; Automotive Electronics shows the steepest expansion trajectory.
Technology:
Maturity curves separate established air-cooled methods from emerging solid-state and phase-change approaches facing qualification bottlenecks.
- Active Cooling:Pumped liquid loops and vapor compression systems with coefficient of performance above 3.0. Medical device manufacturers in Switzerland and the United States specify solid-state alternatives to avoid FDA validation complexity from refrigerant-based systems.
- Thermoelectric Cooling:Peltier modules using bismuth-telluride elements for precise temperature stabilization without moving parts. Aerospace and satellite applications in the United States and France absorb premium pricing for vibration-free reliability despite 5-10% Carnot efficiency limits.
- Passive Cooling:Heat sinks, heat pipes, and thermal interface materials.
- Phase Change Materials:Paraffin and salt hydrate compounds for transient thermal buffering.
Active Cooling dominates installed base; Thermoelectric Cooling is climbing the fastest as refrigerant regulations tighten.
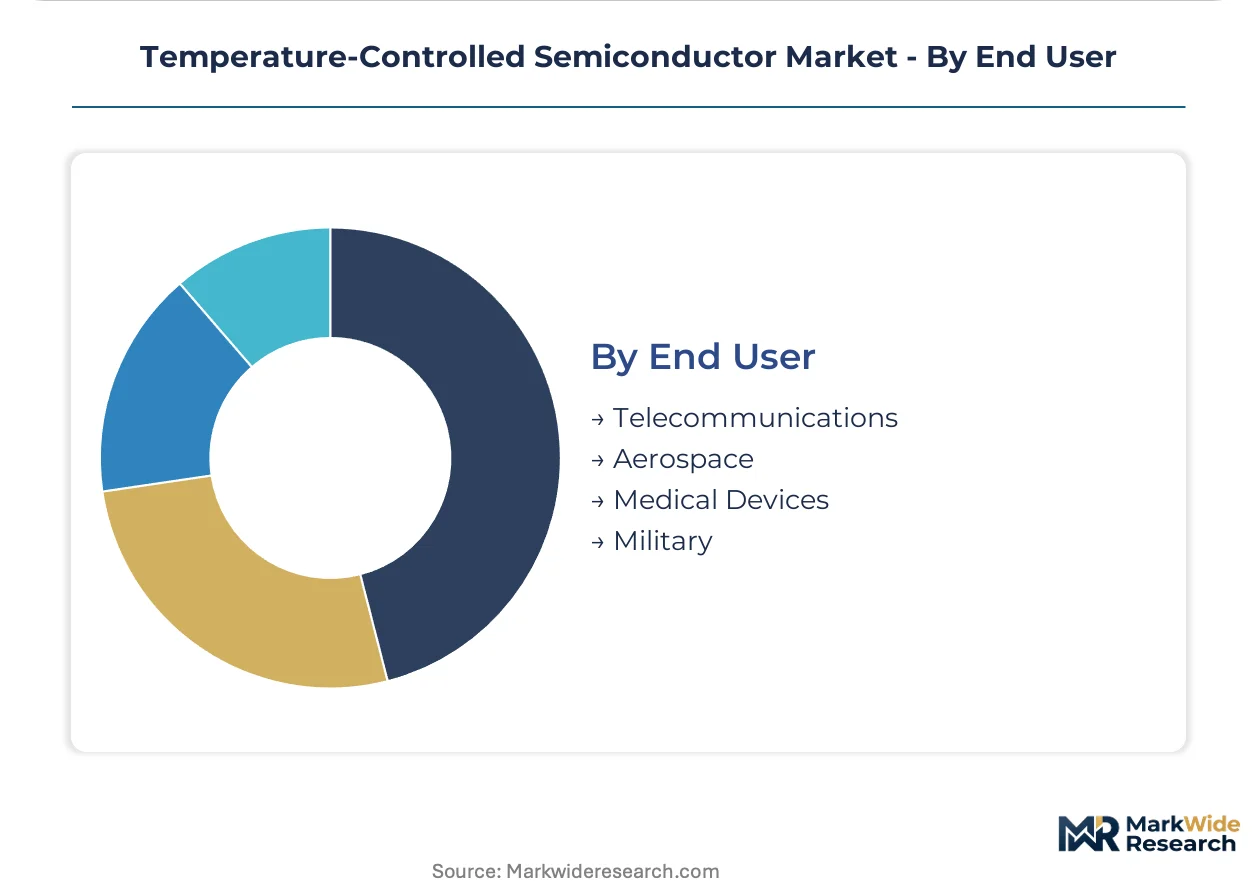
End User:
Margin structure separates price-sensitive telecommunications procurement from premium-validated aerospace and medical segments.
- Medical Devices:Implantable pacemakers, insulin pumps, and diagnostic equipment requiring ISO 13485 thermal stability validation. FDA 21 CFR Part 820 quality system requirements sustain 40-60% gross margins for qualified solid-state cooling module suppliers.
- Aerospace:Avionics and satellite payloads demanding MIL-STD-883 thermal cycling survival. European Space Agency and NASA qualification protocols extend development cycles but lock in decade-long supplier relationships.
- Telecommunications:Base station power amplifiers and optical transceivers.
- Military:Ruggedized electronics with extended temperature range requirements.
Telecommunications leads unit volumes; Medical Devices captures the highest margin pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arizona and Texas semiconductor fabrication clusters are driving concentrated demand for precision cooling infrastructure as AI workload densities escalate thermal management requirements across multiple geographies.
United States
Data center operators in Phoenix and Austin are deploying direct-to-chip liquid cooling for NVIDIA GPU accelerators exceeding 700W TDP. EPA Section 608 refrigerant phasedown timelines are accelerating R-290 and R-744 system adoption. Arizona's Fab 52 and Fab 62 expansions by Taiwan Semiconductor Manufacturing Company are generating localized procurement spikes for thermal sensing systems.
Germany
Automotive electronics OEMs in Stuttgart and Munich require precision temperature monitoring for 800V SiC traction inverters. EU F-Gas Regulation phase-down targets are restructuring refrigerant selection across cooling system supply chains. Frankfurt data center operators are accelerating natural refrigerant alternatives to preempt 2030 compliance cliffs.
China
Hyperscale facilities in Beijing and Shanghai are expanding liquid cooling deployments for domestic AI training clusters. MIIT energy efficiency standards are constraining PUE targets below 1.3 for new data center construction. Yangtze River Delta semiconductor packaging hubs are localizing thermal interface material production under national dual carbon goals.
Japan
Automotive and industrial automation OEMs in Nagoya and Osaka anchor procurement volumes for precision thermocouples and RTDs. METI semiconductor industry revitalization programs are subsidizing advanced packaging investments with integrated thermal management. Kyushu silicon foundry expansions are driving demand for multi-point junction monitoring systems.
India
Production-linked incentive schemes for semiconductor packaging are attracting thermal management component localization investments in Gujarat and Karnataka. BIS certification requirements for electronic cooling equipment are extending product validation timelines. Tamil Nadu electronics manufacturing clusters are emerging as assembly hubs for thermoelectric cooling modules serving medical device exporters.
Temperature-Controlled Semiconductor Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers race to meet compressed deployment timelines for AI data center thermal infrastructure. The vendor base stratifies across three tiers: integrated semiconductor manufacturers with captive thermal sensing portfolios, specialized cooling system OEMs with liquid loop expertise, and component suppliers focused on discrete sensors or interface materials. Two competitive moves define current positioning: strategic partnerships between cooling specialists and server OEMs to bypass traditional distribution channels, and backward integration into silicon carbide substrates to control cost curves for high-performance assemblies.
Among diversified semiconductor manufacturers, Infineon Technologies AG and Texas Instruments Inc. exemplify the integrated tier, leveraging precision sensor portfolios and substrate control to anchor positions in automotive and industrial automation segments. STMicroelectronics NV occupies a position within the system-level solutions archetype, combining sensing with active control circuitry. Specialized thermal engineering firms including Tempco Electric Heater Corporation and Backer AB represent the component-focused tier, serving industrial and medical applications where validated solid-state reliability commands premium positioning.
| Leading Market Players |
|---|
| Tempco Electric Heater Corporation |
| Backer AB |
| Thermocoax |
| Marumae Co., Ltd. |
| NHK Spring Co., Ltd. |
| Mecaro |
| Infineon Technologies AG |
| Texas Instruments Inc. |
| STMicroelectronics NV |
| Others |
Value Network & Pricing Analysis
Hyperscale data center operators in the United States are unbundling thermal hardware from server OEM integrated contracts and establishing direct supplier relationships with cooling specialists, forcing component manufacturers to absorb qualification costs and compress lead times while defending margin positions through certification tiering.
Pricing Analysis
Input-cost pass-through from indium-tin solder and bismuth-telluride elements drives pricing volatility in thermoelectric cooler manufacturing, with Chinese rare earth processing constraints amplifying material cost swings. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical device modules from industrial-grade sensors and commodity thermal interface materials. Pricing pressure stems from hyperscale procurement teams consolidating volume with direct cooling specialists, bypassing traditional distribution markups. Automotive electronics OEMs show lowest price sensitivity due to thermal runaway liability exposure, while telecommunications base station operators prioritize cost-per-unit minimization.
Supply Chain Analysis
NIST-traceable calibration requirements and FDA 21 CFR Part 820 quality system validation gate supplier entry, extending product launch timelines and concentrating qualified capacity with incumbent specialists. Manufacturing concentrates in Taiwan for precision sensors, Germany for automotive-grade thermal management systems, and China for commodity cooling components. Raw material flows draw from Australian rare earth processing for bismuth-telluride elements, Japanese ceramic substrates for thermoelectric modules, and South Korean silicon carbide wafers for high-performance interface materials. Single-source vulnerability sits with Chinese indium refining capacity. Distribution runs through specialized thermal engineering firms serving medical and aerospace verticals, with direct OEM relationships displacing traditional electronics distributors in data center segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where AI workload density escalation and refrigerant phase-down mandates are concentrating procurement with validated suppliers capable of multi-regulatory certification stacking.
For Market Incumbents: Deepen backward integration into silicon carbide substrates to control cost curves for 800V automotive traction inverters, while expanding NIST-accredited calibration laboratory capacity to capture precision sensor demand from Arizona and Texas fab clusters. Defend against hyperscale disintermediation by embedding predictive thermal control algorithms that raise switching costs for data center operators. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and the Netherlands opens a window for R-290 and R-744 natural refrigerant system development, targeting Frankfurt and Amsterdam data center operators facing 2030 compliance cliffs. Focus initial penetration on thermoelectric cooling modules for Swiss and United States medical device manufacturers where FDA validation complexity deters incumbent expansion. Pursue qualification partnerships with specialized thermal engineering firms to bypass direct OEM certification bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive silicon carbide substrate production and established FDA quality system registrations. Long-term viability hinges on positioning for sustained AI infrastructure buildout cycles and automotive electrification transitions across the analysis window. Monitor hyperscale direct procurement program announcements as inflection indicators for cooling specialist valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Infineon's captive wafer production compresses thermal interface material costs for 800V architectures. |
| NIST Calibration Laboratory Expansion | Texas Instruments' precision sensor portfolios leverage accredited metrology capacity to sustain automotive pricing power. |
| Natural Refrigerant System Development | European OEMs accelerate R-290 and R-744 platforms to preempt EU F-Gas Regulation phase-down cliffs. |
| Direct Hyperscale Qualification Programs | Microsoft and Amazon bypass server vendor markups by establishing direct relationships with liquid cooling specialists. |
| Medical Device Thermal Module Validation | FDA 21 CFR Part 820 compliance sustains 40-60% gross margins for qualified solid-state cooling suppliers. |
Research Methodology
Direct dialogue with data center procurement directors, automotive thermal management engineers, medical device quality assurance leads, and semiconductor packaging specialists grounded qualitative findings in operational reality. Secondary validation drew from EPA Section 608 enforcement records, EU F-Gas Regulation implementation timelines, FDA 510(k) thermal device submissions, and hyperscaler capex disclosure filings. Bottom-up and top-down triangulation cross-checked component-level shipment estimates against facility-level cooling infrastructure deployment data.
Bottom-up modeling aggregated unit economics across cooling solutions, sensors, thermoelectric modules, and thermal interface materials by application segment and technology platform. Top-down verification anchored aggregate market size against semiconductor fabrication capacity expansion schedules in Arizona, Texas, Germany, and Japan. Segmentation dimensions included product type, application vertical, cooling technology maturity, and end-user regulatory exposure. CAGRs were derived from regression analysis of historical procurement patterns against AI workload density trajectories and automotive SiC adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU refrigerant phase-down timelines or extended NIST laboratory accreditation backlogs. Model assumptions reflect concurrent EPA, REACH, and FDA compliance stacking burdens that extend product validation cycles. A model refresh is warranted upon material change in hyperscale direct procurement penetration rates or indium supply disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Global Bipolar Power Transistor Market