
 Nano-Magnetic Devices Market | 2026-2036
Nano-Magnetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nano-Magnetic Devices Market Outlook
Buyer concentration among hyperscale data center operators is pivoting toward edge computing deployments, fragmenting demand across regional cloud providers and autonomous vehicle developers. Samsung Electronics leverages its captive semiconductor fabrication capacity to anchor supply for MRAM foundry services. Intel Corporation competes through in-house development of spintronic logic devices aimed at beyond-CMOS computing architectures. Everspin Technologies specializes in discrete MRAM components for industrial automation and aerospace systems.
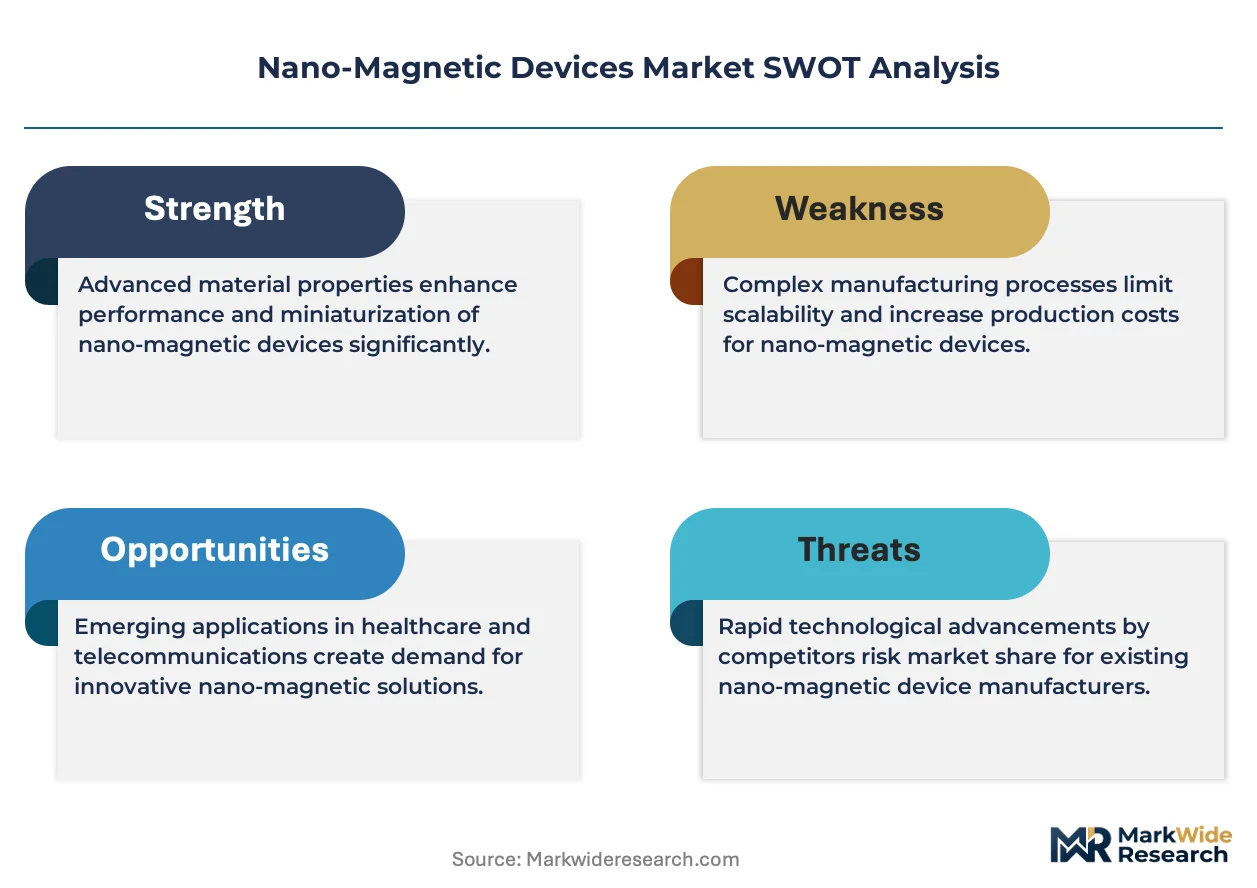
Nano-magnetic devices exploit spin-dependent transport phenomena in thin-film heterostructures typically 1-100 nanometers thick, enabling non-volatile data retention with switching energies below one picojoule per bit. These devices serve as the functional core of next-generation memory, sensing, and quantum information systems. MRAM product categories command premium positioning due to endurance advantages over flash memory in write-intensive workloads. Magnetic sensors within the application dimension are capturing expanding share in automotive torque sensing and current monitoring, while spintronics technology leads R&D investment intensity across patent filings and foundry partnerships.
The EPA governs hazardous material handling in U.S. magnetic thin-film manufacturing facilities, while REACH restricts certain precursor chemicals used in EU-based deposition processes. Japan's METI coordinates national research consortia advancing perpendicular magnetic recording and domain-wall logic devices. Stakeholders must monitor evolving export control classifications for advanced magnetometer technologies and pre-position compliance documentation for dual-use licensing regimes.
Market Dynamics
Electric vehicle powertrain electrification is compressing sensor procurement cycles while REACH and F-Gas Regulation compliance costs are redistributing manufacturing capacity across deposition equipment suppliers.
Growth Catalysts
- Automotive torque sensing:Tier-1 suppliers in Germany's Stuttgart corridor are qualifying magnetoresistive arrays for 800-volt inverter monitoring in next-generation EV platforms.
- REACH precursor restrictions:ECHA's tightening chemical authorization lists are accelerating substitution toward atomic layer deposition precursors with lower fluorinated gas footprints.
- Perpendicular magnetic recording:Japan's METI-funded consortia are transferring domain-wall logic intellectual property into foundry-compatible process flows.
Market Restraints
- Deposition equipment concentration:Sputtering system supply concentrates among Japanese and German capital equipment vendors, creating 18-24 month order backlogs for multi-chamber cluster tools.
- Precursor cost volatility:Cobalt and platinum group metal prices for magnetic thin-film stacks fluctuate with South African mining output and Russian export flows.
- Flash memory endurance gap closure:3D NAND triple-level cell architectures are narrowing the write-cycle advantage that MRAM historically held in industrial logging applications.
Strategic Opportunities
- Edge computing sensor fusion:Autonomous vehicle developers in California and Bavaria are specifying combined magnetometer-inertial measurement units for redundant navigation in GPS-denied environments.
- EU Green Deal funding:Horizon Europe clusters are earmarking support for rare-earth-free magnetic material development to decouple supply chains from Chinese heavy rare earth processing.
- Quantum sensing interfaces:Nitrogen-vacancy center magnetometers are integrating with cryogenic control electronics for chip-scale atomic clock and biomedical imaging platforms.
Industry Challenges
- Spintronics fabrication talent:Foundries report acute shortages of process engineers with combined magnetism and CMOS integration expertise, particularly for magnetic tunnel junction etch and anneal sequences.
- Dual-use export licensing:Advanced magnetometer technologies face evolving Commerce Control List classifications, requiring pre-positioned technical data packages for Bureau of Industry and Security reviews.
- Legacy semiconductor integration:MRAM back-end-of-line thermal budgets must reconcile with copper/low-k interconnect fragility in mature node fabs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano-Magnetic Devices Market |
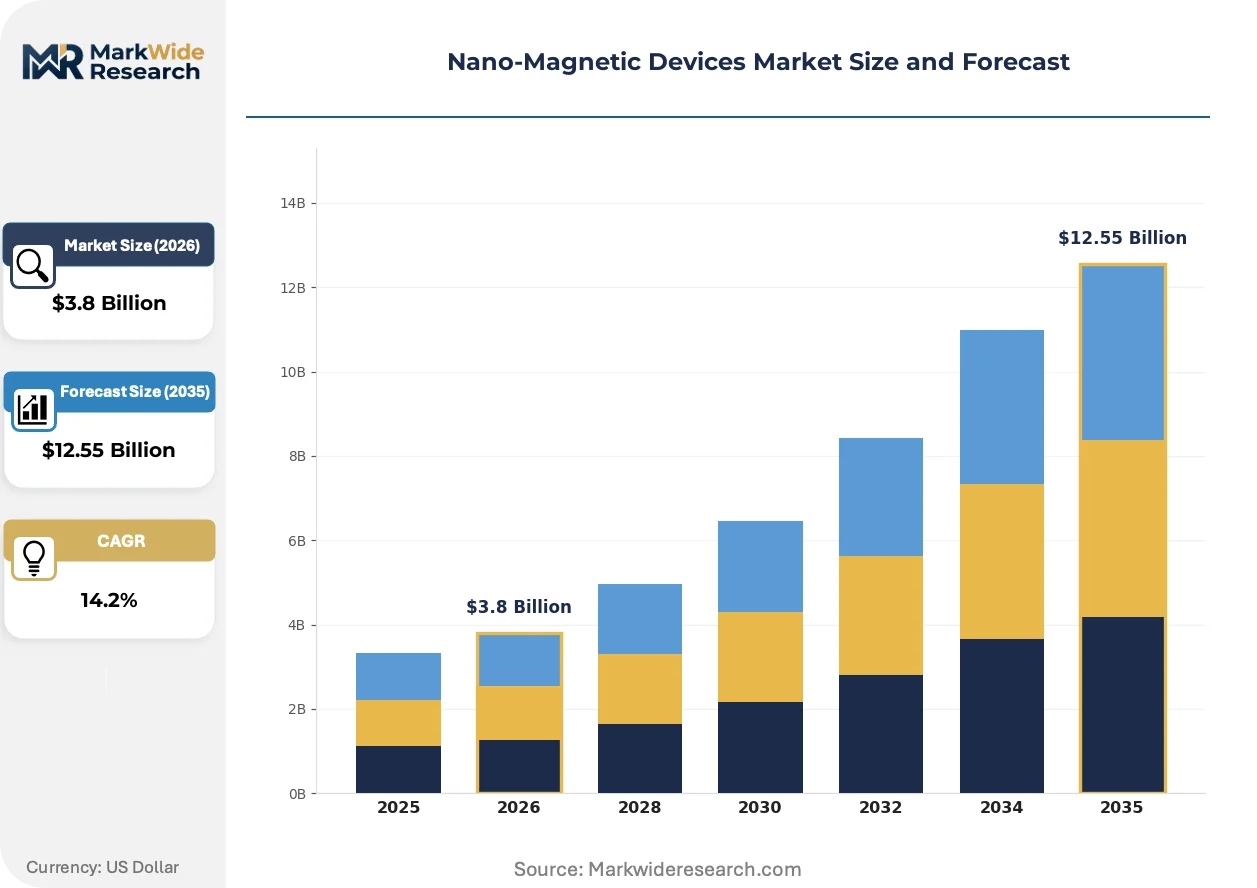
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drives, MRAM, Magnetic Sensors, Recording Heads Application: Data Storage, Medical Imaging, Automotive Sensors, Consumer Electronics End User: Healthcare, Telecommunications, Automotive, Industrial Automation Technology: Spintronics, Magnetic Particle Imaging, Quantum Dots, Molecular Magnets |
| Companies Covered | IBM Corporation, Samsung Electronics, Intel Corporation, Fujitsu Limited, Everspin Technologies, Honeywell International Inc., Hitachi Metals Ltd., LG Electronics Inc., Nanomagnetics Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano-Magnetic Devices Market Strategic Shifts
Spintronic device architectures are converging with advanced packaging technologies while regulatory chemical restrictions are forcing material substitutions across the deposition supply chain.
Magnetic tunnel junctions with perpendicular magnetic anisotropy are integrating into 22nm and below logic-compatible embedded memory macros. Automotive MCU suppliers in Germany and Japan are qualifying these arrays for ASIL-D safety-critical storage at 150°C junction temperatures. This integration is compressing the traditional separation between volatile SRAM and non-volatile flash in powertrain control modules.
ECHA's F-Gas Regulation is phasing down hydrofluorocarbon etching chemistries used in magnetic thin-film patterning. EU-based foundries are retrofitting abatement systems or qualifying fluorine-free plasma chemistries for hard mask removal. MRAM-specific process flows face disproportionate impact due to their reliance on noble metal hard masks and reactive ion etch selectivity requirements.
Hyperscale data center operators are fragmenting procurement across regional cloud providers and specialized edge infrastructure vendors. Tier-2 buyers in Singapore, Ireland, and Virginia are demanding MRAM-based persistent memory for write-heavy caching layers previously served by Intel Optane. This rotation is compressing volume commitments and fragmenting SKU requirements across temperature grade and endurance specifications.
Nano-Magnetic Devices Market Segmentation
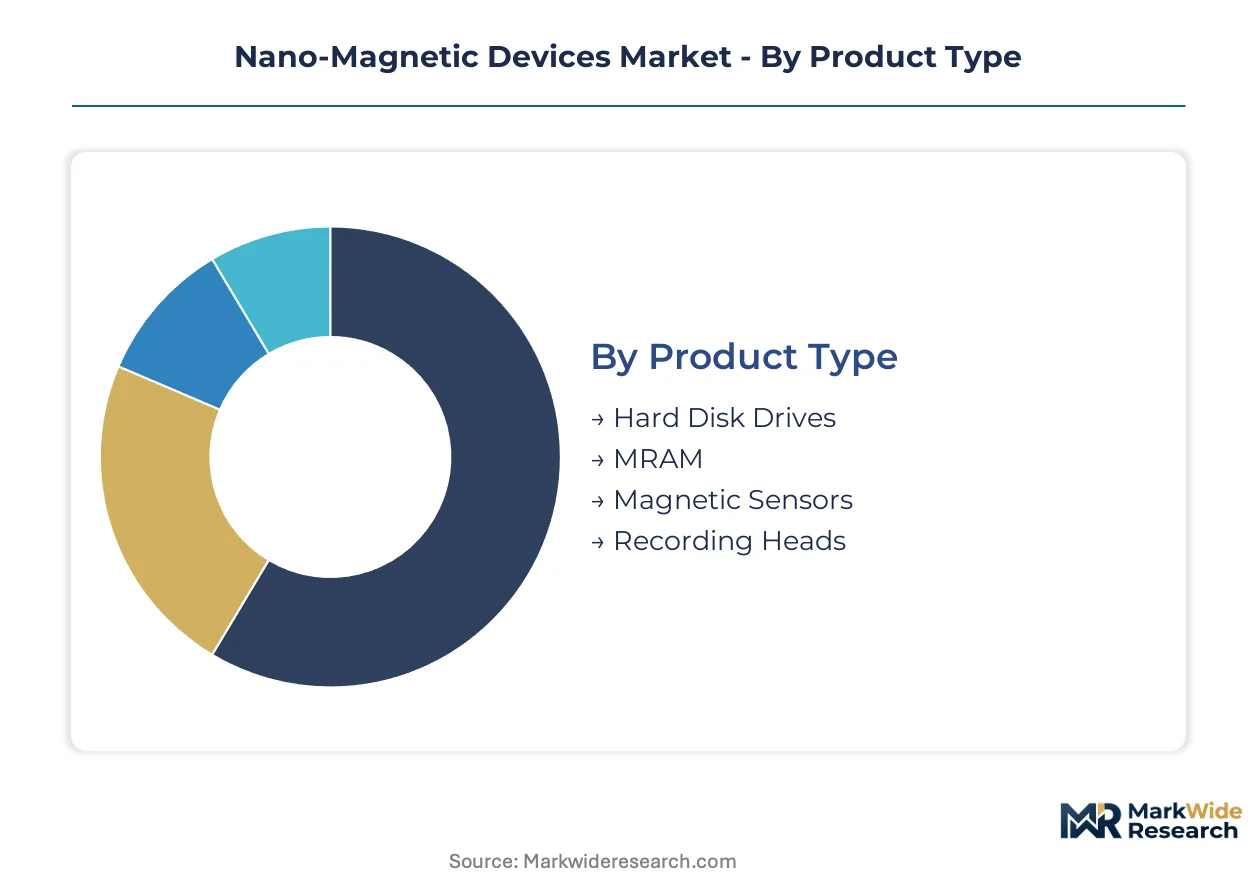
Nano-magnetic devices fragment across multiple technical axes, with product architecture and deposition chemistry determining foundry compatibility. Buyers navigate trade-offs between endurance, switching energy, and thermal budget that reshape procurement patterns across automotive, data center, and medical verticals.
Product Type:
Deposition equipment for magnetic thin-film stacks concentrates among Japanese and German capital equipment vendors, creating order backlogs that favor segments with standardized process flows.
- MRAM:Magnetic tunnel junctions with perpendicular magnetic anisotropy enable sub-picojoule switching at 22nm logic compatibility. Tier-1 automotive MCU suppliers in Germany and Japan are qualifying embedded macros for ASIL-D safety-critical storage at elevated junction temperatures. MRAM absorbs the bulk of installed capacity; Magnetic Sensors are expanding most quickly.
- Magnetic Sensors:Magnetoresistive arrays exploit spin-dependent transport for torque sensing and current monitoring in 800-volt EV inverters. Procurement cycles are compressing as Stuttgart-based Tier-1 suppliers qualify parts for next-generation powertrain platforms.
- Hard Disk Drives:Perpendicular magnetic recording heads remain essential for cold storage tiering despite NAND flash displacement of performance workloads.
- Recording Heads:Domain-wall logic intellectual property from METI-funded consortia is transferring into foundry-compatible process flows for advanced areal density targets.
MRAM captures premium positioning through endurance advantages in write-intensive workloads; Magnetic Sensors are climbing the fastest on electrification-driven demand.
Application:
Cost tier differentiation separates qualification-intensive automotive deployments from high-volume consumer electronics sourcing.
- Automotive Sensors:Redundant magnetometer-inertial measurement units address GPS-denied navigation for autonomous vehicle developers in California and Bavaria. ASIL-D certification requirements extend qualification timelines but lock in multi-year supply agreements.
- Data Storage:Hyperscale operators are fragmenting procurement across regional cloud providers in Singapore, Ireland, and Virginia for MRAM-based persistent memory layers. Tier-2 buyers are displacing Intel Optane with write-heavy caching configurations.
- Medical Imaging:Nitrogen-vacancy center magnetometers integrate with cryogenic control electronics for chip-scale atomic clock and biomedical imaging platforms.
- Consumer Electronics:Price-sensitive sourcing favors mature-node embedded flash alternatives where MRAM thermal budget constraints create integration challenges.
Automotive Sensors command the highest qualification barriers; Data Storage is gaining share fastest on edge computing fragmentation.
End User:
Customer type concentration varies sharply, with automotive and industrial automation demanding captive foundry relationships while healthcare tolerates merchant supply.
- Automotive:Powertrain electrification is compressing sensor procurement cycles for 800-volt inverter monitoring and torque sensing arrays. ECHA REACH compliance is redistributing manufacturing capacity toward atomic layer deposition precursors with lower fluorinated gas footprints.
- Industrial Automation:Discrete MRAM components serve write-intensive logging applications where 3D NAND endurance gaps are narrowing competitive positioning.
- Healthcare:Magnetic particle imaging systems require specialized gradient coils and shielding that limit supplier pool concentration.
- Telecommunications:Edge infrastructure vendors are specifying combined sensor fusion for redundant navigation in GPS-denied environments.
Automotive dominates volume commitments; Industrial Automation is expanding most quickly on factory automation sensor densification.
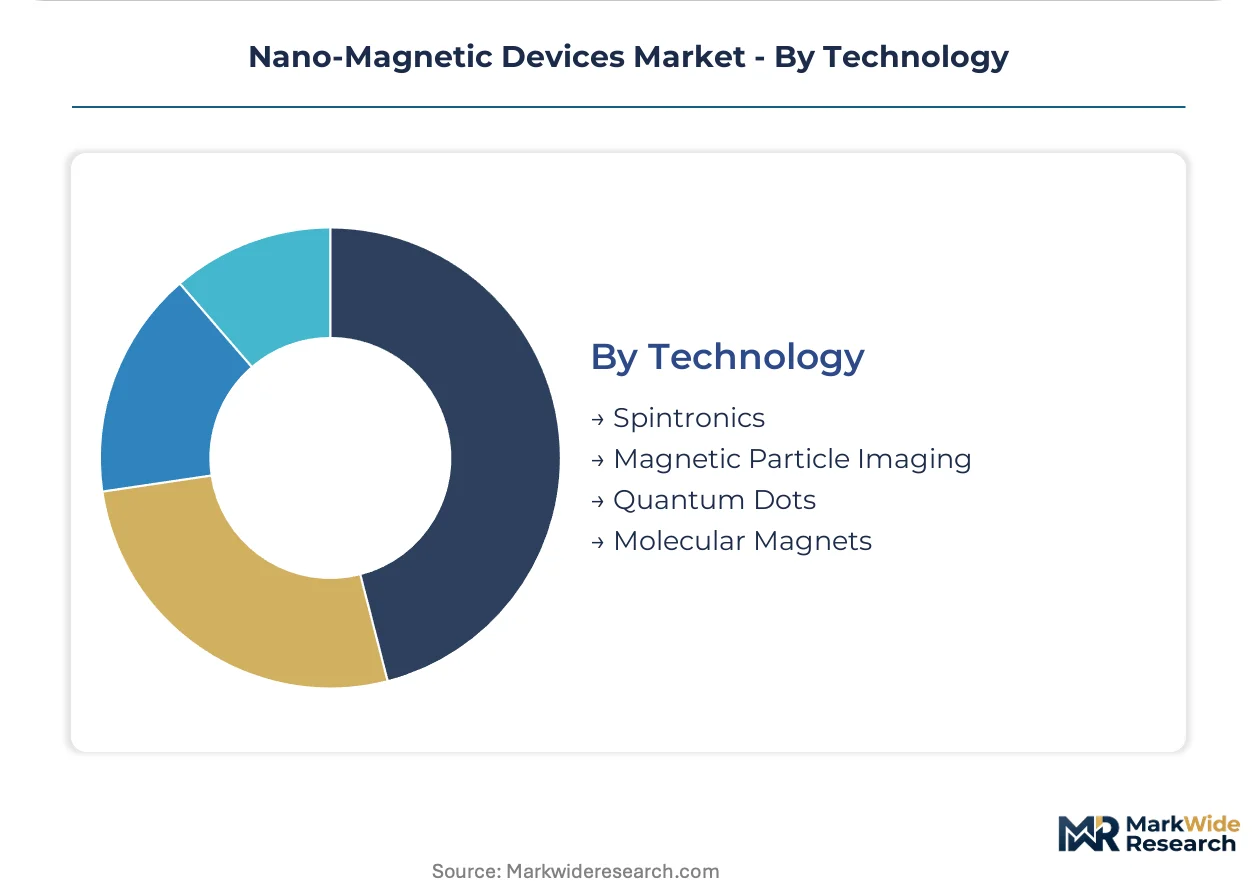
Technology:
Maturity gradients separate commercialized spintronic devices from quantum sensing platforms still in consortium-funded development.
- Spintronics:Magnetic tunnel junction etch and anneal sequences require process engineers with combined magnetism and CMOS integration expertise that foundries report in acute shortage. R&D investment intensity leads patent filings and foundry partnerships across the technology landscape.
- Magnetic Particle Imaging:Tracer-based imaging systems exploit superparamagnetic iron oxide nanoparticles for quantitative functional imaging with no ionizing radiation.
- Quantum Dots:Nitrogen-vacancy center magnetometers are integrating with cryogenic control electronics for chip-scale atomic clock platforms.
- Molecular Magnets:Single-molecule magnet research remains confined to academic and national laboratory consortia with limited foundry transfer pathways.
Spintronics anchors commercial revenue; Quantum Dots are advancing fastest on quantum sensing interface development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in precision engineering corridors where automotive electrification and semiconductor foundry expansion intersect. Germany's Stuttgart-Dresden axis and East Asian fabrication clusters absorb the majority of magnetoresistive sensor procurement. Regulatory chemical restrictions in the European Union and Japan are redistributing deposition capacity toward compliant precursor supply chains.
United States
Autonomous vehicle developers in California specify redundant magnetometer-inertial measurement units for GPS-denied navigation. The EPA governs hazardous material handling in magnetic thin-film manufacturing facilities. Greater Boston hosts quantum sensing research consortia advancing nitrogen-vacancy center magnetometer integration.
Germany
Tier-1 suppliers in Stuttgart qualify magnetoresistive arrays for 800-volt EV inverter monitoring. ECHA's REACH restrictions tighten precursor authorization lists for magnetic thin-film deposition. The precision engineering corridor around Dresden concentrates MRAM foundry qualification activity for automotive ASIL-D applications.
Japan
METI coordinates national research consortia transferring domain-wall logic intellectual property into foundry-compatible process flows. JIS standards govern magnetic recording head specifications for perpendicular magnetic recording architectures. Tokyo-Osaka industrial zones concentrate sputtering equipment manufacturing and magnetic tunnel junction process development.
South Korea
Samsung Electronics leverages captive semiconductor fabrication capacity to anchor MRAM foundry service supply. MFDS oversight applies to medical device components incorporating magnetic nanoparticle imaging systems. Seoul-based capital equipment vendors report 18-24 month order backlogs for multi-chamber cluster deposition tools.
China
Semiconductor foundries in the Yangtze River Delta expand orders for magnetoresistive sensors serving domestic EV powertrain platforms. MIIT coordinates national standards for magnetic thin-film deposition equipment under dual carbon goals. Shanghai's Pudong district concentrates atomic layer deposition precursor development for rare-earth-free magnetic materials.
Nano-Magnetic Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue quantum sensing interfaces and edge computing sensor fusion. The vendor base stratifies across captive foundry operators, discrete component specialists, and capital equipment suppliers. Three archetypes dominate: integrated semiconductor conglomerates with captive MRAM capacity, pure-play magnetic sensor designers serving automotive qualification pipelines, and deposition equipment manufacturers controlling sputtering system supply. Capacity expansion and strategic foundry partnerships constitute the primary competitive vectors as procurement fragments across regional cloud providers.
Within the integrated conglomerate tier, Samsung Electronics exemplifies captive fabrication dominance through in-house MRAM foundry services. Intel Corporation occupies a position in spintronic logic development for beyond-CMOS computing architectures. Everspin Technologies represents the pure-play discrete component archetype, anchoring supply for industrial automation and aerospace MRAM applications. These three entities collectively illustrate the competitive tension between vertical integration and specialized component supply.
| Leading Market Players |
|---|
| IBM Corporation |
| Samsung Electronics |
| Intel Corporation |
| Fujitsu Limited |
| Everspin Technologies |
| Honeywell International Inc. |
| Hitachi Metals Ltd. |
| LG Electronics Inc. |
| Nanomagnetics Instruments |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed semiconductor foundries in East Asia anchor supply discipline for nano-magnetic devices, translating captive fabrication capacity into pricing power over merchant MRAM procurement. Family-owned German capital equipment specialists control sputtering system supply, creating 18-24 month order backlogs that insulate pricing from spot-market volatility.
Pricing Analysis
High-volume automotive sensor contracts trade margin for multi-year lock-in, while low-volume quantum sensing components capture premium positioning. Three-tier pricing structure across ASIL-D certified, industrial-grade, and consumer-tier separates procurement by qualification intensity. Cost compression in consumer electronics MRAM is intensifying because 3D NAND endurance improvements narrow the write-cycle advantage. Tier-1 automotive suppliers in Germany exhibit lowest price sensitivity due to safety-critical certification requirements.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Yokohama consolidate precursor chemicals and deposition equipment before final-mile delivery to foundries. Sputtering system manufacturing concentrates in Japan and Germany, while magnetic thin-film precursor synthesis feeds from South Korean and Chinese chemical complexes. Raw material dependencies rest on South African platinum group metals and Chinese heavy rare earth processing. Single-source vulnerability in multi-chamber cluster tool supply creates procurement bottlenecks. Distribution runs through direct foundry relationships rather than merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around captive fabrication capacity as REACH compliance costs and deposition equipment backlogs force smaller merchant players toward exit or acquisition.
For Market Incumbents: Cement foundry partnerships with automotive MCU suppliers in Germany and Japan through ASIL-D certification co-development. Acquire atomic layer deposition precursor specialists in South Korea to secure fluorine-free chemistry supply ahead of ECHA phase-down deadlines. Flash memory endurance improvements and cobalt price volatility represent dual threats to merchant MRAM positioning. For New Entrants and Emerging Players: Capture edge computing sensor fusion demand from autonomous vehicle developers in California and Bavaria before hyperscale procurement fragments further. Nitrogen-vacancy center magnetometers for quantum sensing interfaces offer the most penetrable white space. Partner with cryogenic control electronics specialists to bypass foundry capacity constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play magnetic sensor designers with existing Tier-1 automotive qualification in Germany's Stuttgart corridor. Long-term viability hinges on rare-earth-free magnetic material IP and domain-wall logic patent estates. Watch for Commerce Control List reclassification of advanced magnetometer technologies as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Expansion | Samsung Electronics anchors MRAM supply through captive semiconductor fabrication capacity in South Korea. |
| ASIL-D Certification Investment | Tier-1 automotive suppliers in Stuttgart qualify embedded memory macros for 800-volt EV platforms. |
| Fluorine-Free Chemistry Transition | ECHA's F-Gas Regulation phases down hydrofluorocarbon etching chemistries for EU-based foundries. |
| Quantum Sensing Interface Development | Nitrogen-vacancy center magnetometers integrate with cryogenic control electronics for biomedical imaging. |
| Rare-Earth-Free Material R&D | Horizon Europe clusters fund magnetic material development to decouple from Chinese processing. |
Study Parameters
Document review covered SEC 10-K filings, ECHA chemical authorization databases, and METI research consortium disclosures, complemented by interviews with semiconductor foundry process engineers, Tier-1 automotive supplier procurement directors, and deposition equipment sales executives. Secondary validation drew from patent filing analysis, customs trade data for magnetic thin-film precursors, and hyperscaler capex disclosures. Bottom-up unit demand estimates and top-down market sizing triangulated across primary and secondary sources.
Segment-level outputs across product type, application, end user, and technology dimensions fed into analytical framework spanning the projection horizon. CAGRs derived from regression against historical foundry capacity expansion, automotive electrification penetration curves, and regulatory compliance cost trajectories. Key inputs included magnetic tunnel junction wafer start data, sputtering equipment order backlogs, and ECHA REACH authorization timelines.
The model holds under stable regulatory enforcement and continued automotive electrification investment; deviation in export control classifications or platinum group metal supply disruptions would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Global Zener Diode Market