
 Flip Chip Technology Market | 2026-2036
Flip Chip Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Flip Chip Technology Market Intelligence
Aftermarket service revenue for legacy wirebond-to-flip chip conversions is narrowing as OEMs shift toward native flip chip designs during initial product development. ASE Technology Holding leverages its integrated fan-out capacity to anchor high-volume production for mobile AP customers. JCET Group sustains R&D intensity through advanced substrate development for automotive radar modules. Taiwan Semiconductor Manufacturing Company dominates the foundry-side flip chip bumping flow, controlling critical copper pillar metallization steps that feed downstream OSAT partners.
Flip chip technology electrically connects a semiconductor die to a substrate or carrier via conductive bumps deposited on the chip surface, eliminating wire bonds and enabling pad pitches below 40 micrometers for high I/O density. Consumer electronics applications lead volume consumption due to smartphone SoC and tablet processor requirements, though automotive electronics represents the fastest-growing segment as ADAS compute platforms migrate from wirebond to flip chip for thermal and signal integrity reasons. Copper bumping material commands premium positioning over solder alternatives in high-current power devices, while wafer-level packaging integration is reshaping how semiconductor manufacturers contract OSAT partners for mid-range logic products.
EPA hazardous substance rules and REACH chemical restrictions constrain lead-free solder alloy formulations and underfill material selections across multi-jurisdictional supply chains. China's MIIT enforces domestic GB standards for gallium nitride device packaging, affecting material qualification timelines for foreign substrate suppliers. ECHA substance-of-very-high-concern listings for certain epoxy hardeners are forcing reformulation of capillary underfills used in industrial applications. Stakeholders must monitor how regional carbon border adjustments reshape substrate sourcing economics between Asian OSAT clusters and European automotive module plants.
Market Dynamics
Advanced packaging demand from AI accelerators and high-performance computing clusters is compressing bump pitch requirements below 40 micrometers, forcing substrate suppliers and OSAT partners to synchronize metallization capabilities across Taiwan's Hsinchu corridor.
Growth Catalysts
- AI Accelerator Deployment:Hyperscale data centers in the United States and China are pulling copper pillar flip chip volumes upward for GPU and TPU modules. Thermal dissipation requirements exceed wirebond capabilities.
- Automotive Radar Migration:ADAS compute platforms in Germany and Japan are switching from wirebond to flip chip for signal integrity at 77-81 GHz frequencies. Substrate qualification cycles are accelerating.
- REACH Chemical Compliance:ECHA substance-of-very-high-concern listings are eliminating legacy epoxy hardeners from capillary underfills, opening qualification windows for reformulated materials with superior thermal cycling performance.
Market Restraints
- Substrate Supply Concentration:ABF substrate capacity concentrates among three Japanese suppliers, creating allocation risk during high-volume mobile AP ramps. Lead times extend to 26 weeks during peak demand.
- Copper Pillar Capital Intensity:Electroplating equipment for 20-micrometer pitch bumping requires $40-60 million per line expansion, freezing out mid-tier OSAT competitors.
- Lead-Free Solder Alloy Constraints:EPA hazardous substance rules and state-level RoHS variations in the United States complicate multi-jurisdictional underfill formulations, extending material qualification timelines.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are attracting substrate suppliers to Gujarat and Karnataka, creating captive demand for flip chip bumping services.
- Wafer-Level Packaging Convergence:Fan-out panel-level packaging is integrating with flip chip flows, enabling OSATs to capture mid-range logic products previously served by wirebond.
- China Dual Carbon Mandates:MIIT enforcement of domestic GB standards for gallium nitride device packaging is forcing foreign substrate suppliers to localize production, opening joint venture structures.
Industry Challenges
- Copper Pillar Metallization Expertise Gap:Foundry-to-OSAT handoff requires synchronized electrochemical deposition control that few technicians outside Taiwan's Hsinchu cluster have mastered.
- Multi-Jurisdictional Certification Overlap:ECHA SVHC listings, EPA hazardous substance rules, and China's GB standards create conflicting material restrictions that formulation chemists must reconcile simultaneously.
- Legacy Wirebond Conversion Friction:Automotive tier-one suppliers in Germany and Japan face 18-24 month requalification cycles when switching established radar modules from wirebond to flip chip architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip Chip Technology Market |
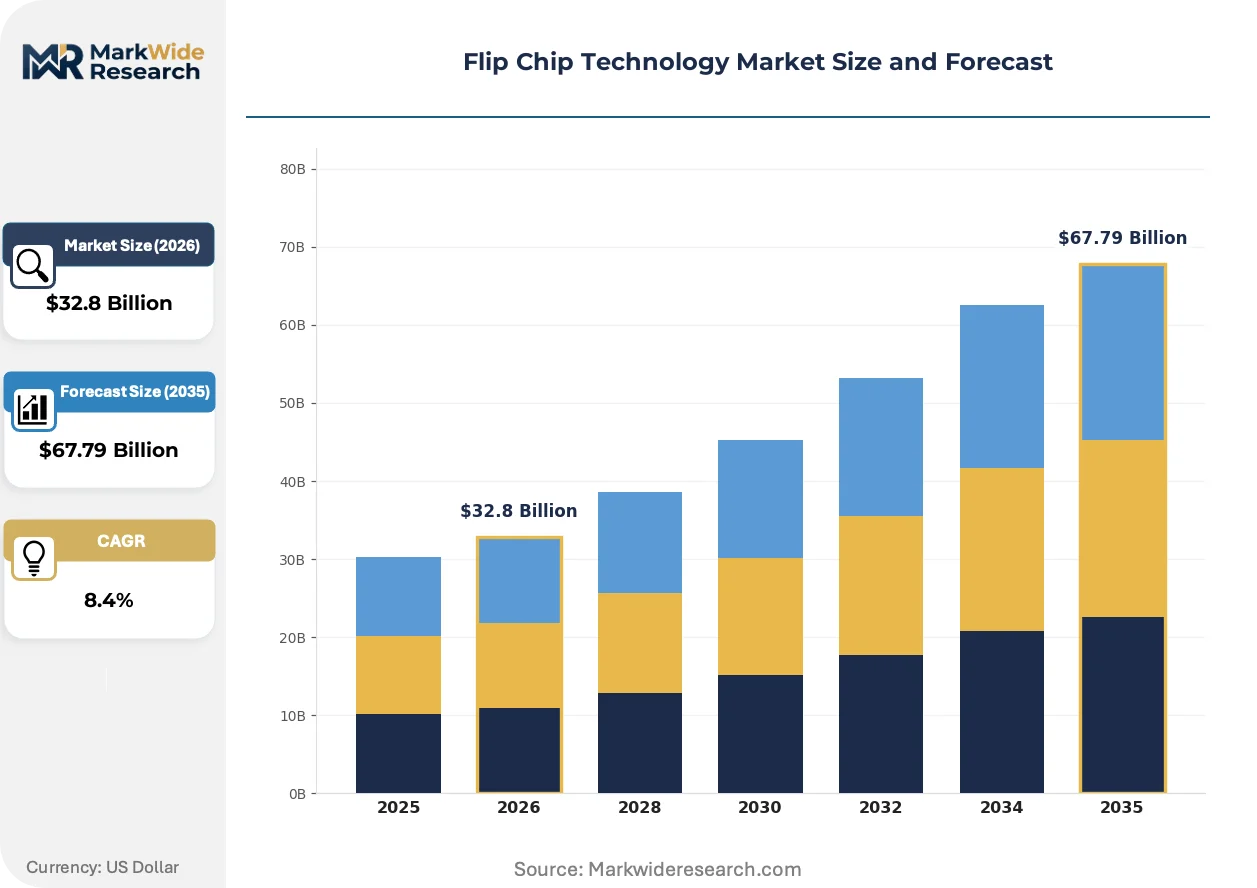
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Applications Material: Silicon, Gallium Nitride, Copper, Organic Substrates End User: OEMs, Semiconductor Manufacturers, System Integrators, Research Institutions Technology: 3D Packaging, Advanced Packaging, Wafer-Level Packaging, Hybrid Integration |
| Companies Covered | JCET Group, UTAC Holdings, Amkor Technology, TongFu Microelectronics, Chipbond Technology Corporation, ASE Technology Holding, Powertech Technology, Hana Micron, Taiwan Semiconductor Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip Chip Technology Market Strategic Shifts & Innovations
Thermal management architectures and regulatory chemical restrictions are simultaneously pushing material scientists and process engineers toward convergent solutions that redefine bumping-to-substrate interfaces.
Thermal interface materials between flip chip dies and heat spreaders are migrating from traditional greases to sintered silver formulations that withstand 250°C junction temperatures. Power module manufacturers in Germany and Japan are adopting these materials for electric vehicle inverters. This shift is compressing the addressable market for legacy silicone-based thermal pads while opening equipment sales for pressure-assisted sintering tools.
ECHA substance-of-very-high-concern listings for specific bisphenol derivatives and epoxy hardeners are forcing capillary underfill reformulations across European automotive supply chains. Industrial module assemblers must qualify alternative chemistries that maintain adhesion strength across -40°C to 150°C thermal cycling. German automotive tier-one suppliers are responding by consolidating qualified material lists and demanding 10-year supply guarantees from reformulated underfill vendors.
Buyer consolidation among hyperscale cloud providers is concentrating flip chip procurement decisions to five dominant semiconductor designers in the United States and China. These buyers are unbundling bumping, substrate procurement, and final test into separately negotiated contracts, displacing traditional turnkey OSAT arrangements. Taiwan's foundry-OSAT integration model is facing pressure from this disaggregation in data center accelerator segments.
Flip Chip Technology Market Segmentation
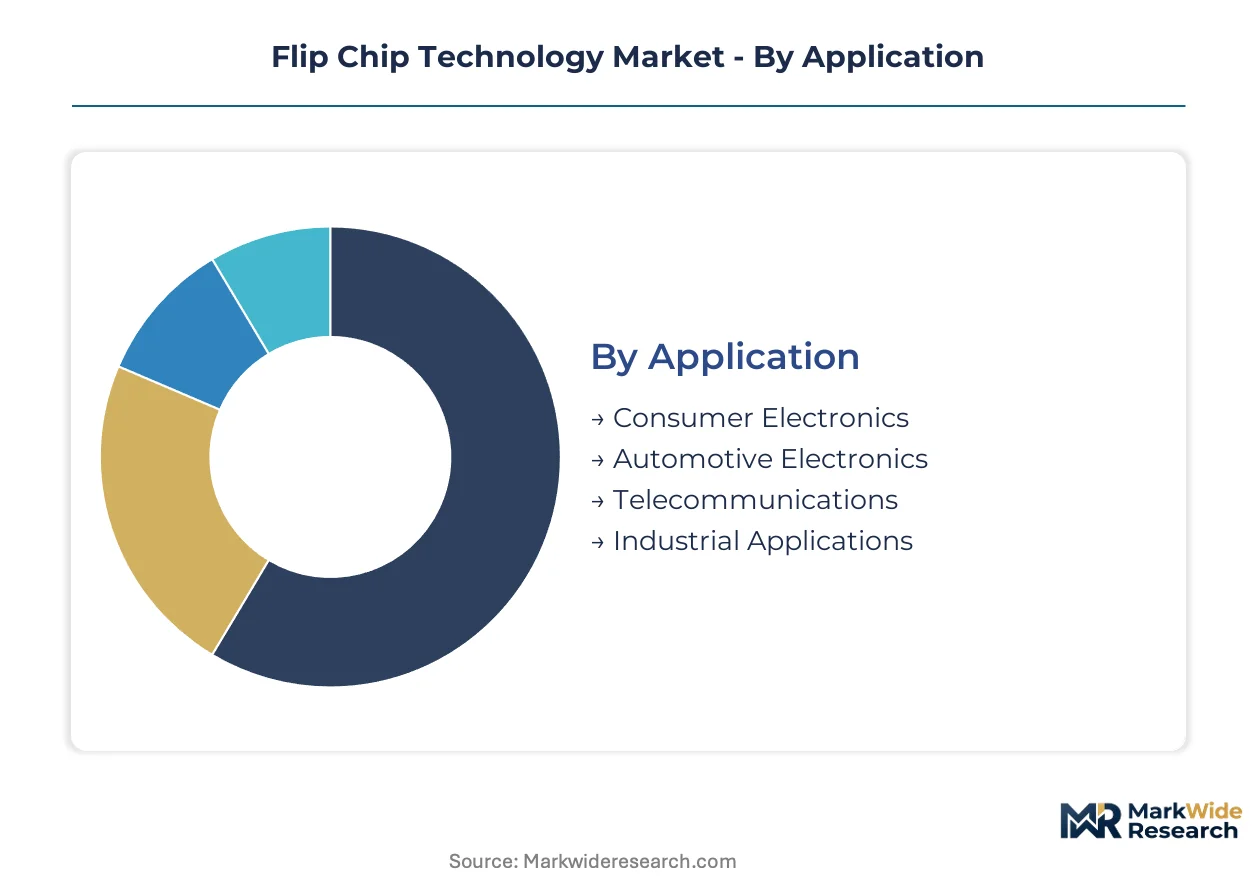
Flip chip technology spans divergent maturity levels across application domains, material systems, and integration architectures. Each segmentation dimension reveals distinct competitive dynamics between entrenched incumbent technologies and emerging alternatives reshaping procurement patterns.
Application:
Mature consumer platforms anchor volume consumption while emerging automotive and industrial segments reshape technical requirements.
- Consumer Electronics:Smartphone SoCs and tablet processors dominate unit demand, with Taiwan's Hsinchu corridor concentrating foundry-to-OSAT integration for mobile AP production. MIIT domestic content rules in China are forcing substrate localization for flagship device models.
- Automotive Electronics:ADAS compute platforms at 77-81 GHz frequencies are displacing wirebond architectures for signal integrity, with German and Japanese tier-one suppliers accelerating qualification cycles. REACH chemical restrictions constrain underfill material selections across European supply chains.
- Telecommunications:Baseband processors and RF front-end modules for 5G infrastructure require sub-40 micrometer bump pitches that concentrate capability among Taiwan's integrated foundry-OSAT partnerships.
- Industrial Applications:Power modules and motor controllers prioritize thermal cycling reliability over density, with EPA hazardous substance rules complicating lead-free solder formulations for multi-jurisdictional deployments.
Consumer electronics retains volume leadership; automotive electronics holds the steepest expansion curve.
Material:
Cost tiers separate commodity substrates from premium compound semiconductor and metallization materials commanding specialized processing equipment.
- Silicon:Standard CMOS dies constitute the baseline volume platform, with copper pillar bumping flows concentrated at Taiwan Semiconductor Manufacturing Company and downstream OSAT partners in Hsinchu.
- Gallium Nitride:Wide-bandgap substrates for power and RF applications face China's GB standards enforcement for domestic packaging qualification, forcing foreign suppliers into joint venture structures.
- Copper:Electroplated pillar metallization for high-current devices requires $40-60 million per line expansion, freezing out mid-tier competitors from sub-20 micrometer pitch capability.
- Organic Substrates:ABF substrate capacity concentrates among three Japanese suppliers, creating allocation risk with 26-week lead times during mobile AP ramps.
Silicon maintains cost leadership; gallium nitride is climbing the fastest as dual carbon mandates accelerate power device substitution.
End User:
Customer type determines procurement structure, from turnkey OSAT arrangements to disaggregated contracting separating bumping, substrate, and test.
- OEMs:Hyperscale cloud providers in the United States and China are unbundling traditional turnkey contracts, separately negotiating bumping, substrate procurement, and final test for AI accelerators.
- Semiconductor Manufacturers:Integrated device houses maintain captive bumping for proprietary power products, with backward integration into copper pillar electroplating common among automotive-qualified suppliers.
- System Integrators:Module assemblers for industrial and automotive applications face ECHA SVHC compliance deadlines for capillary underfill reformulations.
- Research Institutions:University and national laboratory programs pilot hybrid integration schemes, though volumes remain negligible for commercial substrate suppliers.
Semiconductor manufacturers retain procurement volume leadership; OEMs are gaining share fastest through hyperscale disaggregation.
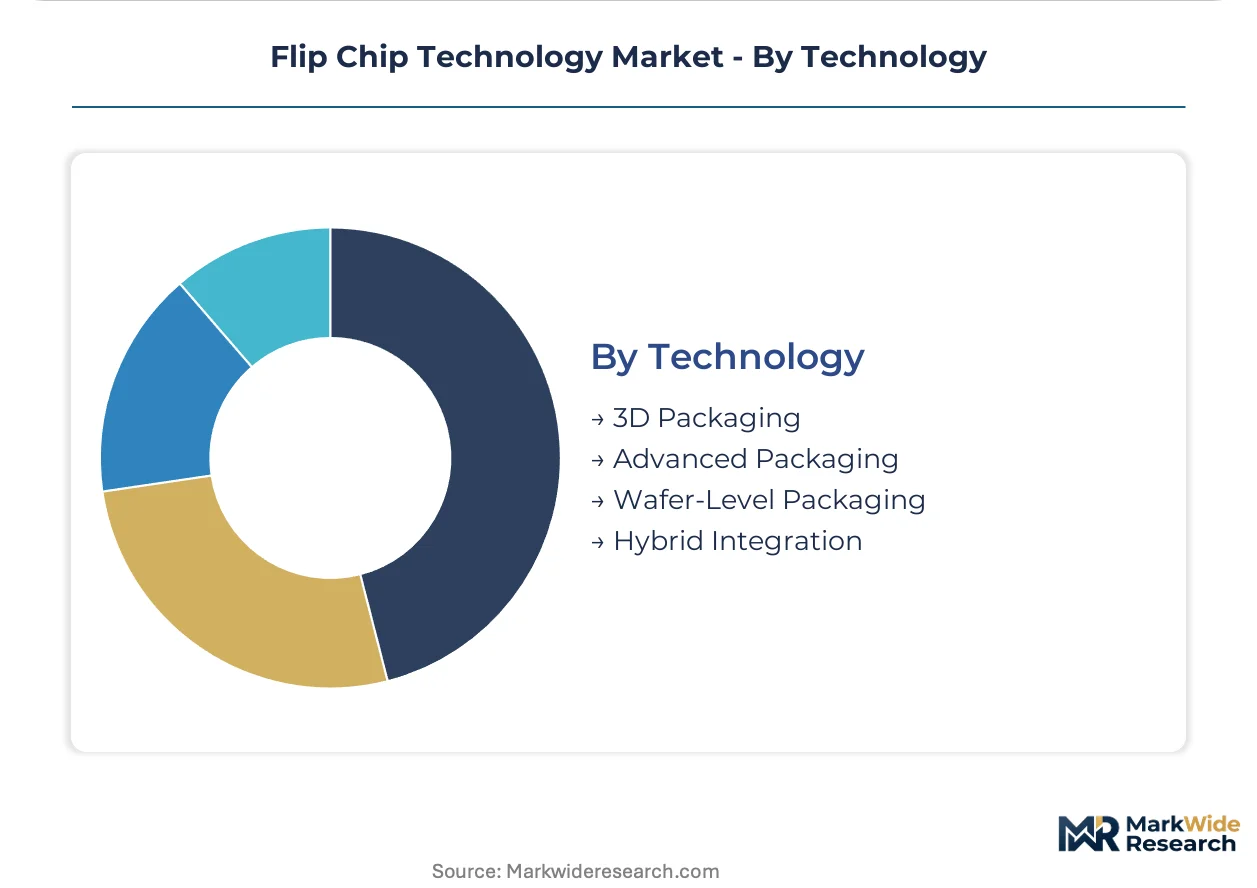
Technology:
Integration depth separates wafer-level approaches from die-level packaging, with hybrid architectures emerging at the convergence boundary.
- 3D Packaging:Through-silicon via stacking enables memory-on-logic configurations for AI accelerators, with thermal dissipation requirements exceeding wirebond capabilities.
- Advanced Packaging:Fan-out panel-level integration is capturing mid-range logic products previously served by wirebond, reshaping OSAT contracting patterns.
- Wafer-Level Packaging:Bumping and redistribution at wafer scale concentrates capability among Taiwan's foundry-integrated players, with ASE Technology Holding anchoring high-volume mobile AP production.
- Hybrid Integration:Chiplets and heterogeneous integration combine dielet technologies from multiple nodes, requiring synchronized substrate design rules across disaggregated supply chains.
Wafer-level packaging retains volume leadership; hybrid integration holds the steepest expansion trajectory as chiplet architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flip chip bumping capacity clusters in Taiwan's Hsinchu corridor, where foundry-to-OSAT integration controls critical copper pillar metallization flows. Substrate supply concentrates among Japanese suppliers, while end-demand pulls from United States hyperscale data centers, German automotive tier-ones, and Chinese gallium nitride power device manufacturers.
United States
Hyperscale cloud providers in Virginia, Oregon, and Texas drive copper pillar volumes for GPU and TPU modules. EPA hazardous substance rules constrain lead-free solder alloy formulations across multi-jurisdictional deployments. Intel's advanced packaging operations in Arizona and New Mexico anchor domestic bumping capability for high-performance computing clusters.
China
Gallium nitride power device manufacturers and AI accelerator designers pull flip chip demand upward under MIIT domestic GB standards enforcement. Dual carbon goals tighten material sourcing rules for semiconductor substrates, forcing foreign suppliers into joint venture structures. Yangtze River Delta foundries in Shanghai and Suzhou deepen captive bumping integration.
Germany
Automotive tier-one suppliers accelerate ADAS radar module conversions from wirebond to flip chip for 77-81 GHz signal integrity. ECHA substance-of-very-high-concern listings eliminate legacy epoxy hardeners from capillary underfills, demanding reformulated material qualifications. Bavaria's automotive electronics corridor concentrates substrate procurement decisions for European EV inverter platforms.
Japan
ABF substrate suppliers in Tokyo and Osaka control allocation risk during mobile AP ramps, with lead times extending to 26 weeks at peak demand. METI industrial policy supports domestic packaging equipment manufacturers serving power module assemblers. Kyushu's semiconductor materials cluster supplies specialized underfill chemistries for industrial thermal cycling requirements.
India
PLI scheme incentives for semiconductor packaging attract substrate suppliers to Gujarat and Karnataka, creating captive demand for flip chip bumping services. CEA power sector mandates accelerate gallium nitride adoption in electric vehicle charging infrastructure. Telangana's emerging electronics manufacturing corridor in Hyderabad draws OSAT investment for mid-range logic products.
Flip Chip Technology Market Key Industry Players
Integrated foundry-OSAT partnerships and independent packaging specialists split the market along capability-depth lines. Taiwan's Hsinchu corridor concentrates premium-tier copper pillar metallization, while Singapore and Chinese OSATs capture mid-range volume through fan-out panel-level integration. Two archetypes dominate: vertically integrated foundry-affiliated packagers controlling critical deposition steps, and scale-driven independents competing on substrate procurement flexibility. Competitive moves center on backward integration into ABF substrate supply and geographic expansion into India PLI scheme zones.
Within the foundry-integrated tier, Taiwan Semiconductor Manufacturing Company and ASE Technology Holding anchor high-performance computing and mobile AP production respectively. Among independent packaging specialists, Amkor Technology and JCET Group occupy positions spanning automotive radar and consumer electronics segments. UTAC Holdings exemplifies the mid-tier OSAT archetype competing on qualification breadth across industrial and telecommunications applications.
| Leading Market Players |
|---|
| JCET Group |
| UTAC Holdings |
| Amkor Technology |
| TongFu Microelectronics |
| Chipbond Technology Corporation |
| ASE Technology Holding |
| Powertech Technology |
| Hana Micron |
| Taiwan Semiconductor Manufacturing Company |
| Others |
Cost & Logistics Intelligence
Undercapacity in Taiwan's Hsinchu corridor copper pillar bumping lines drives allocation premiums for automotive radar and AI accelerator substrates, compressing margins for mid-tier OSAT competitors while concentrating pricing power among integrated foundry-affiliated packagers.
Pricing Analysis
Aftermarket service revenue from legacy wirebond-to-flip chip conversion programs anchors lifetime value for established OSATs, though this stream narrows as OEMs shift toward native flip chip designs. Three-tier pricing structure across premium copper pillar, standard solder bump, and economy wirebond tiers separates thermal performance grades. Cost compression in mid-range mobile AP bumping intensifies because fan-out panel-level packaging captures volume previously served by traditional flip chip. Automotive tier-one suppliers in Germany and Japan show least price sensitivity due to 18-24 month requalification cycles, while consumer electronics OEMs in China drive hardest bargain through consolidated procurement.
Supply Chain Analysis
Export control restrictions on advanced electroplating equipment constrain sub-20 micrometer pitch capability expansion outside Taiwan, South Korea, and the United States. Raw material flows draw from Japanese ABF substrate suppliers, Chinese gallium nitride wafer foundries, and German epoxy hardener specialists. Single-source vulnerability concentrates in Tokyo and Osaka substrate allocation decisions, where three suppliers control mobile AP ramp capacity. Distribution runs through foundry-integrated partnerships for high-performance computing clusters and independent OSAT networks for mid-range consumer logic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flip chip technology faces substitution pressure from fan-out panel-level packaging in mid-range logic applications, forcing incumbents to defend premium positioning through metallization capability depth.
For Market Incumbents: Harden copper pillar expertise through captive electroplating line expansion in Taiwan's Hsinchu corridor, insulating against fan-out packaging erosion in mobile AP segments. Secure 10-year supply guarantees with reformulated capillary underfill vendors to lock in automotive radar qualifications before ECHA SVHC deadlines eliminate legacy chemistries. Backward integration into ABF substrate procurement buffers allocation risk during hyperscale data center accelerator ramps. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Karnataka PLI scheme zones, where captive demand for flip chip bumping services outpaces local supply. Target gallium nitride power module packaging for electric vehicle charging infrastructure, a segment where China's GB standards enforcement forces foreign substrate suppliers into joint venture structures that create partnership entry points. Lead with automotive radar module conversion services, offering accelerated requalification timelines against incumbent 18-24 month cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sub-20 micrometer pitch copper pillar lines, freezing out mid-tier competitors and consolidating returns among Hsinchu-integrated players. Prioritize acquisition targets with synchronized foundry-OSAT handoff capabilities and MIIT domestic qualification status for China gallium nitride packaging. Watch for inflection in India PLI scheme disbursement velocity as signal of substrate supplier relocation commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Copper Pillar Line Expansion | $40-60 million per line investments concentrate capability among Taiwan's Hsinchu-integrated foundry-OSAT partnerships. |
| ABF Substrate Backward Integration | Upstream control over Japanese supplier allocation decisions buffers 26-week lead time exposure during mobile AP ramps. |
| Capillary Underfill Reformulation | ECHA SVHC-compliant chemistry qualifications secure 10-year supply guarantees from German automotive tier-one suppliers. |
| India PLI Zone Establishment | Gujarat and Karnataka substrate supplier relocation creates captive demand for local flip chip bumping services. |
| Gallium Nitride Packaging Localization | MIIT GB standards enforcement in China forces joint venture structures that open partnership entry points for foreign entrants. |
Research Approach
A standing panel of OSAT operations directors, substrate procurement managers at automotive tier-one suppliers, foundry packaging integration leads, and capillary underfill formulation chemists provided ongoing calibration across primary interview rounds. Secondary validation drew from SEC 10-K filings by listed packaging specialists, MIIT GB standards documentation, ECHA SVHC registry updates, and Japan's METI industrial equipment shipment statistics. Bottom-up unit demand modeling across smartphone SoC, automotive radar, and AI accelerator applications triangulated against top-down semiconductor packaging revenue estimates.
Scenario-bracketing around EPA hazardous substance rule enforcement intensity, ECHA substance-of-very-high-concern listing timelines, and MIIT domestic content phase-in schedules bounded the projection horizon. Segmentation dimensions spanned application domain, bumping material system, end-user procurement structure, and integration technology depth. CAGRs derived from elasticity-adjusted demand curves for copper pillar versus solder bump alternatives, with gallium nitride power device adoption curves and fan-out packaging substitution rates as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in hyperscale data center capex cycles, automotive production volumes, or China-EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect assumptions about ECHA SVHC listing progression, MIIT enforcement consistency, and ABF substrate capacity expansion timelines. Material shifts in export control regime coverage for advanced electroplating equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
Americas Semiconductor Device Market