
 Charge Pumps Market | 2026-2036
Charge Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Charge Pumps Market Outlook
A widening capability gap between captive foundry operators and fabless designers is rotating competitive advantage toward vertically integrated players. Texas Instruments leverages in-house 300mm analog fabrication to sustain margin control across integrated charge pump portfolios. Analog Devices anchors its position through precision switched-capacitor IP developed for industrial and healthcare signal chains. STMicroelectronics competes by extending its European automotive-qualified manufacturing footprint into high-reliability charge pump modules.
Charge pumps are switched-capacitor DC-DC converters that transfer energy through controlled charging and discharging of external capacitors, achieving voltage multiplication or inversion without magnetic components. These circuits operate at switching frequencies typically ranging from hundreds of kilohertz to several megahertz, enabling compact form factors critical for battery-powered electronics and space-constrained PCB layouts. Integrated charge pumps dominate unit shipments by embedding voltage regulation and protection functions within single-die power management ICs, while standalone variants retain relevance in applications demanding discrete flexibility or specialized voltage rails. Automotive applications represent the fastest-expanding segment as electrified powertrains and ADAS sensor arrays multiply low-current auxiliary voltage requirements across vehicle platforms.
FDA electromagnetic compatibility standards for portable medical devices and EPA energy efficiency mandates for consumer electronics are tightening compliance thresholds for power conversion efficiency and conducted emissions. EU REACH substance restrictions and RoHS hazardous material limits are reshaping semiconductor packaging material selections and foundry process chemistries. China MIIT domestic certification requirements for telecommunications equipment are creating parallel qualification pathways that favor local supply chain relationships. Stakeholders must monitor evolving multi-jurisdictional efficiency and material standards to align product roadmaps with diverging regional compliance timelines.
Market Dynamics
Portable device manufacturers are consolidating switched-capacitor procurement around integrated power management ICs, compressing design cycles and squeezing standalone component margins across the voltage conversion supply base.
Growth Catalysts
- EU RoHS and REACH substance restrictions:These frameworks are accelerating material transitions in semiconductor packaging, favoring suppliers with compliant process chemistries and certified foundry relationships for automotive and medical charge pump modules.
- Electrified powertrain proliferation:Automotive OEMs are multiplying low-current auxiliary voltage rails across vehicle platforms, expanding addressable unit volume for high-reliability charge pump solutions in ADAS sensor arrays and battery management subsystems.
- China MIIT domestic certification pathways:Parallel telecommunications equipment qualification requirements are reinforcing local supply chain relationships, channeling procurement toward domestic fab capacity expansion for voltage conversion components.
Market Restraints
- Silicon wafer input cost volatility:Fluctuations in 300mm analog-grade substrate pricing compress margin predictability for integrated charge pump portfolios, particularly affecting fabless designers without captive foundry arrangements.
- Magnetic component substitution in high-current rails:Inductor-based buck-boost converters retain efficiency advantages above 500mA output, constraining charge pump addressable market in power-hungry consumer electronics segments.
- Multi-jurisdictional compliance fragmentation:Diverging EPA energy efficiency mandates, FDA electromagnetic compatibility standards, and EU material restrictions force parallel qualification investments, extending product development timelines.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor assembly and testing are creating greenfield capacity for charge pump module localization serving domestic mobile and wearable device markets.
- GaN-SiC convergence in power management:Integration of wide-bandgap switching with switched-capacitor topologies enables higher-frequency operation, opening thermal headroom for dense PCB layouts in aerospace and defense applications.
- Direct procurement from tier-one automotive:Bypassing traditional distribution channels, powertrain electrification programs are establishing long-term supply agreements with qualified charge pump manufacturers for platform-level voltage conversion.
Industry Challenges
- Analog mixed-signal design talent scarcity:Specialized expertise in switched-capacitor topology optimization and noise-sensitive layout practices remains concentrated among experienced practitioners, constraining fabless expansion.
- Automotive AEC-Q100 certification timelines:Extended qualification protocols for high-reliability charge pump modules delay revenue recognition, particularly for suppliers pivoting from consumer electronics to vehicle electrification segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charge Pumps Market |
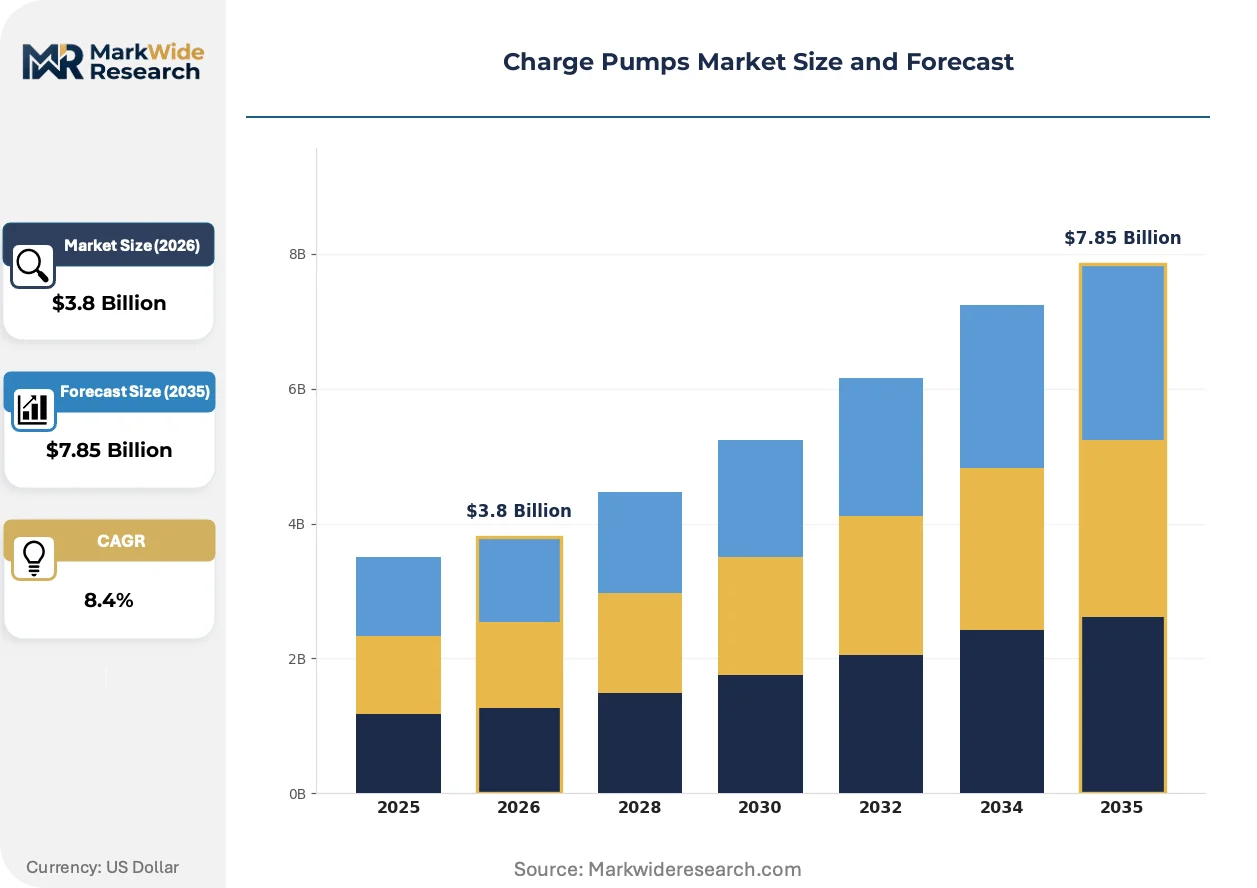
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Charge Pumps, Standalone Charge Pumps, High Voltage Charge Pumps, Low Voltage Charge Pumps Application: Portable Devices, Consumer Electronics, Automotive Applications, Industrial Equipment End User: Telecommunication, Healthcare, Automotive OEMs, Home Appliances Technology: Switched-Capacitor, Inductive Boost, Non-Isolated, Isolated |
| Companies Covered | Texas Instruments Incorporated, Analog Devices, Inc., Microchip Technology Inc., Maxim Integrated, ON Semiconductor, STMicroelectronics N.V., NXP Semiconductors N.V., Renesas Electronics Corporation, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charge Pumps Market Strategic Shifts
Switched-capacitor architectures are evolving beyond simple voltage multiplication toward programmable, multi-rail power management integration, compressing board area requirements while multiplying functional density in battery-powered systems.
Fully integrated charge pump subsystems are displacing discrete capacitor-diode networks in space-constrained wearables and hearables. Apple and Samsung tier-one suppliers are adopting single-die solutions with embedded feedback loops at compressed design cycles. This integration is displacing standalone component vendors from high-volume mobile procurement pipelines.
EPA energy efficiency mandates for external power supplies and EU Ecodesign requirements for standby power are tightening no-load consumption thresholds. Charge pump manufacturers are redesigning control loops for burst-mode operation and automatic phase shedding. Consumer electronics OEMs targeting North American and European retail channels are prioritizing certified-efficient integrated solutions over discrete alternatives.
Contract manufacturers in Shenzhen and Dongguan are consolidating component procurement through vertically integrated power module suppliers, bypassing traditional semiconductor distribution. This channel compression is most visible in China, where domestic fab capacity expansion enables direct relationships between charge pump designers and EMS providers serving global portable device brands.
Charge Pumps Market Segmentation
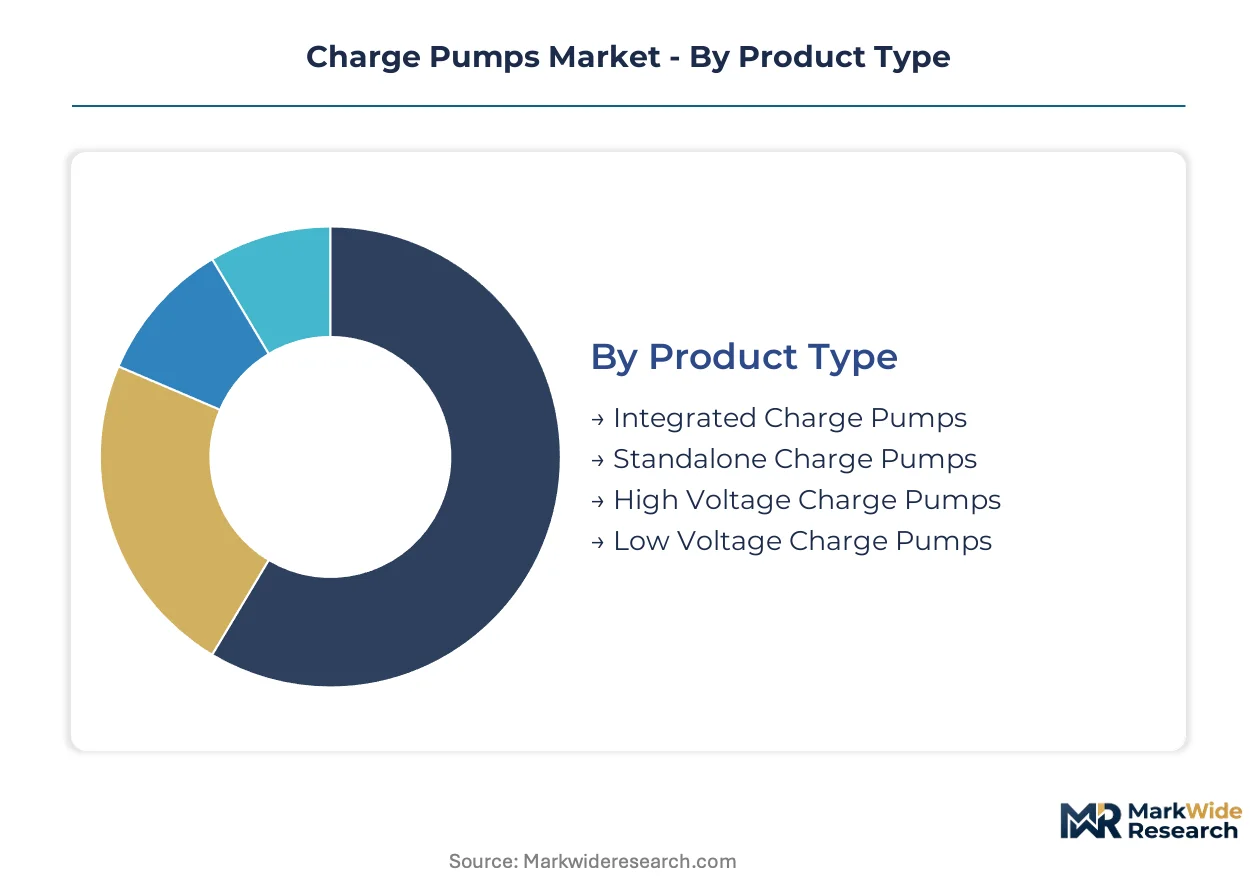
Charge pump architectures fragment across voltage classes, integration levels, and switching topologies that dictate procurement patterns. Each segment carries distinct qualification requirements, margin structures, and geographic demand concentrations that reshape competitive positioning.
Product Type:
Domestic consumption in China absorbs the bulk of integrated solutions, while export-led demand from European automotive programs sustains standalone and high-voltage variants.
- Integrated Charge Pumps:Single-die architectures embed voltage regulation, feedback loops, and protection functions within power management ICs. Smartphone and wearable OEMs in Shenzhen and Dongguan consolidate procurement around these solutions, compressing design cycles and squeezing discrete component margins.
- Standalone Charge Pumps:Discrete capacitor-diode networks retain relevance where specialized voltage rails or design flexibility outweigh integration benefits. Industrial equipment manufacturers in Germany specify these for legacy system retrofits requiring precise customization.
- High Voltage Charge Pumps:Specialized topologies for automotive ADAS sensor arrays and battery management subsystems.
- Low Voltage Charge Pumps:Compact solutions for hearables and IoT edge devices with sub-100mA requirements.
Integrated Charge Pumps holds the largest share; momentum sits with High Voltage Charge Pumps.
Application:
Cost tier separation distinguishes premium automotive electrification programs from high-volume consumer electronics procurement.
- Automotive Applications:Electrified powertrains multiply low-current auxiliary voltage rails across vehicle platforms. Tier-one suppliers in Stuttgart, Wolfsburg, and Munich establish long-term supply agreements for AEC-Q100 qualified modules serving ADAS and battery management subsystems.
- Portable Devices:Space-constrained wearables and hearables demand fully integrated switched-capacitor subsystems. Apple and Samsung supply chains in Vietnam and India specify single-die solutions at compressed design cycles.
- Consumer Electronics:EPA energy efficiency mandates and EU Ecodesign standby power requirements tighten no-load consumption thresholds for external power supplies.
- Industrial Equipment:Precision signal chains in healthcare and factory automation require noise-optimized voltage conversion.
Automotive Applications commands premium pricing; Portable Devices delivers unit volume scale.
End User:
Customer type fragmentation separates qualified automotive OEM procurement from price-sensitive home appliance manufacturing.
- Automotive OEMs:Platform-level electrification programs bypass traditional distribution channels for direct manufacturer agreements. High-reliability charge pump modules face extended AEC-Q100 qualification timelines that delay revenue recognition.
- Telecommunication:China MIIT domestic certification pathways for telecommunications equipment reinforce local supply chain relationships. Domestic fab capacity expansion channels procurement toward local voltage conversion component sourcing.
- Healthcare:FDA electromagnetic compatibility standards for portable medical devices tighten compliance thresholds for conducted emissions and power conversion efficiency.
- Home Appliances:Cost-optimized solutions for white goods with basic voltage multiplication requirements.
Automotive OEMs dominates value capture; Telecommunication shows steepest expansion trajectory.
Technology:
Supply concentration in switched-capacitor IP holders shapes competitive access across topology categories.
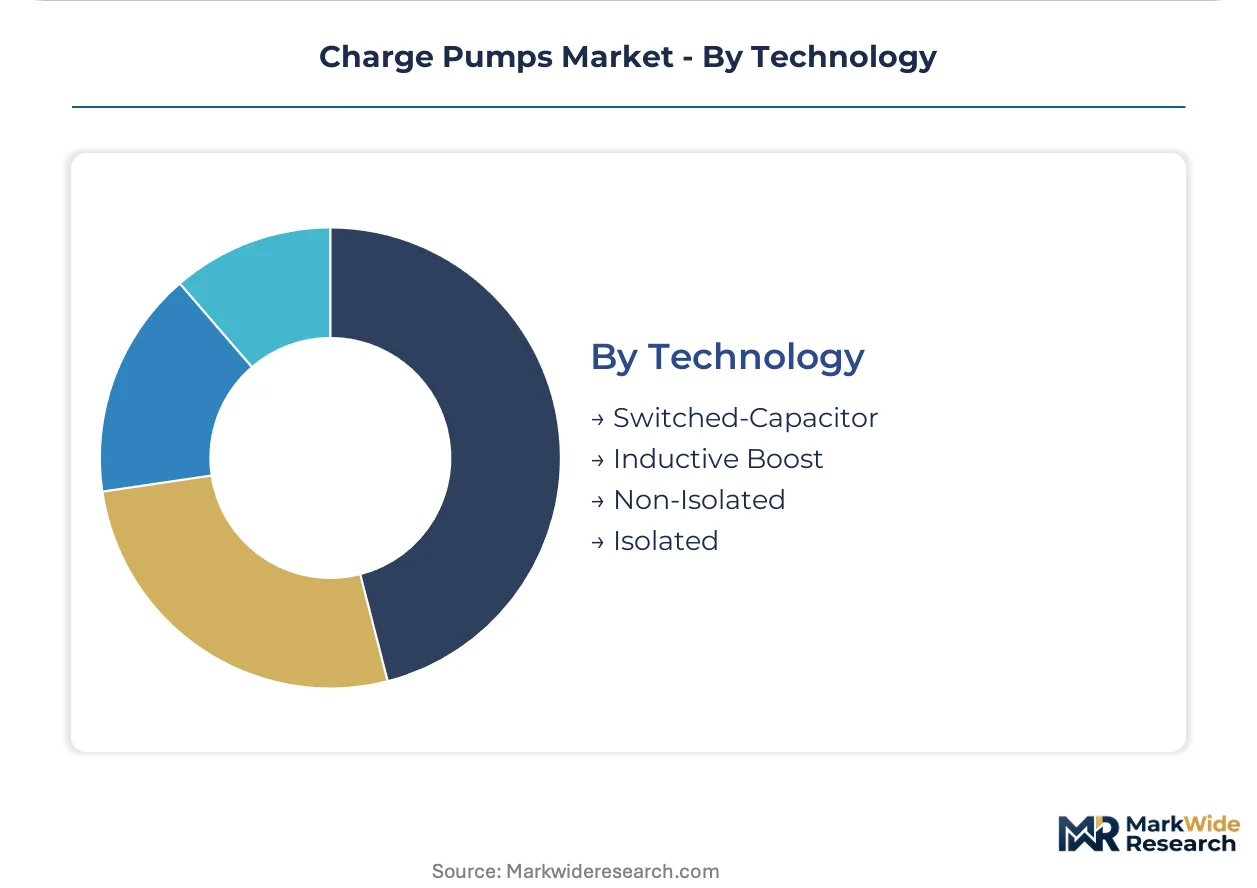
- Switched-Capacitor:Charge transfer through controlled capacitor charging and discharging achieves voltage multiplication without magnetic components. Frequencies from hundreds of kilohertz to several megahertz enable compact form factors critical for battery-powered electronics and dense PCB layouts.
- Inductive Boost:Inductor-based buck-boost converters retain efficiency advantages above 500mA output, constraining charge pump addressable market in power-hungry segments.
- Non-Isolated:Direct DC-DC conversion without galvanic isolation for cost-sensitive consumer applications.
- Isolated:Transformer-coupled architectures for medical and industrial safety-critical voltage rails.
Switched-Capacitor anchors the technology base; Isolated solutions gain share in medical qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premium multiples over procurement costs in Vietnam, reflecting divergent certification requirements and automotive qualification intensity across manufacturing geographies.
China
Domestic fab capacity expansion in Shanghai and Wuxi accelerates local sourcing of voltage conversion components for telecommunications and consumer electronics. MIIT domestic certification pathways reinforce supply chain relationships with indigenous charge pump designers. Contract manufacturers in Shenzhen and Dongguan consolidate procurement through vertically integrated power module suppliers.
United States
EPA energy efficiency mandates for external power supplies tighten no-load consumption thresholds, compressing design cycles for portable device power management. FDA electromagnetic compatibility standards for portable medical devices elevate compliance investment for healthcare-bound components. Design activity concentrates in Silicon Valley and Greater Austin, where analog mixed-signal talent clusters around integrated power management development.
Germany
Automotive OEMs in Stuttgart, Wolfsburg, and Munich establish long-term supply agreements for AEC-Q100 qualified charge pump modules serving electrified powertrains. EU REACH substance restrictions and RoHS hazardous material limits reshape semiconductor packaging material selections. Industrial equipment manufacturers specify standalone switched-capacitor networks for precision signal chain retrofits.
Japan
METI efficiency standards and JIS certification requirements govern power conversion component qualification for domestic electronics manufacturing. Precision industrial and healthcare applications sustain demand for noise-optimized voltage conversion in Osaka and Nagoya industrial corridors. Tier-one automotive suppliers integrate high-reliability charge pump subsystems into ADAS sensor platforms.
India
PLI scheme production-linked incentives for semiconductor assembly and testing create greenfield capacity for charge pump module localization. Domestic mobile and wearable device markets expand procurement from qualified EMS providers in Karnataka and Tamil Nadu. BIS standards compliance requirements channel investment toward certified manufacturing infrastructure.
Charge Pumps Market Competitive Environment
Concentration sits with diversified analog semiconductor conglomerates possessing captive fabrication capacity. Texas Instruments, Analog Devices, and STMicroelectronics anchor tier-one positioning through vertically integrated manufacturing and automotive qualification pipelines. The vendor base separates into three strategic archetypes: integrated power management IC specialists, discrete component suppliers serving industrial retrofits, and emerging wide-bandgap convergence players. Competitive moves center on AEC-Q100 certification acceleration and 300mm analog fab capacity expansion.
Among US-based diversified analog conglomerates, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions reflecting in-house fabrication scale and precision switched-capacitor IP depth. STMicroelectronics N.V. represents European automotive-qualified manufacturing extension into high-reliability modules. These three exemplify the capability-moat structure where captive foundry access separates margin-sustainable portfolios from fabless competitors exposed to silicon wafer input cost volatility.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Microchip Technology Inc. |
| Maxim Integrated |
| ON Semiconductor |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| Renesas Electronics Corporation |
| Infineon Technologies AG |
| Others |
Value Chain & Pricing Dynamics
AEC-Q100 automotive qualification gates supply access while simultaneously stratifying price tiers between certified and uncertified charge pump portfolios. Tier-one automotive OEMs in Stuttgart and Wolfsburg pay configured-to-order premiums for qualified modules, while standard integrated solutions compete on wafer-scale economics in Shenzhen procurement pipelines.
Pricing Analysis
Configured-to-order pricing for automotive-qualified modules commands substantial premiums over standard integrated solutions for consumer electronics. Pricing stratifies across AEC-Q100 certified, industrial-grade, and commercial-grade tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in commercial-grade segments intensifies as contract manufacturers consolidate procurement around vertically integrated power module suppliers. Consumer electronics OEMs in Vietnam and India exhibit highest price sensitivity, while automotive OEMs accept premium positioning for reliability assurance.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for analog-grade silicon substrates and specialty capacitor components. Manufacturing concentrates in China, Taiwan, and South Korea, with 300mm analog wafer fabrication drawing from polysilicon feedstock and photoresist chemical supplies. Single-source vulnerability in advanced node analog fabrication creates structural risk for fabless designers. Distribution runs through vertically integrated power module suppliers serving EMS providers directly, bypassing traditional semiconductor distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The charge pumps market tracks semiconductor capital expenditure cycles, with current fab capacity expansion indicating recovery-phase positioning favorable for qualified supplier investments.
For Market Incumbents: Compound AEC-Q100 certification pipelines to defend automotive revenue streams against emerging wide-bandgap convergence players. Accelerate 300mm analog fab capacity additions in cost-optimized geographies to offset silicon wafer input cost volatility. Deepen captive fabrication control as margin protection against fabless competitors exposed to substrate pricing swings. For New Entrants and Emerging Players: Differentiate on GaN-SiC switched-capacitor integration for aerospace and defense thermal-density applications underserved by incumbent analog portfolios. Target India PLI scheme greenfield capacity for domestic mobile and wearable device markets with localized BIS-compliant manufacturing. Pursue direct EMS partnerships in Karnataka and Tamil Nadu to bypass established distribution channels. For Investors and Strategic Acquirers: EU REACH substance restriction enforcement reshapes the acquisition landscape toward suppliers with certified compliant process chemistries and established foundry relationships. Five-to-ten year viability favors vertically integrated analog conglomerates with automotive qualification pipelines over fabless designers facing margin compression. Monitor China MIIT domestic certification pathway expansion as inflection signal for local supply chain preference intensification.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Certification Acceleration | Qualification timelines for automotive modules in Stuttgart programs compress competitive access windows. |
| 300mm Analog Fab Capacity Expansion | In-house fabrication scale in Wuxi and Greater Austin sustains margin control against wafer cost volatility. |
| GaN-SiC Topology Integration | Wide-bandgap switching convergence opens thermal headroom for dense aerospace PCB layouts. |
| India PLI Localization | Production-linked incentives in Karnataka create greenfield charge pump module capacity for domestic EMS. |
| Direct Automotive OEM Agreements | Platform-level supply contracts with Munich electrification programs bypass traditional distribution channels. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, MIIT certification databases, and AEC-Q100 qualification registries. Conversations with analog power management designers, automotive Tier 1 procurement officers, EMS supply chain managers, and fab equipment specialists informed demand-side and supply-side assessments. Bottom-up unit shipment estimates triangulate against top-down semiconductor industry revenue benchmarks.
Segmentation dimensions modeled span product type, application vertical, integration level, voltage class, and regional regulatory cluster across the projection horizon. CAGRs derive from fitted growth curves applied to historical shipment data and forward capacity expansion announcements. Forecast inputs incorporate analog fab utilization rates, automotive electrification platform ramp schedules, and REACH compliance transition timelines.
The analysis sits within stated boundaries; outcomes outside sustained analog wafer supply expansion and stable automotive electrification investment would require recalibration. Forecasts reflect assumptions regarding certification timeline stability and foundry capacity allocation priorities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Voltage Stabilizer System Market
Power Systems
Thermoelectric Assemblies Market
Power Systems
Power Integrated Modules Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
North America Micro Inverter Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
South America Battery Management System Market
Power Systems
Global Plasma Generators Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
MOSFET and IGBT Gate Driver Market
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Global Data Center Transformer Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Thyristor Market
Power Systems
Global Next Generation Power Semiconductors Market