
 Silicon Carbide (SIC) Power Semiconductors Market | 2026-2036
Silicon Carbide (SIC) Power Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
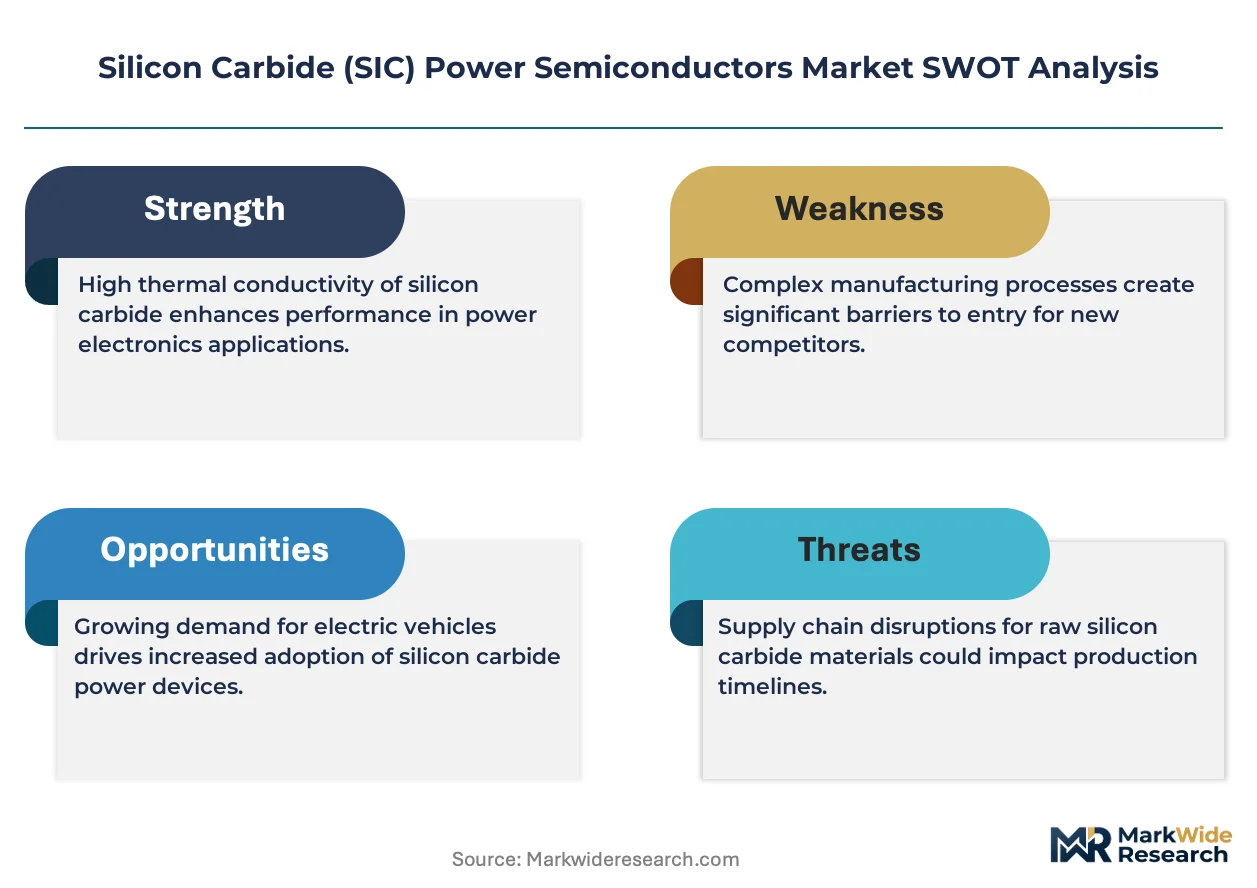
Silicon Carbide (SIC) Power Semiconductors Market Analysis
The EU Green Deal is restructuring procurement priorities across European automotive tier-ones, forcing faster displacement of silicon IGBTs in traction inverters. Wolfspeed Inc. anchors North American substrate supply through its vertically integrated Mohawk Valley fab. STMicroelectronics N.V. competes via European foundry partnerships and module packaging depth. Infineon Technologies AG dominates industrial drive applications with its CoolSiC portfolio spanning discrete and module formats.
Silicon carbide power semiconductors are wide-bandgap devices fabricated on 4H-SiC polytype substrates with bandgap energy of 3.26 eV, enabling switching frequencies above 100 kHz at breakdown voltages exceeding 1,200 V for high-efficiency power conversion. MOSFETs command the largest product type share as they displace silicon super-junction devices in EV onboard chargers and DC-DC converters. Epitaxy represents the most technically contested technology segment because defect density control during homoepitaxial growth determines final device yield and cost structure. Electric Vehicles anchor application demand, though Renewable Energy inverters are scaling fastest as utility-scale solar and wind projects adopt 1,500 V DC architectures.
The EPA tailpipe standards and EU F-Gas Regulation jointly shape product roadmaps by mandating efficiency gains that silicon carbide uniquely delivers. China's MIIT dual carbon goals and NMPA industrial standards accelerate domestic qualification timelines for automotive-grade devices. Stakeholders must monitor substrate wafer diameter transitions from 150 mm to 200 mm, as this technical inflection will reshape cost curves and supplier rankings without warning.
Market Dynamics
Wafer diameter transitions from 150 mm to 200 mm substrates are compressing cost curves faster than device yield improvements, forcing foundries to commit capital before demand visibility clears. This technical inflection is redrawing supplier rankings as captive substrate capacity becomes the primary competitive moat.
Growth Catalysts
- EPA tailpipe standards:The regulations mandate efficiency thresholds that silicon IGBTs cannot meet, forcing automotive OEMs to qualify SiC MOSFETs for traction inverters ahead of original roadmaps.
- Electric vehicle powertrain integration:Onboard chargers and DC-DC converters are switching to 1,200 V SiC architectures to reduce thermal management mass and extend driving range.
- China's MIIT dual carbon goals:Domestic substrate capacity expansion in Jiangsu and Shandong provinces is accelerating automotive-grade device qualification timelines for local EV manufacturers.
Market Restraints
- Substrate cost volatility:4H-SiC boule growth requires energy-intensive physical vapor transport, exposing margins to electricity price swings in manufacturing clusters.
- Epitaxy yield limitations:Defect density control during homoepitaxial growth on 150 mm wafers remains the dominant yield killer, constraining effective supply expansion.
- Silicon super-junction competition:Mature silicon devices below 900 V applications retain cost advantages that delay SiC penetration in industrial motor drives.
Strategic Opportunities
- Renewable energy inverters:Utility-scale solar and wind projects adopting 1,500 V DC architectures create fresh demand for high-voltage SiC modules beyond automotive saturation.
- EU F-Gas Regulation:The framework mandates efficiency gains in power conversion equipment, opening subsidy pathways for SiC adoption in European grid infrastructure.
- 200 mm wafer transition:Early movers mastering larger-diameter substrate production will capture disproportionate share as cost-per-ampere drops reshape procurement criteria.
Industry Challenges
- Power electronics talent scarcity:The shortage of engineers trained in wide-bandgap device characterization and gate driver design is extending product development cycles.
- Automotive AEC-Q101 certification:Extended qualification timelines for discrete SiC devices create inventory risk as OEMs demand multi-year supply commitments before volume approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Carbide (SIC) Power Semiconductors Market |
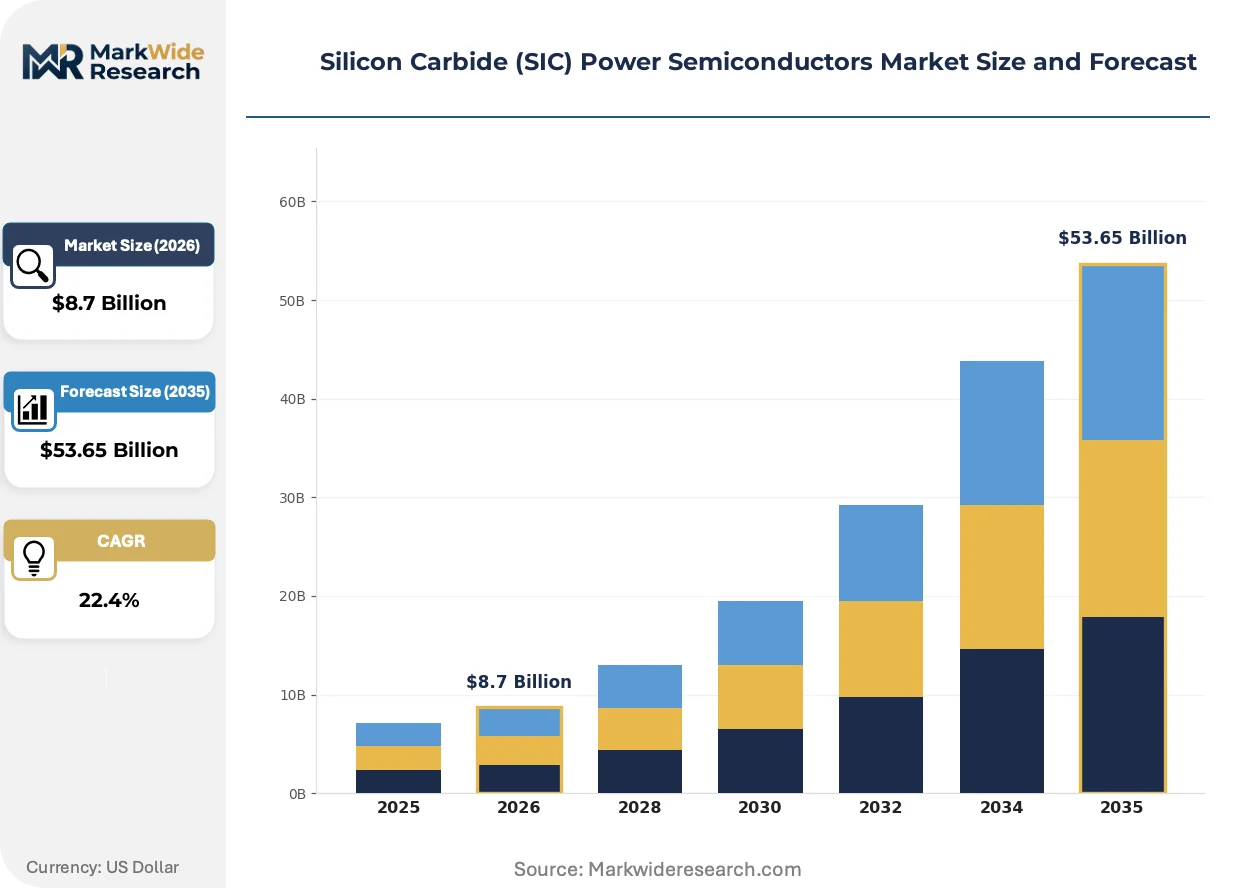
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diodes, MOSFETs, IGBTs, Modules Technology: Substrate Technology, Epitaxy, Doping Techniques, Fabrication Application: Electric Vehicles, Renewable Energy, Power Supplies, Industrial Drives End User: Aerospace, Automotive, Telecommunications, Consumer Electronics |
| Companies Covered | Infineon Technologies AG, STMicroelectronics N.V., Wolfspeed Inc., onsemi Corporation, ROHM Co., Ltd., Littelfuse Inc., Fuji Electric Co., Ltd, Mitsubishi Electric Corporation, GeneSiC Semiconductor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Carbide (SIC) Power Semiconductors Market Emerging Trajectories
Process automation and substrate scaling are converging to compress manufacturing economics while regulatory pressure accelerates qualification velocity across automotive supply chains.
Automated epitaxy process control is automating defect mapping and real-time growth parameter adjustment during homoepitaxial layer deposition. Tier-one foundries in Germany and Japan are deploying these systems to reduce manual intervention and improve wafer-to-wafer uniformity. This automation is compressing the timeline for 200 mm process qualification and reducing reliance on specialized technician labor pools.
The EU Green Deal's carbon border adjustment mechanism is forcing European automotive tier-ones to document supply chain emissions from substrate mining through module assembly. This regulatory pressure is accelerating supplier audits and favoring vertically integrated manufacturers with transparent Scope 3 reporting. German OEMs are responding by consolidating procurement around qualified European foundry partnerships.
Direct OEM-foundry contracting is displacing traditional distributor-led procurement for automotive-grade SiC devices. Tier-one EV manufacturers in China and the United States are negotiating multi-year offtake agreements directly with substrate producers to secure allocation ahead of capacity ramps. This channel shift is most visible in Ningbo and Detroit manufacturing corridors where volume commitments now precede AEC-Q101 completion.
Silicon Carbide (SIC) Power Semiconductors Market Segmentation
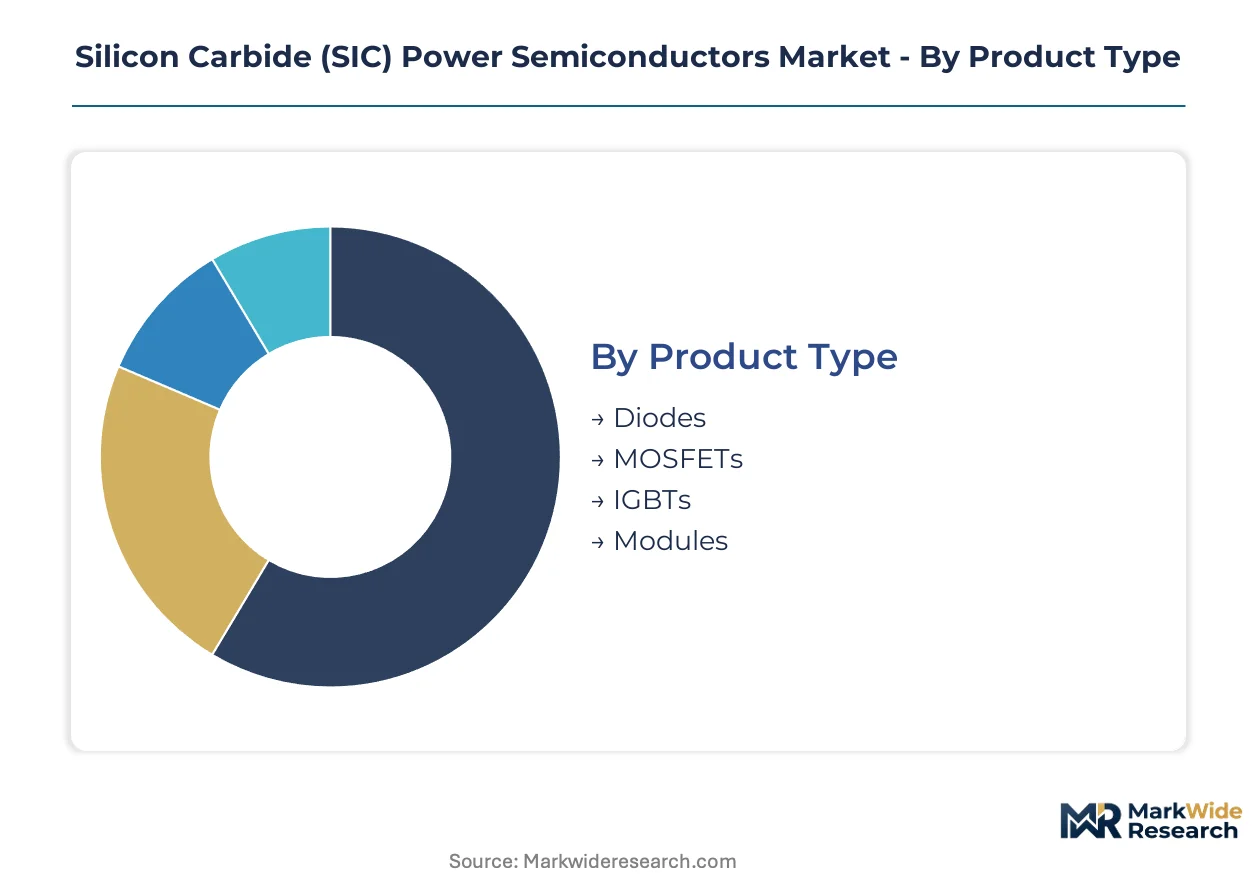
Silicon carbide power semiconductor procurement follows distinct technical and economic logics across each dimension. Buyers weigh switching frequency requirements against qualification timelines, while supply constraints reshape prioritization within each category.
Product Type:
Engineering teams select devices based on voltage blocking requirements and thermal management constraints, with cost-per-ampere driving final specification.
- MOSFETs:These unipolar switching devices deliver on-resistance below 10 mΩ at 1,200 V, enabling traction inverter designs that shed 40% of cooling system mass. Demand concentrates in Ningbo and Detroit manufacturing corridors where 800 V EV architectures are becoming standard.
- Modules:Integrated half-bridge and six-pack configurations package multiple dies with ceramic substrates and gate drivers, reducing assembly complexity for 300 kW+ drivetrains. European wind inverter OEMs are consolidating procurement around 1,700 V rated modules to simplify 1,500 V DC bus designs.
- Diodes:Schottky barrier rectifiers serve freewheeling and boost converter roles where switching losses dominate silicon alternatives.
- IGBTs:Bipolar devices retain niche positioning in hybrid modules combining Si IGBTs with SiC diodes for cost-sensitive industrial drives.
Volume sits with MOSFETs; growth tilts toward modules as system-level integration accelerates.
Technology:
Process maturity determines yield economics and effective supply expansion rates across the manufacturing chain.
- Epitaxy:Homoepitaxial growth of 4H-SiC layers on off-axis substrates demands defect density below 1 cm⁻² for automotive-grade reliability. German and Japanese foundries are deploying automated process control to compress 200 mm qualification timelines.
- Substrate Technology:4H-SiC boule growth via physical vapor transport sets the fundamental cost floor, with electricity-intensive manufacturing clustering in Jiangsu and Shandong provinces to leverage industrial power pricing.
- Doping Techniques:Nitrogen and aluminum ion implantation create source, drain, and body regions with activation anneals above 1,600°C.
- Fabrication:Trench gate etching and ohmic contact metallization complete device processing, with 200 mm wafer transitions requiring retooling of implant and lithography equipment.
Yield constraints concentrate in epitaxy; capacity expansion depends most critically on substrate technology.
Application:
End-use requirements span from automotive AEC-Q101 qualification to utility-scale reliability standards, fragmenting procurement specifications.
- Electric Vehicles:Onboard chargers, DC-DC converters, and traction inverters anchor current demand volumes, with 800 V architectures displacing 400 V designs across premium and mass-market segments. Chinese OEMs are qualifying domestic devices ahead of MIIT dual carbon compliance deadlines.
- Renewable Energy:Utility-scale solar and wind inverters adopting 1,500 V DC architectures create fresh demand for high-voltage modules, with European projects leveraging EU F-Gas Regulation subsidies to justify SiC premiums.
- Power Supplies:Data center and telecommunications rectifiers prioritize efficiency at partial load conditions where silicon losses compound.
- Industrial Drives:Motor control applications above 900 V are switching to SiC, though silicon super-junction devices retain cost advantages below this threshold.
Revenue concentration favors electric vehicles; renewable energy is climbing the fastest as project pipelines accelerate.
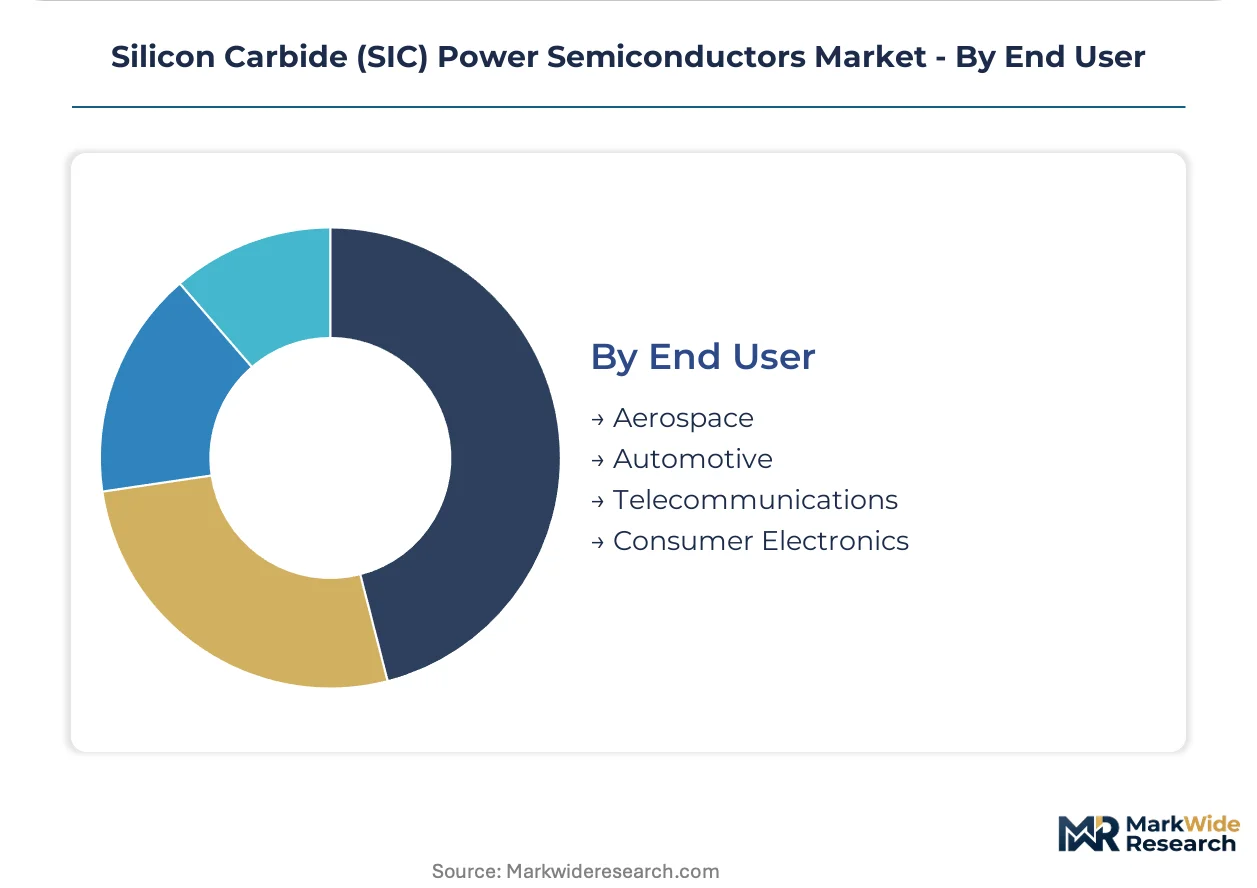
End User:
Customer qualification standards and volume scales create tiered supply relationships, with automotive and aerospace demanding the most intensive certification.
- Automotive:Tier-one EV manufacturers negotiate multi-year offtake agreements directly with substrate producers, bypassing traditional distribution. AEC-Q101 qualification timelines extending 18-24 months create inventory risk for suppliers committing capacity ahead of volume approval.
- Aerospace:Satellite power conditioning and aircraft actuator systems prioritize radiation hardness and thermal cycling resilience over cost, accepting premium pricing for hermetic packaging and traceable substrate provenance.
- Telecommunications:Base station power supplies and data center rectifiers demand high-frequency operation to reduce magnetics size, with efficiency gains translating directly to operating cost reductions.
- Consumer Electronics:Adapter and charger applications below 100 W remain silicon-dominated, though GaN and SiC are penetrating premium laptop and mobile fast-charging segments.
Procurement scale peaks with automotive; margin structure favors aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo anchors substrate capacity expansion through Jiangsu and Shandong province clustering, where electricity-intensive boule growth leverages industrial power pricing. Detroit corridors concentrate EV powertrain integration. German automotive tier-ones restructure procurement around EU Green Deal compliance.
China
MIIT dual carbon goals compress automotive-grade device qualification timelines for BYD and NIO supply chains. NMPA industrial standards enforce reliability benchmarks that domestic foundries must meet before volume approval. Jiangsu province hosts the fastest 200 mm wafer pilot lines, with Shandong boule growth facilities scaling to capture cost-per-ampere advantages.
United States
EPA tailpipe standards mandate efficiency thresholds silicon IGBTs cannot satisfy, forcing Ford and GM to accelerate SiC traction inverter roadmaps. The Inflation Reduction Act subsidizes domestic semiconductor fabrication through CHIPS Act alignment. Mohawk Valley in New York hosts vertically integrated substrate production serving North American EV corridors.
Germany
KBA vehicle certification timelines pressure BMW and Volkswagen to qualify European-sourced modules ahead of 2025 fleet efficiency deadlines. EU F-Gas Regulation mandates power conversion equipment upgrades that SiC uniquely addresses. Bavaria hosts automated epitaxy process control deployments that compress 200 mm qualification timelines.
Japan
METI semiconductor strategy directs capital toward wide-bandgap device characterization talent pools. JIS standards create qualification pathways for automotive and industrial applications. Kyushu maintains concentration in substrate fabrication equipment supply, feeding global boule growth capacity expansion.
South Korea
MFDS medical device power supply requirements create secondary demand for high-frequency SiC rectifiers. Hyundai-Kia EV platforms drive 800 V architecture adoption across premium and mass-market segments. Seoul Capital Area foundries specialize in trench gate etching processes for next-generation MOSFET designs.
Silicon Carbide (SIC) Power Semiconductors Market Vendor Landscape
Premium-margin players sit above commodity-margin players across substrate captive capacity and automotive qualification depth. The vendor base stratifies into three tiers: vertically integrated substrate-to-device manufacturers, European foundry-dependent module packagers, and Japanese industrial drive specialists. Two dominant competitive moves define positioning: 200 mm wafer transition commitments ahead of demand visibility, and direct OEM-foundry offtake agreements that bypass traditional distribution channels.
Among vertically integrated substrate producers, Wolfspeed Inc. anchors North American supply through captive boule growth and fabrication. STMicroelectronics N.V. exemplifies the European foundry partnership model, leveraging regional packaging depth to serve German automotive tier-ones. Infineon Technologies AG occupies the industrial drive specialization tier, with CoolSiC portfolio breadth spanning discrete and module formats for factory automation and renewable energy inverter OEMs.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| Wolfspeed Inc. |
| onsemi Corporation |
| ROHM Co., Ltd. |
| Littelfuse Inc. |
| Fuji Electric Co., Ltd |
| Mitsubishi Electric Corporation |
| GeneSiC Semiconductor Inc. |
| Others |
Supply Flow & Price Mechanics
Physical vapor transport electricity consumption in Jiangsu and Shandong provinces feeds through substrate boule costs to module pricing tiers, with energy-intensive 4H-SiC crystal growth anchoring the premium band and epitaxy yield losses compressing margins at the standard tier.
Pricing Analysis
Yield-per-wafer throughput anchors value-based pricing, with automotive-grade MOSFETs commanding premiums against industrial diodes. Pricing stratifies across AEC-Q101 certified, JIS-qualified, and uncertified tiers. Cost compression in standard-tier modules is intensifying because Chinese domestic capacity expansion is accelerating. Industrial drive OEMs exhibit highest price sensitivity; aerospace satellite power conditioning shows lowest.
Supply Chain Analysis
Single-source vulnerability sits with 4H-SiC substrate boule supply concentrated in China, the United States, and Japan. Polysilicon feedstock, high-purity graphite crucibles, and argon process gas draw from specialty chemical suppliers. Tariff exposure on semiconductor fabrication equipment creates procurement risk. Distribution runs through direct OEM-foundry offtake agreements displacing traditional component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxy defect density constraints prop pricing power by throttling effective supply expansion regardless of substrate capacity announcements.
For Market Incumbents: Anchor captive boule growth capacity in Mohawk Valley or Jiangsu corridors to defend against Chinese substrate entrants. Lock multi-year offtake agreements with Detroit and Ningbo EV manufacturers before 200 mm qualification waves commoditize 150 mm supply. Certification depth in AEC-Q101 and JIS standards remains the critical lever. For New Entrants and Emerging Players: Capture renewable energy inverter module white space in European utility-scale solar projects leveraging EU F-Gas Regulation subsidy pathways. Industrial motor drives above 900 V present the most penetrable displacement opportunity against silicon super-junction incumbents. Pursue foundry partnership models with German automotive tier-ones seeking second-source qualification. For Investors and Strategic Acquirers: 200 mm wafer pilot line announcements from Jiangsu facilities are the leading indicator that cost-per-ampere curves will flatten faster than consensus assumes. Five-to-ten year viability favors vertically integrated substrate-to-device manufacturers over module packagers dependent on external epitaxy supply. Watch EPA tailpipe standard enforcement velocity as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| 200 mm Wafer Transition | Captures cost-per-ampere advantages before competitors qualify larger-diameter processes. |
| Direct OEM-Foundry Contracting | Bypasses distributor margins and secures allocation ahead of automotive AEC-Q101 completion. |
| Automated Epitaxy Process Control | Compresses yield-killing defect density through real-time growth parameter adjustment. |
| Renewable Energy Module Certification | Opens EU F-Gas Regulation subsidy pathways for utility-scale inverter projects. |
| Substrate Capacity Expansion | Locks electricity-intensive boule growth in low-cost industrial power clusters. |
Methodological Framework
Independent corroboration across substrate fabrication executives, automotive Tier 1 procurement officers, and renewable energy inverter OEMs underwrites the qualitative findings. Primary fieldwork with epitaxy process engineers, power electronics design leads, and foundry operations managers combined with secondary validation from MIIT policy filings, EPA regulatory dockets, EU ETS carbon border documentation, and SEC semiconductor capex disclosures. Bottom-up wafer throughput estimates and top-down EV production forecasts were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window isolates substrate scaling effects from device yield improvements. Segmentation modeling spans product type, voltage rating tier, application end-use, and regional regulatory cluster. CAGRs were derived from supply-constrained demand absorption curves rather than unconstrained market sizing. Forecast inputs include 800 V EV architecture penetration rates and utility-scale solar inverter replacement cycles.
The model holds under sustained EPA and EU Green Deal enforcement; deviation in MIIT dual carbon timeline acceleration or 200 mm yield breakthroughs would shift supply elasticity assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Varactor Diode Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Precision Link Carrier Market