
 Medical Crutches Market | 2026-2036
Medical Crutches Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Crutches Market Intelligence
Chinese aluminum tubing supply for lightweight crutch frames is hardening as producers absorb energy cost volatility. Invacare Corporation leverages its North American distribution network to sustain institutional contract renewals. Drive DeVilbiss Healthcare competes on value-engineered portfolios that anchor homecare channel penetration. Medline Industries controls private-label supply relationships with major hospital purchasing cooperatives.
Medical crutches are ambulatory assistive devices manufactured from aluminum alloys, composite polymers, or hardwood laminates, typically adjustable between 4.5 and 6.5 feet in user height and rated for static load capacities spanning 150 to over 350 pounds, designed to transfer body weight from lower extremities to the upper body during temporary or permanent mobility impairment. Standard crutches still occupy the highest unit volume globally, though forearm crutches are gaining preference in European rehabilitation protocols for long-term ergonomic benefit. Aluminum dominates material selection for its strength-to-weight ratio, while composite variants command premium positioning in sports medicine applications where vibration dampening matters.
FDA 510(k) clearance requirements and ISO 13485 quality management systems govern market access for crutch manufacturers selling into the United States, with the EPA additionally restricting certain polymer additives in pediatric device configurations. The EU Medical Device Regulation imposes stricter post-market surveillance and unique device identification obligations on European-bound shipments. Stakeholders must monitor evolving reimbursement coding from CMS and parallel national health authorities, as coverage determinations directly influence provider procurement behavior and patient out-of-pocket exposure across care settings.
Market Dynamics
Hospital purchasing cooperatives are consolidating procurement authority into fewer hands, forcing manufacturers to restructure pricing and service terms around volume commitments rather than individual institutional relationships.
Growth Catalysts
- ISO 13485 certification mandates:Quality management requirements are filtering out marginal suppliers and elevating compliant manufacturers into preferred vendor status with major health systems.
- Aluminum tubing innovation:Advanced extrusion techniques from Chinese producers are reducing frame weight without sacrificing load ratings, expanding addressable patient populations.
- Sports medicine clinics:Rising athletic injury volumes in the United States are sustaining replacement cycles for composite forearm crutches with superior vibration dampening.
Market Restraints
- Energy cost volatility:Aluminum smelting input expenses are compressing margins for lightweight frame producers dependent on Chinese supply.
- FDA 510(k) clearance timelines:Regulatory review periods for new crutch configurations are extending commercialization schedules and freezing design iteration.
- Walker substitution:Knee scooters and rollators are capturing short-term rehabilitation episodes where crutches previously dominated.
Strategic Opportunities
- Pediatric configurations:EPA restrictions on polymer additives in children's devices are creating first-mover advantages for compliant material innovators.
- Homecare direct-to-patient:E-commerce channels are bypassing durable medical equipment distributors and capturing margin previously lost to intermediaries.
- EU MDR compliance:Unique device identification requirements are advantaging manufacturers with established European quality infrastructure over late entrants.
Industry Challenges
- Biomechanical engineering talent:Shortage of specialists capable of optimizing load distribution across adjustable crutch geometries is constraining product development pipelines.
- CMS reimbursement coding alignment:Misalignment between device categories and coverage determinations is creating revenue recognition uncertainty for providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Crutches Market |
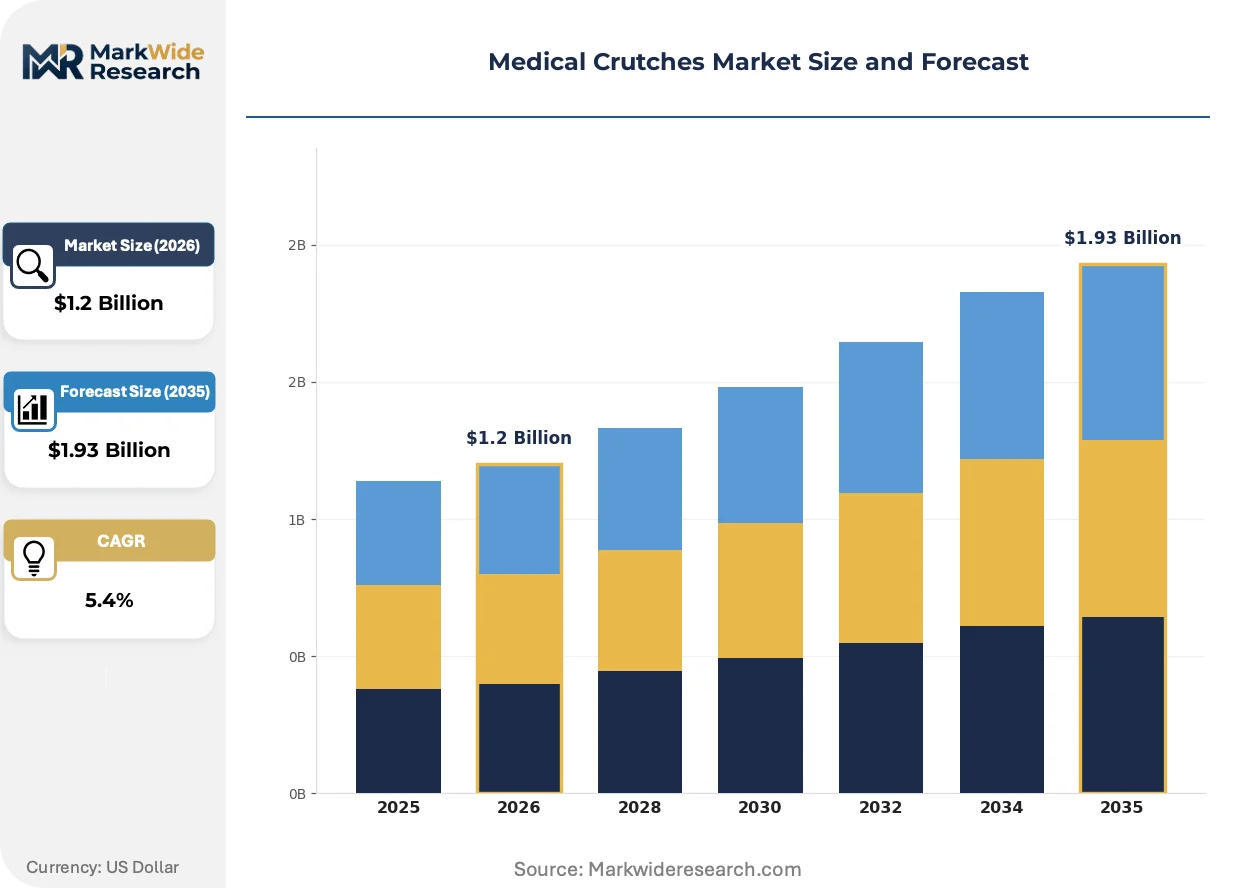
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.93 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Crutches, Forearm Crutches, Knee Crutches, Platform Crutches Material: Aluminum, Wood, Plastic, Composite Weight Capacity: Up to 150 lbs, 150-250 lbs, 250-350 lbs, Over 350 lbs End User: Hospitals, Rehabilitation Centers, Homecare, Sports Clinics |
| Companies Covered | Invacare Corporation, Drive DeVilbiss Healthcare, Medline Industries, Sunrise Medical, Cardinal Health, Ottobock SE & Co. KGaA, Nova Medical Products, AMG Medical, Breg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Crutches Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory digitization are compressing product lifecycles while elevating performance benchmarks across ambulatory assistive categories.
Carbon fiber reinforced polymer construction is electrifying the premium sports medicine segment. Elite athletic training facilities are specifying these frames for their superior stiffness-to-weight ratios and fatigue resistance. The technology is electrifying price stratification between institutional commodity procurement and patient-paid performance segments.
EU Medical Device Regulation post-market surveillance obligations are tightening traceability requirements. Manufacturers must now maintain active complaint monitoring and periodic safety update reporting for European-bound shipments. Rehabilitation providers in Germany and France are prioritizing suppliers with established notified body relationships to minimize supply interruption risk.
Patient self-selection through online durable medical equipment platforms is fragmenting traditional distributor relationships. Homecare patients are researching specifications independently and demanding direct fulfillment, displacing the historical role of discharge planners as gatekeepers. This pattern is most pronounced in United States metropolitan markets with high digital literacy demographics.
Medical Crutches Market Segmentation
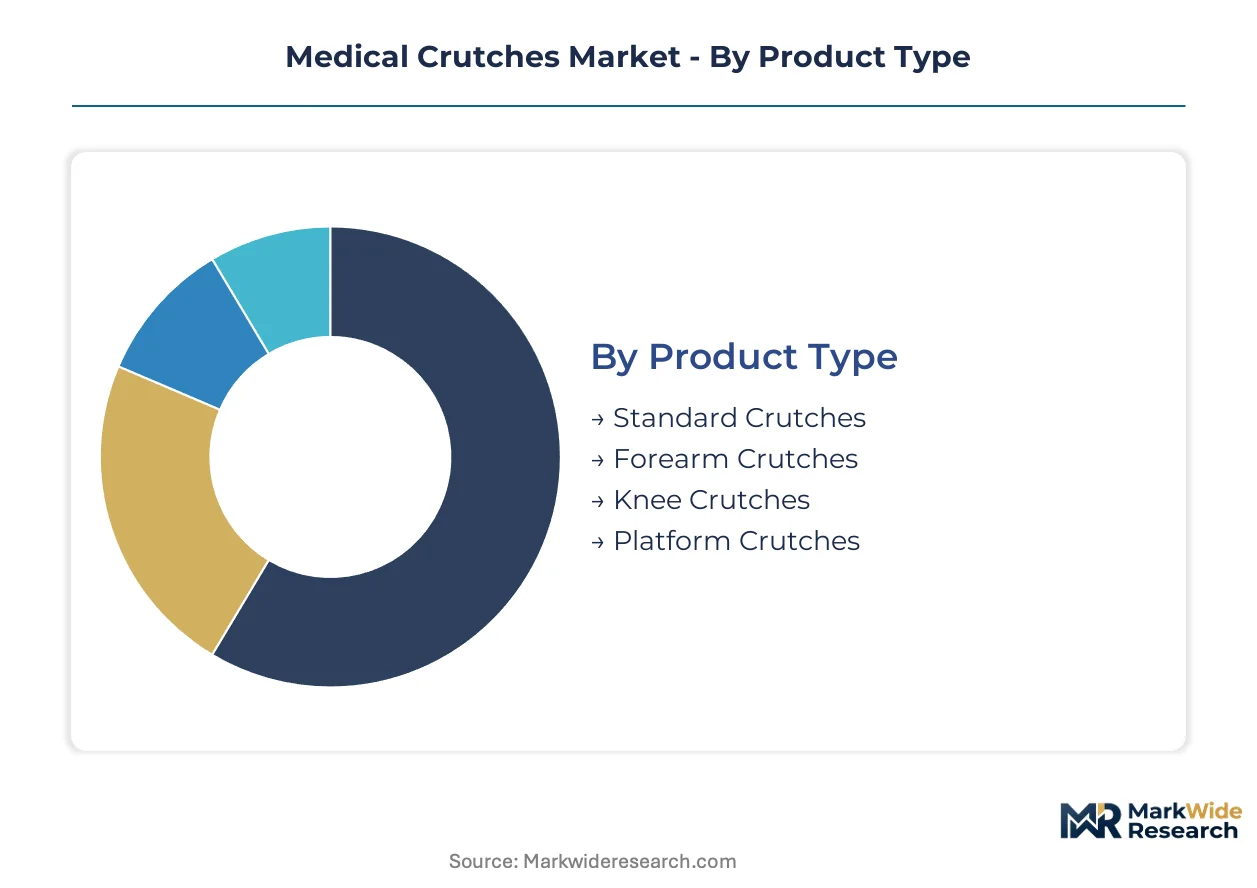
Crutch procurement patterns diverge sharply across institutional and retail channels, with product specifications, material selection, and load ratings determining contract eligibility. Manufacturers must align production configurations to distinct reimbursement codes and patient mobility profiles.
Product Type:
Capital intensity varies substantially across crutch architectures, with forearm and knee crutch variants requiring specialized tooling and ergonomic testing infrastructure.
- Standard Crutches:Axillary frames with underarm pads and handgrips dominate hospital discharge volumes. United States health systems specify these for short-term post-operative recovery where cost containment overrides ergonomic optimization.
- Forearm Crutches:Cuff-based designs with adjustable forearm supports command higher tooling investments for precision-molded components. German rehabilitation centers specify these for long-term neuromuscular conditions where weight-bearing distribution and gait mechanics receive clinical priority.
- Knee Crutches:Single-leg platforms with padded knee rests transfer load to the thigh, eliminating axillary pressure. These configurations require CNC-machined adjustment mechanisms.
- Platform Crutches:Horizontal forearm platforms with vertical handgrips accommodate patients with limited grip strength or wrist pathologies. Production involves specialized welding fixtures.
Most installed capacity flows through Standard Crutches. Expansion is steepest in Forearm Crutches.
Material:
Raw material sourcing strategies determine margin structure, with aluminum extrusion contracts locking in multi-year cost positions.
- Aluminum:6061-T6 and 7000-series alloys deliver optimal strength-to-weight ratios for institutional procurement. Chinese smelter energy costs directly frame competitive pricing for lightweight frame producers.
- Wood:Hardwood laminates persist in emerging market segments where import substitution policies favor domestic timber processing. These frames require seasonal moisture conditioning.
- Plastic:Injection-molded polymer components reduce per-unit material costs for pediatric and bariatric accessory lines. EPA restrictions on phthalate additives constrain formulation options.
- Composite:Carbon fiber reinforced polymers serve sports medicine applications where vibration dampening and fatigue resistance justify patient-paid premiums. Layup processes demand cleanroom environments.
Aluminum absorbs the largest share of production volume. Composites are climbing the fastest as athletic training facilities upgrade specifications.
Weight Capacity:
Engineering validation costs escalate with load rating thresholds, as bariatric configurations require destructive testing and reinforced joint geometries.
- Up to 150 lbs:Pediatric and geriatric lightweight frames with reduced wall thickness. These specifications concentrate in homecare channels serving smaller-stature patients.
- 150-250 lbs:Standard adult configurations meeting ISO 11199-2 static load requirements. Hospital purchasing cooperatives specify these for general orthopedic discharge.
- 250-350 lbs:Reinforced aluminum tubing with doubled wall thickness at stress points. United States bariatric surgery programs drive procurement for post-operative mobility.
- Over 350 lbs:Heavy-duty steel-reinforced frames with custom-machined joints. Limited production runs require dedicated tooling amortization across low volumes.
The 150-250 lbs segment carries the highest unit throughput. The 250-350 lbs category is expanding most quickly alongside bariatric procedure volumes.
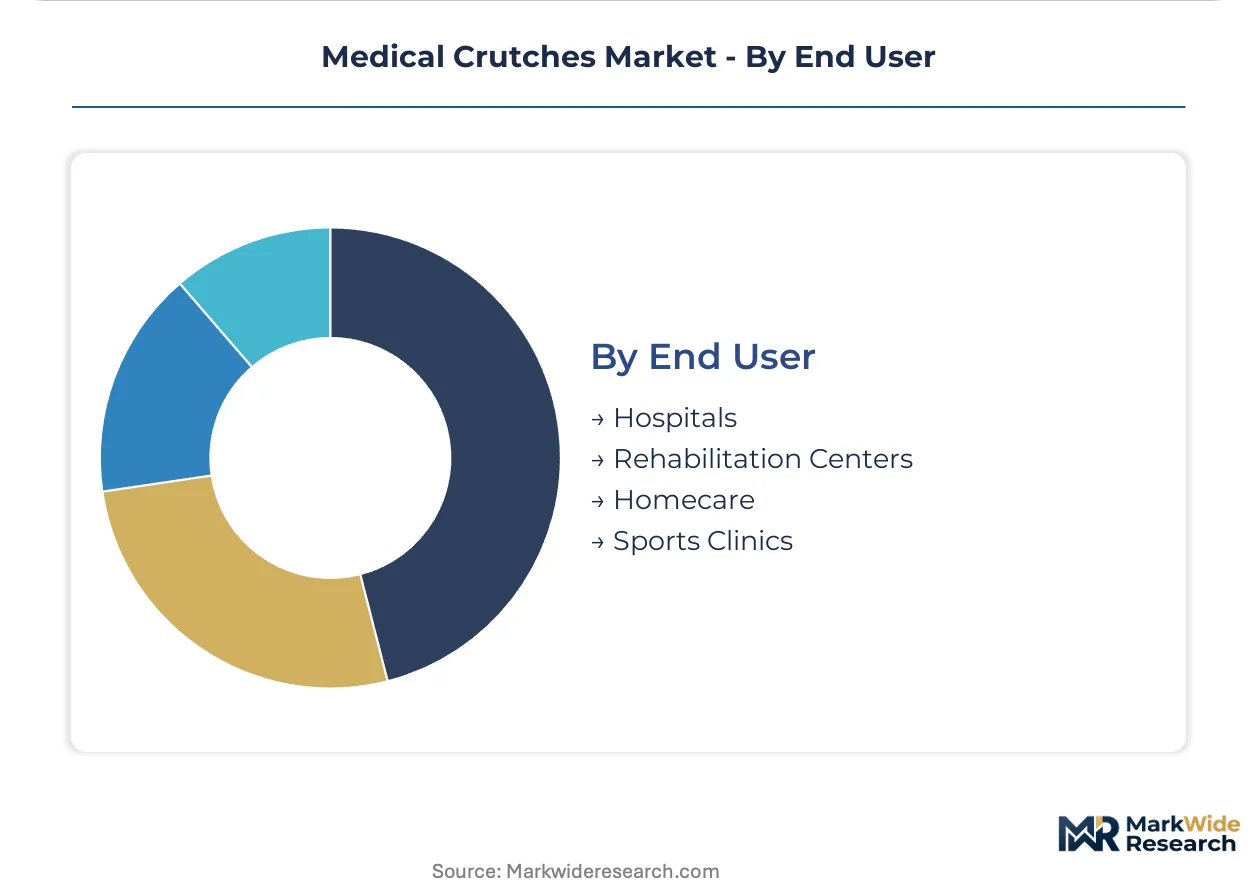
End User:
Channel-specific compliance requirements segment the vendor base, with institutional contracts demanding ISO 13485 certification and homecare tolerating broader quality variance.
- Hospitals:Acute care facilities with centralized materials management and GPO-contracted pricing. These buyers prioritize supply continuity and standardized adjustment protocols.
- Rehabilitation Centers:Outpatient therapy clinics specifying forearm crutches for gait training programs. German and French providers emphasize ergonomic adjustability.
- Homecare:Direct-to-patient fulfillment through durable medical equipment retailers and e-commerce platforms. CMS reimbursement coding determines patient out-of-pocket exposure.
- Sports Clinics:Elite athletic training facilities purchasing composite forearm crutches with custom color and branding options. These buyers bypass traditional distribution markups.
Hospitals anchor procurement volume. Sports Clinics are gaining share fastest as patient self-selection fragments traditional gatekeeper relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes exceed German hospital system purchases by a factor of three, yet both markets face tightening regulatory compliance timelines that favor established quality infrastructure.
United States
CMS reimbursement coding revisions and bariatric surgery expansion drive institutional procurement. FDA 510(k) clearance timelines extend commercialization schedules for new configurations. Cleveland Clinic and Mayo Clinic systems in the Midwest anchor GPO contract volumes for standard axillary frames.
Germany
Outpatient rehabilitation protocols emphasize forearm crutch ergonomics for neuromuscular conditions. EU MDR post-market surveillance obligations tighten traceability requirements. Stuttgart and Munich industrial clusters concentrate precision-molded component fabrication for cuff-based designs.
China
Domestic aluminum extrusion capacity absorbs energy cost volatility while serving export demand. NMPA device registration rules align with international quality benchmarks. Zhejiang and Guangdong provinces host lightweight frame manufacturing hubs supplying North American distributors.
Japan
Aging demographics sustain replacement cycles across homecare channels. METI industrial standards govern material specifications for assistive devices. Osaka-Kobe manufacturing corridor specializes in composite polymer layup for sports medicine applications.
United Kingdom
NHS procurement consolidation shifts volume toward framework agreement holders. MHRA post-Brexit regulatory autonomy maintains EU MDR alignment for market access. Midlands manufacturing base produces hardwood laminate variants for cost-sensitive segments.
Medical Crutches Market Key Industry Players
United States producers anchor the institutional tier; Chinese fabricators hold the lightweight frame supply base. The vendor base stratifies across three tiers: multinational diversified medical device conglomerates with GPO relationships, regional specialists focused on ergonomic forearm configurations, and contract manufacturers serving private-label programs. Strategic moves concentrate on ISO 13485 certification acquisition and aluminum extrusion contract renegotiation.
Within the diversified conglomerate tier, Invacare Corporation and Drive DeVilbiss Healthcare exemplify scale-driven positioning through North American distribution infrastructure. Medline Industries occupies a distinct anchor position in private-label supply relationships. Among European quality specialists, Ottobock SE & Co. KGaA represents the precision-engineering archetype with established notified body relationships for EU MDR compliance.
| Leading Market Players |
|---|
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Medline Industries |
| Sunrise Medical |
| Cardinal Health |
| Ottobock SE & Co. KGaA |
| Nova Medical Products |
| AMG Medical |
| Breg |
| Others |
Cost & Logistics Intelligence
Aluminum LME spot pricing volatility cascades through Chinese extrusion contracts into three distinct procurement tiers, with energy-intensive smelter economics forcing frame producers to renegotiate annual offtake terms against hospital GPO contract ceilings. This raw-material cost transmission splits the market between commodity axillary frames and patient-paid composite forearm variants where material science premiums absorb upstream pressure.
Pricing Analysis
Distributor markups of 35-45 percent on institutional contracts separate landed factory costs from hospital acquisition prices, with ISO 13485 certification tier and aluminum grade specification driving price differentiation between GPO-anchored standard frames and sports clinic composite orders. Cost compression in lightweight aluminum tubing is intensifying because Chinese energy subsidies are eroding, while homecare direct-to-patient channels show the highest price sensitivity as uninsured patients comparison-shop online specifications.
Supply Chain Analysis
ISO 13485 certification gating filters supplier access to United States hospital systems, with Chinese Zhejiang and Guangdong provinces anchoring aluminum frame extrusion, German Stuttgart-Munich clusters supplying precision-molded forearm cuffs, and Japanese Osaka-Kobe corridors feeding composite polymer layup for athletic applications. Raw material flows draw from 6061-T6 aluminum billet, carbon fiber prepreg, and hardwood laminates, with single-source vulnerability concentrated in Chinese smelter energy contracts. Distribution runs through durable medical equipment wholesalers, direct e-commerce fulfillment, and hospital materials management consignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
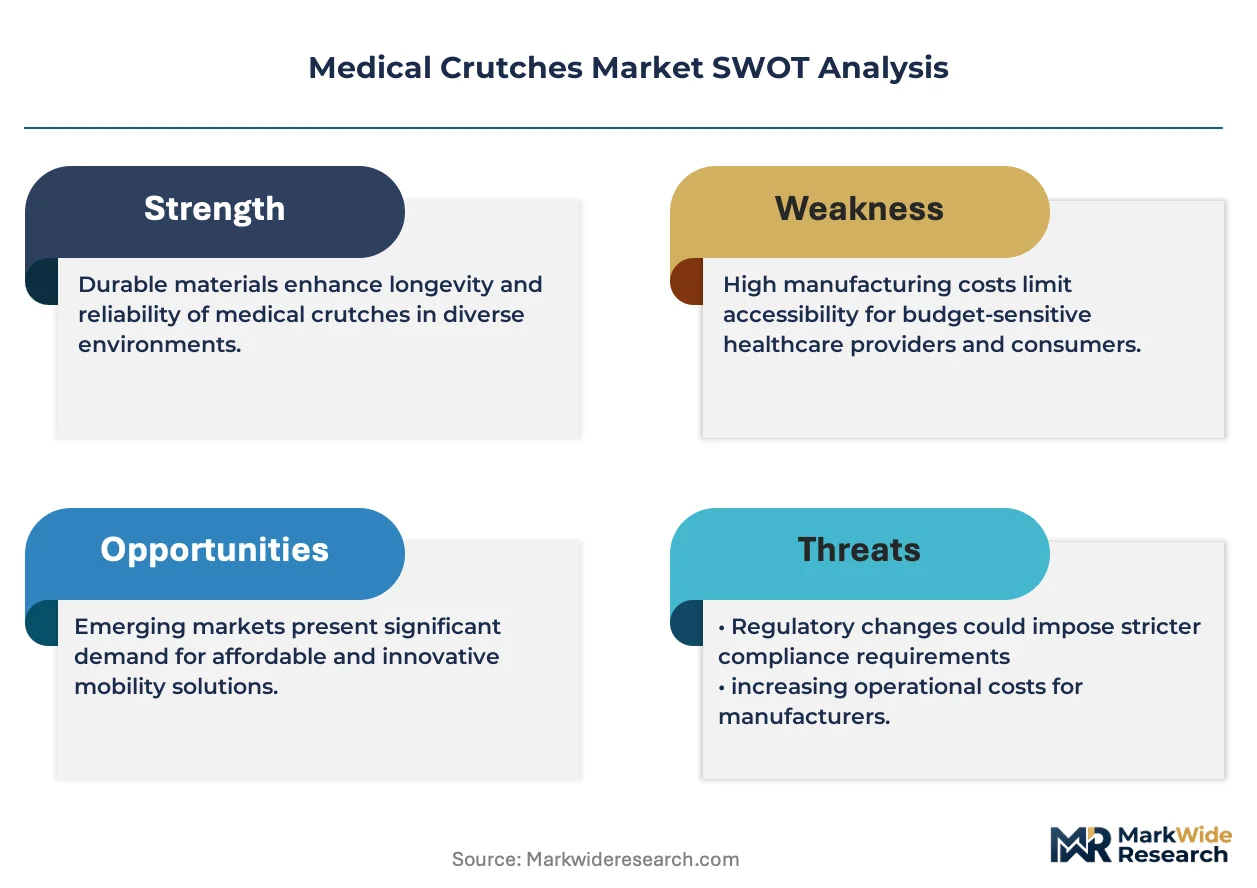
Medical crutches function as a regulatory compounder where FDA 510(k) clearance timelines and EU MDR post-market surveillance obligations continuously elevate compliance costs, with ISO 13485 certification mandates from 2021-2024 filtering marginal suppliers and consolidating procurement authority into quality-validated vendor pools.
For Market Incumbents: To counter walker and knee scooter substitution in short-term rehabilitation episodes, Invacare-class manufacturers should deepen backward integration into aluminum extrusion capacity in Zhejiang corridor partnerships while locking multi-year GPO contracts with Cleveland Clinic and Mayo Clinic systems to secure discharge volume pipelines against homecare channel fragmentation. For New Entrants and Emerging Players: E-commerce direct-to-patient routes offer the most penetrable white-space entry, with uninsured homecare patients in United States metropolitan markets seeking specification-transparent fulfillment outside distributor markups, and pediatric EPA-compliant polymer configurations presenting first-mover material innovation angles for niche positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with European quality specialists possessing established notified body relationships for EU MDR compliance, where Ottobock-class precision engineering capabilities command scarcity premiums over commodity frame producers. The signal to watch is CMS reimbursement coding alignment shifts that would revalue provider procurement behavior across institutional and homecare channels.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Quality management validation secures preferred vendor status with hospital purchasing cooperatives. |
| Aluminum Extrusion Contract Renegotiation | Multi-year offtake terms with Chinese producers lock in cost positions against energy volatility. |
| Direct-to-Patient E-Commerce Launch | Digital fulfillment captures margin from durable medical equipment distributor intermediaries. |
| Pediatric EPA-Compliant Material Development | Phthalate-free polymer formulations create first-mover advantages in restricted children's device segments. |
| EU MDR Notified Body Relationship Investment | Established European quality infrastructure minimizes supply interruption risk for German and French rehabilitation providers. |
Research Approach
Coverage spans United States, Germany, China, and Japan, with primary inputs from each market combining interviews with hospital purchasing committee managers, GPO contracts directors, biomedical engineers optimizing crutch geometries, and durable medical equipment distribution executives, validated against secondary sources including FDA 510(k) clearance databases, CMS Medicare reimbursement coding tables, EU MDR notified body registries, and aluminum trade flow customs records, with bottom-up unit volume builds triangulated against top-down market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, material grade, weight capacity tier, and end-user channel dimensions, with CAGRs derived from regression analysis of historical procurement patterns and forward projection of bariatric surgery volumes, sports injury incidence, and aging demographic mobility impairment rates throughout the forecast period.
Raw material cost spikes, FDA review timeline extensions, and CMS coding misalignments are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in Chinese aluminum smelter energy subsidy policy or EPA polymer additive restriction scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
3D Medical Implant Market