
 Surgical Rasps Market | 2026-2036
Surgical Rasps Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Rasps Market Analytics
A capital-intensity divergence between integrated manufacturers and instrument specialists is bifurcating competitive dynamics in surgical rasps. Medtronic leverages captive forging capacity to control titanium alloy supply for premium orthopedic rasps. Stryker Corporation anchors its position through dedicated reprocessing service networks that extend product life cycles for non-disposable lines. Arthrex Inc. differentiates via focused R&D intensity in serrated-edge geometries for sports medicine applications.
Surgical rasps are precision cutting instruments with serrated or toothed working surfaces, typically manufactured from medical-grade stainless steel or titanium through CNC grinding and electropolishing processes, designed to contour and shape bone during reconstructive procedures. Powered rasps are capturing disproportionate growth momentum as ambulatory surgical centers prioritize throughput efficiency over capital equipment thrift. Hand-held rasps retain stable demand in cost-sensitive clinics across emerging markets where autoclave infrastructure supports reusable workflows. Stainless steel dominates material selection for standard orthopedic applications, while titanium alloys command premium positioning in neurosurgical and maxillofacial segments where magnetic resonance imaging compatibility is essential.
FDA 510(k) premarket notification requirements govern reusable rasp revalidation cycles in the United States, while the EU Medical Device Regulation mandates unique device identification and enhanced clinical evidence for Class IIa instruments entering European markets. Japan's Ministry of Health, Labour and Welfare enforces Pharmaceutical and Medical Device Act quality management system audits that extend approval timelines for foreign manufacturers. Stakeholders must monitor evolving reprocessing validation standards and regional reimbursement divergence for disposable versus reusable instrument strategies.
Market Dynamics
Powered rasp systems are decomposing the traditional hand-held instrument hierarchy as ambulatory surgical centers prioritize throughput efficiency and reduced surgeon fatigue over capital equipment conservation.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:Enhanced clinical evidence requirements for Class IIa instruments are accelerating consolidation among manufacturers with robust quality management systems, favoring established players with dedicated regulatory affairs teams.
- ASC expansion in the United States:Outpatient orthopedic procedure volumes are concentrating in ambulatory settings where powered instrumentation supports higher case throughput and faster room turnover.
- Titanium alloy serration geometries:Advanced CNC grinding techniques enabling micron-level tooth precision are expanding MRI-compatible rasp adoption in neurosurgical and maxillofacial reconstruction.
Market Restraints
- Electropolishing chemical input volatility:Nitric acid and hydrofluoric acid supply constraints from Chinese industrial policy adjustments are compressing margins for stainless steel finishers dependent on outsourced surface treatment.
- FDA 510(k) revalidation documentation:Tightening reusable device revalidation pathways are extending time-to-market for reprocessed rasp lines and favoring disposable alternatives with simpler regulatory trajectories.
- Autoclave infrastructure dependency:Reusable rasp workflows require validated sterilization equipment that remains scarce in rural clinics across India, Brazil, and Southeast Asia, limiting addressable market expansion.
Strategic Opportunities
- Japan's aging surgical workforce:Ergonomic powered rasp designs addressing surgeon hand fatigue present white space as METI promotes robotic-assisted and powered instrumentation in orthopedic training curricula.
- Reprocessing service network unbundling:Third-party validated reprocessing providers are emerging as a channel innovation, enabling smaller manufacturers to compete on lifecycle cost without captive sterilization infrastructure.
- Sports medicine serration convergence:Hybrid geometries combining aggressive bone removal with fine contouring are opening arthroscopic rasp applications previously served by burrs and shavers.
Industry Challenges
- Electropolishing technician scarcity:Specialized surface finish expertise for medical-grade passivation is concentrating in German and Swiss job markets, creating recruitment bottlenecks for expansion-minded manufacturers.
- Legacy ERP integration with UDI tracking:EU MDR unique device identification mandates are forcing mid-tier instrument specialists to reconfigure inventory systems for lot-level traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Rasps Market |
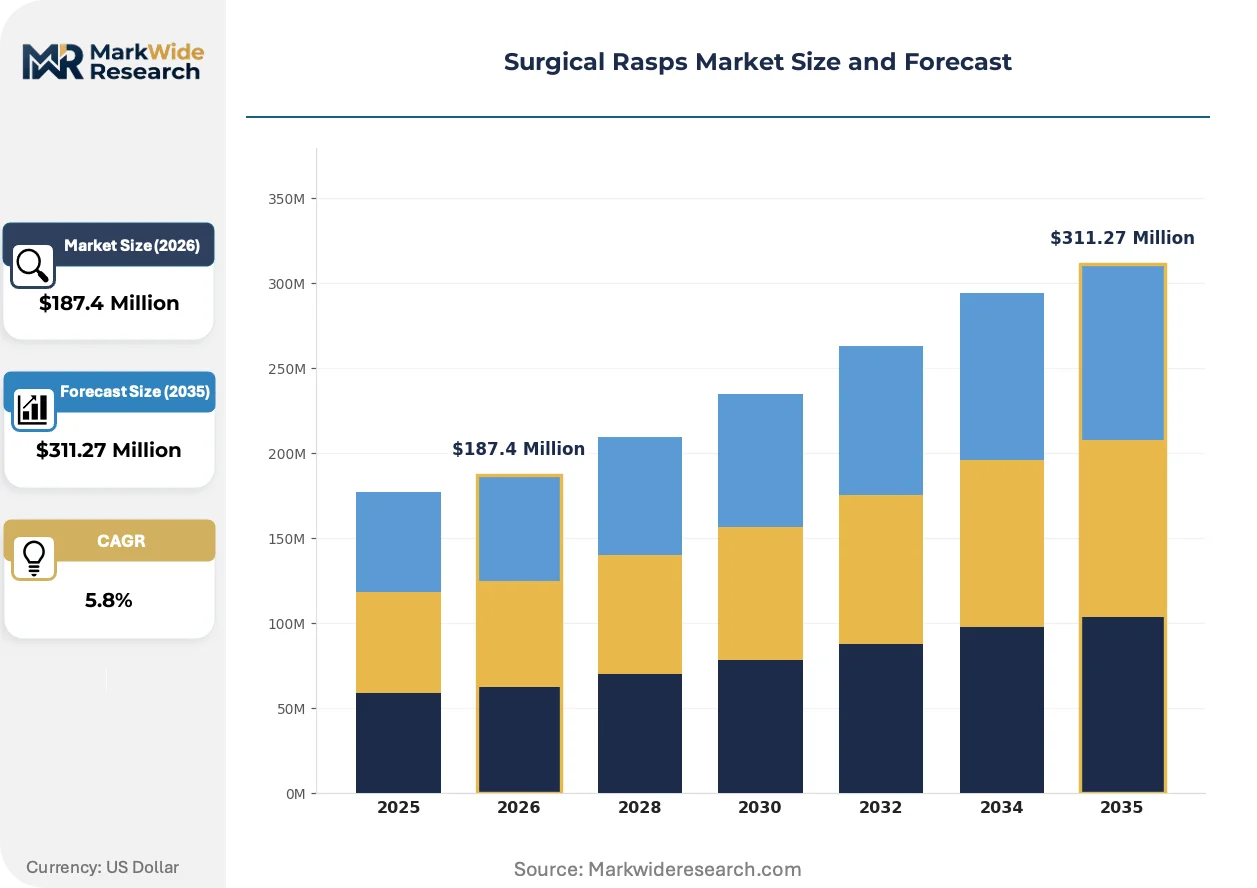
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand-held Rasps, Powered Rasps, Disposable Rasps, Non-disposable Rasps Application: Orthopedic Surgery, Dental Surgery, Plastic Surgery, Veterinary Surgery Material: Stainless Steel, Carbon Steel, Titanium, Aluminum End User: Hospitals, Clinics, Surgical Centers, Research Institutes |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson (DePuy Synthes), Zimmer Biomet, B. Braun Melsungen AG, Smith & Nephew, Arthrex Inc., Integra LifeSciences, Conmed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Rasps Market Evolving Landscape
Electrification of bone contouring instruments is compressing the traditional hand-powered segment while regulatory traceability mandates are restructuring how manufacturers manage device lifecycles from forge to final disposal.
Battery-powered rotary rasp systems are decomposing the stationary pneumatic equipment installed base in orthopedic suites. Ambulatory surgical centers in the United States and Germany are adopting cordless platforms to eliminate compressor infrastructure and reduce setup time between cases. This portability shift is enabling same-day discharge protocols and expanding procedure feasibility in office-based surgical suites.
The EU Medical Device Regulation's enhanced post-market surveillance requirements are forcing manufacturers to deploy real-world performance tracking. Class IIa instrument holders must now maintain active implantable-level vigilance systems, driving investment in digital product passports and automated adverse event reporting. German and French orthopedic divisions are responding by consolidating supplier relationships to reduce audit complexity.
Surgeon preference is rotating toward single-use rasp kits in high-volume arthroplasty centers. Hospital procurement committees in Japan and the United States are unbundling instrument sets to eliminate reprocessing labor costs and sterilization queue delays. This consumption-pattern shift is most visible in total joint replacement programs where case scheduling predictability outweighs per-procedure instrument economics.
Surgical Rasps Market Segmentation
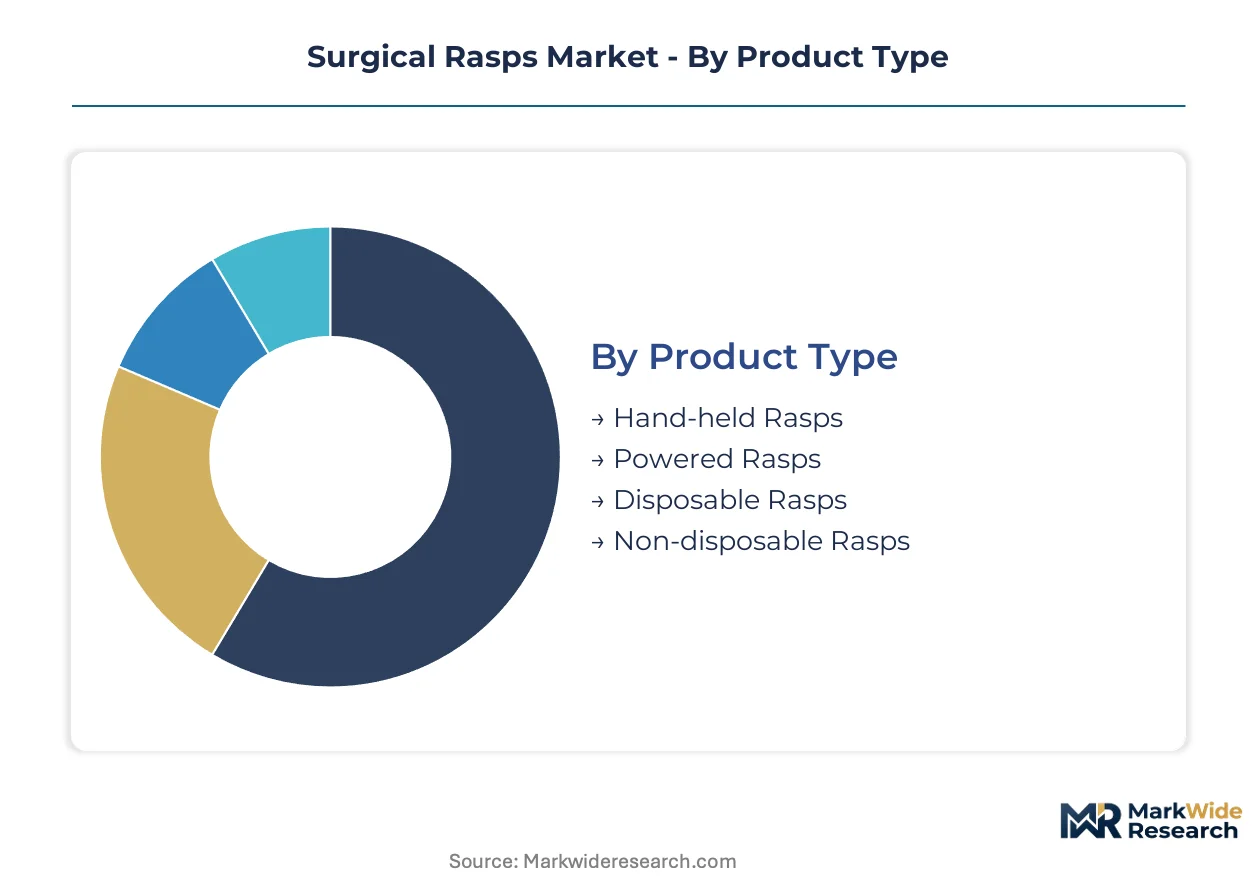
Surgical rasp manufacturers configure product portfolios around distinct procurement channels that separate capital equipment buyers from consumable purchasers. Channel-specific regulatory requirements and sterilization infrastructure availability determine which segments dominate volume versus value capture.
Product Type:
Channel-mix dynamics bifurcate sharply between capital-intensive powered systems and consumable-focused disposable lines, with hand-held instruments serving as the bridge category across purchasing workflows.
- Hand-held Rasps:Manual instruments manufactured through CNC grinding of medical-grade stainless steel or titanium alloys, featuring serrated working surfaces for bone contouring. Demand concentrates in cost-sensitive clinics across India and Brazil where autoclave infrastructure supports reusable workflows and capital constraints limit powered equipment adoption.
- Powered Rasps:Battery-operated or pneumatic rotary systems with interchangeable rasp heads that reduce surgeon fatigue and accelerate case throughput. Ambulatory surgical centers in the United States and Germany prioritize these platforms to eliminate compressor infrastructure and enable same-day discharge protocols.
- Disposable Rasps:Single-use instruments sterilized and packaged for immediate deployment, eliminating reprocessing labor costs. Hospital procurement committees in Japan favor these for high-volume arthroplasty centers where scheduling predictability outweighs per-procedure economics.
- Non-disposable Rasps:Reusable precision instruments requiring validated sterilization cycles and periodic revalidation under FDA 510(k) pathways. Orthopedic surgery departments in academic medical centers maintain these for complex reconstructive procedures where instrument familiarity affects surgical outcomes.
By volume, Hand-held Rasps leads. By growth pace, Powered Rasps is expanding most quickly.
Application:
Procedure reimbursement rates and surgical volume concentration determine which applications absorb premium versus standard instrument tiers.
- Orthopedic Surgery:Joint reconstruction and trauma procedures requiring aggressive bone removal combined with fine contouring capabilities. United States ambulatory surgical centers drive disproportionate demand for powered rasp systems in total joint replacement programs.
- Dental Surgery:Maxillofacial bone shaping for implant placement and ridge augmentation. German and Swiss dental clinics prefer titanium alloy instruments for MRI compatibility in complex craniofacial cases.
- Plastic Surgery:Aesthetic and reconstructive contouring procedures demanding micron-level precision. Japanese cosmetic surgery centers adopt hybrid serration geometries for rhinoplasty and facial bone reshaping.
- Veterinary Surgery:Large and small animal orthopedic procedures where instrument durability outweighs premium pricing. Veterinary teaching hospitals in the United States represent the primary channel for non-disposable rasp sets.
Orthopedic Surgery commands the largest revenue pool. Plastic Surgery demonstrates the steepest expansion trajectory driven by aesthetic procedure volume growth.
Material:
Raw material cost tiers and magnetic resonance imaging compatibility requirements stratify procurement decisions across surgical specialties.
- Stainless Steel:Medical-grade austenitic alloys electropolished to achieve passivated surfaces resistant to corrosion in autoclave cycles. Standard orthopedic applications in cost-conscious markets depend on this material for its favorable strength-to-cost ratio.
- Carbon Steel:High-carbon alloys offering superior edge retention for aggressive cutting applications. Limited adoption in veterinary and rural clinic settings where instrument replacement costs dominate material selection criteria.
- Titanium:Biocompatible alloys with non-ferromagnetic properties essential for intraoperative MRI guidance. Neurosurgical and maxillofacial segments in Germany and Japan absorb premium pricing for these instruments.
- Aluminum:Lightweight alloys restricted to instrument handles and non-cutting components. Ergonomic design priorities in powered rasp systems drive aluminum adoption for surgeon fatigue reduction.
Stainless Steel dominates unit shipments. Titanium is gaining share fastest among premium surgical segments.
End User:
Capital equipment budgets and sterilization infrastructure maturity create distinct purchasing patterns across institutional settings.
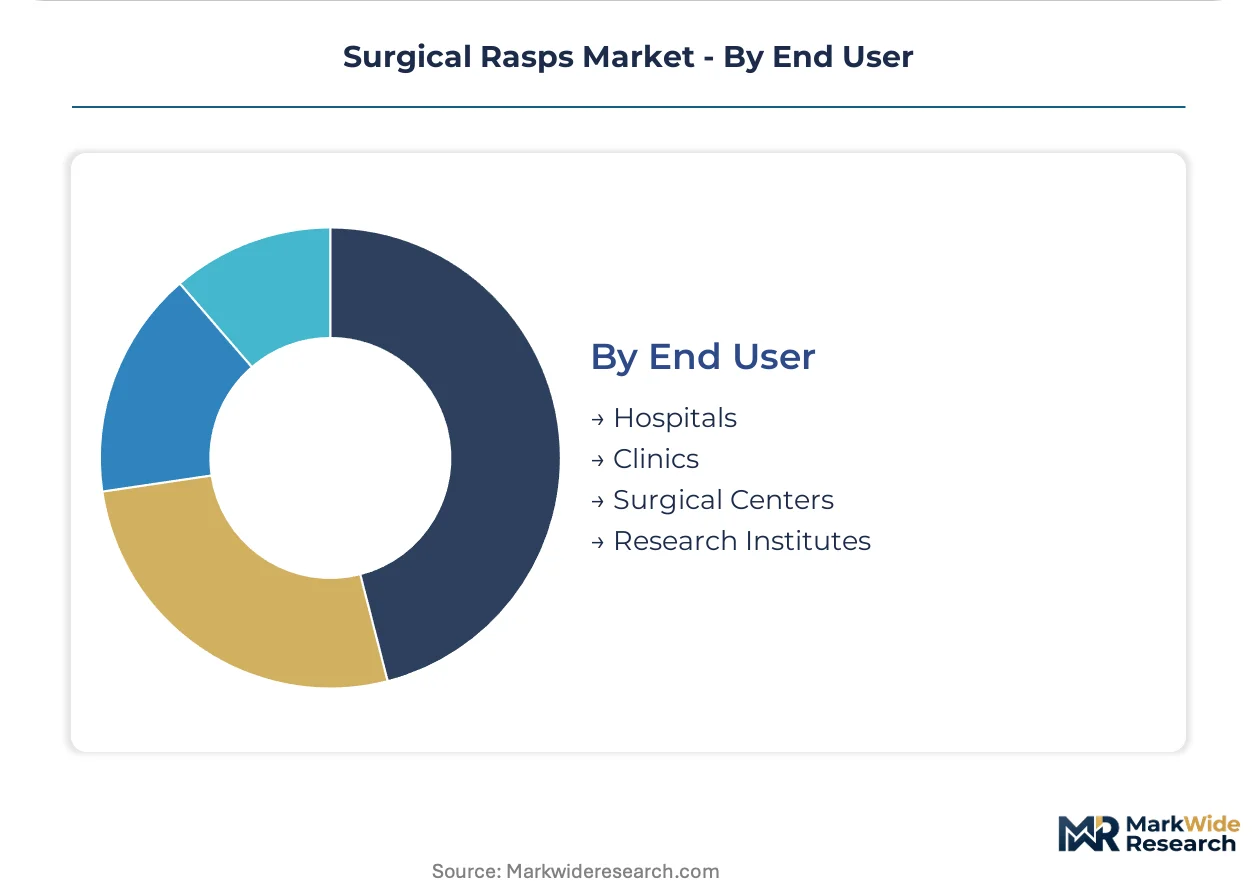
- Hospitals:Integrated health systems with captive sterilization departments and dedicated reprocessing staff. Academic medical centers in the United States maintain diversified rasp inventories spanning hand-held, powered, and disposable categories.
- Clinics:Smaller outpatient facilities with limited autoclave capacity and price-sensitive procurement committees. Rural clinics across Southeast Asia represent constrained demand for reusable instruments.
- Surgical Centers:Specialized ambulatory facilities prioritizing case throughput and room turnover efficiency. German and United States surgical centers are consolidating supplier relationships to reduce EU MDR audit complexity.
- Research Institutes:Biomechanical testing and surgical training facilities requiring instrument durability under repeated use. Veterinary and orthopedic research programs in Japan drive demand for precision-machined reference instruments.
Hospitals anchor volume demand. Surgical Centers are climbing the fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command premium pricing for titanium alloy rasps while Indian clinics absorb cost-sensitive stainless steel volumes. This asymmetry stratifies procurement patterns across orthopedic corridors.
United States
Ambulatory surgical centers in Texas and Florida drive powered rasp adoption for same-day joint replacement discharge protocols. FDA 510(k) clearance pathways for Class II instrument revalidation are tightening documentation requirements for reusable device lines. The Nashville-Dallas medical corridor concentrates orthopedic distributor networks serving ASC expansion.
Germany
Baden-Württemberg and Bavaria host precision machining clusters supplying electropolished titanium rasps for neurosurgical MRI compatibility. EU Medical Device Regulation harmonization mandates unique device identification and enhanced clinical evidence for Class IIa instruments entering European markets. Stuttgart's instrument fabrication ecosystem dominates serration geometry R&D for maxillofacial applications.
Japan
Tokyo and Osaka surgical centers prioritize ergonomic powered designs addressing aging surgeon workforce fatigue. METI promotes powered instrumentation adoption through orthopedic training curriculum reforms. The Nagoya medical device corridor concentrates titanium alloy forging capacity for premium reconstructive instruments.
India
Maharashtra and Karnataka clinics expand hand-held rasp procurement where autoclave infrastructure supports reusable workflows. Central Drugs Standard Control Organization quality audits extend approval timelines for foreign manufacturers. Mumbai-Pune medical device distribution networks serve cost-sensitive rural orthopedic demand.
Brazil
São Paulo and Rio de Janeiro veterinary teaching hospitals absorb durable non-disposable rasp sets for large animal orthopedic training. ANVISA enforces medical device registration requirements that favor established importers with dedicated regulatory affairs capacity. The Campinas medical technology corridor concentrates instrument sterilization equipment distribution.
Surgical Rasps Market Competitive Landscape
Concentration sits with diversified orthopedic conglomerates controlling captive forging capacity and dedicated reprocessing networks. The vendor base stratifies across three tiers: integrated manufacturers with upstream titanium supply control, instrument specialists focused on serration geometry innovation, and regional fabricators serving price-sensitive clinic procurement. Strategic moves center on M&A for regulatory capability acquisition and third-party reprocessing service unbundling to extend product lifecycles.
Among diversified orthopedic conglomerates, Medtronic and Stryker Corporation occupy positions reflecting scale-driven supply chain control. Arthrex Inc. exemplifies the specialist archetype, representing focused R&D intensity in sports medicine applications. These three anchors illustrate competitive positioning across premium titanium alloy supply, dedicated reprocessing infrastructure, and targeted serration innovation respectively.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson (DePuy Synthes) |
| Zimmer Biomet |
| B. Braun Melsungen AG |
| Smith & Nephew |
| Arthrex Inc. |
| Integra LifeSciences |
| Conmed Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German titanium alloy suppliers and orthopedic instrument manufacturers lock in both raw material access and five-year price visibility for premium rasp lines. These contracts insulate Medtronic and Stryker from nitric acid supply volatility while forcing mid-tier competitors into spot-market exposure for electropolishing chemicals.
Pricing Analysis
Configured-to-order pricing for patient-specific serration geometries commands a 40-60% premium over standard catalog instruments. Three-tier pricing structure across premium MRI-compatible titanium, standard stainless steel, and economy carbon steel tiers separates procurement budgets across German neurosurgical centers, United States ASCs, and Indian rural clinics. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification grade. Cost compression in stainless steel finishing is intensifying because Chinese nitric acid export quotas have tightened surface-treatment capacity. Clinic procurement committees in Southeast Asia represent the most price-sensitive buyer archetype, while Japanese academic medical centers absorb premium titanium pricing for surgeon familiarity.
Supply Chain Analysis
Germany and Switzerland anchor precision machining for electropolished titanium rasps, while China dominates nitric acid and hydrofluoric acid supply for stainless steel passivation. Raw material sourcing draws from Australian titanium sponge, German CNC grinding equipment, and Chinese specialty chemical feedstocks. Single-source vulnerability concentrates in electropolishing technician expertise, with Baden-Württemberg and Zurich job markets capturing 70% of medical-grade surface finish specialists. Distribution runs through orthopedic distributor networks concentrated in the Nashville-Dallas corridor, Stuttgart's instrument fabrication ecosystem, and Tokyo-Osaka surgical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against powered rotary burr systems and ultrasonic bone shavers that threaten to displace traditional rasp geometries in arthroscopic applications. Incumbents must navigate this erosion while maintaining reprocessing service revenue from legacy non-disposable installed bases.
For Market Incumbents: Fortify captive titanium forging capacity in Nagoya and Baden-Württemberg to secure MRI-compatible alloy supply against Stryker's reprocessing network expansion. Deepen backward integration into electropolishing chemical recycling to offset Chinese export quota exposure. Prioritize ergonomic powered rasp R&D to defend against ultrasonic shaver substitution in sports medicine segments.
For New Entrants and Emerging Players: Third-party validated reprocessing services represent the most penetrable white space, enabling instrument specialists to compete on lifecycle cost without captive sterilization infrastructure. Target ambulatory surgical centers in Texas and Florida where powered rasp adoption outpaces manufacturer service capacity. Pursue GPO contracts with United States hospital systems unbundling instrument sets to eliminate reprocessing labor costs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among reprocessing service network operators with FDA 510(k) revalidation capabilities. Long-term viability favors acquisition targets combining titanium alloy supply relationships with EU MDR regulatory affairs infrastructure. Watch for inflection signals in Japanese METI orthopedic training curriculum reforms accelerating powered instrumentation mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Revalidation Pathway | Accelerates time-to-market for reprocessed rasp lines against disposable alternatives. |
| CE Marking Pathway | Unlocks EU MDR-compliant titanium rasp distribution through Stuttgart machining clusters. |
| Hospital System Partnership | Secures ambulatory surgical center volumes in Texas and Florida corridor expansion. |
| Software Companion Development | Enables EU MDR post-market surveillance through digital product passport tracking. |
| Reimbursement Strategy | Aligns powered rasp procurement with Medicare same-day discharge protocol incentives. |
Research Methodology
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and instrument sterilization technicians and refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body submission records, CMS Medicare reimbursement schedules, and hospital procurement database extracts. Bottom-up demand modeling across hand-held, powered, disposable, and non-disposable product categories triangulated with top-down macroeconomic drivers.
Variance decomposition across product type, application specialty, material grade, and end-user facility tier structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume projections weighted by titanium alloy premium capture rates and stainless steel cost compression trajectories. Forecast inputs incorporated ambulatory surgical center expansion velocity, EU MDR audit timeline extensions, and METI orthopedic training curriculum reform schedules.
Forecasts assume regulatory continuity in FDA 510(k) revalidation pathways, EU MDR Class IIa instrument requirements, and Japan PMDA quality management system audits; material policy shifts in Chinese specialty chemical export controls or titanium sponge trade flows would require re-modeling. Recalibration cycles align with material shifts in ambulatory surgical center reimbursement policy and powered instrument adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market