
 India Spinal Surgery Devices Market | 2026-2036
India Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Spinal Surgery Devices Market Foresight
CDSCO's 2017 Medical Device Rules is repositioning import licensing and post-market surveillance requirements for spinal implants. Medtronic PLC leverages its Chennai distribution hub to sustain direct hospital contracts across South India. Stryker Corporation anchors its competitive stance through specialized training institutes for surgeons in tier-2 cities. Zimmer Biomet differentiates via titanium interbody cage portfolios tailored to Indian lumbar fusion protocols.
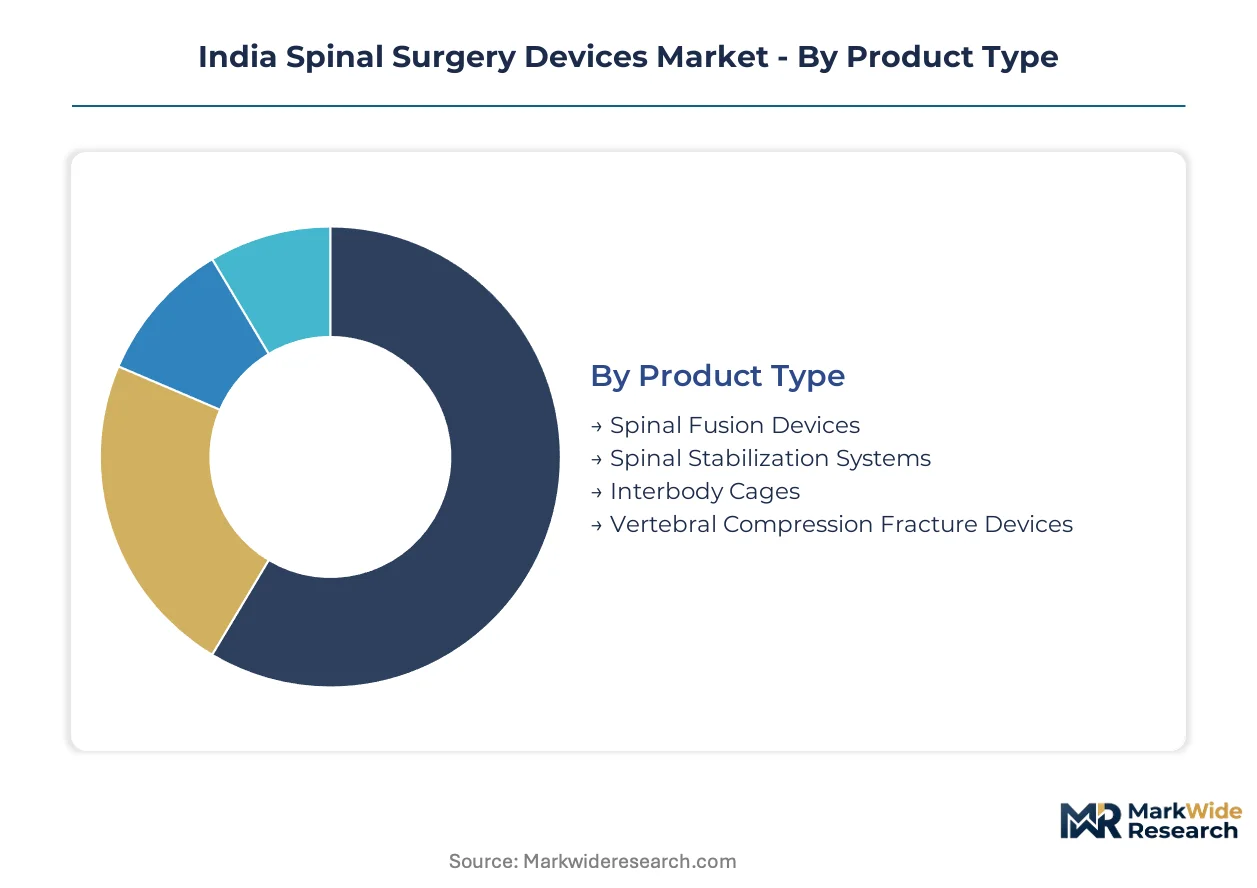
India spinal surgery devices encompass implantable hardware and instrumentation designed to restore vertebral alignment, decompress neural elements, or achieve arthrodesis, typically manufactured from titanium alloys or polyetheretherketone composites with surface modifications to promote osseointegration. These systems serve orthopedic and neurosurgical interventions for degenerative disc disease, trauma, and deformity correction. Spinal fusion devices occupy the largest revenue pool given reimbursement familiarity and surgeon training depth, while interbody cages in titanium represent the fastest-expanding material-format combination due to radiolucency and modulus-matching advantages. Vertebral compression fracture devices remain comparatively nascent, with kyphoplasty balloon systems seeing selective uptake in corporate hospital chains.
BIS certification requirements for metallic implants and CDSCO's risk-based device classification create layered compliance obligations that favor established multinationals with regulatory affairs infrastructure. The PLI scheme for medical devices manufacturing is gradually shifting procurement preferences toward domestically assembled stabilization systems. Stakeholders must monitor state-level hospital procurement tenders where centralized purchasing is consolidating vendor rosters and reshaping channel economics.
Market Dynamics
CDSCO's 2017 Medical Device Rules and subsequent amendments are compressing import licensing timelines while expanding post-market surveillance obligations, forcing distributors to restructure compliance infrastructure around risk-based device classifications.
Growth Catalysts
- PLI Scheme for Medical Devices:Domestic manufacturing incentives are drawing assembly operations for spinal stabilization systems to Gujarat and Karnataka, reducing landed cost disadvantages against imports.
- Minimally Invasive Surgery Expansion:Tier-1 hospitals in Mumbai and Delhi are retrofitting operating theaters with navigation-enabled suites, expanding addressable procedure volumes for percutaneous fixation.
- Neurosurgery Residency Pipelines:Maharashtra and Karnataka training programs are graduating specialists trained in deformity correction techniques, expanding the surgeon base capable of complex fusion procedures.
Market Restraints
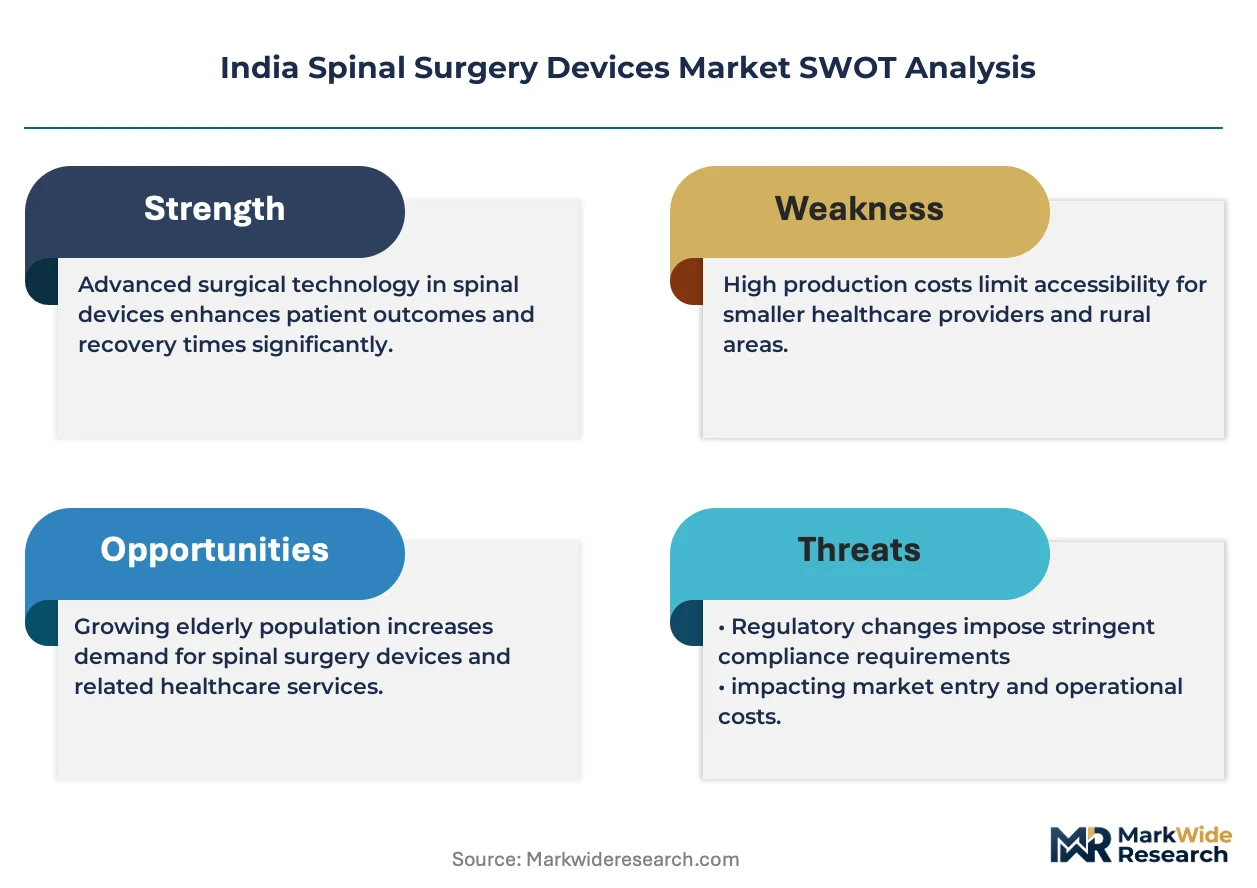
- BIS Certification Delays:Metallic implant testing at designated laboratories creates 8-12 month approval bottlenecks for new titanium alloy formulations.
- Import Dependency for PEEK:Polyetheretherketone interbody cages rely on polymer feedstock from European and East Asian suppliers, exposing margins to currency volatility.
- Reimbursement Gaps:Public insurance schemes exclude kyphoplasty balloons and motion-preservation devices, restricting volumes to self-pay and corporate hospital segments.
Strategic Opportunities
- Tier-2 City Penetration:Nagpur, Kochi, and Jaipur are developing spine centers of excellence with government hospital partnerships, creating first-mover advantages for training-focused suppliers.
- Biologics-Device Convergence:Demineralized bone matrix combined with titanium cages is gaining traction in lumbar fusion protocols, opening adjacent revenue streams.
- Centralized Procurement Tenders:State-level hospital purchasing consortia in Tamil Nadu and Telangana are consolidating vendor rosters, favoring suppliers with local assembly and service infrastructure.
Industry Challenges
- Biomedical Engineer Shortage:Implant inventory management and sterilization protocol optimization require specialized technicians that hospital chains struggle to retain.
- Surgeon Training Standardization:Variable cadaveric lab access across residency programs produces inconsistent technique adoption curves for navigation-assisted placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Spinal Surgery Devices Market |
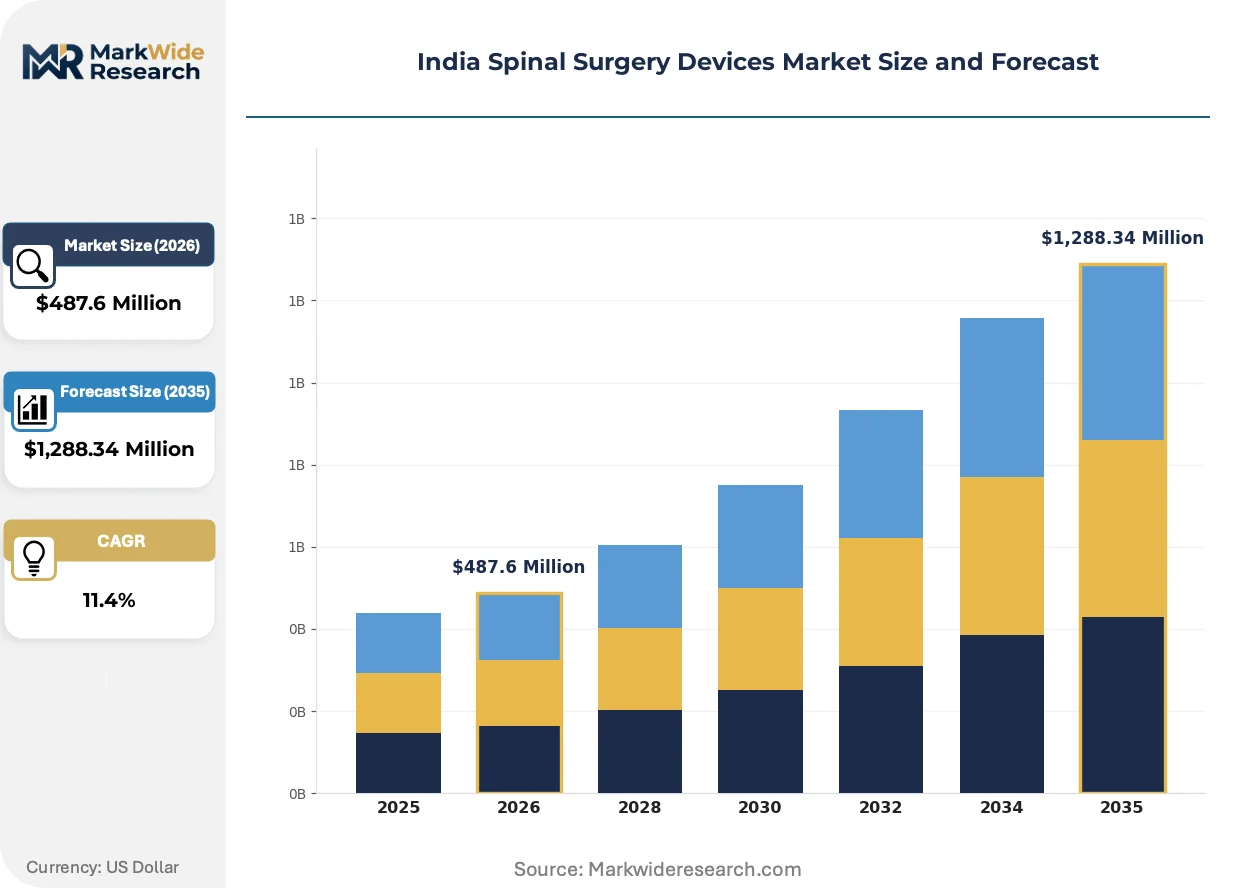
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Fusion Devices, Spinal Stabilization Systems, Interbody Cages, Vertebral Compression Fracture Devices End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Surgical Centers Distribution Channel: Direct Sales, Distributors, Online Channels, Medical Device Retailers Material: Titanium, Biocompatible Polymers, Stainless Steel, Ceramic |
| Companies Covered | Medtronic PLC, Stryker Corporation, Zimmer Biomet, Globus Medical Inc, DePuy Synthes (Johnson & Johnson), Smith & Nephew PLC, Orthofix Medical Inc, Matrix Meditec Pvt Ltd, S H Pitkar Orthotools Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Spinal Surgery Devices Market Shifts & Advancements
Navigation and robotics are compressing the learning curve for complex deformity correction while CDSCO's quality enforcement is elevating documentation standards across the supply chain.
Robot-assisted pedicle screw placement is electrifying surgical workflows in corporate hospital chains. Apollo and Max Healthcare systems are deploying spine navigation platforms across Delhi-NCR and Hyderabad units. This technology is electrifying competitive positioning by enabling marketing of sub-millimeter accuracy claims to informed patients.
CDSCO's tightened post-market surveillance under the 2017 Medical Device Rules is mandating adverse event reporting for Class C and D implants. Importers must now maintain vigilance databases with 72-hour serious incident notification timelines. Spinal fusion hardware categories are responding with investments in traceability systems and complaint-handling infrastructure.
Corporate hospital chains are unbundling implant procurement from surgeon preference cards. Centralized value analysis committees in Mumbai and Bengaluru are standardizing cage and screw specifications across orthopedic and neurosurgical departments. This consolidation is most visible in Maharashtra, where Fortis and Aster DM facilities have reduced active vendor counts by half since 2022.
India Spinal Surgery Devices Market Segmentation
Segmentation in the India spinal surgery devices market reveals how capital deployment, regulatory pathways, and surgeon training depth concentrate revenue across distinct product categories. Understanding these divisions exposes where procurement consolidation and technology adoption curves diverge most sharply.
Product Type:
Capital intensity varies dramatically across implant categories, with navigation-enabled systems demanding theater retrofit investments that only corporate hospital chains can absorb.
- Spinal Fusion Devices:These systems incorporate pedicle screws, rods, and cross-connectors machined from titanium alloys to achieve rigid arthrodesis. Demand clusters in Maharashtra and Karnataka where neurosurgery residency programs produce surgeons trained in deformity correction protocols.
- Interbody Cages:Titanium and PEEK constructs restore disc height and promote osseointegration through porous surface architectures. Mumbai and Delhi tier-1 hospitals are retrofitting navigation suites specifically to expand percutaneous cage placement volumes.
- Spinal Stabilization Systems:Dynamic fixation devices preserve motion while limiting segmental instability.
- Vertebral Compression Fracture Devices:Kyphoplasty balloon systems and vertebral augmentation tools address osteoporotic collapse.
Most installed capacity flows through spinal fusion devices. Expansion is steepest in interbody cages.
End User:
Procurement authority and reimbursement access separate end-user tiers, with centralized purchasing consolidating vendor access for the largest facilities.
- Hospitals:Corporate chains in Delhi-NCR and Hyderabad deploy navigation platforms and absorb CDSCO compliance costs through dedicated regulatory affairs teams. Fortis and Aster DM facilities in Maharashtra have halved active vendor counts since 2022 through value analysis committees.
- Orthopedic Clinics:Outpatient settings in tier-2 cities like Nagpur and Jaipur concentrate diagnostic workup and post-operative rehabilitation, referring complex fusion cases to hospital partners.
- Rehabilitation Centers:Post-surgical recovery facilities manage mobility restoration protocols.
- Surgical Centers:Ambulatory settings perform limited decompression procedures.
Hospital procurement committees now dominate volume allocation. Orthopedic clinics are gaining referral leverage fastest.
Distribution Channel:
Channel economics shift with CDSCO's risk-based classification requirements, favoring distributors with vigilance database infrastructure over transactional intermediaries.
- Direct Sales:Medtronic PLC leverages its Chennai distribution hub to sustain direct contracts across South India, bypassing distributor margins while maintaining 72-hour adverse event reporting compliance.
- Distributors:Regional networks handle BIS certification documentation and sterilization protocol training for tier-2 hospital expansions.
- Online Channels:Digital procurement platforms serve consumable and instrument categories.
- Medical Device Retailers:Brick-and-mortar outlets supply external orthotic and bracing products.
Direct sales capture the highest-value implant contracts. Distributor networks are expanding geographic coverage most aggressively.
Material:
Raw material selection determines BIS testing timelines and import dependency exposure, with domestic titanium processing gaining PLI scheme support.
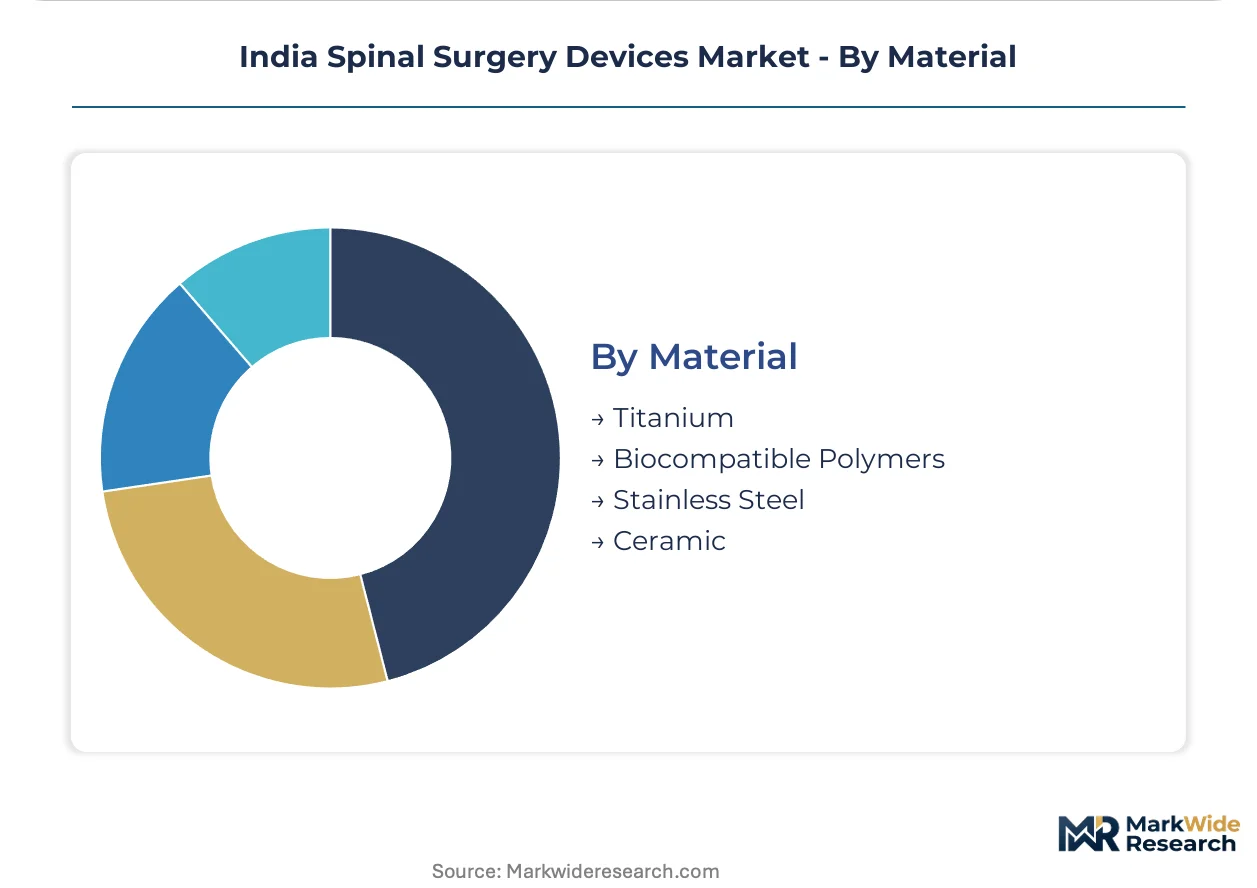
- Titanium:Ti-6Al-4V ELI alloys dominate interbody cage and screw manufacturing, with radiolucency and modulus-matching properties driving surgeon preference. Gujarat and Karnataka assembly operations are reducing landed cost disadvantages through PLI incentives.
- Biocompatible Polymers:PEEK interbody cages rely on European and East Asian feedstock, exposing margins to currency volatility and extended supply chains.
- Stainless Steel:316LVM grades serve cost-sensitive stabilization applications.
- Ceramic:Alumina and zirconia composites address wear-resistant bearing surfaces.
Titanium commands the largest production footprint. Biocompatible polymers are climbing the fastest as cage demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurosurgery residency programs in Maharashtra and Karnataka anchor specialist supply chains, concentrating surgical expertise in western and southern corridors. CDSCO's risk-based device classification and BIS certification requirements reshape procurement economics across state-level hospital networks. Manufacturing incentives under the PLI scheme are drawing assembly operations toward Gujarat and Karnataka.
Maharashtra
Mumbai's tier-1 hospitals retrofit navigation-enabled operating theaters to expand minimally invasive spine volumes. CDSCO's tightened post-market surveillance obligations force corporate chains to maintain dedicated regulatory affairs teams. Fortis and Aster DM facilities in Mumbai and Pune have halved active vendor counts since 2022 through centralized value analysis committees.
Karnataka
Bengaluru's neurosurgery training programs graduate specialists trained in deformity correction protocols, feeding demand for complex fusion hardware. The PLI scheme for medical devices manufacturing attracts spinal stabilization assembly operations to the state's industrial corridors. Corporate hospital chains in Bengaluru deploy robot-assisted pedicle screw placement platforms to differentiate surgical offerings.
Delhi-NCR
Apollo and Max Healthcare systems anchor navigation platform deployment across Delhi-NCR and Hyderabad units, electrifying competitive positioning through accuracy claims. CDSCO's 72-hour serious incident notification timelines for Class C and D implants compel importers to maintain vigilance databases. Centralized procurement consortia in Haryana and Uttar Pradesh reshape channel economics through vendor roster consolidation.
Tamil Nadu
Medtronic PLC leverages its Chennai distribution hub to sustain direct hospital contracts across South India, bypassing distributor margins while maintaining compliance infrastructure. State-level hospital purchasing consortia consolidate vendor access, favoring suppliers with local assembly capabilities. Tier-2 cities including Coimbatore develop spine centers of excellence through government hospital partnerships.
Telangana
Hyderabad's corporate hospital chains absorb capital intensity for navigation-enabled theater retrofits, expanding addressable volumes for percutaneous fixation. Centralized value analysis committees standardize cage and screw specifications across orthopedic and neurosurgical departments. Biologics-device convergence opportunities emerge as demineralized bone matrix combined with titanium cages gains traction in lumbar fusion protocols.
India Spinal Surgery Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across implant and instrumentation categories, producing a tiered market structure. Multinational corporations with established regulatory affairs infrastructure capture high-value contracts in tier-1 hospital chains. Three archetypes dominate: integrated orthopedic conglomerates with broad trauma and spine portfolios, dedicated spine pure-plays with surgeon training ecosystems, and domestic assemblers leveraging PLI scheme incentives. Competitive moves concentrate on M&A for technology access and geographic expansion through state-level tender participation.
Among multinational anchors, Medtronic PLC, Stryker Corporation, and Zimmer Biomet occupy positions representing integrated orthopedic conglomerates with regulatory scale advantages. Medtronic exemplifies direct distribution architecture through its Chennai hub. Stryker represents surgeon training-focused positioning in tier-2 city penetration. Zimmer Biomet anchors titanium interbody cage specialization aligned with Indian lumbar fusion protocols. Domestic specialists including Matrix Meditec Pvt Ltd and S H Pitkar Orthotools Pvt Ltd sit within the PLI-leveraged assembler tier, competing on landed cost and state tender compliance.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Zimmer Biomet |
| Globus Medical Inc |
| DePuy Synthes (Johnson & Johnson) |
| Smith & Nephew PLC |
| Orthofix Medical Inc |
| Matrix Meditec Pvt Ltd |
| S H Pitkar Orthotools Pvt Ltd |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between CDSCO-registered Class C implants and unregistered alternatives splits procurement economics across Maharashtra and Karnataka hospital networks. Tier-1 corporate chains absorb BIS testing premiums through centralized value analysis committees, while tier-2 facilities face 8-12 month approval bottlenecks that compress margin structures for distributors serving price-sensitive government tenders.
Pricing Analysis
Bundled surgeon training contracts versus unbundled hardware-only transactions define the dominant pricing split. CDSCO registration tier and BIS certification status drive price differentiation, with navigation-enabled systems commanding premiums over conventional instrumentation. Pricing pressure stems from PLI scheme incentives drawing domestic assembly operations to Gujarat and Karnataka, eroding import cost disadvantages. Government hospital procurement committees exhibit highest price sensitivity; corporate chains with dedicated regulatory affairs teams demonstrate lowest sensitivity to certification premiums.
Supply Chain Analysis
Single-source vulnerability sits with European and East Asian suppliers of PEEK polymer feedstock for interbody cage manufacturing. Raw material sourcing draws from Germany, Switzerland, and South Korea for titanium alloy billet, while polymer feedstock centers on Belgium and Japan. Currency volatility exposure compounds regulatory restriction risk through CDSCO's 72-hour adverse event reporting mandates. Distribution runs through Medtronic's Chennai hub for direct hospital contracts, with regional distributors handling BIS documentation for tier-2 expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as surgeon training depth and navigation platform deployment shift demand toward premium specifications. CDSCO's tightened post-market surveillance elevates compliance costs that favor established players with vigilance infrastructure.
For Market Incumbents: Cement regulatory scale advantages by expanding Chennai and Bengaluru distribution hubs to absorb CDSCO compliance costs in-house. Deepen backward integration into titanium processing through PLI-linked Gujarat assembly partnerships, countering margin compression from domestic entrants. Prioritize surgeon training institute investments in Nagpur and Kochi to lock in tier-2 referral networks before competitor penetration.
For New Entrants and Emerging Players: Launch via state-level hospital procurement consortia in Tamil Nadu and Telangana, where vendor roster consolidation creates entry points for locally assembled stabilization systems. Target vertebral compression fracture devices, the most underpenetrated category with kyphoplasty balloon volumes restricted to self-pay segments. Pursue biologics-device convergence angles, combining demineralized bone matrix with titanium cages to differentiate in lumbar fusion protocols.
For Investors and Strategic Acquirers: Consolidation pressure builds where PLI scheme beneficiaries achieve BIS certification scale faster than multinational regulatory affairs teams can adapt. Five-to-ten year viability favors domestic assemblers with state tender compliance infrastructure and surgeon training partnerships. Watch for inflection where centralized procurement consortia in Maharashtra and Karnataka reduce active vendor counts below sustainable thresholds, triggering acquisition premiums for remaining independents.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Pathway Investment | Accelerates market access for Class C and D spinal implants through streamlined licensing. |
| Surgeon Training Institute Partnership | Locks in procedure volume commitments from tier-2 city spine centers in Nagpur and Jaipur. |
| PLI-Linked Domestic Assembly | Reduces landed cost disadvantages against imports through Gujarat and Karnataka operations. |
| Navigation Platform Hospital Deployment | Differentiates corporate chains in Delhi-NCR through sub-millimeter accuracy marketing claims. |
| Biologics-Device Combination Development | Opens adjacent revenue streams in lumbar fusion through demineralized bone matrix integration. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Delhi-NCR, Tamil Nadu, and Telangana, with primary inputs from each region's neurosurgery residency programs and hospital procurement committees. The analysis combines interviews with orthopedic surgeons, biomedical engineers, GPO contracts managers, and CDSCO regulatory affairs leads with secondary validation from CDSCO medical device registration databases, state hospital tender records, and PLI scheme beneficiary disclosures. Bottom-up procedure volume estimates triangulate against top-down implant shipment data from BIS certification records.
Granularity-level modeling deploys product-type segmentation at the SKU level for fusion devices, interbody cages, and stabilization systems, with material-grade splits for titanium versus PEEK constructs. End-user modeling separates corporate hospital chains, government facilities, and orthopedic clinics across tier-1 and tier-2 city classifications. CAGRs derive from surgical procedure growth rates cross-referenced against implant penetration assumptions, with navigation platform deployment curves and PLI scheme capacity buildouts as key forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CDSCO enforcement intensity shifts and rupee volatility against euro-denominated PEEK feedstock contracts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market