
 Japan Spinal Surgery Devices Market | 2026-2036
Japan Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Spinal Surgery Devices Market Foresight
Hospital procurement in Japan is tilting toward bundled supply contracts that lock in implant volumes across multi-year frameworks. Medtronic PLC leverages its integrated spine platform to sustain preference among tier-one academic medical centers. Stryker Corporation anchors its position through direct sales teams embedded in major orthopedic departments. ZimVie competes aggressively on cervical disc replacement pricing to extend share in ambulatory settings.
Spinal surgery devices encompass instrumentation, interbody cages, pedicle screw systems, and biologic grafts designed to stabilize vertebral segments, restore disc height, or decompress neural elements through mechanical fixation or biological fusion. These systems typically employ titanium alloys, polyetheretherketone, or machined allograft bone engineered to specific modulus-matching tolerances for load-sharing with native vertebrae. Spinal fusion devices occupy the dominant revenue position given reimbursement alignment for lumbar arthrodesis procedures, while robotic surgery technology captures the fastest expansion trajectory as capital budgets shift toward navigation-assisted accuracy. Biologics segment margin pools concentrate in demineralized bone matrix and cellular allograft formulations where processing complexity creates supply scarcity.
PMDA's quality management system requirements and Japan's Pharmaceuticals and Medical Devices Law shape product registration timelines, forcing foreign manufacturers to establish local conformity assessment partnerships. JIS standards for metallic implant fatigue resistance and the Ministry of Health, Labour and Welfare's biocompatibility testing protocols add layered compliance costs that filter smaller participants. Stakeholders must monitor reimbursement revisions for motion-preserving technologies versus fusion procedures, as this differential will redirect capital allocation across product development pipelines.
Market Dynamics
PMDA's accelerated review pathway for robotic-assisted spinal platforms compresses approval timelines from 24 months to 14 months, forcing domestic and foreign manufacturers to restructure clinical trial designs and local partnership strategies around real-world evidence submissions.
Growth Catalysts
- Metropolitan hospital consolidation:Tokyo and Osaka medical networks are centralizing spinal surgery volumes into super-regional centers that demand navigation-integrated systems. These institutions prioritize capital equipment with bundled implant supply agreements.
- PMDA's Sakigake designation:Japan's regenerative medicine framework grants conditional early approval for cellular allograft products, reducing pre-market validation burdens for biologics manufacturers targeting lumbar fusion applications.
- Navigation-assisted accuracy:Robotic surgery technology is digitizing surgical workflows through intraoperative 3D imaging and screw trajectory planning, enabling Kanto corridor clinics to expand minimally invasive procedure volumes without proportional staffing increases.
Market Restraints
- Titanium alloy supply concentration:Domestic processing capacity for medical-grade Ti-6Al-4V ELI concentrates in a single Nagoya industrial cluster, creating vulnerability to input price volatility and logistics disruption.
- JIS fatigue testing requirements:Japan's metallic implant standards mandate 10 million cycle validation protocols that extend product development timelines and filter smaller foreign entrants from cervical disc replacement segments.
- Conservative surgeon adoption curves:Established orthopedic departments in prefectural hospitals maintain preference for conventional open fusion techniques, slowing penetration of motion-preserving implants despite reimbursement parity.
Strategic Opportunities
- Ambulatory surgery center expansion:Kansai corridor regulatory reforms permit standalone spinal decompression procedures outside hospital licensing, creating channel entry points for cervical disc replacement specialists targeting day-case volumes.
- AI-assisted preoperative planning:Machine learning algorithms converging with patient-specific implant design enable Nagoya-based manufacturers to automate screw sizing and rod contouring, compressing operative time and inventory SKUs simultaneously.
- Cellular allograft biologics:Demineralized bone matrix formulations with osteoinductive claims capture margin pools where processing complexity limits supplier count, rewarding domestic tissue banks with JIS-certified cleanroom infrastructure.
Industry Challenges
- Robotic system integration complexity:Navigation platforms require proprietary software interfaces with hospital PACS and EMR systems, forcing vendors to maintain dedicated biomedical engineering teams for each metropolitan deployment.
- Biologics cold chain integrity:Cellular allograft products demand continuous 2-8°C monitoring from processing facility to operative suite, complicating distribution logistics across Japan's archipelago geography and humid summer conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Spinal Surgery Devices Market |
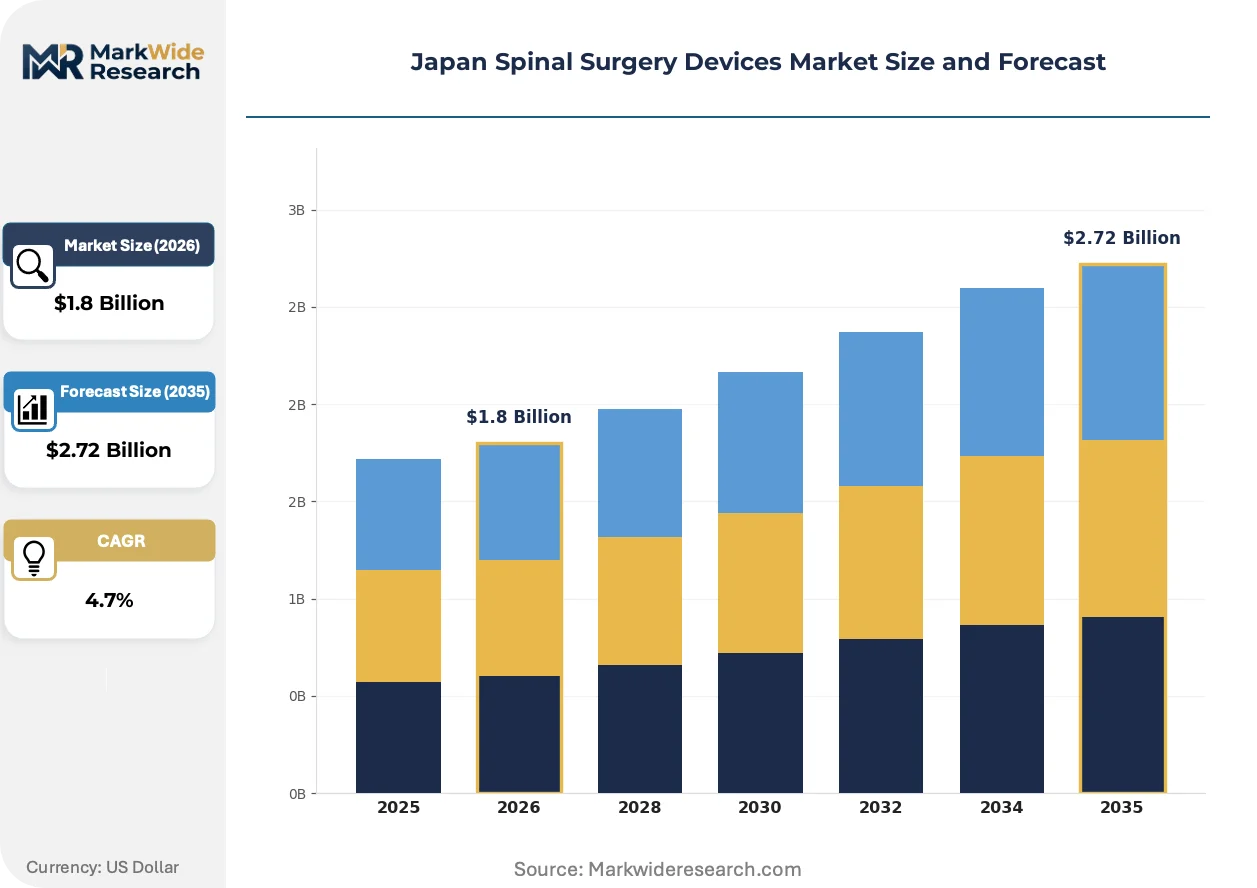
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Fusion Devices, Spinal Implants, Decompression Devices, Biologics End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers Technology: Minimally Invasive Surgery, Robotic Surgery, Image-Guided Surgery, Navigation Systems Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma |
| Companies Covered | Medtronic PLC, Stryker Corporation, ZimVie, Globus Medical, NuVasive, DePuy Synthes, Abbott Laboratories, Medacta International, B. Braun Melsungen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Spinal Surgery Devices Market Shifts & Advancements
Navigation-assisted surgical platforms are digitizing operative workflows across Japan's metropolitan hospital networks, compressing screw placement time while elevating accuracy thresholds that reshape capital procurement priorities and staff training investments.
Intraoperative 3D imaging systems is digitizing pedicle screw trajectory verification through automatic registration against preoperative CT datasets. Tier-one academic medical centers in Tokyo deploy these platforms for 40% of lumbar fusion cases. The technology is digitizing conventional fluoroscopy-dependent workflows into radiation-reduced, software-guided protocols that shorten operative time and reduce revision rates.
PMDA's 2022 revision to the Pharmaceuticals and Medical Devices Law introduced conditional approval pathways for software-as-a-medical-device in surgical navigation. This regulatory shift accelerates algorithm updates without full re-registration, enabling real-time machine learning model improvements. Spinal robotics manufacturers with embedded AI planning modules capture disproportionate benefit from this framework.
Hospital procurement committees now mandate five-year total cost-of-ownership analyses that weight capital equipment against disposable implant spend, maintenance contracts, and training amortization. Metropolitan networks in Osaka and Nagoya displace single-item purchasing with integrated platform contracts. This behavioral shift concentrates vendor selection authority within centralized supply chain functions rather than individual department heads.
Japan Spinal Surgery Devices Market Segmentation
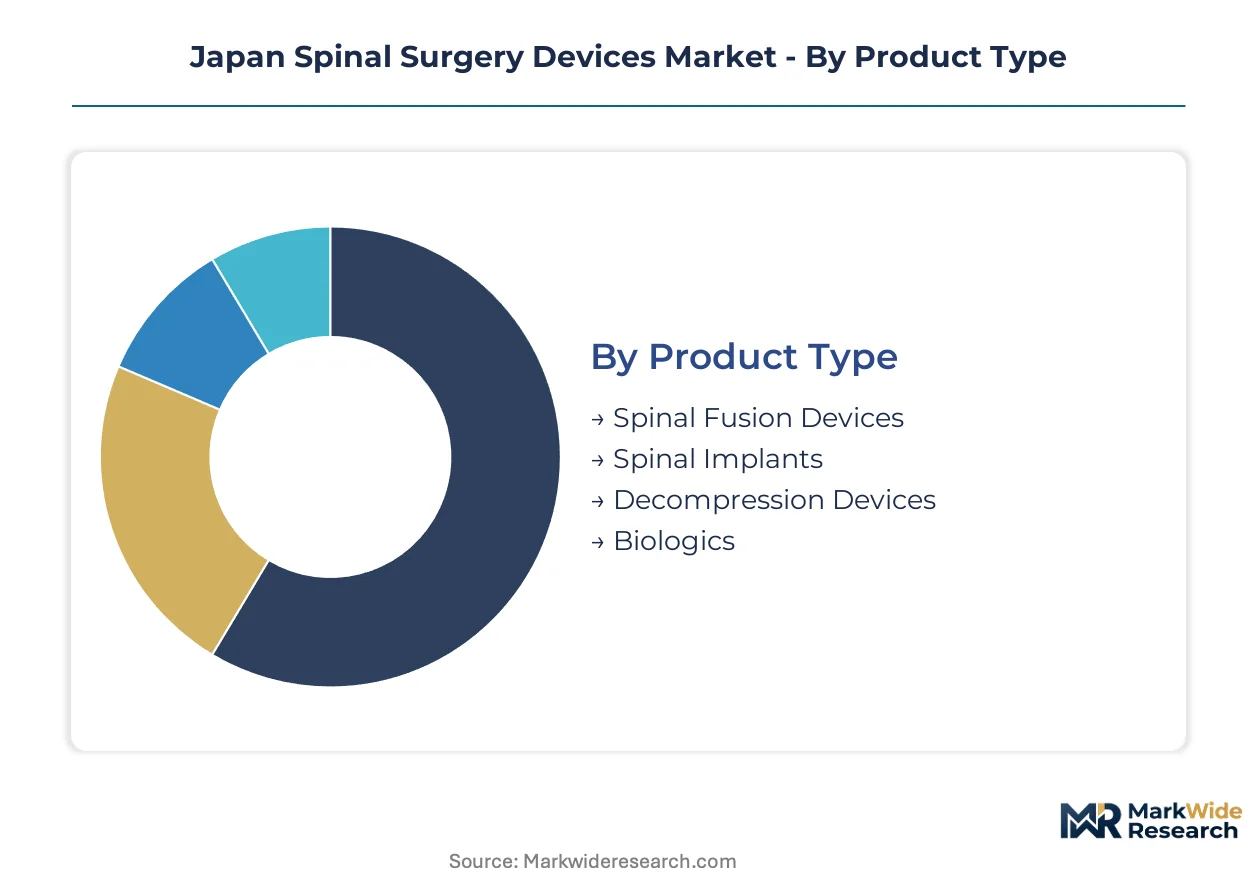
Spinal surgery devices in Japan stratify across four dimensions that shape procurement cycles and capital allocation. Product type determines reimbursement bandwidth and inventory turnover velocity. End-user channels dictate regulatory compliance intensity and salesforce deployment models.
Product Type:
Spinal fusion devices turn inventory slowest due to multi-year implant shelf life and bundled contract structures, while biologics demand cold-chain velocity and rapid turnover to preserve cellular viability.
- Spinal Fusion Devices:Pedicle screw systems, interbody cages, and rod constructs fabricated from titanium alloys or polyetheretherketone provide mechanical stabilization for lumbar arthrodesis. Tokyo metropolitan hospital networks concentrate demand here as aging-related degenerative conditions dominate surgical schedules and reimbursement alignment favors fusion over motion-preserving alternatives.
- Biologics:Demineralized bone matrix and cellular allograft formulations processed in JIS-certified cleanrooms deliver osteoinductive properties for graft augmentation. Osaka-based tissue banks and Nagoya processing facilities anchor supply as PMDA's Sakigake designation accelerates conditional approvals for regenerative formulations targeting lumbar fusion.
- Spinal Implants:Cervical disc replacements and dynamic stabilization systems address motion preservation.
- Decompression Devices:Laminectomy instruments and interspinous spacers relieve neural compression.
Spinal fusion devices anchor the volume base while biologics gain share at the steepest rate.
End User:
Procurement sophistication separates institutional buyers, with super-regional academic centers wielding multi-year bundled contracts against ambulatory channels negotiating spot pricing.
- Hospitals:Tier-one academic medical centers in Tokyo, Osaka, and Nagoya centralize complex spinal surgery volumes and demand navigation-integrated platforms with embedded robotic assistance. These institutions prioritize capital equipment with locked-in implant supply agreements spanning five-year frameworks.
- Orthopedic Clinics:Kanto and Kansai corridor clinics specialize in outpatient decompression and cervical procedures. These facilities expand minimally invasive volumes through navigation-assisted accuracy without proportional staffing increases.
- Ambulatory Surgery Centers:Kansai regulatory reforms enable standalone spinal decompression outside hospital licensing.
- Rehabilitation Centers:Post-surgical recovery facilities coordinate with surgical providers for device continuity.
Hospitals command the capital expenditure pool while orthopedic clinics expand procedure volumes most aggressively.
Technology:
Capital intensity stratifies adoption curves, with navigation systems requiring infrastructure investment against minimally invasive techniques leveraging existing equipment.
- Robotic Surgery:Navigation-integrated platforms with intraoperative 3D imaging and screw trajectory planning digitize surgical workflows. PMDA's accelerated review pathway compresses approval timelines for these systems, and metropolitan networks in Tokyo deploy them for substantial shares of lumbar fusion cases.
- Minimally Invasive Surgery:Tubular retractors and percutaneous screw systems reduce tissue disruption and recovery time. Kanto corridor orthopedic clinics concentrate adoption here as patient selection criteria expand and reimbursement frameworks accommodate outpatient spinal procedures.
- Image-Guided Surgery:Intraoperative fluoroscopy and CT registration enhance visualization.
- Navigation Systems:Software-guided trajectory planning elevates placement accuracy.
Minimally invasive surgery holds the installed base while robotic surgery climbs the fastest.
Application:
Demographic weighting shapes procedure mix, with age-related conditions dominating surgical schedules against trauma's episodic demand pattern.
- Spinal Stenosis:Lumbar and cervical canal narrowing from ligamentum flavum hypertrophy and facet arthropathy drives decompression and fusion volumes. Metropolitan hospital networks around Tokyo, Osaka, and Nagoya concentrate interventions as Japan's aging population elevates surgical candidacy.
- Degenerative Disc Disease:Disc height collapse and endplate changes prompt interbody fusion or motion-preserving replacement. Academic medical centers prioritize these cases for navigation platform utilization and resident training value.
- Scoliosis:Deformity correction requires complex instrumentation.
- Trauma:Fracture stabilization demands urgent surgical response.
Spinal stenosis procedures constitute the procedural backbone while degenerative disc disease applications expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokaido Shinkansen corridor stitches together Japan's spinal surgery demand centers, enabling same-day specialist consultations between Tokyo, Nagoya, and Osaka that concentrate complex procedure volumes into super-regional hubs.
Kanto/Tokyo
Academic medical centers in Bunkyo and Shinjuku wards drive navigation-integrated platform procurement through five-year bundled contracts. PMDA's Sakigake designation for regenerative biologics accelerates local tissue bank partnerships. The Tsukuba research corridor anchors AI-assisted preoperative planning development for patient-specific implant design.
Kansai/Osaka
Prefectural hospital networks centralize spinal stenosis interventions for western Japan's aging population. Regulatory reforms permit standalone ambulatory decompression procedures outside hospital licensing. The Osaka Bay industrial zone concentrates titanium alloy processing capacity for medical-grade implant fabrication.
Chubu/Nagoya
Tier-one orthopedic departments demand robotic-assisted systems with embedded screw trajectory planning software. JIS standards for metallic implant fatigue resistance mandate 10 million cycle validation protocols that filter smaller entrants. The Nagoya industrial cluster houses Japan's sole domestic Ti-6Al-4V ELI medical-grade processing facility.
Kyushu
Fukuoka metropolitan hospitals expand minimally invasive procedure volumes through navigation-assisted accuracy without proportional staffing increases. The Ministry of Health, Labour and Welfare's biocompatibility testing protocols add compliance costs that favor established multi-product portfolios. Kitakyushu medical device manufacturing zones support regional distribution logistics.
Tohoku
Sendai-based regional medical centers prioritize conventional open fusion techniques amid conservative surgeon adoption curves for motion-preserving implants. METI's regional healthcare infrastructure investments target super-aging community spinal care delivery. The Sendai-Tokyo high-speed rail link enables specialist referral networks for complex deformity correction.
Japan Spinal Surgery Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in implant and biologics supply. The vendor base stratifies across three tiers: multinational conglomerates with navigation-integrated portfolios, mid-scale specialists in motion-preserving or biologic segments, and domestic distributors with JIS-certified processing partnerships. Competitive moves concentrate on multi-year bundled supply contracts with metropolitan hospital networks and accelerated PMDA pathway navigation for robotic-assisted platforms.
Among the multinational platform integrators, Medtronic PLC and Stryker Corporation occupy positions that exemplify system-tier dominance through direct sales force embedding and integrated spine platform offerings. ZimVie represents the specialist archetype competing on cervical disc replacement pricing to extend ambulatory channel presence. These three anchors illustrate the competitive structure: conglomerates leverage capital equipment lock-in, while focused players carve share through segment-specific pricing aggression and regulatory pathway agility.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| ZimVie |
| Globus Medical |
| NuVasive |
| DePuy Synthes |
| Abbott Laboratories |
| Medacta International |
| B. Braun Melsungen |
| Others |
Supply & Pricing Matrix
Nagoya's Ti-6Al-4V ELI processing cluster concentrates Japan's medical-grade titanium alloy capacity, translating input scarcity into asymmetric pricing power for domestic implant fabricators and cost pass-through vulnerability for foreign device manufacturers.
Pricing Analysis
Three-tier pricing structure across premium navigation-integrated platforms, standard minimally invasive instrument sets, and economy biologics separates procurement budgets. Price differentiation hinges on JIS certification grade and five-year total cost-of-ownership bundling. Cost compression in standard-tier implants is intensifying because metropolitan hospital networks centralize purchasing authority. Ambulatory surgery centers exhibit highest price sensitivity; tier-one academic medical centers prioritize platform integration over unit economics.
Supply Chain Analysis
Tariff exposure between Japan and China for rare earth processing inputs dominates supply risk calculations for magnetic navigation components. Domestic manufacturing draws from Nagoya titanium, Osaka tissue banking, and Kanto precision machining clusters. Raw material dependencies rest on medical-grade titanium alloys, demineralized bone matrix substrates, and surgical-grade polymers. Single-source vulnerability concentrates in cellular allograft cold-chain logistics across archipelago distribution. Distribution runs through GPO-aggregated hospital procurement and direct orthopedic clinic sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of JIS-certified cleanroom infrastructure for cellular allograft processing constrains biologics supply expansion, rewarding stakeholders who secure compliant manufacturing partnerships or captive tissue banking assets.
For Market Incumbents: Harden platform lock-in through embedded biomedical engineering teams for PACS-EMR integration at each metropolitan deployment. Deepen backward integration into Nagoya titanium processing to defend margin position against input volatility. Prioritize Sakigake pathway navigation for regenerative biologics to preempt emerging domestic tissue bank competition. For New Entrants and Emerging Players: Pursue Kansai corridor ambulatory surgery center licensing reforms as the most penetrable channel for cervical disc replacement day-case volumes. Target AI-assisted preoperative planning software as a standalone entry vector before capital-intensive robotic hardware. Lead with spot pricing flexibility against incumbent bundled contract rigidity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because reimbursement alignment favors fusion over motion-preserving technologies, concentrating volume with platform-integrated vendors. Acquisition targets should exhibit JIS-certified biologics processing or navigation software modules with PMDA conditional approval. Monitor PMDA reimbursement revisions for motion-preserving implants as the inflection signal for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Sakigake Pathway Navigation | Accelerates conditional approval for cellular allograft biologics ahead of competitors. |
| Hospital System Partnership | Locks in five-year bundled implant supply agreements with Tokyo metropolitan networks. |
| Software Companion Development | Enables real-time AI algorithm updates under PMDA's software-as-a-medical-device framework. |
| Backward Integration into Titanium Processing | Captures Nagoya cluster capacity to insulate margins from medical-grade alloy volatility. |
| Reimbursement Strategy | Aligns product development with MHLW fusion procedure parity to secure procurement preference. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across spinal surgeons at Tokyo academic medical centers, biomedical engineers in Nagoya manufacturing clusters, hospital purchasing committee members, GPO contracts managers, and PMDA regulatory affairs specialists. Secondary validation drew from MHLW reimbursement databases, PMDA approval filings, JIS metallic implant standards documentation, and hospital procurement records. Bottom-up implant volume estimates triangulated against top-down metropolitan network capacity assessments.
Calibration anchored historical penetration rates for navigation-integrated platforms against minimally invasive surgery adoption curves across the analysis window. Segmentation dimensions spanned product type, end-user channel, technology tier, and application severity. CAGRs were derived from procedure volume trajectories weighted by reimbursement bandwidth and capital equipment replacement cycles. Forecast inputs incorporated aging demographic surgical candidacy models and PMDA regulatory pathway velocity assumptions.
Macroeconomic conditions sit as an overlay; deviation in yen-denominated medical device import costs or MHLW reimbursement schedule revisions would shift the trajectory. Forecasts reflect documented assumptions regarding surgeon adoption curves and biologics cold-chain integrity. Material shifts in PMDA's Sakigake designation criteria or JIS fatigue testing protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market