
 Veterinary Orthopedic Drills Market | 2026-2036
Veterinary Orthopedic Drills Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Orthopedic Drills Market Analytics
Titanium alloy is hardening its position as the preferred drill bit substrate, displacing traditional stainless steel in premium veterinary orthopedic applications due to superior fatigue resistance and biocompatibility. Arthrex leverages its integrated implant-drill ecosystem to sustain pricing power across academic veterinary hospitals. DePuy Synthes Vet anchors its competitive position through backward integration into surgical power tool manufacturing. KYON differentiates via specialized AO-compatible drill systems for companion animal orthopedics.
Veterinary orthopedic drills are precision rotary instruments engineered for bone preparation in animal fracture repair and joint procedures, typically operating at 800–1,500 RPM with torque modulation to prevent thermal necrosis of surrounding tissue. Electric drills dominate installed base in fixed surgical suites, while battery-powered configurations represent the fastest-growing segment as mobile veterinarians and field surgical units prioritize cordless maneuverability. Wireless technology is displacing tethered power delivery in ambulatory settings, though pneumatic systems retain share in high-torque large-animal applications where sustained cutting force matters.
FDA Center for Veterinary Medicine oversight shapes device classification and 510(k) clearance pathways for powered surgical instruments in the United States, while EU MDR and CE marking requirements govern market access across European veterinary markets. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards constrain material selection and power system design for manufacturers targeting multiple jurisdictions. Stakeholders must monitor how evolving battery chemistry regulations and wireless electromagnetic compatibility standards reshape R&D prioritization and product certification timelines.
Market Dynamics
Battery-powered drill platforms are absorbing procurement priority from tethered pneumatic systems as mobile veterinary surgical units expand their service radius beyond fixed clinic infrastructure.
Growth Catalysts
- EU MDR pathway harmonization:Streamlined CE marking for powered surgical instruments accelerates multi-country market entry for veterinary orthopedic drill manufacturers targeting European specialty clinics.
- Titanium alloy fatigue resistance:Superior material performance in high-RPM bone preparation applications extends instrument lifespan and reduces thermal necrosis risk in companion animal procedures.
- Specialty clinic consolidation:United States veterinary hospital networks are centralizing orthopedic service line investments, creating concentrated demand for integrated drill-implant ecosystems.
Market Restraints
- Lithium-ion battery chemistry volatility:Raw material cost swings and supply concentration in Asian processing facilities compress margin predictability for cordless drill producers.
- IEC 60601 electrical safety certification:Extended validation timelines for wireless power systems delay product launches and freeze R&D capital in regulatory queues.
- Pneumatic infrastructure lock-in:Existing high-torque large-animal surgical suites in Germany and the United States resist full electrification due to sunk capital in compressed air systems.
Strategic Opportunities
- German mobile veterinary expansion:Field surgical units serving equine and farm animal populations present untapped demand for battery-powered drill configurations with extended runtime.
- ISO 10993 biocompatibility premium tier:Certification-driven procurement preferences in academic veterinary hospitals create pricing separation for drill bit substrates with documented cytotoxicity testing.
- Wireless electromagnetic compatibility convergence:Integration of Bluetooth torque monitoring with drill control systems enables real-time bone density adaptation during procedures.
Industry Challenges
- Veterinary orthopedic surgical training pipelines:Limited residency slots and specialized continuing education capacity constrain the installer base for advanced drill platforms.
- 510(k) clearance documentation burden:FDA Center for Veterinary Medicine requirements for substantial equivalence demonstrations consume 18-24 month development cycles.
- Legacy pneumatic-electric integration:Hybrid surgical suites require dual-power drill inventories, complicating sterilization workflows and capital planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Orthopedic Drills Market |
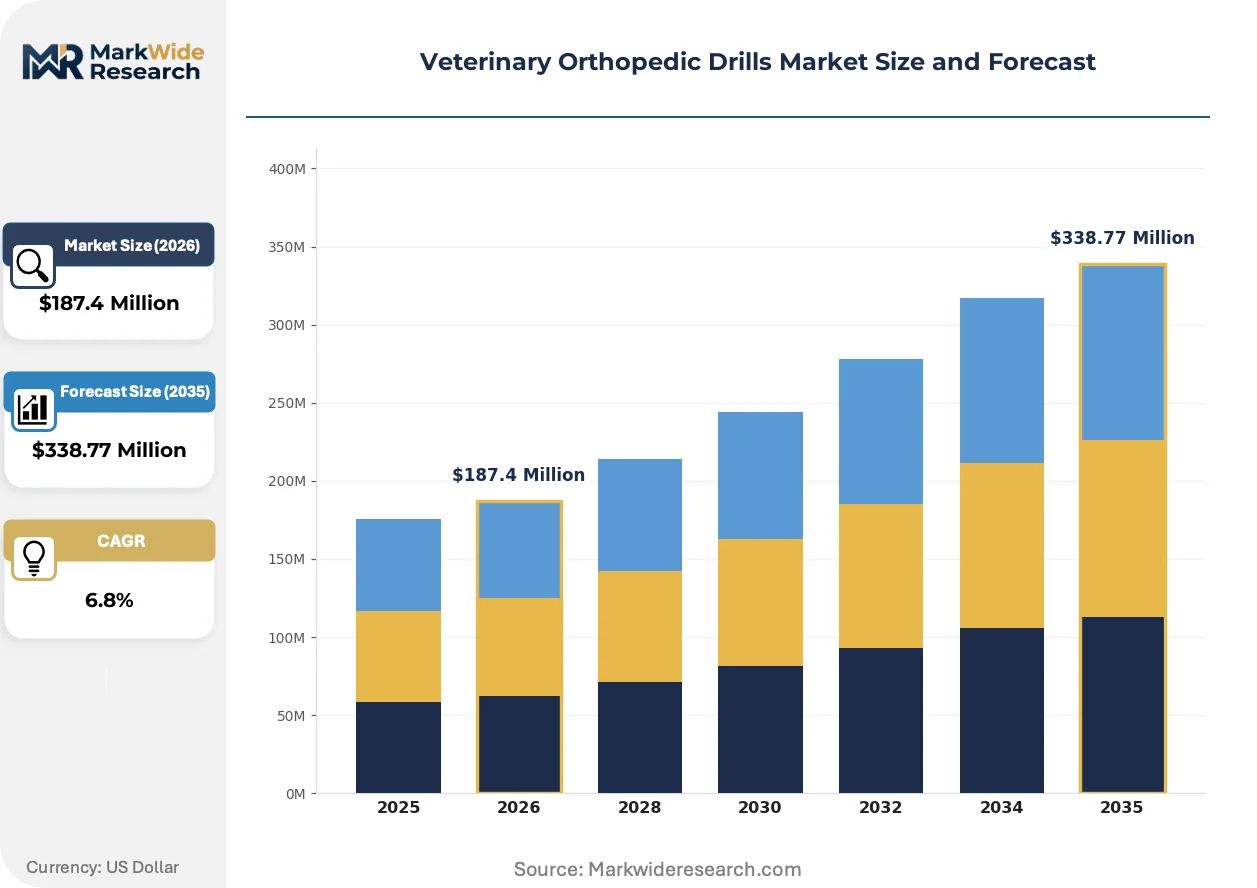
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Drills, Pneumatic Drills, Battery-Powered Drills, Manual Drills Application: Fracture Repair, Bone Cutting, Osteotomy, Screw Insertion End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinarians Technology: High-Speed Drilling, Low-Temperature Technology, Wireless Technology, Rotary Technology |
| Companies Covered | IMEX Veterinary, Surgical Holdings Veterinary, Vet Surgical Resources, Movora, Arthrex, DePuy Synthes Vet, Veterinary Orthopedic Implants, KYON, BioMedtrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Orthopedic Drills Market Evolving Landscape
Active reshaping in veterinary orthopedic drills centers on cordless power density improvements, regulatory harmonization pressures, and procurement centralization among multi-site specialty groups.
Brushless DC motor architectures are absorbing engineering priority in next-generation veterinary drill platforms. These systems deliver higher torque-to-weight ratios at 800-1,500 RPM operating ranges. Mobile surgical units in the United States are adopting them faster than fixed-suite installations. The technology is absorbing service contract value from traditional equipment vendors by enabling longer maintenance intervals and remote diagnostics.
EU MDR Article 10 technical documentation requirements are tightening post-market surveillance obligations for powered surgical instruments. Manufacturers must now maintain systematic clinical data collection across distributed veterinary installations. Battery-powered drill lines with integrated usage logging are capturing regulatory preference in German and French markets.
Consolidated procurement by United States veterinary hospital networks is compressing vendor negotiation cycles. Multi-year equipment standardization agreements are replacing transactional purchasing. Academic veterinary hospitals in California and Texas are piloting subscription-based drill access models that bundle maintenance and consumables.
Veterinary Orthopedic Drills Market Segmentation
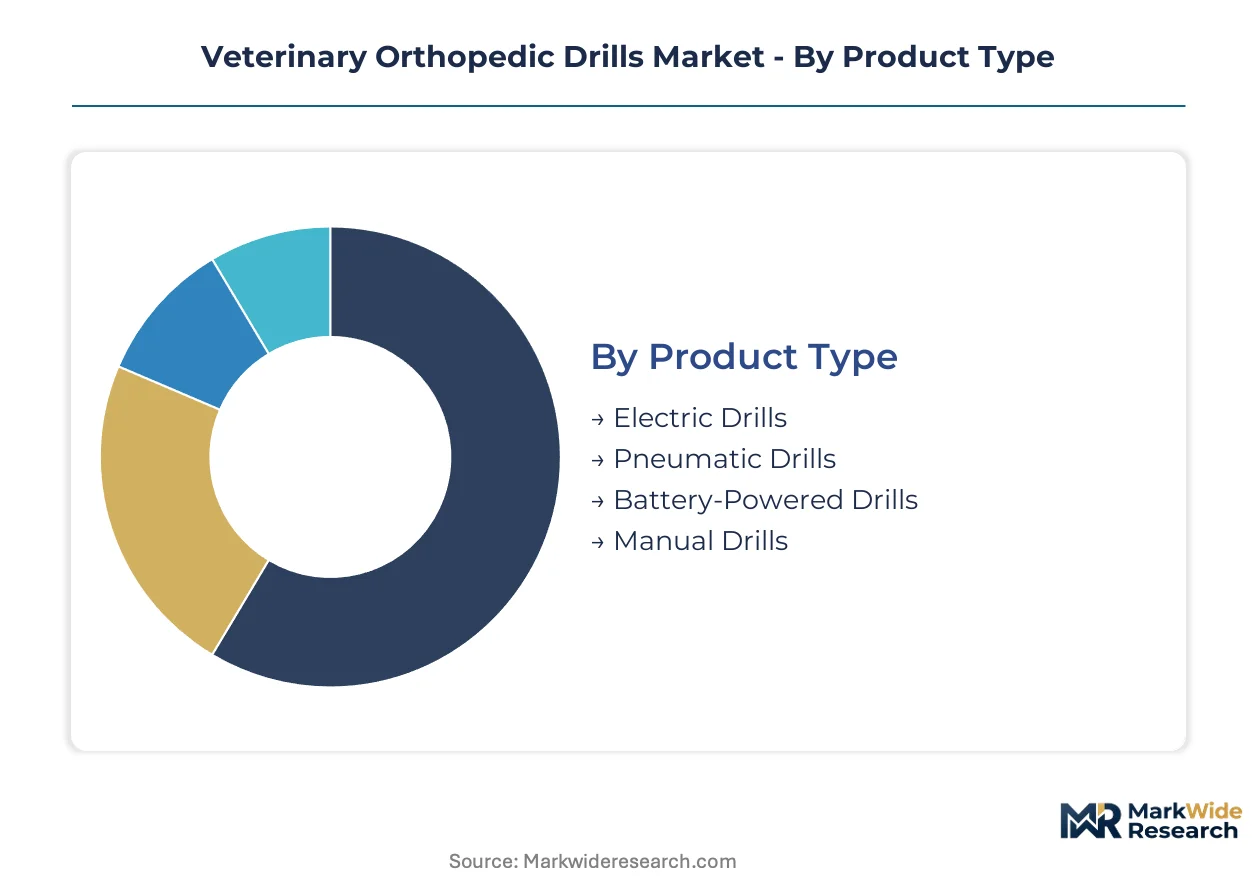
Veterinary orthopedic drill procurement diverges sharply between fixed surgical infrastructure and ambulatory practice models. Each segment category reflects distinct capital deployment patterns, regulatory exposure, and maintenance workflows that shape vendor positioning.
Product Type:
Customization intensity varies from standardized pneumatic platforms to configurable battery-powered systems with modular handpiece attachments.
- Electric Drills:Tethered AC-powered systems deliver sustained torque at 800–1,500 RPM for fixed surgical suites in academic veterinary hospitals. United States specialty clinic networks concentrate procurement here, prioritizing integrated sterilization compatibility and multi-year service contracts over acquisition cost.
- Battery-Powered Drills:Lithium-ion cordless platforms with brushless DC motors achieve torque-to-weight ratios matching tethered systems while enabling field surgical mobility. German equine practitioners and United States mobile veterinarians drive demand, prioritizing extended runtime configurations and rapid-swap battery systems for uninterrupted procedural workflows.
- Pneumatic Drills:Compressed-air systems retain installed base in high-torque large-animal applications where sustained cutting force outweighs maneuverability constraints.
- Manual Drills:Hand-powered instruments serve backup roles in resource-constrained settings and regulatory backup requirements for powered system failures.
Most installed capacity flows through Electric Drills. Expansion is steepest in Battery-Powered Drills.
Application:
Procedure complexity determines power system specifications, with thermal management requirements escalating from simple fixation to complex osteotomy.
- Fracture Repair:Bone plate and screw fixation procedures demand precise RPM control to prevent thermal necrosis in companion animal long-bone surgeries. United States specialty clinics standardize on systems with integrated torque modulation and automatic stall detection.
- Osteotomy:Planned bone resection procedures require sustained high-torque performance with irrigation integration for thermal management in TPLO and TTA cruciate repair. German academic veterinary hospitals drive specification development for these procedures.
- Bone Cutting:Resection and amputation procedures utilize aggressive cutting geometries with enhanced irrigation channels.
- Screw Insertion:Final fixation steps prioritize low-speed, high-torque control for accurate seating without strip-out.
Procedure volume concentrates in Fracture Repair. Technical specification advancement centers on Osteotomy.
End User:
Capital intensity and mobility requirements segment procurement authority across institutional and individual practice models.
- Veterinary Clinics:Independent and network-affiliated specialty practices in the United States consolidate orthopedic service lines, driving multi-unit equipment standardization agreements with integrated maintenance bundling.
- Mobile Veterinarians:Field surgical units serving equine and farm animal populations in Germany and the United States prioritize cordless platforms with extended battery runtime and ruggedized sterilization compatibility.
- Animal Hospitals:Multi-specialty referral institutions maintain hybrid inventories accommodating diverse species and procedure types.
- Research Institutions:Academic veterinary medical centers drive validation protocols and training curriculum development for emerging drill technologies.
Procurement authority concentrates in Veterinary Clinics. Equipment refresh cycles are accelerating among Mobile Veterinarians.
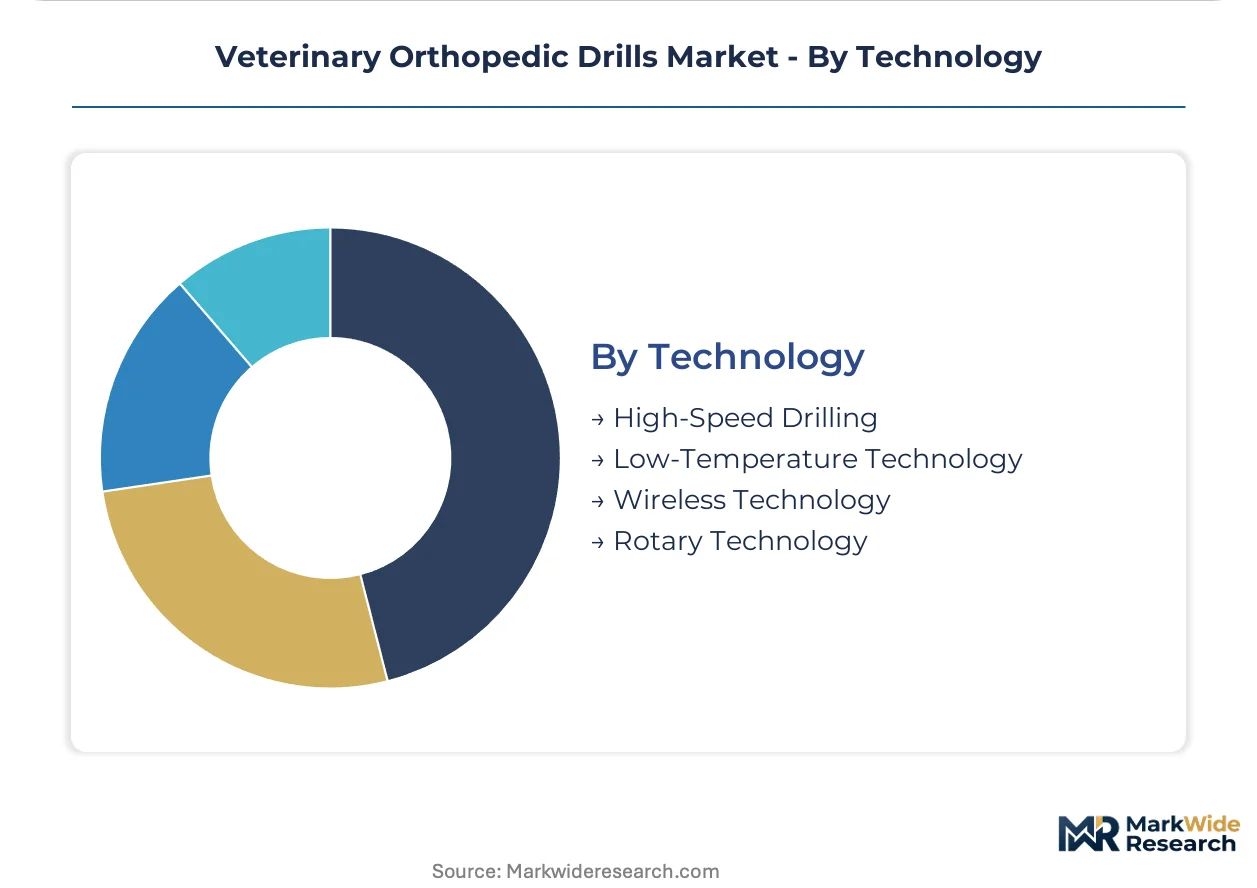
Technology:
Performance differentiation clusters around thermal management and connectivity integration rather than raw power specifications.
- Wireless Technology:Bluetooth-enabled torque monitoring and drill control systems enable real-time bone density adaptation during procedures. United States academic veterinary hospitals pilot these platforms for resident training and outcome documentation.
- Low-Temperature Technology:Advanced irrigation integration and cutting geometry optimization minimize thermal necrosis risk in high-RPM bone preparation. German specialty clinics specify these systems for cruciate repair procedures with strict post-operative mobility protocols.
- High-Speed Drilling:Optimized cutting geometries and motor control algorithms maximize material removal rates in time-constrained procedures.
- Rotary Technology:Standard oscillating and rotating handpiece configurations serve baseline procedural requirements across all user segments.
Adoption penetration is deepest in Low-Temperature Technology. Development investment is concentrating in Wireless Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States specialty veterinary hospital networks concentrate procurement authority for orthopedic power systems. Germany's equine surgical centers drive specification development for high-torque mobile configurations. Academic veterinary medical centers in both markets pilot wireless torque monitoring platforms.
United States
California and Texas academic veterinary hospitals consolidate multi-site equipment standardization agreements for integrated drill-implant ecosystems. FDA Center for Veterinary Medicine 510(k) clearance pathways govern powered surgical instrument market access. The Greater Boston corridor anchors resident training curriculum development for brushless DC motor platforms with remote diagnostic capability.
Germany
Bavarian equine practitioners and Baden-Württemberg specialty clinics absorb battery-powered drill platforms for field surgical mobility. EU MDR Article 10 technical documentation requirements tighten post-market surveillance for powered surgical instruments. The North Rhine-Westphalia industrial cluster hosts precision motor manufacturers supplying torque modulation systems for cruciate repair procedures.
United Kingdom
London and Southeast England referral hospitals standardize on low-temperature irrigation-integrated systems for thermal management. MHRA recognition of EU MDR certificates streamlines CE-marked device importation from continental suppliers. The Midlands corridor concentrates veterinary orthopedic residency programs driving validation protocols for emerging drill technologies.
Japan
Kanto region academic veterinary centers specify titanium alloy drill bit substrates for companion animal fracture repair. PMDA consultation procedures align with ISO 10993 biocompatibility testing requirements for powered surgical instruments. Osaka-based specialty clinics pilot subscription-based equipment access models bundling maintenance and consumables.
Australia
New South Wales and Victoria mobile veterinarians prioritize rapid-swap battery systems for uninterrupted field surgical workflows. TGA medical device regulations incorporate IEC 60601 electrical safety standards for wireless power systems. Brisbane-area equine surgical units absorb extended runtime configurations serving farm animal populations across Queensland.
Veterinary Orthopedic Drills Market Competitive Landscape
Global majors compete with regional champions across integrated implant-drill ecosystems versus specialized surgical power tool manufacturing. The vendor base stratifies into three tiers: diversified orthopedic conglomerates with captive drill production, mid-scale veterinary specialists with AO-compatible system focus, and regional equipment fabricators serving price-sensitive clinic networks. Two strategic archetypes dominate competitive positioning: backward-integrated manufacturers controlling surgical power tool production, and technology licensors partnering with sterilization-compatible component suppliers. M&A activity concentrates on battery chemistry and brushless motor capabilities, while multi-year service contract bundling absorbs procurement negotiation cycles.
Within the diversified orthopedic tier, Arthrex and DePuy Synthes Vet occupy positions exemplifying integrated implant-drill ecosystem strategies. KYON anchors the specialized veterinary segment with AO-compatible system focus for companion animal applications. These three entities represent distinct competitive archetypes: the first leveraging integrated portfolios for pricing power, the second exploiting backward integration into surgical power tool manufacturing, and the third differentiating through specialized compatibility with established fixation standards.
| Leading Market Players |
|---|
| IMEX Veterinary |
| Surgical Holdings Veterinary |
| Vet Surgical Resources |
| Movora |
| Arthrex |
| DePuy Synthes Vet |
| Veterinary Orthopedic Implants |
| KYON |
| BioMedtrix |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up veterinary hospital networks in the United States are consolidating procurement authority, compressing vendor margins while demanding extended service bundling that reshapes supplier cost structures across battery-powered and tethered drill platforms.
Pricing Analysis
Lithium-ion cell cost pass-through from Asian processing facilities is compressing margin predictability for cordless drill producers, forcing three-tier pricing structure across premium titanium-alloy systems, standard stainless-steel configurations, and economy-grade manual backups. FDA 510(k) clearance tier and ISO 10993 biocompatibility certification separate pricing bands most sharply. Pricing pressure stems from consolidated procurement by United States specialty clinic networks demanding multi-year equipment standardization. Mobile veterinarians in Germany exhibit highest price sensitivity due to capital constraints, while academic veterinary hospitals in California and Texas show lowest sensitivity given bundled subscription access models.
Supply Chain Analysis
ISO 10993 biocompatibility and IEC 60601 electrical safety certifications gate supplier entry, concentrating precision motor manufacturing in Germany's North Rhine-Westphalia cluster, battery cell assembly in South Korea and Japan, and titanium alloy substrate processing in the United States. Brushless DC motor controllers, rapid-swap battery systems, and sterilization-compatible handpiece housings constitute critical component dependencies. Single-source vulnerability in lithium-ion cathode chemistry exposes producers to raw material cost swings. Distribution runs through specialized veterinary equipment distributors serving hospital networks and direct manufacturer relationships with academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German mobile veterinary expansion presents a geographic-arbitrage opportunity, as EU MDR harmonization lowers regulatory entry costs relative to FDA 510(k) pathways while field surgical demand for extended-runtime battery systems outpaces domestic supply capacity.
For Market Incumbents: Anticipate brushless DC motor commoditization by locking in multi-year service contracts with United States academic veterinary hospitals before emerging Asian motor suppliers achieve IEC 60601 certification. Defend against pneumatic-to-electric conversion stalls in large-animal suites by offering hybrid power inventory financing. Prioritize backward integration into surgical power tool manufacturing to preserve margin on high-torque configurations. For New Entrants and Emerging Players: Enter via German equine field surgical units, where battery-powered drill penetration remains below fixed-clinic levels and local precision motor suppliers lack veterinary-specific torque modulation expertise. Target mobile veterinarians in Queensland, Australia with rapid-swap battery systems designed for uninterrupted farm animal workflows. Pursue white-label partnerships with established sterilization-compatible component suppliers to bypass capital-intensive manufacturing scale-up. For Investors and Strategic Acquirers: Diversified orthopedic conglomerates with captive veterinary divisions are the most active acquirer in this space, seeking battery chemistry and brushless motor capabilities to complete integrated implant-drill ecosystems. Long-term viability hinges on subscription-based equipment access models displacing transactional purchasing across the forecast horizon. Acquisition target archetype: mid-scale veterinary specialists with AO-compatible system focus and established German distribution. Watch for inflection when United States hospital network consolidation accelerates equipment refresh cycles beyond historical replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Chemistry Acquisition | Secures lithium-ion supply chain control for cordless platform expansion against raw material volatility. |
| EU MDR Technical Documentation Investment | Accelerates CE-marked device entry into German and French veterinary markets ahead of competitors. |
| Brushless DC Motor Platform Launch | Captures mobile veterinarian demand in United States and Australia with torque-to-weight advantages. |
| Academic Hospital System Partnership | Locks in multi-year equipment standardization agreements with integrated maintenance and consumables bundling. |
| Wireless Torque Monitoring Integration | Enables real-time bone density adaptation for resident training and outcome documentation in California academic centers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary orthopedic surgeons, hospital purchasing committee members, biomedical engineers at academic medical centers, and GPO contracts managers with secondary validation against FDA 510(k) clearance databases, EU MDR Article 10 technical documentation filings, and hospital procurement records. Bottom-up equipment shipment tracking and top-down specialty clinic revenue analysis were triangulated to anchor market sizing.
Comparable-period anchoring linked projection assumptions to historical reference points across the modeling period without year-specific calibration. Segmentation dimensions modeled include power system type, procedure application, end-user capital intensity, and geographic regulatory cluster. CAGRs were derived from installed base evolution and replacement cycle compression. Forecast inputs incorporated battery energy density improvement curves and veterinary orthopedic residency program expansion rates.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time mobile veterinarian equipment deployment tracking introduce uncertainty bands around cordless platform penetration assumptions. Forecasts reflect documented assumptions about specialty clinic consolidation velocity and EU MDR enforcement consistency. A model refresh is warranted upon material change in lithium-ion raw material cost trajectories or FDA Center for Veterinary Medicine guidance on powered surgical instrument classification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Smart Orthopedic Implants Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market