
 Automated Dialysis Concentrated Production Systems Market | 2026-2036
Automated Dialysis Concentrated Production Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Dialysis Concentrated Production Systems Market Analytics
Hospital procurement departments is bifurcating from dialysis center buyers as health systems pursue centralized pharmaceutical compounding to cut per-treatment costs and reduce medication errors. Fresenius Medical Care leverages its vertically integrated supply chain to control concentrate quality from manufacturing through clinic delivery. Baxter International anchors its competitive stance through R&D intensity in closed-system automation that limits operator exposure to bicarbonate powders. B. Braun Melsungen differentiates via modular system architectures that allow dialysis centers to scale production capacity incrementally.
Automated dialysis concentrated production systems are electromechanical platforms that mix acid concentrate, bicarbonate concentrate, and purified water to precise ionic specifications for hemodialysis delivery, typically operating under ISO 13959 water quality standards with conductivity monitoring and automated batch documentation. The primary commercial purpose centers on eliminating manual compounding variability while generating audit trails for regulatory compliance. Continuous production technology leads in throughput efficiency for high-volume hospital settings, whereas modular systems capture fastest-growing interest among mid-size dialysis chains seeking scalable capital deployment. Integrated solutions command the deepest margin pools by bundling reverse osmosis pretreatment, concentrate blending, and distribution piping into single-source contracts.
The US FDA enforces quality system regulation under 21 CFR Part 820 for dialysis device manufacturing, while the European Medicines Agency applies CE marking and Medical Device Regulation standards that govern automated pharmaceutical compounding equipment market access. ISO 13485 certification requirements shape supplier qualification timelines, particularly for OEMs seeking to serve Fresenius and Baxter direct purchasing programs. Stakeholders must monitor evolving EPA pharmaceutical effluent guidelines that could mandate closed-loop concentrate systems to reduce dialysate discharge volumes.
Market Dynamics
Large dialysis organization procurement departments are consolidating concentrate production into centralized automated facilities to eliminate batch-to-batch variability and satisfy FDA 21 CFR Part 820 audit requirements. This structural concentration is compressing vendor margins while elevating validation documentation burdens for equipment suppliers.
Growth Catalysts
- Hospital centralization:Health system pharmacy directors are consolidating bicarbonate compounding into single automated suites to reduce per-treatment labor costs and medication error rates.
- ISO 13959 enforcement:Water quality standards for dialysis are tightening conductivity monitoring requirements, forcing clinics to upgrade from manual mixing to automated batch documentation systems.
- Bicarbonate powder exposure limits:Occupational safety regulations are accelerating closed-system automation adoption to limit operator respiratory exposure during concentrate preparation.
Market Restraints
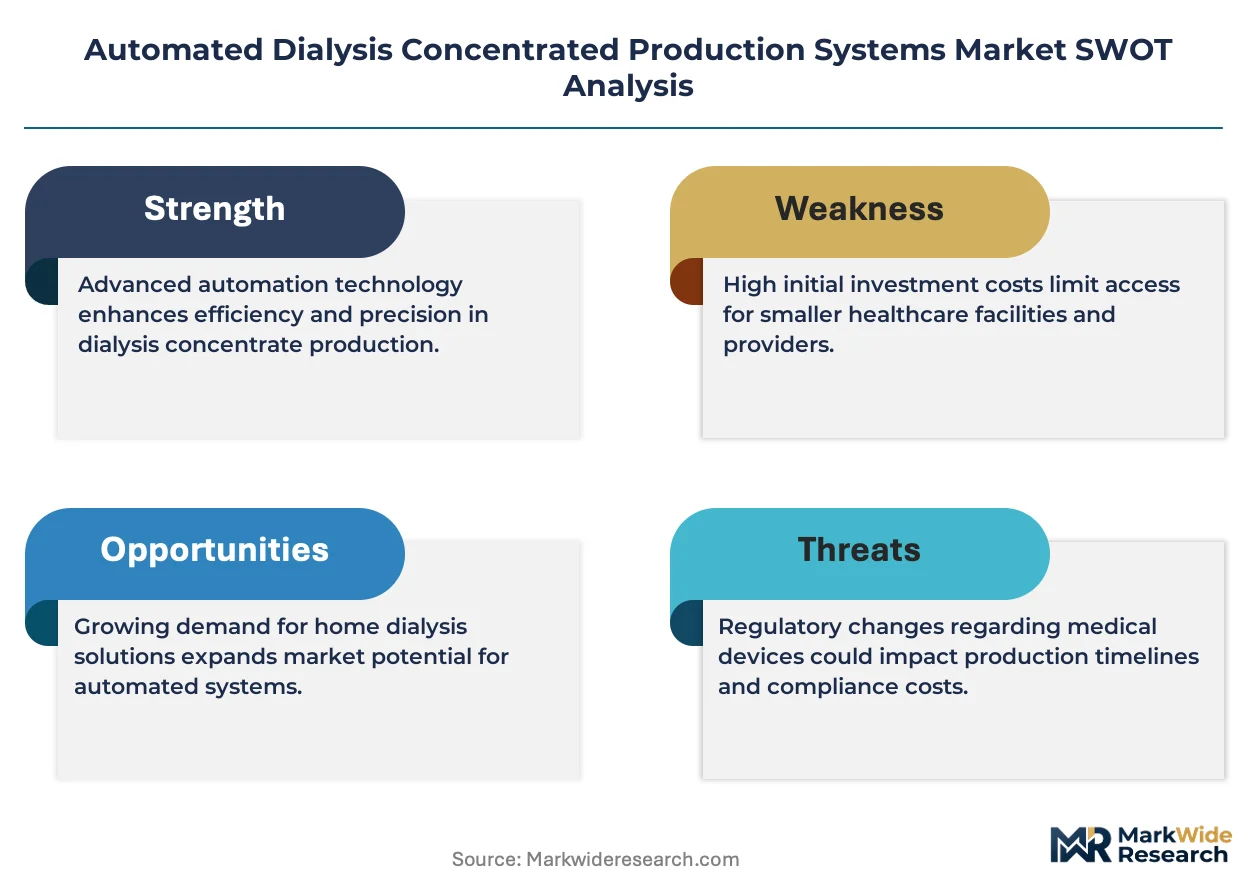
- Stainless steel input volatility:Electropolished 316L vessel costs fluctuate with nickel pricing, compressing system manufacturer margins on fixed-price hospital contracts.
- Supply concentration:High-purity bicarbonate powder production concentrates among three European chemical suppliers, creating geographic chokepoints for North American system operators.
- Validation timeline friction:FDA 21 CFR Part 820 quality system documentation requirements extend new equipment commissioning by eight to fourteen months, delaying revenue recognition for manufacturers.
Strategic Opportunities
- Mid-size dialysis chain whitespace:Regional networks operating fifty to two hundred stations lack capital for continuous production lines, creating demand for modular batch systems with incremental scaling.
- EPA effluent mandates:Emerging pharmaceutical discharge guidelines will require closed-loop dialysate recovery systems, opening retrofit markets for concentrate production equipment with integrated waste reduction.
- Remote monitoring convergence:Cloud-based conductivity logging combined with predictive maintenance algorithms enables service revenue models beyond equipment sales.
Industry Challenges
- Biomedical technician scarcity:Automated concentrate systems require cross-trained personnel fluent in both dialysis clinical protocols and PLC programming, a skill combination concentrated among aging hospital engineering staff.
- Legacy integration complexity:New automated batch systems must interface with existing reverse osmosis infrastructure using proprietary communication protocols from 1990s-era installations.
- ISO 13485 certification delays:Supplier qualification timelines for OEM direct purchasing programs extend eighteen to twenty-four months, freezing out smaller equipment vendors from Fresenius and Baxter supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Dialysis Concentrated Production Systems Market |
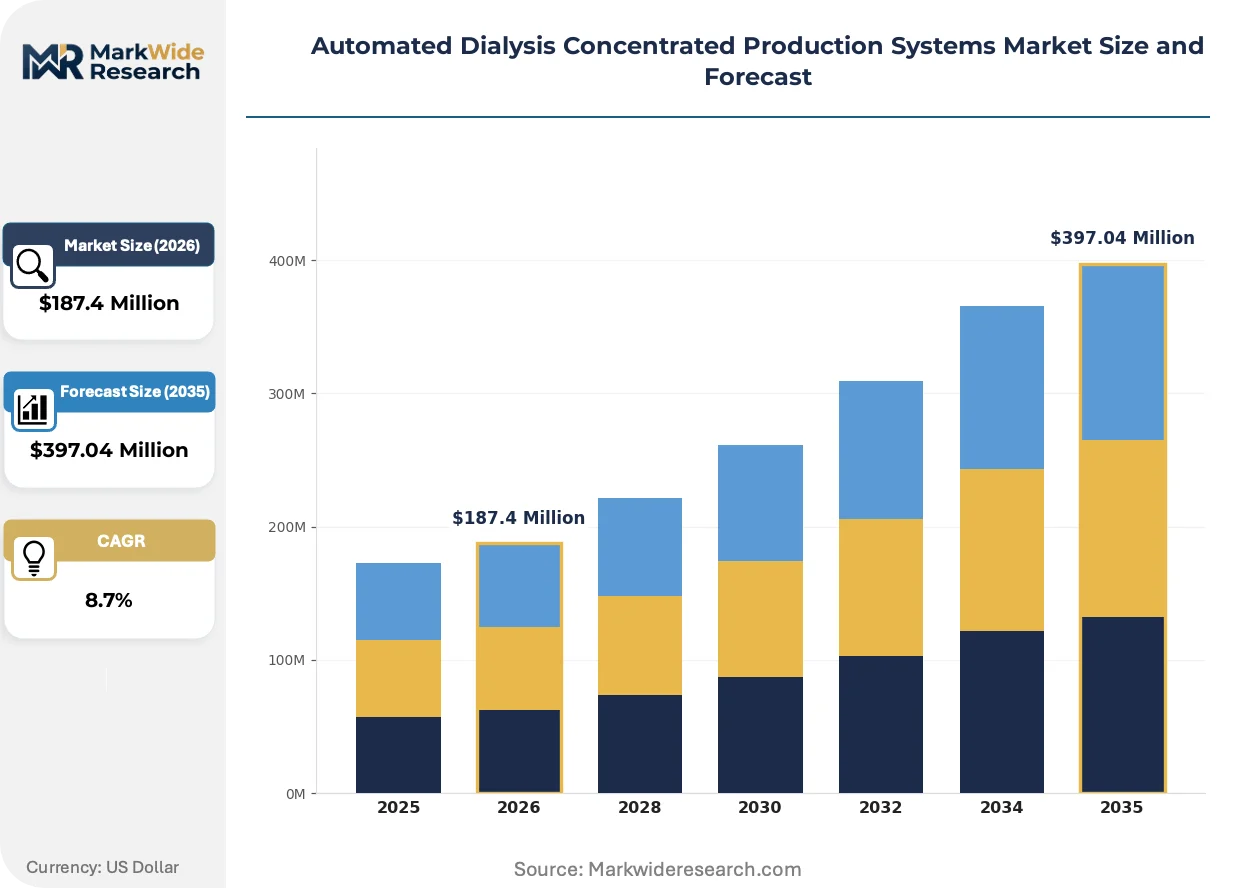
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Production, Continuous Production, Modular Systems, Integrated Solutions End User: Hospitals, Dialysis Centers, Home Care, Clinics Technology: Reverse Osmosis, Filtration, Electrodialysis, Concentration Systems Application: Chronic Kidney Disease, Acute Kidney Injury, Renal Replacement Therapy, Others |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun Melsungen, Ren Med Medical Products & Trade, Rockwell Medical, Nipro Corporation, MEDIVATORS, Farmasol, Dialysis Medical Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Dialysis Concentrated Production Systems Market Evolving Landscape
Closed-loop automation architectures are displacing open-batch systems across high-volume dialysis operations, driven by occupational exposure regulations and real-time conductivity monitoring capabilities. Equipment manufacturers are embedding predictive algorithms to shift revenue from capital sales toward service subscriptions.
Membrane-based bicarbonate concentrate generation is miniaturizing system footprints for satellite dialysis clinics previously excluded from automated production economics. Rural health networks in the United States are piloting these compact units to eliminate daily delivery logistics for liquid concentrate totes. The technology is compressing minimum efficient scale thresholds, enabling automated production in facilities below fifteen stations.
EPA pharmaceutical effluent guidelines are mandating dialysate waste reduction technologies that integrate concentrate production with closed-loop recovery systems. Hospital systems in water-stressed regions are retrofitting existing automated lines with ultrafiltration modules to meet discharge permits. The regulatory pressure is accelerating R&D investment in zero-liquid-discharge architectures among equipment suppliers serving California and Arizona markets.
Consolidated service contracts are replacing discrete equipment purchases as dialysis chains seek to unbundle capital expenditure from operational budgets. Large dialysis organizations are negotiating ten-year agreements bundling concentrate production, maintenance, and consumables into per-treatment fees. This procurement evolution is most visible in the United States, where Fresenius and DaVita network standardization creates volume leverage for outcome-based pricing structures.
Automated Dialysis Concentrated Production Systems Market Segmentation
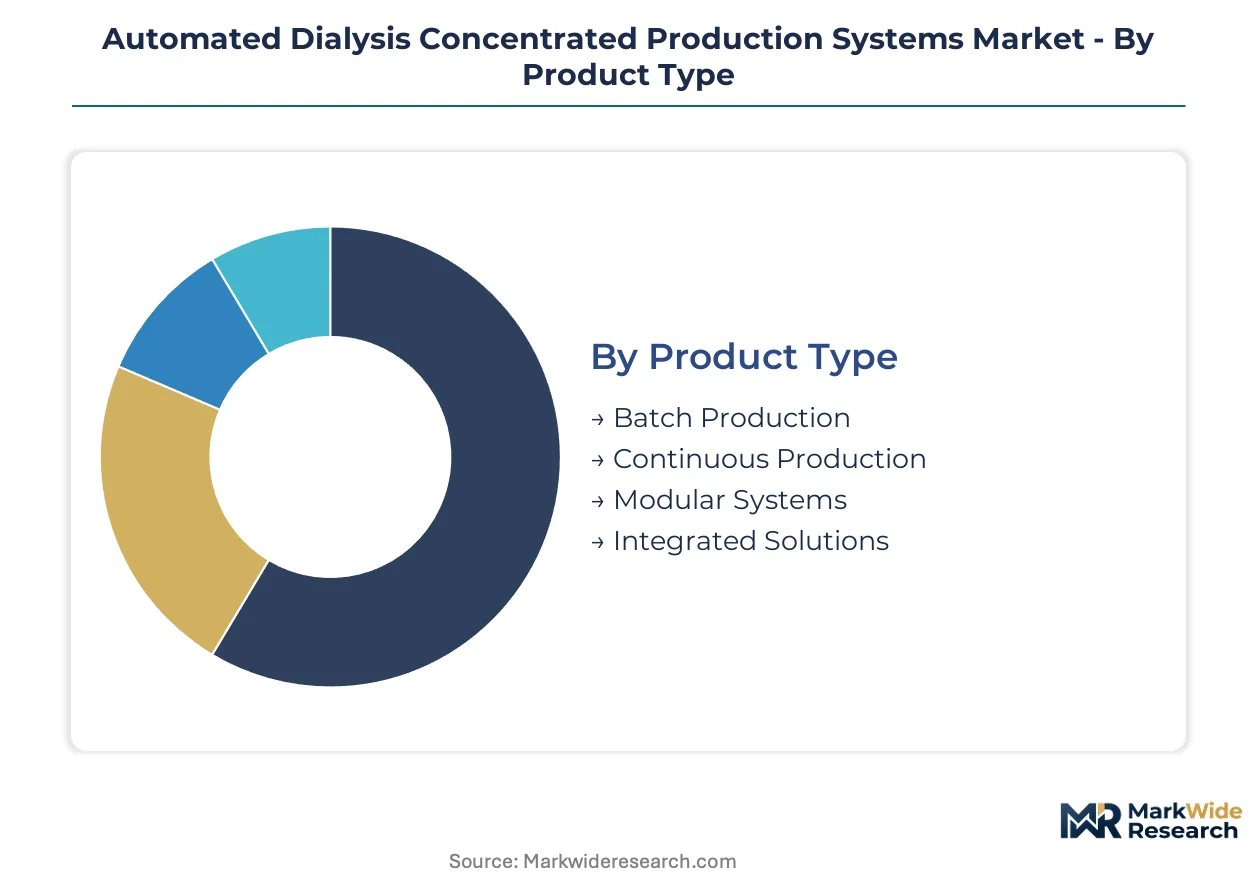
Segmentation in automated dialysis concentrated production systems reveals distinct margin architectures across production modalities and care settings. Hospital procurement patterns diverge sharply from dialysis center buying behavior, creating tiered pricing structures that reward integrated solution providers.
Product Type:
Margin pools concentrate in integrated solutions bundling pretreatment, blending, and distribution infrastructure under single-source contracts.
- Batch Production:Electromechanical platforms mix acid concentrate, bicarbonate, and purified water in discrete cycles with automated documentation for FDA 21 CFR Part 820 compliance. Demand clusters in mid-size dialysis chains across the United States seeking lower capital thresholds than continuous lines.
- Continuous Production:Uninterrupted flow systems achieve highest throughput efficiency for high-volume hospital settings running 24-hour operations. Fresenius and DaVita network standardization in the United States is driving procurement consolidation toward these systems.
- Modular Systems:Scalable architectures allow incremental capacity expansion without full line replacement.
- Integrated Solutions:Bundled contracts combining reverse osmosis, concentrate blending, and distribution piping command premium pricing.
The dominant share belongs to Integrated Solutions, while Modular Systems is closing the gap fastest.
End User:
Customer concentration shapes validation requirements and service contract structures across the care continuum.
- Hospitals:Health system pharmacy directors consolidate bicarbonate compounding into centralized automated suites to reduce per-treatment labor costs and medication error rates. ISO 13959 water quality enforcement is accelerating upgrades from manual mixing across United States hospital networks.
- Dialysis Centers:Large dialysis organization procurement departments standardize toward centralized automated mixing operations to eliminate batch-to-batch variability.
- Home Care:Compact membrane-based systems are miniaturizing footprints for satellite clinics.
- Clinics:Rural health networks pilot automated production to eliminate daily liquid concentrate delivery logistics.
Hospitals capture the deepest margin pools, though Home Care is expanding most quickly.
Technology:
Technology selection determines regulatory pathway complexity and aftermarket service attach rates.
- Reverse Osmosis:Pretreatment membranes remove dissolved solids and organic contaminants prior to concentrate blending, operating under ISO 13959 conductivity monitoring requirements. EPA pharmaceutical effluent guidelines in water-stressed United States regions are mandating closed-loop recovery retrofits.
- Filtration:Depth and membrane filtration stages protect downstream blending equipment from particulate contamination.
- Electrodialysis:Electric field-driven ion separation is miniaturizing system footprints for satellite deployment.
- Concentration Systems:Evaporation and crystallization modules enable zero-liquid-discharge architectures.
Reverse Osmosis maintains installed base leadership, while Electrodialysis is gaining share fastest.
Application:
Clinical indication drives specification stringency and replacement cycle timing.
- Chronic Kidney Disease:Long-term hemodialysis programs require highest reliability and audit trail completeness for CMS reimbursement compliance. Large United States dialysis chains operating fifty to two hundred stations are consolidating production into centralized facilities.
- Acute Kidney Injury:ICU-based renal replacement therapy demands rapid deployment and flexible concentrate formulations.
- Renal Replacement Therapy:Continuous and intermittent modalities span inpatient and outpatient settings.
- Others:Peritoneal dialysis and experimental indications occupy niche volumes.
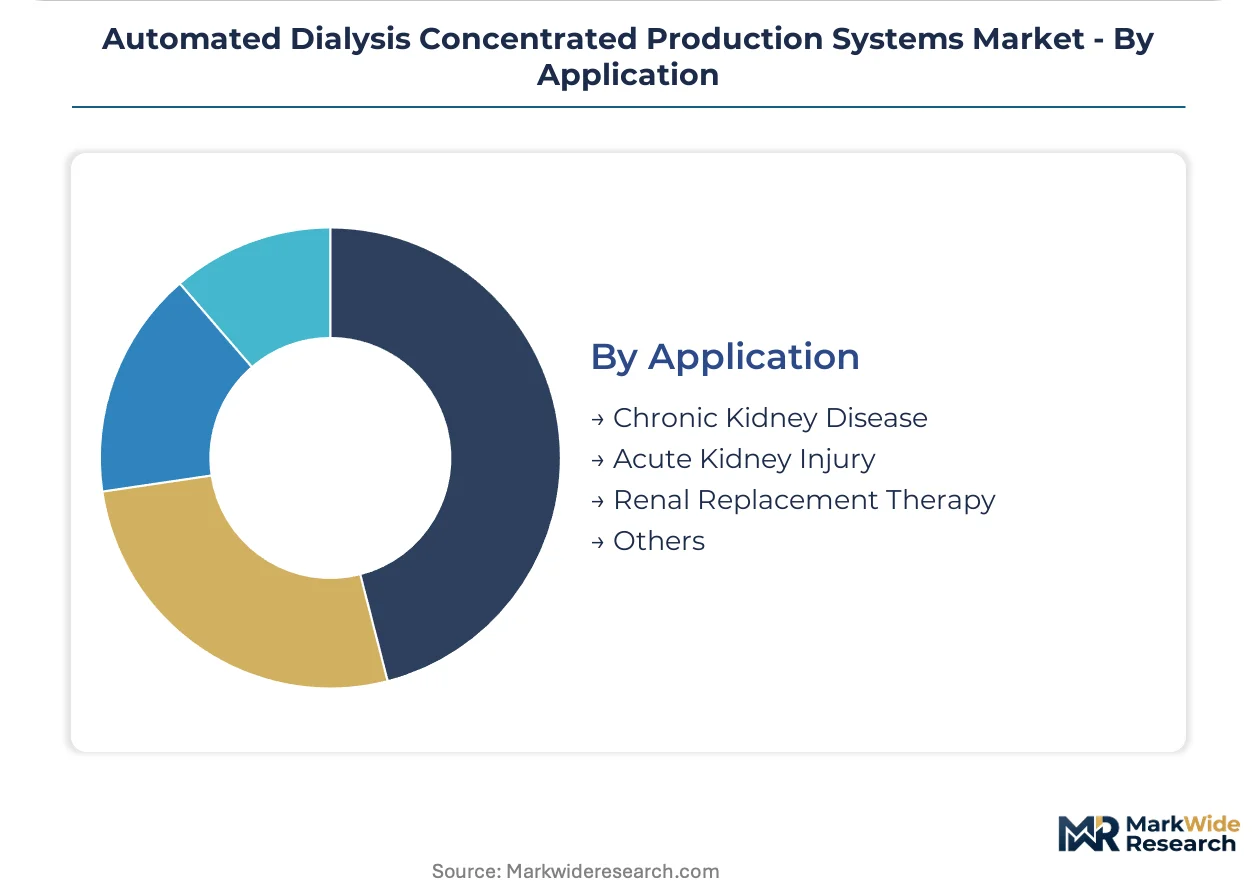
Chronic Kidney Disease commands dominant share, while Acute Kidney Injury is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export automated concentrate production systems to dialysis networks across the United States, establishing the primary trade corridor for high-capacity continuous production lines.
United States
Large dialysis organization procurement departments at Fresenius and DaVita drive standardization toward centralized automated mixing operations. The FDA enforces 21 CFR Part 820 quality system regulations that extend new equipment commissioning timelines by eight to fourteen months. Manufacturing clusters in Minnesota and Illinois produce electropolished 316L vessels for hospital-based concentrate suites.
Germany
Mid-size dialysis chains across Europe source modular batch systems from German fabricators seeking incremental scaling without full line replacement. The European Medicines Agency applies CE marking and Medical Device Regulation standards governing automated pharmaceutical compounding equipment market access. Industrial concentrations in Baden-Württemberg and North Rhine-Westphalia specialize in PLC-integrated blending platforms.
Japan
Academic medical centers in Tokyo and Osaka deploy membrane-based bicarbonate concentrate generation for compact satellite clinic footprints. The Ministry of Economy, Trade and Industry promotes domestic production of dialysis consumables through targeted industrial policy. Manufacturing capabilities concentrate in the Chubu region around Nagoya, where precision engineering firms supply conductivity monitoring subsystems.
China
Provincial hospital networks in the Yangtze River Delta upgrade from manual mixing to automated batch documentation systems under tightening water quality enforcement. The National Medical Products Administration aligns device registration requirements with international ISO 13485 certification standards. Production facilities in Jiangsu and Zhejiang provinces manufacture reverse osmosis pretreatment modules for regional dialysis chains.
Brazil
Private dialysis operators in São Paulo and Rio de Janeiro import European continuous production lines to serve expanding chronic kidney disease patient populations. The national health surveillance agency applies ANVISA medical device regulations that mandate local validation studies for imported concentrate systems. Service partnerships concentrate in the Southeast region, where technical training centers address biomedical technician scarcity.
Automated Dialysis Concentrated Production Systems Market Competitive Landscape
Listed leaders compete with private specialists across validation documentation and service contract structures, creating tiered competitive dynamics. The vendor base concentrates among vertically integrated dialysis therapy providers and independent equipment fabricators serving regional hospital networks. Three archetypes dominate: integrated therapy providers controlling concentrate quality from manufacturing through clinic delivery, automation specialists emphasizing closed-system operator safety, and modular system architects enabling incremental capacity scaling. Competitive moves center on ten-year bundled service contracts replacing discrete equipment purchases, and backward integration into high-purity bicarbonate powder sourcing.
Among Germany-based diversified medical technology groups, Fresenius Medical Care and B. Braun Melsungen exemplify contrasting strategic positions within the integrated solutions tier. Fresenius Medical Care represents the therapy-provider archetype with captive concentrate production serving owned clinic networks. B. Braun Melsungen occupies a position emphasizing modular architectures for mid-size dialysis chains. Baxter International anchors the North American competitive set as a publicly traded automation specialist. These three entities collectively illustrate the market's segmentation between vertical integration strategies and open equipment supply models.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun Melsungen |
| Ren Med Medical Products & Trade |
| Rockwell Medical |
| Nipro Corporation |
| MEDIVATORS |
| Farmasol |
| Dialysis Medical Solutions |
| Others |
Value Network & Pricing Analysis
ISO 13485 certification requirements gate both supplier qualification timelines and price differentiation across the automated dialysis concentrate production equipment market, compressing smaller fabricators into economy-tier positioning while elevating validated incumbents to premium contracting status.
Pricing Analysis
Next-generation membrane-based systems command 40-60% price premiums over electromechanical batch platforms, while prior-generation open-batch configurations face accelerating obsolescence discounts. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation depth and FDA 21 CFR Part 820 audit trail completeness. Cost compression in standard-tier continuous production lines is intensifying because Fresenius and DaVita procurement consolidation demands outcome-based per-treatment pricing. Mid-size dialysis chains exhibit highest price sensitivity, whereas hospital pharmacy directors prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Container availability constraints on trans-Atlantic lanes from German industrial clusters to United States dialysis networks have elevated inbound logistics costs for electropolished 316L vessels and PLC-integrated blending platforms. Manufacturing concentrates in Germany, the United States, and Japan, with high-purity bicarbonate powder production anchored in European chemical complexes. Electropolished stainless steel vessels, conductivity monitoring subsystems, and pharmaceutical-grade bicarbonate powder constitute critical input dependencies. Single-source vulnerability permeates high-purity bicarbonate supply, where three European suppliers control North American access. Distribution runs through direct OEM purchasing programs and regional hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as mid-size dialysis chain consolidation creates whitespace for modular system architects, while hospital centralization simultaneously demands integrated solution providers.
For Market Incumbents: Secure ten-year bundled service contracts with large dialysis organizations before membrane-based miniaturization disrupts continuous production line economics. Deepen backward integration into high-purity bicarbonate powder sourcing to insulate margins from European supply concentration. FDA validation timeline extensions represent the primary margin pressure point requiring preemptive documentation investment. For New Entrants and Emerging Players: Differentiate on membrane-based footprint miniaturization for rural health networks and satellite clinics below fifteen stations. Target mid-size United States dialysis chains operating fifty to two hundred stations with modular batch systems offering incremental scaling without full line replacement. Pursue service-subscription revenue models with predictive maintenance algorithms to bypass capital sales barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automation specialists holding FDA-validated installed bases but limited R&D pipelines for closed-loop architectures. Long-term viability hinges on regulatory compliance technology and service revenue attach rates rather than equipment shipment volumes. Monitor EPA pharmaceutical effluent guideline finalization as inflection signal for zero-liquid-discharge retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bicarbonate Supply | Captive sourcing from European chemical suppliers neutralizes geographic chokepoint risk for North American operators. |
| Membrane-Based System Miniaturization | Compact footprints enable automated production economics in satellite clinics previously excluded from concentrate automation. |
| Cloud-Based Predictive Maintenance Platform | Remote conductivity logging shifts revenue from capital sales toward recurring service subscriptions with dialysis chains. |
| FDA 21 CFR Part 820 Pre-Validation Investment | Accelerated documentation packages compress eight-to-fourteen-month commissioning timelines for hospital procurement. |
| Closed-Loop Dialysate Recovery Integration | Ultrafiltration module bundling addresses emerging EPA effluent mandates in water-stressed California and Arizona markets. |
Research Methodology
Operator-level perspectives from biomedical engineering directors, hospital pharmacy procurement managers, dialysis chain operations executives, and GPO contracts specialists anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement contract registries, and ISO certification authority records. Bottom-up equipment shipment modeling and top-down dialysis treatment volume analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast outputs against variable adoption rates for membrane-based miniaturization and regulatory acceleration scenarios across the projection horizon. Segmentation dimensions modeled include production modality, end-user facility type, pretreatment technology, and clinical application indication. CAGRs derived from treatment volume growth, equipment replacement cycles, and technology substitution elasticities. Forecast inputs incorporated large dialysis organization standardization timelines and EPA effluent guideline implementation trajectories.
Decision-makers should treat outputs as directional under stable FDA quality system enforcement and nickel price assumptions; material deviation would warrant model refresh. Specific risk factors include biomedical technician scarcity delaying commissioning, bicarbonate supply disruption from European logistics constraints, and accelerated membrane technology adoption collapsing continuous production line demand. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Forensic Equipment and Supplies Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Hospital Stretchers Market
Medical Equipment
Proctologic Table Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Electric Bed Market
Medical Equipment
Global Medical Refrigerators Market