
 Global Orthopedic Splints Market | 2026-2036
Global Orthopedic Splints Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Splints Market Foresight
Hospital procurement consortia is reconfiguring how orthopedic splints reach end users across developed markets. Stryker leverages its direct-to-provider contracts to sustain volume commitments in acute care settings. DJO Global competes through specialized sports medicine distribution, while Ottobock anchors its position in rehabilitation channel partnerships across Europe.
Orthopedic splints are rigid, semi-rigid, or soft devices fabricated from thermoplastic, aluminum, carbon fiber, or padded fabric systems, designed to immobilize limbs, stabilize fractures, and protect soft tissue injuries during healing. These devices typically incorporate moisture-wicking liners, adjustable strapping mechanisms, and radiolucent materials to permit diagnostic imaging without removal. Rigid splints dominate hospital purchasing due to their structural reliability in trauma settings, while soft splints capture expanding share in outpatient rehabilitation where patient comfort drives repeat utilization. Carbon fiber variants command premium positioning among sports medicine facilities seeking lightweight durability for active patient populations.
The U.S. FDA classifies orthopedic splints as Class I or II medical devices depending on structural claims, while the EU MDR requires notified body oversight for most immobilization products entering European markets. ISO 13485 certification shapes supplier eligibility for institutional tenders, creating compliance barriers for uncertified manufacturers. Stakeholders must monitor evolving biodegradability mandates and reimbursement coding changes that will determine which material platforms and product formats secure sustainable commercial traction.
Market Dynamics
Hospital procurement consortia consolidation is compressing vendor margins and forcing manufacturers to restructure distribution models around direct contracting and volume-based pricing tiers. This buyer-side concentration is reshaping how orthopedic splints reach acute care settings across developed markets.
Growth Catalysts
- EU MDR compliance mandates:The EU Medical Device Regulation is accelerating notified body oversight requirements, favoring certified manufacturers with established quality management systems and ISO 13485 documentation.
- Sports medicine outpatient expansion:Ambulatory orthopedic facilities in the United States and Germany are scaling splint procurement as same-day procedures displace inpatient admissions.
- Carbon fiber material adoption:Lightweight composite fabrication is penetrating premium trauma care segments where radiolucency and patient mobility drive purchasing decisions.
Market Restraints
- Thermoplastic resin cost volatility:Petrochemical feedstock fluctuations are squeezing margins for mid-tier splint manufacturers dependent on petroleum-derived molding compounds.
- Chinese manufacturing concentration:Raw material processing and component fabrication cluster in Pearl River Delta facilities, creating geopolitical and logistics vulnerability for global supply chains.
- Reimbursement coding compression:CMS and private payor bundling of durable medical equipment is constraining price realization for standard immobilization products.
Strategic Opportunities
- India ambulatory network buildout:Government-funded primary health centers and Ayushman Bharat expansion are creating institutional demand for cost-optimized splint configurations.
- 3D printing convergence with patient-specific modeling:Digital scanning and additive fabrication are enabling custom-fit splint production at point-of-care settings.
- Biodegradable polymer regulatory tailwind:EU Green Deal circular economy mandates are opening procurement channels for compostable immobilization alternatives in European hospital systems.
Industry Challenges
- ISO 13485 certification timeline compression:Notified body backlogs are extending quality system audit queues, delaying market entry for emerging manufacturers.
- Legacy ERP integration friction:Hospital procurement platforms require EDI connectivity and real-time inventory visibility that smaller suppliers struggle to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Splints Market |
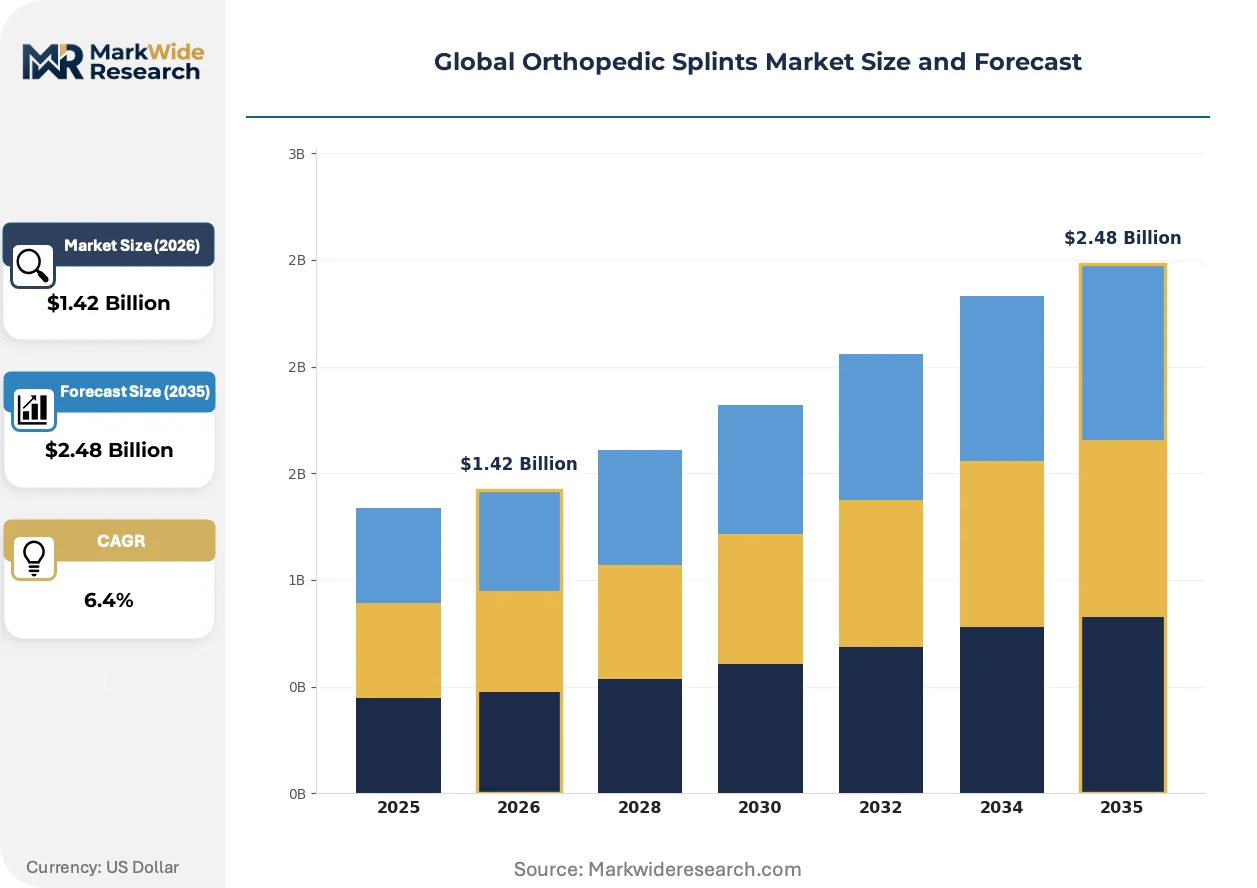
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Splints, Soft Splints, Pneumatic Splints, Adjustable Splints, Semi-Rigid Splints Application: Fracture Stabilization, Soft Tissue Injury, Post-Surgical Immobilization, Joint Support, Pain Management End User: Orthopedic Clinics, Rehabilitation Centers, Emergency Care Providers, Sports Medicine Facilities, Physiotherapy Clinics Material: Thermoplastic, Aluminum, Carbon Fiber, Foam Padding, Fabric Straps |
| Companies Covered | 3M, Essity, Ottobock, DeRoyal Industries, Medi GmbH & Co. KG, Zimmer Biomet, Stryker, DJO Global, Össur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Splints Market Shifts & Advancements
Digital fabrication and sustainable material science are converging to redefine orthopedic immobilization, with point-of-care manufacturing and circular economy mandates accelerating product format experimentation.
Patient-specific 3D-printed splint fabrication is collapsing the traditional mold-and-trim workflow that has dominated orthopedic casting for decades. Sports medicine clinics in Japan and Germany are piloting in-house printing stations that produce anatomically contoured immobilizers within hours. This distributed production model is collapsing inventory carrying costs and enabling same-day customization previously reserved for specialized trauma centers.
EU MDR technical documentation requirements are forcing manufacturers to rebuild clinical evidence portfolios for legacy product lines. The regulation's heightened scrutiny of biocompatibility and post-market surveillance is diverting R&D resources toward regulatory compliance rather than product innovation. European notified bodies are prioritizing audit capacity for high-risk devices, leaving Class I splint manufacturers in extended certification queues.
Direct-to-hospital contracting is displacing distributor-mediated purchasing for high-volume splint categories. Integrated delivery networks in the United States are consolidating supplier panels and demanding vendor-managed inventory arrangements. This channel compression is most visible in Texas and California health systems where procurement officers negotiate multi-year sole-source agreements for standard immobilization products.
Global Orthopedic Splints Market Segmentation
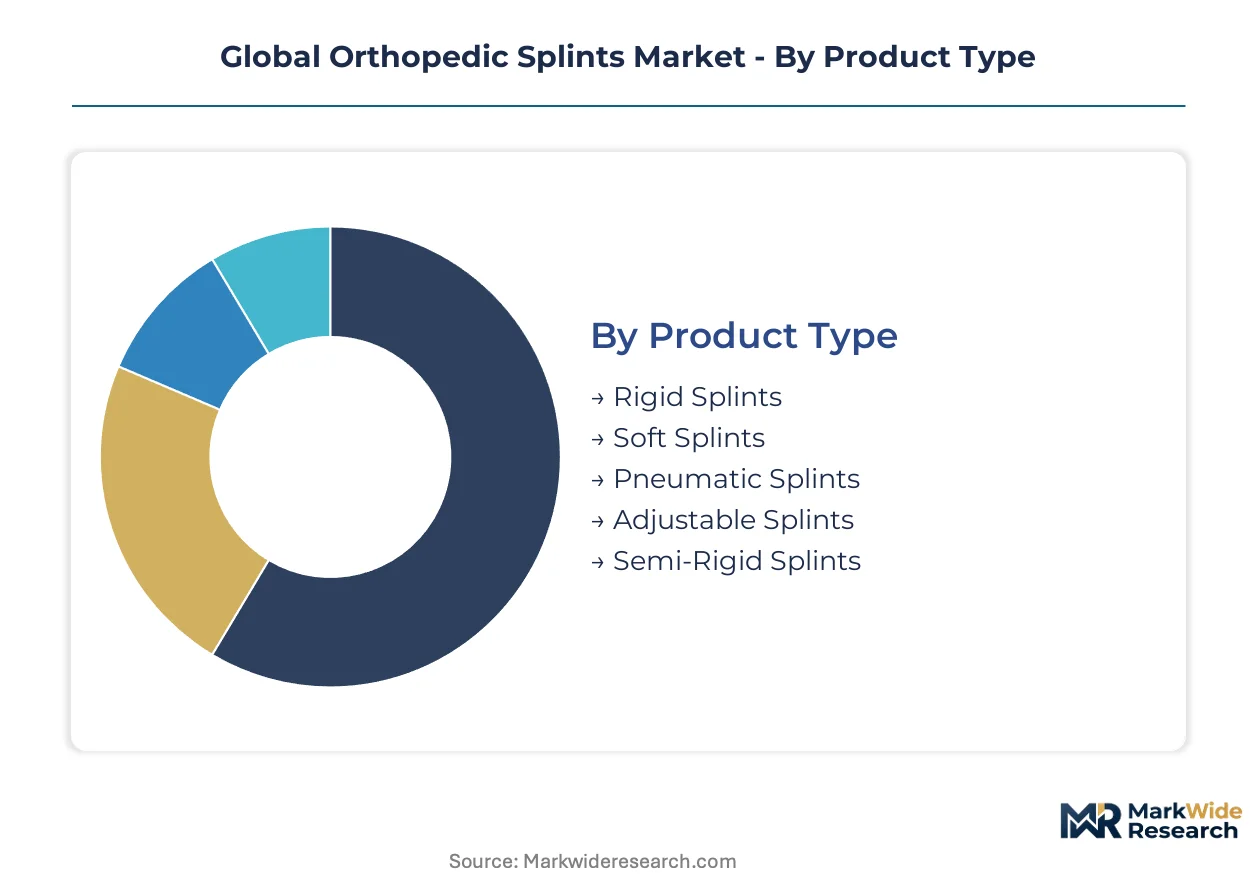
Orthopedic splint segmentation reveals how material science, clinical setting, and injury type shape procurement patterns. Manufacturers align product portfolios against these dimensions to secure contract tiers with consolidated hospital buyers.
Product Type:
The use-case spectrum spans trauma stabilization through ambulatory comfort, with structural rigidity determining clinical deployment.
- Rigid Splints:Thermoplastic or aluminum frameworks deliver structural immobilization for acute fractures. Emergency departments in the United States and Germany specify these for trauma admissions where radiolucency permits imaging without removal.
- Soft Splints:Padded fabric systems prioritize patient comfort during extended wear. Rehabilitation centers in Japan favor these for outpatient protocols where compliance drives repeat utilization.
- Pneumatic Splints:Inflatable bladder designs enable rapid field application by paramedic services.
- Adjustable Splints:Modular strapping accommodates edema progression during recovery phases.
- Semi-Rigid Splints:Hybrid construction balances support with limited joint mobility for transitional care.
Established volume favors rigid platforms; emerging adoption favors soft configurations.
Application:
Cost tier stratification separates acute intervention from maintenance-phase products.
- Fracture Stabilization:Load-bearing immobilization for osseous trauma commands premium pricing in hospital procurement. German trauma networks prioritize carbon fiber variants for weight-bearing compliance.
- Soft Tissue Injury:Ligament and tendon protection protocols drive volume in sports medicine channels. United States outpatient clinics specify moisture-wicking liners for athlete populations.
- Post-Surgical Immobilization:Controlled mobility protocols follow arthroscopic procedures.
- Joint Support:Prophylactic bracing for degenerative conditions.
- Pain Management:Offloading designs for chronic musculoskeletal conditions.
Acute applications dominate contract value; maintenance-phase segments expand most quickly.
End User:
Customer type determines specification rigor and reorder frequency across the care continuum.
- Orthopedic Clinics:Specialized practices demand anatomically contoured inventory for same-day fitting. United States ambulatory surgery centers negotiate vendor-managed stock for high-turnover SKUs.
- Sports Medicine Facilities:Performance-oriented specifications prioritize lightweight materials and aesthetic customization. Japanese professional team physicians specify carbon fiber for competitive athlete return-to-play timelines.
- Rehabilitation Centers:Long-term wear protocols emphasize comfort and hygiene.
- Emergency Care Providers:Rapid-application designs for pre-hospital stabilization.
- Physiotherapy Clinics:Graduated mobilization products for functional recovery.
Institutional buyers concentrate volume; specialized sports channels command margin premiums.
Material:
Supply concentration and processing cost structure the competitive landscape for input sourcing.
- Thermoplastic:Moldable polymers enable custom contouring through heat activation. Pearl River Delta fabrication clusters supply mid-tier manufacturers, exposing margins to petrochemical volatility.
- Carbon Fiber:Composite layup delivers strength-to-weight ratios for premium positioning. German sports medicine procurement specifies these for active patient demographics.
- Aluminum:Malleable metal strips provide economical rigid support.
- Foam Padding:Open-cell and closed-cell formulations manage moisture and pressure distribution.
- Fabric Straps:Hook-and-loop or buckle systems enable adjustable compression.
Conventional materials anchor volume; advanced composites gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German trauma networks extract 15-20% price premiums over equivalent procurement in India, while Pearl River Delta manufacturers supply standard thermoplastic platforms at compressed margins. This asymmetry structures how multinational vendors tier their product portfolios across developed and emerging markets.
United States
Ambulatory surgery centers in Texas and California are consolidating splint procurement through integrated delivery networks that demand vendor-managed inventory arrangements. The FDA's Class I and II device classifications govern market entry, with 510(k) pathways shaping product development timelines. Boston-area sports medicine clinics specify carbon fiber variants for athlete return-to-play protocols.
Germany
Trauma networks prioritize radiolucent carbon fiber splints for weight-bearing compliance in active patient populations. The EU MDR's notified body oversight requirements favor established manufacturers with ISO 13485 certification, extending audit queues for emerging entrants. The Düsseldorf-Cologne corridor hosts rehabilitation channel partnerships that anchor Ottobock's European distribution.
Japan
Professional team physicians in Tokyo and Osaka specify lightweight composite immobilizers for competitive athlete timelines. The PMDA's quality management requirements align with international standards, smoothing market access for certified foreign manufacturers. Nagoya-area clinics are piloting point-of-care 3D printing stations for patient-specific splint fabrication.
China
Government-funded primary health centers are scaling procurement of cost-optimized splint configurations under healthcare infrastructure expansion programs. The NMPA's medical device registration requirements are tightening clinical evidence standards for imported immobilization products. Pearl River Delta thermoplastic fabrication clusters supply mid-tier global manufacturers, exposing margins to petrochemical feedstock volatility.
India
Ayushman Bharat expansion is creating institutional demand for standard immobilization products across government-funded primary health centers. The CDSCO's medical device rules are converging with international quality standards, reshaping supplier eligibility for hospital tenders. Maharashtra's Mumbai-Pune corridor is emerging as a distribution hub for imported premium splints serving private hospital networks.
Global Orthopedic Splints Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying raw materials and fabrication inputs to finished goods manufacturers. Hospital procurement consortia consolidation has compressed the vendor base into three recognizable tiers: multinational device conglomerates with direct-to-provider contracts, regional specialists anchored in rehabilitation or sports medicine channels, and commodity fabricators serving price-sensitive institutional buyers. Dominant competitive moves include backward integration into thermoplastic resin processing and strategic partnerships with ambulatory surgery center networks.
Among diversified medical technology conglomerates, Stryker and Zimmer Biomet occupy positions that exemplify platform-scale supply to acute care settings. DJO Global represents the specialized sports medicine archetype, competing through dedicated distribution rather than breadth of portfolio. Ottobock anchors the rehabilitation channel partnership model across European markets. These three named entities illustrate how competitive positioning stratifies between system-tier suppliers and focused segment specialists.
| Leading Market Players |
|---|
| 3M |
| Essity |
| Ottobock |
| DeRoyal Industries |
| Medi GmbH & Co. KG |
| Zimmer Biomet |
| Stryker |
| DJO Global |
| Össur |
| Others |
Supply & Pricing Matrix
Pearl River Delta thermoplastic fabrication clusters anchor global splint manufacturing capacity, with their resin processing scale translating directly into tiered pricing power for downstream finished goods. German trauma networks absorb 15-20% premiums over equivalent Indian procurement, while mid-tier manufacturers exposed to petrochemical volatility squeeze margins to defend hospital contract tiers.
Pricing Analysis
Configured-to-order pricing for patient-specific 3D-printed splints commands substantial premiums over standard thermoplastic platforms, with customization depth and carbon fiber material grade as primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification status and radiolucency performance. Cost compression in standard immobilization tiers is intensifying because CMS bundling and GPO volume aggregation constrain price realization. Emergency departments exhibit lowest price sensitivity due to trauma workflow urgency; primary health centers in emerging markets demonstrate highest sensitivity, prioritizing procurement cost over performance specifications.
Supply Chain Analysis
Export-control regimes on advanced carbon fiber prepregs and medical-grade thermoplastic resins limit technology transfer to unauthorized fabrication facilities, constraining supply expansion. Manufacturing gravity centers on China for resin processing and component molding, Germany for precision composite layup, and the United States for sterile final assembly. Raw material dependencies draw from petrochemical feedstocks, aluminum smelter output, and textile-grade foam substrates. Single-source vulnerability concentrates in Pearl River Delta resin suppliers, where geopolitical friction or logistics disruption would cascade through global splint availability. Distribution runs through hospital procurement consortia and integrated delivery networks that demand vendor-managed inventory with real-time EDI connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orthopedic splints market functions as a defensive-moat story where regulatory entrenchment through EU MDR certification and ISO 13485 quality system documentation creates durable barriers against unqualified competitors.
For Market Incumbents: Build certification moats by accelerating notified body audit completion for legacy product lines before queue backlogs extend further. Anchor hospital system partnerships through vendor-managed inventory arrangements that embed switching costs into procurement workflows. Threaten margin compression from thermoplastic resin volatility demands backward integration into captive resin processing or long-term offtake agreements with Pearl River Delta suppliers. For New Entrants and Emerging Players: Establish a beachhead in India's Ayushman Bharat-funded primary health centers where institutional demand outpaces certified supplier availability. Target point-of-care 3D printing service models for Japanese sports medicine clinics seeking same-day customization without capital investment. Go-to-market leverage rests on partnerships with rehabilitation channel distributors rather than direct hospital contracting. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement consortia concentration will compress the vendor base to scale-efficient survivors. Acquisition target archetype: regional specialists with ISO 13485 certification and established rehabilitation channel relationships in underserved European or Asian markets. Signal to watch: notified body audit queue lengths as proxy for competitive entry friction.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body priority access secures hospital procurement eligibility before competitor audit completion. |
| Point-of-Care 3D Printing Deployment | In-house fabrication stations at Nagoya and Boston clinics collapse inventory costs and enable same-day customization. |
| Carbon Fiber Backward Integration | Captive composite layup capacity insulates margin from export-control restrictions on medical-grade prepregs. |
| Hospital System Direct Contracting | Multi-year sole-source agreements with Texas and California IDNs lock out distributor-mediated competitors. |
| Biodegradable Polymer R&D Investment | EU Green Deal circular economy mandates open procurement channels for compostable immobilization alternatives. |
Research Methodology
A spread of perspectives from hospital purchasing committee members, biomedical engineers at trauma networks, GPO contracts managers, and sports medicine clinic directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and CMS durable medical equipment reimbursement schedules. Bottom-up demand modeling across end-user segments triangulated with top-down market sizing from material consumption and trade flow data.
Demand-supply balance framing anchored the analytical framework, with volume and value outputs derived from patient procedure volumes, splint utilization rates per intervention type, and replacement cycle dynamics across the projection horizon. Segmentation dimensions modeled include product rigidity class, material platform, application severity tier, end-user facility type, and regional regulatory cluster. CAGRs emerged from spline interpolation of historical shipment data and elasticity-adjusted demand projections, with carbon fiber adoption curves and 3D printing penetration rates as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, healthcare reimbursement policy, or trade regime stability would shift the trajectory. Forecasts incorporate assumptions regarding notified body audit processing times, hospital procurement consolidation velocity, and sports medicine outpatient migration trends. Material shifts in EU MDR enforcement intensity, biodegradability mandate timing, or carbon fiber export-control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Global Acetabular Cups Market