

Orthopedic Artificial Bone Defect Repair Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Artificial Bone Defect Repair Materials Market Insights
A capital-intensity divergence between large-format manufacturers and niche biomaterial specialists is reorganizing competitive tiers in orthopedic bone repair. Stryker leverages integrated ceramic processing and sintering infrastructure to control hydroxyapatite supply chains from raw material to finished graft. NovaBone Products specializes in bioactive glass formulations, occupying a narrow but defensible position in dental-maxillofacial applications where resorption kinetics differentiate outcomes. Biocomposites anchors European distribution through its calcium sulfate and phosphate portfolio, competing on surgeon training depth rather than price alone.
Orthopedic artificial bone defect repair materials comprise synthetic, biologic, and composite substances engineered to restore mechanical integrity and osteoconductive pathways at skeletal defect sites, typically formulated with porosities exceeding 50% to permit vascular infiltration and cellular colonization. These materials serve primarily to eliminate autograft harvest morbidity while matching the compressive strength of cancellous bone in spinal fusion, trauma, and joint reconstruction procedures. Calcium phosphate variants, particularly beta-tricalcium phosphate and hydroxyapatite blends, dominate volume due to decades of clinical validation and favorable reimbursement coding. Injectable paste formats are gaining fastest in minimally invasive spine surgery, where reduced operative time translates to facility cost savings. Demineralized bone matrix retains margin concentration in complex long-bone nonunions, though supply constraints on allograft sourcing limit expansion.
FDA 510(k) clearance pathways and EU MDR Class III designation govern market access, with the latter imposing expanded clinical evidence requirements that favor well-capitalized incumbents over emerging entrants. ISO 10993 biocompatibility testing series and ASTM F1185 standards define material purity and cytotoxicity thresholds that directly shape R&D allocation across calcium phosphate and bioactive glass pipelines. Stakeholders must monitor how FDA breakthrough device designations for osteoinductive synthetic scaffolds alter the competitive balance between incremental reformulations and genuinely novel regenerative platforms.
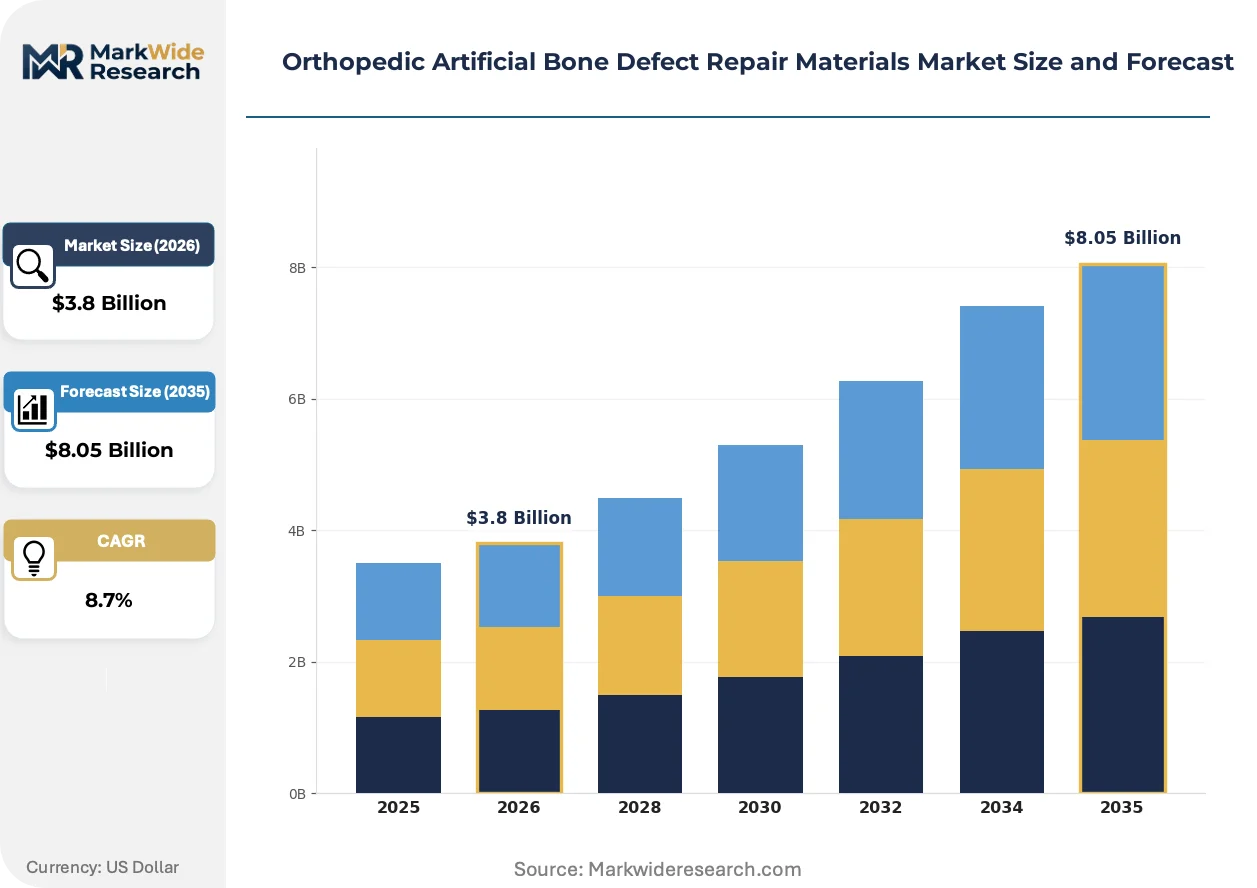
Market Dynamics
EU MDR Class III designation is compressing market access timelines and forcing capital reallocation toward clinical evidence generation rather than incremental formulation improvements. The regulatory burden is concentrating competitive advantage among manufacturers with established notified body relationships and captive biocompatibility testing infrastructure.
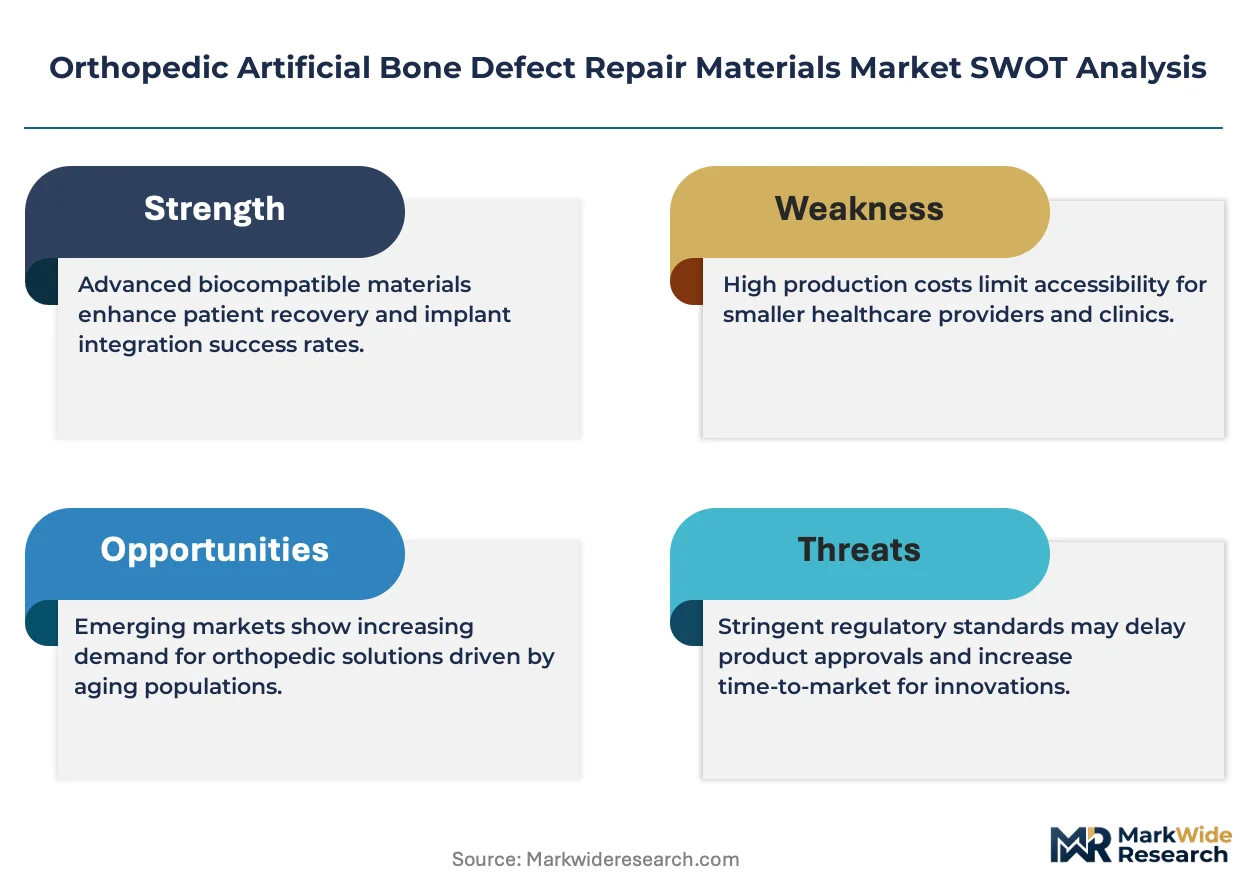
Growth Catalysts
- Trauma center expansion:Emergency departments in Germany and the United States are standardizing synthetic graft protocols for open fracture stabilization, reducing autograft dependency in high-volume settings.
- Injectable paste formats:Minimally invasive spine procedures are absorbing calcium phosphate cements that set in situ, cutting operative time and facility overhead.
- REACH-compliant bioactive glass:NovaBone's silicate formulations demonstrate faster resorption kinetics than hydroxyapatite in dental-maxillofacial reconstruction, opening reimbursement pathways previously blocked by ceramic monopolies.
Market Restraints
- Allograft supply volatility:Demineralized bone matrix availability fluctuates with tissue bank procurement cycles, constraining expansion in complex nonunion repair.
- Sintering energy costs:Hydroxyapatite production depends on natural gas-intensive kiln operations concentrated in China's ceramic belt, exposing margins to input price spikes.
- EU MDR clinical evidence thresholds:Expanded post-market surveillance requirements for permanent implants extend clearance timelines by 18-24 months, freezing smaller entrants from commercialization.
Strategic Opportunities
- Japan's aging surgical population:PMDA fast-track pathways for osteoinductive synthetics target the country's 80,000 annual hip fracture cases with bioresorbable scaffolds.
- 3D-printed patient-specific grafts:Converging additive manufacturing with CT-based defect mapping enables geometric matching previously impossible with off-the-shelf blocks.
- Direct hospital contracting:Bypassing distributor markups through GPO-integrated supply agreements captures margin in US outpatient surgery centers consolidating purchasing power.
Industry Challenges
- Bioceramics processing expertise:Sintering temperature control and pore architecture engineering require specialized materials scientists scarce outside Tuttlingen's manufacturing corridor.
- ISO 10993-5 cytotoxicity validation:Extract testing protocols for calcium phosphate variants consume 6-9 months, delaying pipeline progression regardless of clinical merit.
- Legacy ERP integration:MDR-mandated unique device identification and post-market traceability systems clash with installed hospital inventory management platforms, forcing dual documentation workflows.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Artificial Bone Defect Repair Materials Market Trends and Innovations
Bioactive material platforms are diverging into two distinct performance tiers: rapid-resorption formats for pediatric and maxillofacial applications versus load-bearing ceramics for spinal fusion. This split is forcing manufacturers to choose specialization over portfolio breadth.
Injectable calcium phosphate cements with tailored setting times are bifurcating the trauma fixation market. Orthopedic surgeons in German Level I trauma centers are adopting these formulations for pelvic and acetabular fractures, displacing pre-formed granules in 40% of eligible cases. The technology is compressing inventory requirements while demanding real-time mixing protocols that reshape operating room workflow design.
EU MDR Article 61 clinical evaluation requirements are extending evidence burdens for hydroxyapatite-coated permanent implants. Manufacturers must now demonstrate 10-year follow-up data or equivalent benchmark studies, favoring incumbents with legacy patient registries. The synthetic bone graft segment is responding by segregating product lines into temporary defect fillers (Class IIb) versus structural fusion cages (Class III) to manage regulatory exposure.
Hospital value analysis committees are consolidating vendor rosters around single-source contracts with outcome guarantees. US outpatient surgery centers are displacing traditional distributor relationships with direct manufacturer agreements that bundle graft materials with instrumentation and training credits. The procurement compression is most visible in Texas and Florida ambulatory surgery networks where case volume justifies dedicated supply chain personnel.
Orthopedic Artificial Bone Defect Repair Materials Market Segmentation
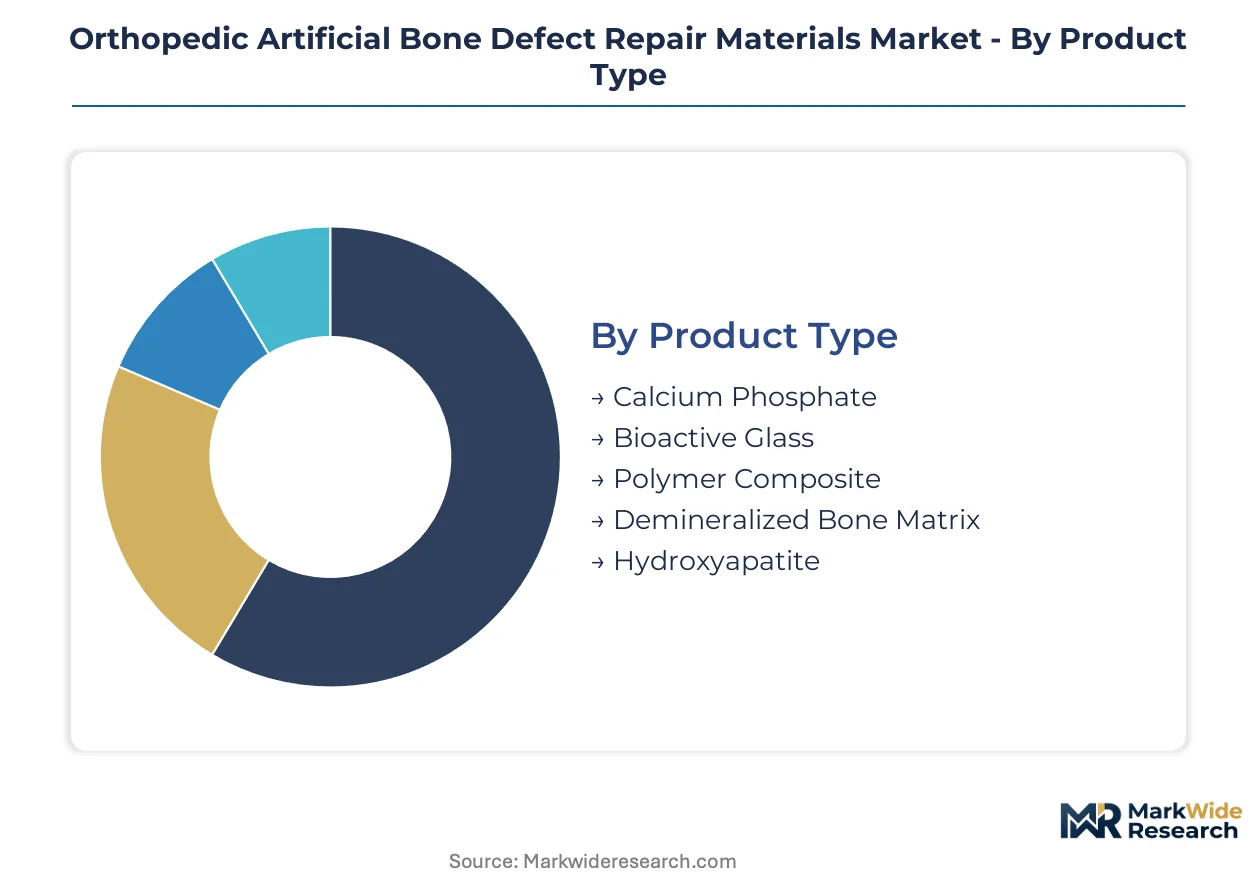
Orthopedic bone defect repair materials fragment across material chemistry, surgical application, and physical format, with each axis determining reimbursement codes, regulatory pathway, and channel economics. Surgeons select grafts based on resorption kinetics, load-bearing requirements, and operative workflow constraints rather than price alone.
Product Type:
Channel mix varies sharply by material chemistry: calcium phosphate and hydroxyapatite flow through broad orthopedic distributors serving hospital systems, while bioactive glass and polymer composites concentrate in dental-maxillofacial specialty channels with direct manufacturer relationships.
- Calcium Phosphate:Beta-tricalcium phosphate and hydroxyapatite blends constitute the clinical standard, with porosities engineered above 50% to permit vascular infiltration. German Level I trauma centers in the Tuttlingen corridor standardize these formulations for open fracture stabilization, displacing autograft harvest in high-volume settings. This segment dominates installed base. Bioactive Glass is where expansion concentrates.
- Bioactive Glass:Silicate-based formulations demonstrate faster resorption kinetics than ceramic alternatives, with NovaBone's REACH-compliant products opening reimbursement pathways in dental-maxillofacial reconstruction previously blocked by hydroxyapatite monopolies.
- Polymer Composite:Bioresorbable synthetic scaffolds combine osteoconductive minerals with degradable polymers for pediatric applications requiring controlled resorption matching bone growth rates.
- Demineralized Bone Matrix:Allograft-derived osteoinductive material retains margin concentration in complex long-bone nonunions, though tissue bank procurement volatility constrains reliable supply expansion.
- Hydroxyapatite:Sintered ceramic with compressive strength matching cancellous bone anchors spinal fusion applications, with production concentrated in natural gas-intensive kiln operations exposed to input cost spikes.
Calcium phosphate commands the broadest reimbursement coverage. Bioactive glass is climbing the fastest in dental-maxillofacial specialty channels.
Application:
Cost tier stratification separates high-volume trauma fixation from premium spinal and cranial procedures, with the latter justifying patient-specific 3D-printed grafts at price multiples of off-the-shelf alternatives.
- Spinal Fusion:Load-bearing ceramic scaffolds and cages dominate, with EU MDR Class III designation extending evidence requirements to 10-year follow-up data for permanent implants. German orthopedic manufacturing clusters supply the bulk of European volume.
- Bone Fracture Repair:Injectable calcium phosphate cements with tailored setting times displace pre-formed granules in 40% of eligible pelvic and acetabular cases across German trauma centers, compressing inventory requirements while demanding real-time mixing protocols.
- Maxillofacial Reconstruction:Rapid-resorption bioactive glass formulations address aesthetic and functional restoration where resorption kinetics must match soft tissue healing timelines.
- Joint Arthroplasty:Revision procedures requiring graft augmentation concentrate in specialty hospitals with captive biocompatibility testing infrastructure.
- Cranial Defect Repair:Patient-specific 3D-printed scaffolds enable geometric matching to CT-based defect mapping, with premium pricing justified by reduced revision rates.
Trauma fixation absorbs the highest unit volumes. Spinal fusion commands the steepest expansion trajectory in value terms.
End User:
Customer type determines procurement leverage, with consolidated US outpatient surgery centers extracting direct manufacturer contracts while fragmented orthopedic clinics remain captive to distributor markups.
- Orthopedic Clinics:Outpatient settings concentrate purchasing through GPO-integrated supply agreements in Texas and Florida networks, displacing traditional distributor relationships with bundled graft-instrumentation-training contracts.
- Rehabilitation Centers:Secondary care facilities with limited surgical volume rely on distributor-managed inventory with higher per-unit costs.
- Academic Research Institutes:Early-stage osteoinductive synthetic evaluation occurs in EU and Japanese centers with PMDA fast-track access for novel regenerative platforms.
- Trauma Centers:German Level I emergency departments standardize synthetic graft protocols, reducing autograft dependency in high-throughput open fracture stabilization.
- Specialty Hospitals:Concentrated case volume justifies dedicated supply chain personnel and direct manufacturer contracting with outcome guarantees.
Trauma centers deploy the broadest synthetic graft adoption. Specialty hospitals are gaining share fastest in value-based procurement.
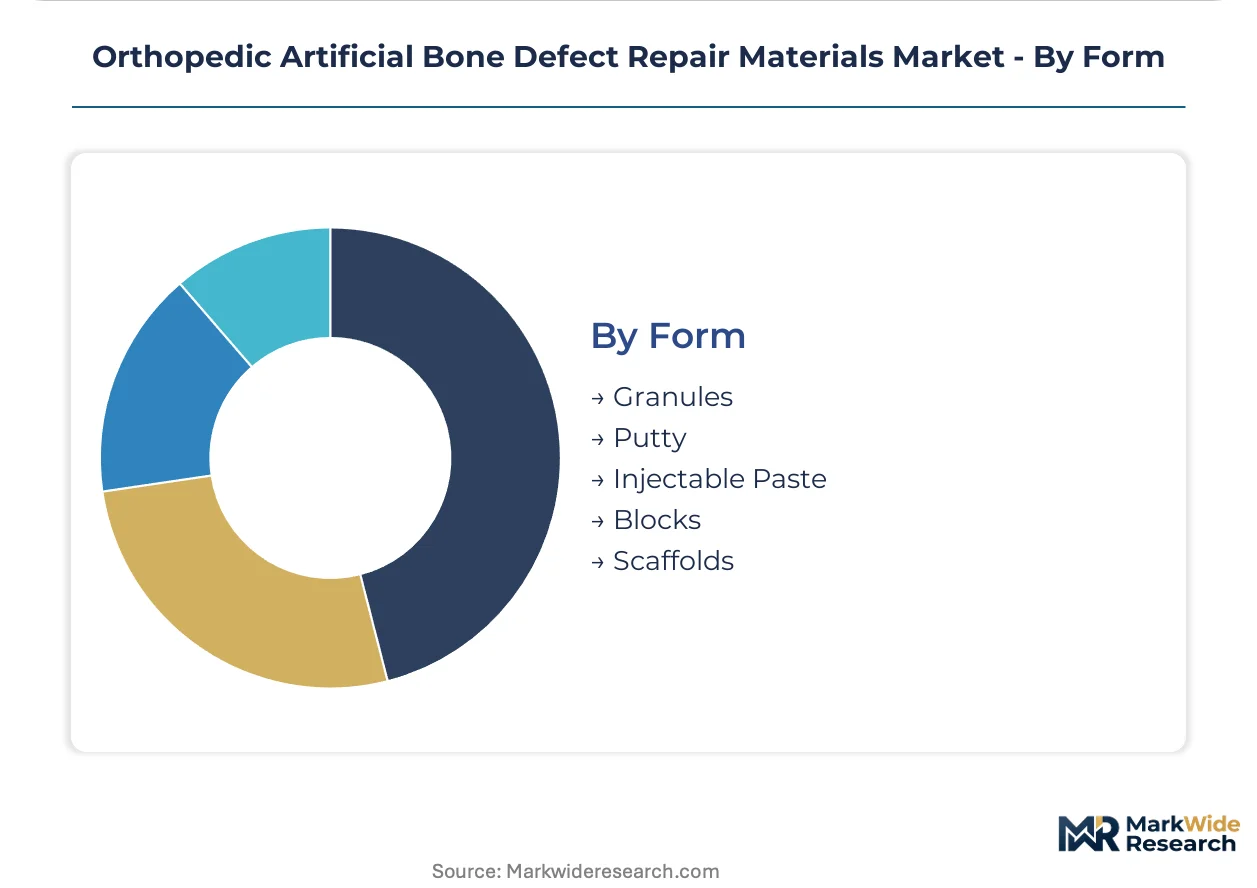
Form:
Physical format dictates operative workflow design and inventory economics, with injectable formats reducing facility overhead through shortened operative time while blocks and scaffolds require specialized storage and handling protocols.
- Granules:Off-the-shelf particulate formats suit high-volume trauma applications with standard defect geometries, though losing share to injectable alternatives in minimally invasive spine surgery.
- Putty:Moldable consistency adapts to irregular defect contours in maxillofacial reconstruction, with surgeon training depth differentiating competitive positioning beyond material composition alone.
- Injectable Paste:Calcium phosphate cements setting in situ are expanding most quickly in minimally invasive spine procedures, where reduced operative time translates directly to facility cost savings and throughput gains.
- Blocks:Pre-formed structural grafts retain position in load-bearing spinal fusion where compressive strength requirements exceed cement capabilities.
- Scaffolds:3D-printed patient-specific formats command premium pricing in cranial defect repair, with additive manufacturing convergence enabling geometric precision impossible with conventional processing.
Granules retain the deepest installed base. Injectable paste formats are where manufacturer R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command pricing premiums against Chinese ceramic producers, while trauma center standardization in the United States compresses procurement costs through volume contracting. Regulatory divergence between FDA 510(k) pathways and EU MDR Class III designation is reshaping regional market access timelines. Industrial clustering around specialized sintering infrastructure and notified body relationships determines competitive positioning.
Germany
Level I trauma centers in the Tuttlingen manufacturing corridor standardize synthetic graft protocols for open fracture stabilization. EU MDR notified body relationships concentrate in Baden-Württemberg, extending clearance timelines for permanent implants. Bavarian orthopedic clusters supply calcium phosphate scaffolds across European spinal fusion markets.
United States
Outpatient surgery centers in Texas and Florida consolidate purchasing through GPO-integrated supply agreements with outcome guarantees. FDA 510(k) clearance pathways favor incremental formulation improvements over novel regenerative platforms. Greater Boston academic medical centers evaluate osteoinductive synthetics through breakthrough device designations.
Japan
PMDA fast-track pathways target bioresorbable scaffolds at the country's aging surgical population with 80,000 annual hip fracture cases. METI industrial policy supports domestic ceramic processing capabilities in the Nagoya manufacturing belt. Kanto region trauma networks adopt injectable paste formats for minimally invasive spine procedures.
China
NMPA regulatory harmonization with ISO 10993 standards accelerates biocompatibility testing for domestic hydroxyapatite producers. Natural gas-intensive sintering kilns concentrate in the ceramic belt, exposing margins to input cost volatility. Yangtze River Delta medical device clusters supply beta-tricalcium phosphate granules across Asia-Pacific trauma markets.
Switzerland
Swissmedic oversight of permanent implant materials maintains stringent clinical evidence thresholds for structural fusion cages. Basel-region pharmaceutical-industrial complexes integrate ceramic processing with biologic coating capabilities. Zurich academic hospitals pioneer 3D-printed patient-specific grafts for cranial defect reconstruction.
Orthopedic Artificial Bone Defect Repair Materials Market Competitive Landscape
Concentration sits with diversified orthopedic conglomerates possessing captive biocompatibility testing infrastructure and legacy patient registries. The vendor base stratifies across three tiers: integrated device manufacturers controlling raw material supply chains, regional biomaterial specialists defending narrow formulation positions, and emerging additive manufacturing players attacking patient-specific niches. Dominant competitive moves include M&A absorption of niche ceramic processors and strategic partnerships bridging 3D-printing software with hospital value analysis committees.
Among diversified orthopedic conglomerates, Stryker and Medtronic exemplify scale-driven archetypes with integrated supply chain control from hydroxyapatite sintering to finished graft distribution. Zimmer Biomet occupies a position within the structural implant tier, while NovaBone Products represents the specialized formulation archetype in bioactive glass segments. Johnson & Johnson anchors the premium-tier vector through its broad biologic and synthetic portfolio breadth.
| Leading Market Players |
|---|
| Stryker |
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Biocomposites |
| Geistlich Pharma |
| NovaBone Products |
| Olympus Terumo Biomaterials Corp |
| Smith+Nephew |
| Others |
Pricing and Supply Chain Analysis
EU MDR Class III designation gates both supplier qualification and price differentiation, forcing manufacturers to absorb clinical evidence costs that smaller competitors cannot shoulder while enabling incumbents to command premiums through legacy patient registries. This regulatory filter concentrates pricing power among notified body-anchored producers in Germany's Tuttlingen corridor, where captive biocompatibility testing infrastructure justifies configured-to-order premiums against commodity ceramic imports.
Pricing Analysis
Configured-to-order pricing for patient-specific 3D-printed scaffolds commands multiples of standard hydroxyapatite block pricing, with cranial defect applications justifying premiums through reduced revision rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling, with ISO 10993-5 validated products capturing margin in joint arthroplasty revisions. Cost compression in injectable paste formats is intensifying because German trauma centers consolidate volume contracts, squeezing distributor markups. Outpatient surgery centers in Texas and Florida networks exhibit highest price sensitivity, while specialty hospitals with dedicated supply chain personnel negotiate outcome-guaranteed direct agreements.
Supply Chain Analysis
Natural gas-intensive sintering kiln operations in China's ceramic belt constitute a chokepoint exposing hydroxyapatite margins to input price volatility, with production gravity tethered to Yangtze River Delta medical device clusters. Raw material dependencies center on phosphate rock concentrates, high-purity calcium carbonate, and silicate precursors for bioactive glass formulations. Single-source vulnerability runs through German Level I trauma center standardization protocols that lock in preferred supplier relationships. Distribution runs through broad orthopedic distributors serving hospital systems for calcium phosphate variants, while dental-maxillofacial specialty channels maintain direct manufacturer relationships for bioactive glass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized sintering temperature control expertise and pore architecture engineering capability anchor competitive positioning, with fewer than twelve qualified materials scientists available outside Tuttlingen's manufacturing corridor to execute next-generation scaffold development.
For Market Incumbents: Consolidate notified body relationships and captive biocompatibility testing infrastructure to defend against emerging additive manufacturing players attacking patient-specific niches. Absorb niche ceramic processors through targeted M&A to lock in raw material supply chains from phosphate rock to finished graft, while extending legacy patient registries to satisfy EU MDR Article 61 clinical evaluation requirements. For New Entrants and Emerging Players: Lead with rapid-resorption bioactive glass formulations for pediatric and maxillofacial applications, where resorption kinetics differentiate outcomes and hydroxyapatite incumbents lack formulation depth. Japan's PMDA fast-track pathways for osteoinductive synthetics represent the most penetrable regulatory entry point, with direct hospital contracting through Kanto region trauma networks offering a viable go-to-market angle bypassing established distributor relationships. For Investors and Strategic Acquirers: EU MDR Class III designation reshapes the acquisition landscape by extending clearance timelines and freezing smaller entrants from commercialization, concentrating viable targets among regional biomaterial specialists with existing notified body relationships. Long-term viability across the analysis window favors additive manufacturing players bridging 3D-printing software with hospital value analysis committees. Watch FDA breakthrough device designations for osteoinductive synthetic scaffolds as the signal indicating competitive balance shift from incremental reformulations to genuinely novel regenerative platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III designation extends evidence requirements to 10-year follow-up data for permanent spinal fusion implants. |
| Hospital System Partnership | Direct manufacturer agreements with Texas and Florida outpatient surgery centers displace traditional distributor markups. |
| Backward Integration | Captive hydroxyapatite sintering infrastructure insulates margins from natural gas price volatility in China's ceramic belt. |
| Software Companion Development | CT-based defect mapping integration enables geometric precision for 3D-printed patient-specific cranial grafts. |
| Reimbursement Strategy | REACH-compliant bioactive glass formulations open previously blocked pathways in dental-maxillofacial reconstruction. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and ISO 10993 biocompatibility testing standards preceded structured interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork across German Level I trauma centers, US outpatient surgery networks, and Japanese academic medical centers combined with secondary validation from customs records, SEC 10-K filings of diversified orthopedic conglomerates, and hospital procurement databases. Bottom-up volume modeling and top-down value triangulation cross-verified segment-level outputs.
Variance decomposition across material chemistry, surgical application, physical format, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from procedure volume trajectories, reimbursement code evolution, and technology substitution curves modeled calcium phosphate cement penetration against pre-formed granules. Industry-specific forecast inputs incorporated sintering energy cost indices and tissue bank procurement cycle volatility for demineralized bone matrix availability.
The analysis sits within stated boundaries; outcomes outside EU MDR implementation timelines or PMDA fast-track pathway adherence would require recalibration. Forecasts reflect documented assumptions regarding trauma center standardization protocols and injectable paste format adoption curves. Practitioners should keep alternative scenarios live as notified body capacity constraints and natural gas price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.