
 Oxygen Conserving Devices Market | 2026-2036
Oxygen Conserving Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Conserving Devices Market Analytics
Respiratory therapist specialization is bifurcating the competitive landscape as trained clinical staff shortages limit homecare expansion in rural territories while urban centers scale remote patient monitoring programs. Philips Respironics leverages its sleep therapy infrastructure to cross-sell conserving devices through established durable medical equipment channels. Inogen Inc. competes through direct-to-consumer portable oxygen concentrator distribution, bypassing traditional HME intermediaries. Drive DeVilbiss Healthcare anchors its position in the rehabilitation center segment with cost-optimized demand flow systems.
Oxygen conserving devices regulate oxygen delivery by synchronizing pulse-dose output with patient inhalation cycles, typically achieving conservation ratios of 3:1 to 7:1 compared to continuous flow systems through pneumatic or electronic sensing mechanisms. These devices serve primarily to extend portable oxygen cylinder duration and reduce refill logistics for ambulatory patients requiring long-term oxygen therapy. Demand flow technology leads installed base volumes due to mechanical simplicity and lower maintenance burden, while adaptive algorithm systems capture premium positioning through real-time respiratory pattern adjustment. The homecare patient end user segment generates the fastest volume growth as post-acute care shifts away from hospital-based oxygen administration.
FDA 510(k) premarket notification requirements govern device classification and predicate equivalence determination for electromechanical and electronic sensor platforms entering the United States market. ISO 80601-2-69 standards for oxygen concentrator safety and IEC 60601-1 electromagnetic compatibility certifications shape design engineering priorities and international market access pathways. Stakeholders must monitor evolving Medicare competitive bidding program adjustments for home oxygen therapy reimbursement rates and their direct impact on patient out-of-pocket cost sensitivity.
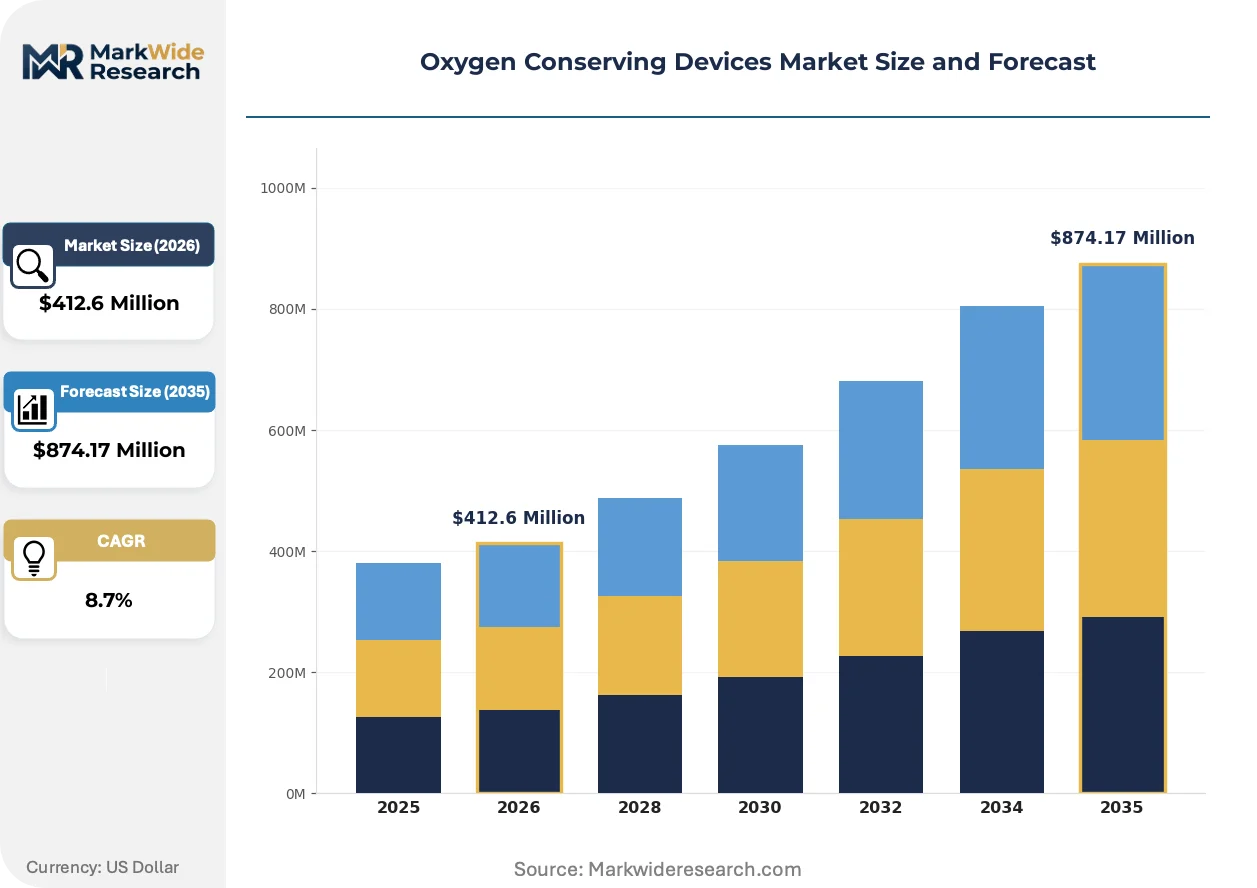
Market Dynamics
Post-acute care decentralization is compressing device procurement timelines as hospitals discharge COPD patients faster into home-based oxygen therapy programs, forcing manufacturers to recalibrate distribution networks for direct-to-patient fulfillment models.
Growth Catalysts
- Medicare competitive bidding expansion:CMS reimbursement code updates for portable oxygen equipment are lowering patient out-of-pocket thresholds and accelerating HME provider inventory turns in the United States.
- Pulse-dose algorithm advancement:Electronic sensing platforms with real-time respiratory pattern recognition are extending cylinder duration ratios beyond mechanical demand flow limits, reducing refill logistics burdens for ambulatory users.
- Germany's ambulatory care restructuring:Diagnosis-related group reforms incentivizing early hospital discharge are routing chronic respiratory patients toward home oxygen therapy with conserving device prescriptions.
Market Restraints
- Lithium-ion battery supply concentration:Portable concentrator manufacturers face input cost volatility tied to cathode material processing bottlenecks in concentrated Asian supply nodes.
- FDA 510(k) predicate equivalence requirements:Electromechanical platform entrants must demonstrate substantial equivalence to cleared devices, extending premarket notification timelines for novel sensor architectures.
- Continuous flow oxygen substitution:High-acuity patients with inconsistent breathing patterns remain tethered to liquid oxygen reservoirs, limiting addressable market expansion for pulse-dose systems.
Strategic Opportunities
- Japan's super-aging prefectures:Rural Hokkaido and Tohoku regions with limited respiratory therapist density present whitespace for telemedicine-integrated conserving device deployments.
- ISO 80601-2-69 harmonization:Converging international safety standards for oxygen concentrator electrical systems are streamlining multi-country registration pathways for modular device platforms.
- Rehabilitation center channel bypass:Direct rental partnerships with pulmonary rehabilitation clinics are circumventing traditional durable medical equipment distributor markups.
Industry Challenges
- Respiratory therapist certification gaps:Rural territories in the United States lack credentialed clinical staff to train patients on adaptive algorithm interfaces, constraining homecare expansion.
- IEC 60601-1 electromagnetic compatibility testing:Preclinical validation for electronic sensor platforms requires specialized anechoic chamber access, stretching R&D capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Conserving Devices Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Flow, Demand Flow, Portable Concentrators, Home Systems End User: Hospitals, Homecare Patients, Emergency Services, Rehabilitation Centers Technology: Electromechanical, Electronic Sensors, Adaptive Algorithms, Hybrid Systems Application: Chronic Obstructive Pulmonary Disease, Sleep Apnea, Asthma Management, Oxygen Therapy |
| Companies Covered | Philips Respironics, Inogen Inc., Invacare Corporation, Drive DeVilbiss Healthcare, ResMed Inc., Chart Industries, Medtronic plc, Precision Medical, Inc., CAIRE Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Conserving Devices Market Evolving Landscape
Device architecture is pivoting toward patient-carried form factors that dissolve the boundary between stationary and ambulatory oxygen delivery, compressing the historical trade-off between conservation efficiency and physical portability.
Microelectromechanical pressure sensors are miniaturizing pulse-dose triggering mechanisms to wearable dimensions while maintaining pneumatic response fidelity. Homecare patients with active lifestyles are adopting these platforms fastest, particularly in Japanese and German markets where outdoor mobility remains a therapeutic priority. This miniaturization is compressing the installed base advantage of legacy demand flow systems by enabling cylinder-free ambulation.
EU Medical Device Regulation (MDR) post-market surveillance requirements are mandating clinical evidence updates for legacy 510(k)-cleared predicates, forcing manufacturers to refresh technical documentation or withdraw older electromechanical platforms. The industrial consequence is accelerated portfolio rationalization toward electronically controlled systems with better data logging capabilities. German notified bodies are processing these renewals slowest, creating temporary market access friction for mid-tier suppliers.
Patient acquisition channels are fragmentating as sleep apnea device users cross-pollinate into oxygen therapy through integrated respiratory care platforms. Durable medical equipment intermediaries are losing exclusivity as manufacturers deploy direct-to-consumer rental portals with remote monitoring subscriptions. This disintermediation is most visible in United States metropolitan corridors where Medicare Advantage plans favor bundled device-and-service contracts over traditional fee-for-equipment arrangements.
Oxygen Conserving Devices Market Segmentation
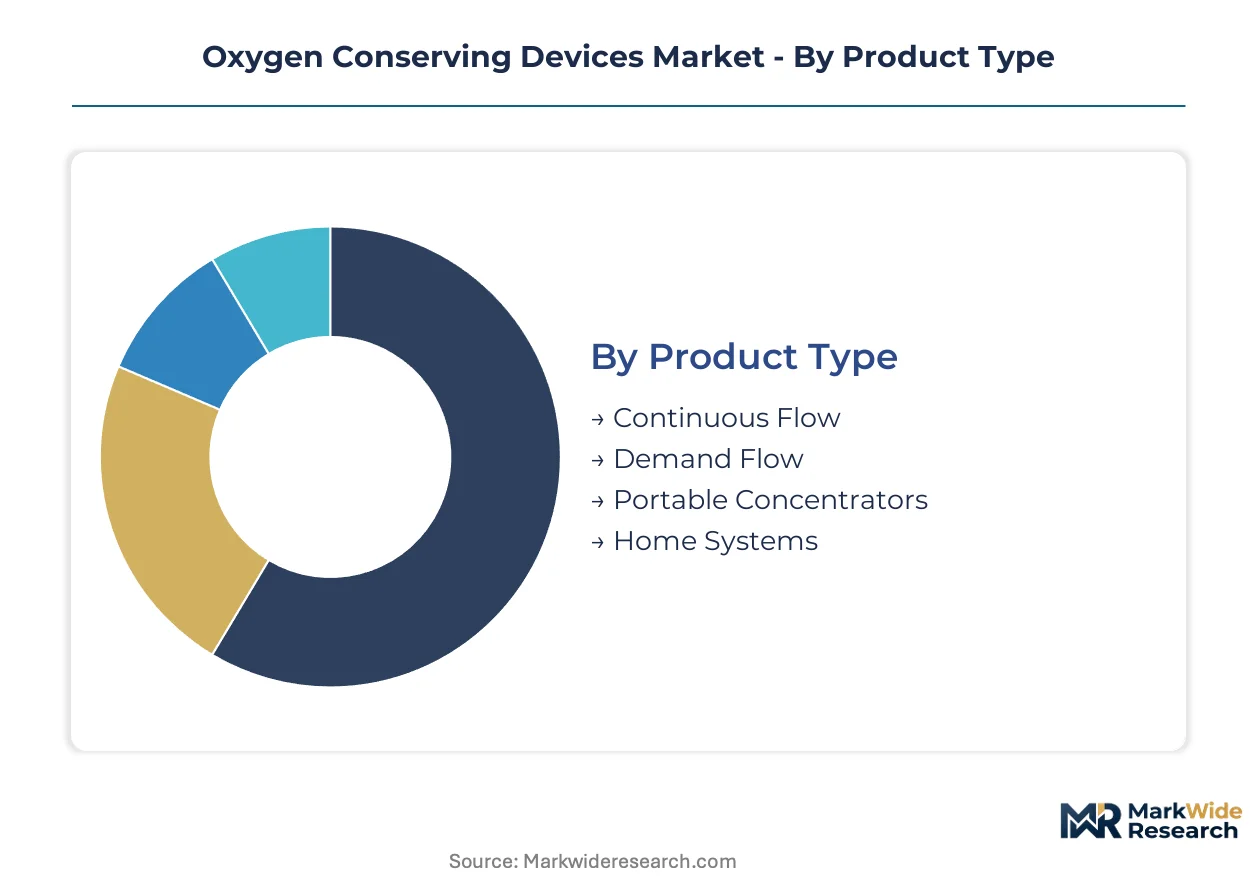
Segmentation in oxygen conserving devices reveals where substitution pressures and reimbursement incentives reshape procurement priorities. Manufacturers calibrate platform architectures to match the clinical requirements and mobility expectations of distinct patient cohorts.
Product Type:
Continuous flow systems face the strongest substitution threat as pulse-dose alternatives extend cylinder duration and reduce logistics costs for ambulatory patients.
- Continuous Flow:Delivers unregulated oxygen at fixed liter-per-minute rates regardless of respiratory phase. Demand concentrates in acute hospital settings where high-acuity COPD patients require stable saturation levels during unstable breathing patterns.
- Demand Flow:Mechanical pneumatic valves trigger oxygen release only during inhalation, achieving conservation ratios of 3:1 to 4:1. Homecare patients in Germany and Japan adopt these systems fastest where refill infrastructure remains sparse in rural prefectures.
- Portable Concentrators:Battery-powered molecular sieve units extract oxygen from ambient air, eliminating cylinder logistics entirely. Lithium-ion supply constraints in concentrated Asian processing nodes create input cost volatility for manufacturers.
- Home Systems:Stationary concentrators with integrated conserving attachments serve nocturnal oxygen therapy requirements. Medicare competitive bidding reimbursement codes shape patient out-of-pocket thresholds in the United States.
Demand flow systems retain volume leadership; portable concentrators hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital procurement from rental-driven homecare economics.
- Hospitals:Acute care facilities prioritize device redundancy and alarm integration over conservation efficiency. FDA 510(k) clearance pathways govern electromechanical platform selection for inpatient respiratory wards.
- Homecare Patients:Ambulatory users with active lifestyles drive fastest adoption of wearable pulse-dose platforms. Post-acute care decentralization in the United States compresses discharge-to-device timelines for COPD cohorts.
- Emergency Services:Pre-hospital oxygen delivery requires rapid-deployment cylinder systems with minimal training burden. ISO 80601-2-69 electrical safety standards constrain platform selection for ground and air ambulance fleets.
- Rehabilitation Centers:Pulmonary therapy clinics prescribe conserving devices as part of graduated mobility programs. Direct rental partnerships with these facilities circumvent traditional durable medical equipment distributor markups.
Homecare patients represent the fastest-growing trajectory; hospitals maintain the highest equipment specification thresholds.
Technology:
Application maturity divides legacy mechanical platforms from algorithm-enabled adaptive systems.
- Electromechanical:Pneumatic demand valves with spring-loaded diaphragms trigger oxygen delivery based on negative pressure differentials. Rural territories in the United States favor these systems for their mechanical simplicity and minimal maintenance requirements.
- Electronic Sensors:Microelectromechanical pressure transducers detect inhalation onset with millisecond latency. IEC 60601-1 electromagnetic compatibility testing requirements stretch R&D validation timelines for new platform entrants.
- Adaptive Algorithms:Real-time respiratory pattern recognition adjusts pulse-dose timing and volume to match changing patient effort. Respiratory therapist certification gaps in rural Hokkaido and Tohoku regions constrain training-intensive deployments.
- Hybrid Systems:Combined mechanical-electronic architectures provide fail-safe oxygen delivery during sensor malfunction. EU Medical Device Regulation post-market surveillance mandates are accelerating portfolio rationalization toward these data-logging-capable platforms.
Electromechanical platforms retain installed base dominance; adaptive algorithms command the steepest expansion curve.
Application:
Geographic concentration of chronic respiratory disease prevalence determines regional procurement patterns.
- Chronic Obstructive Pulmonary Disease:Long-term oxygen therapy for emphysema and chronic bronchitis patients constitutes the primary clinical indication. Germany's diagnosis-related group reforms incentivize early hospital discharge into home-based conserving device programs.
- Sleep Apnea:Nocturnal oxygen supplementation for overlap syndrome patients bridges CPAP therapy gaps. Sleep therapy infrastructure in the United States enables cross-selling through established durable medical equipment channels.
- Asthma Management:Acute exacerbation recovery protocols incorporate short-term conserving device prescriptions. Pediatric applications remain limited due to inconsistent breathing pattern reliability in young patients.
- Oxygen Therapy:General long-term oxygen therapy encompasses interstitial lung disease and pulmonary fibrosis indications. Medicare reimbursement code updates for portable equipment lower patient cost barriers in the United States.
COPD applications retain volume leadership; sleep apnea holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and Medicare reimbursement codes anchor commercial viability in the United States, while aging demographics and chronic respiratory disease prevalence concentrate procurement across Germany and Japan.
United States
Medicare competitive bidding program expansions for portable oxygen equipment compress patient out-of-pocket thresholds and accelerate durable medical equipment provider inventory turns. FDA 510(k) premarket notification requirements govern electromechanical platform classification and predicate equivalence determination for market entrants. The Southeast corridor from Florida through Georgia hosts dense pulmonary rehabilitation clinic networks where direct rental partnerships circumvent traditional distributor markups.
Germany
Diagnosis-related group reforms incentivizing early hospital discharge route chronic respiratory patients toward home oxygen therapy with conserving device prescriptions. EU Medical Device Regulation post-market surveillance mandates from German notified bodies process technical documentation renewals slowest, creating temporary market access friction. Bavaria's medical technology cluster around Munich anchors notified body concentration and regulatory service provider density for oxygen concentrator compliance.
Japan
Super-aging prefectures in rural Hokkaido and Tohoku present whitespace for telemedicine-integrated conserving device deployments where respiratory therapist density remains limited. METI industrial standards harmonization with ISO 80601-2-69 safety specifications streamlines multi-country registration pathways for modular device platforms. The Kanto region surrounding Tokyo concentrates sleep therapy infrastructure that enables cross-selling into oxygen therapy through integrated respiratory care channels.
United Kingdom
NHS England long-term oxygen therapy prescribing guidelines shape conserving device procurement criteria for COPD and interstitial lung disease patient cohorts. MHRA post-Brexit regulatory autonomy maintains equivalence with EU MDR surveillance requirements while streamlining UK-specific market authorization timelines. The Greater Manchester and West Midlands hospital trusts pilot remote patient monitoring programs that compress discharge-to-device timelines for post-acute respiratory patients.
Canada
Provincial health authority reimbursement schedules for home oxygen therapy equipment vary across Ontario, Quebec, and British Columbia, creating patchwork procurement economics. Health Canada medical device licensing requirements align with FDA predicate equivalence frameworks, easing cross-border platform registration for US-origin manufacturers. The Ontario corridor from Toronto to Ottawa concentrates pulmonary rehabilitation center density where graduated mobility programs incorporate conserving device prescriptions.
Oxygen Conserving Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with durable medical equipment channel control separating scale players from component suppliers. The vendor base arranges across sleep therapy cross-sellers, portable concentrator direct-to-consumer distributors, and rehabilitation center-focused demand flow specialists. Three strategic archetypes dominate: integrated respiratory platforms leveraging sleep apnea infrastructure, direct-to-patient rental portals bypassing traditional intermediaries, and cost-optimized mechanical system suppliers anchoring institutional procurement. Competitive moves concentrate on channel disintermediation through direct rental partnerships and portfolio rationalization toward electronically controlled systems with data logging capabilities.
Among integrated platform operators, Philips Respironics and ResMed Inc. occupy positions that exemplify sleep therapy infrastructure leverage for oxygen therapy cross-selling. Inogen Inc. sits within the direct-to-consumer archetype, representing portable concentrator distribution models that bypass traditional durable medical equipment intermediaries. Drive DeVilbiss Healthcare anchors the institutional-focused tier, exemplifying cost-optimized demand flow system positioning for rehabilitation center and post-acute care segments.
| Leading Market Players |
|---|
| Philips Respironics |
| Inogen Inc. |
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| ResMed Inc. |
| Chart Industries |
| Medtronic plc |
| Precision Medical, Inc. |
| CAIRE Inc. |
| Others |
Value Network & Pricing Analysis
Pulse-dose algorithm substitution for mechanical demand valves is redrawing procurement economics as electronic sensing platforms concentrate manufacturing in Taiwanese semiconductor foundries while compressing margins for legacy pneumatic suppliers in Germany and the United States.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement as hospital systems and durable medical equipment providers lock in multi-year pricing for electromechanical platforms, while spot-market dynamics govern lithium-ion battery procurement for portable concentrator manufacturers. Three-tier pricing structure across adaptive algorithm, electronic sensor, and electromechanical levels reflects FDA 510(k) certification tiers and respiratory therapist training requirements. Pricing pressure stems from Medicare competitive bidding compression on home oxygen therapy reimbursement rates. Homecare patients exhibit highest price sensitivity due to out-of-pocket cost exposure, whereas acute care facilities prioritize device redundancy over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among portable concentrator assemblers sourcing microelectromechanical pressure sensors from Taiwan, South Korea, and Japan, while strategic stockpiling of lithium-ion cathode materials occurs at concentrated Asian processing nodes in China and South Korea. Raw material dependencies center on rare earth elements for molecular sieve membranes, precision-machined aluminum for pneumatic valves, and cobalt-nickel cathode formulations. Single-source vulnerability in Taiwanese MEMS sensor fabrication poses structural risk. Distribution runs through durable medical equipment intermediaries, though direct-to-patient rental portals are gaining channel share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-acute care decentralization fragments procurement authority across pulmonary rehabilitation clinics, homecare agencies, and direct-to-consumer platforms, creating niche entry points for specialized players outside traditional hospital supply chains.
For Market Incumbents: Secure respiratory therapist training infrastructure in rural United States territories to defend against telemedicine-integrated challengers. Lock in backward integration into lithium-ion battery pack assembly to buffer cathode material cost volatility from concentrated Asian suppliers. Fortify FDA 510(k) predicate libraries to extend clearance timelines for electromechanical entrants.
For New Entrants and Emerging Players: Differentiate on adaptive algorithm platforms requiring minimal clinical training for rural Japan's Hokkaido and Tohoku prefectures where respiratory therapist density remains lowest. Target direct rental partnerships with pulmonary rehabilitation centers in the United States Southeast corridor to circumvent distributor markups. Pursue ISO 80601-2-69 harmonization as a go-to-market accelerant for modular device platforms.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid system specialists with data-logging capabilities that satisfy EU Medical Device Regulation post-market surveillance mandates. Long-term viability hinges on portfolio rationalization toward electronically controlled platforms with telemedicine integration. Watch Medicare competitive bidding program adjustments for home oxygen therapy as an inflection signal for patient out-of-pocket elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Electronic sensor platforms require predicate equivalence demonstrations that extend premarket timelines. |
| CE Marking Pathway | EU Medical Device Regulation post-market surveillance mandates accelerate documentation refresh cycles. |
| Hospital System Partnership | Direct rental agreements with pulmonary rehabilitation clinics bypass traditional distributor markups. |
| Software Companion Development | Remote patient monitoring subscriptions disintermediate durable medical equipment intermediaries. |
| Reimbursement Strategy | Medicare competitive bidding code updates directly shape patient out-of-pocket cost thresholds. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with respiratory therapists, biomedical engineers at hospital purchasing committees, durable medical equipment procurement managers, and GPO contracts administrators. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare competitive bidding program disclosures, ISO 80601-2-69 technical documentation, and hospital procurement records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Across the analysis window, volume and value outputs reflect a segmented approach modeling product type, end user, technology platform, and application indication dimensions. CAGRs were derived from fitted growth curves applied to installed base replacement cycles and ambulatory patient population expansion. Forecast inputs incorporated lithium-ion battery supply constraints, FDA clearance timeline distributions, and Medicare reimbursement elasticity parameters.
Material uncertainties — regulatory pathway delays, cathode material supply disruptions, respiratory therapist certification gaps — sit outside the modeled envelope. Forecasts reflect assumptions about competitive bidding stability and ISO harmonization progress. Revision becomes warranted when Medicare reimbursement compression crosses thresholds that trigger patient non-compliance or device return rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Patellar Implant Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Medical Thermometer Market