
 India Orthopedic Braces and Supports Market | 2026-2036
India Orthopedic Braces and Supports Market Size, Share, and Industry Trends Forecast 2026-2036
India Orthopedic Braces and Supports Market Insights
Capital-intensity divergence between domestic fabricators and multinational implant-grade specialists is bifurcating competitive terrain in India. Tynor Orthotics leverages its Gujarat manufacturing base to dominate value-tier knee and ankle categories across tier-2 cities. DJO sustains premium positioning through imported carbon-composite lines distributed via Apollo and Max hospital networks. Ottobock anchors its presence in pediatric and neuromuscular segments where reimbursement tie-ins with state disability programs create stickier accounts.
Orthopedic braces and supports encompass rigid, semi-rigid, and soft apparatus engineered from neoprene blends, thermoformable plastics, and lightweight aluminum alloys to immobilize, compress, or mechanically assist compromised joints and musculoskeletal structures. Fabric-based soft supports currently occupy the highest volume tier due to self-application convenience and sub-INR 500 price accessibility, while composite-material hinged braces command superior margins in post-surgical rehabilitation channels directed through hospitals and rehabilitation centers. Online retail and medical stores together constitute the dominant distribution architecture, though direct sales to institutional buyers are gaining traction as hospital chains centralize procurement.
BIS certification requirements and CDSCO's escalating medical device quality audits are compressing informal manufacturer participation while elevating compliance costs for legitimate operators. The PLI scheme's medical device incentives are reshaping capital allocation toward domestic molding and textile-lamination capabilities. Stakeholders must monitor how Ayushman Bharat's expanding procedure coverage redistributes volume between public hospital tenders and private clinic cash-pay segments.
Market Dynamics
CDSCO's escalating medical device quality audits are compressing informal manufacturer participation while elevating compliance costs for legitimate operators. The PLI scheme's medical device incentives are reshaping capital allocation toward domestic molding and textile-lamination capabilities.
Growth Catalysts
- PLI scheme incentives:Production-linked incentives for medical devices are redirecting capital toward domestic molding and textile-lamination capabilities. Gujarat and Maharashtra manufacturing clusters are expanding capacity.
- Ayushman Bharat expansion:Procedure coverage growth is redistributing volume between public hospital tenders and private clinic cash-pay segments. Tier-2 city hospitals are upgrading orthopedic infrastructure.
- Sports medicine infrastructure:Urban youth sports injury cases are expanding hospital procurement volumes. Mumbai-Pune corridor private orthopedic chains are consolidating supply contracts.
Market Restraints
- Import dependence for carbon-composite materials:Premium hinged braces require aerospace-grade composites sourced from Germany and Japan. Currency volatility inflates landed costs for implant-grade specialists.
- BIS certification bottlenecks:Bureau of Indian Standards testing timelines extend 14-18 months for novel textile-lamination combinations. Small fabricators lack capital to maintain parallel certification tracks.
- Substitution by physiotherapy:Post-surgical rehabilitation protocols in Max and Apollo networks are shortening brace-wear duration. Active recovery protocols displace rigid immobilization in knee arthroscopy cases.
Strategic Opportunities
- Neuromuscular pediatric segments:State disability program reimbursement tie-ins create sticky accounts with multi-year replacement cycles. Ottobock's established presence demonstrates model viability.
- Online retail channel expansion:Self-application soft supports under INR 500 price points are migrating from medical stores to e-commerce platforms. Flipkart and Amazon health categories are building dedicated orthopedic storefronts.
- Thermoformable plastic convergence:3D scanning and CAD-CAM integration is enabling mass-customization of ankle-foot orthoses. Tamil Nadu dental technology clusters are repurposing thermoforming equipment.
Industry Challenges
- Biomedical textile engineering talent scarcity:Neoprene blend formulation and compression gradient design require polymer chemistry expertise concentrated in IIT Mumbai and ICT Mumbai programs. Domestic manufacturers compete with automotive and aerospace sectors for graduates.
- CDSCO audit preparation costs:Quality management system documentation and batch traceability infrastructure demands capital outlays exceeding INR 2 crore for mid-tier fabricators. Working capital compression limits R&D spending.
- Hospital chain procurement centralization:Apollo and Max network-level tendering is compressing supplier margins and extending payment cycles to 90-120 days. Smaller fabricators face exclusion from institutional volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Orthopedic Braces and Supports Market |
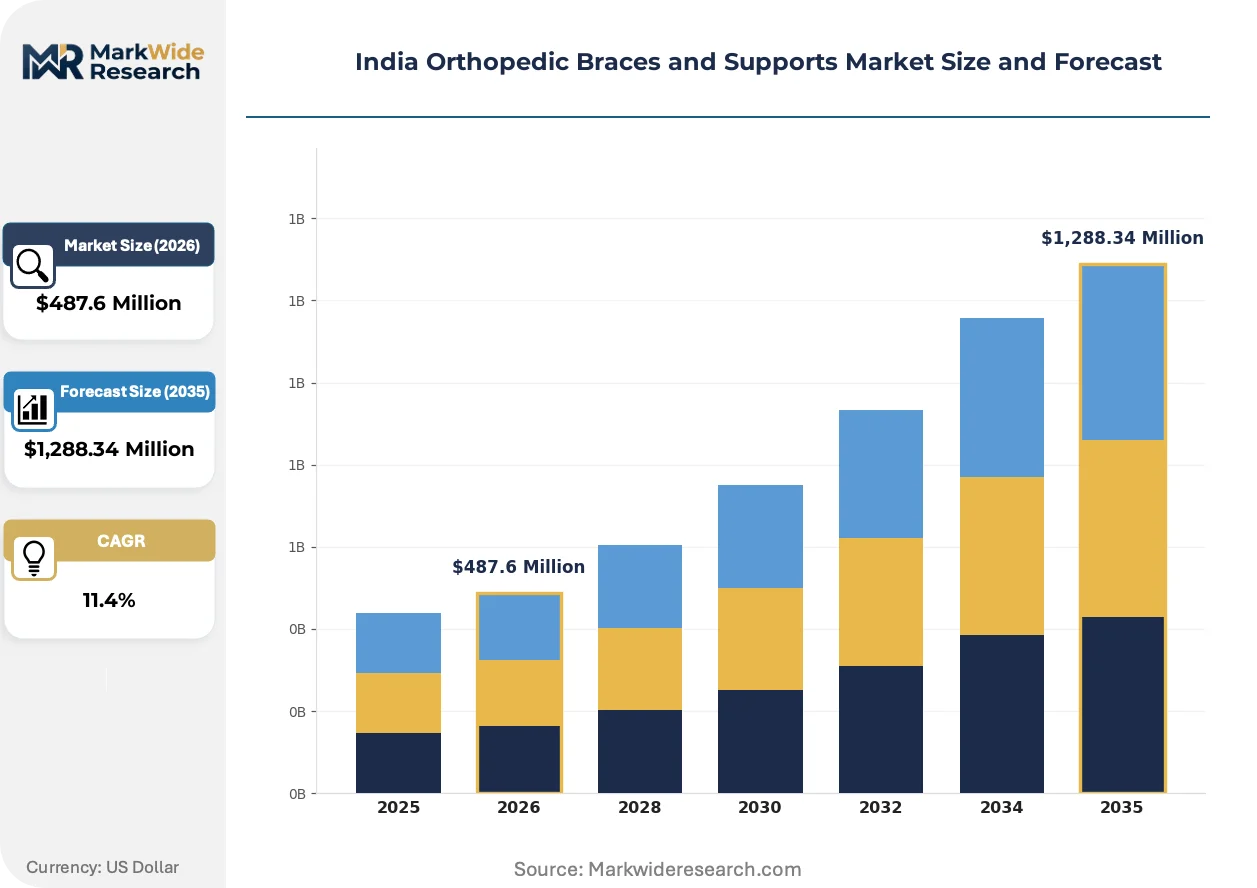
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Braces, Ankle Supports, Elbow Braces, Wrist Supports End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Material: Fabric, Plastic, Metal, Composite Distribution Channel: Online Retail, Medical Stores, Pharmacies, Direct Sales |
| Companies Covered | Tynor Orthotics, BSN Medical, Ascent Meditech Limited, Vision Meditech Pvt. Ltd., Ottobock, Össur, DeRoyal Industries, Bauerfeind, DJO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Orthopedic Braces and Supports Market Trends and Innovations
Digital fabrication and regulatory digitization are compressing product development cycles while expanding customization capabilities. Material science advances and distribution channel evolution are simultaneously reshaping competitive positioning.
Sensor-embedded braces are miniaturizing. MEMS accelerometers and pressure-sensitive textiles enable real-time gait analysis and compliance monitoring. Post-surgical rehabilitation centers in Bengaluru and Hyderabad are piloting connected devices for remote patient monitoring. This technology is miniaturizing the distinction between passive support and active therapeutic intervention, creating premium pricing tiers for data-enabled outcomes.
CDSCO's Medical Device Rules 2017 amendments are tightening post-market surveillance obligations. Adverse event reporting timelines have compressed from 30 days to 7 days for Class C and D devices. Domestic manufacturers in Ahmedabad and Vadodara are restructuring quality assurance departments to manage pharmacovigilance integration. Hinged knee braces and spinal orthoses face heightened scrutiny given their higher-risk classification.
Direct-to-consumer channels are fragmenting traditional medical store dominance. Urban millennials with sports injuries are researching brace specifications online before purchase. E-commerce platforms are deploying virtual fitting tools and chatbot-guided sizing. This shift is most visible in Maharashtra and Karnataka metropolitan markets where pharmacy retail density already exceeds national averages.
India Orthopedic Braces and Supports Market Segmentation
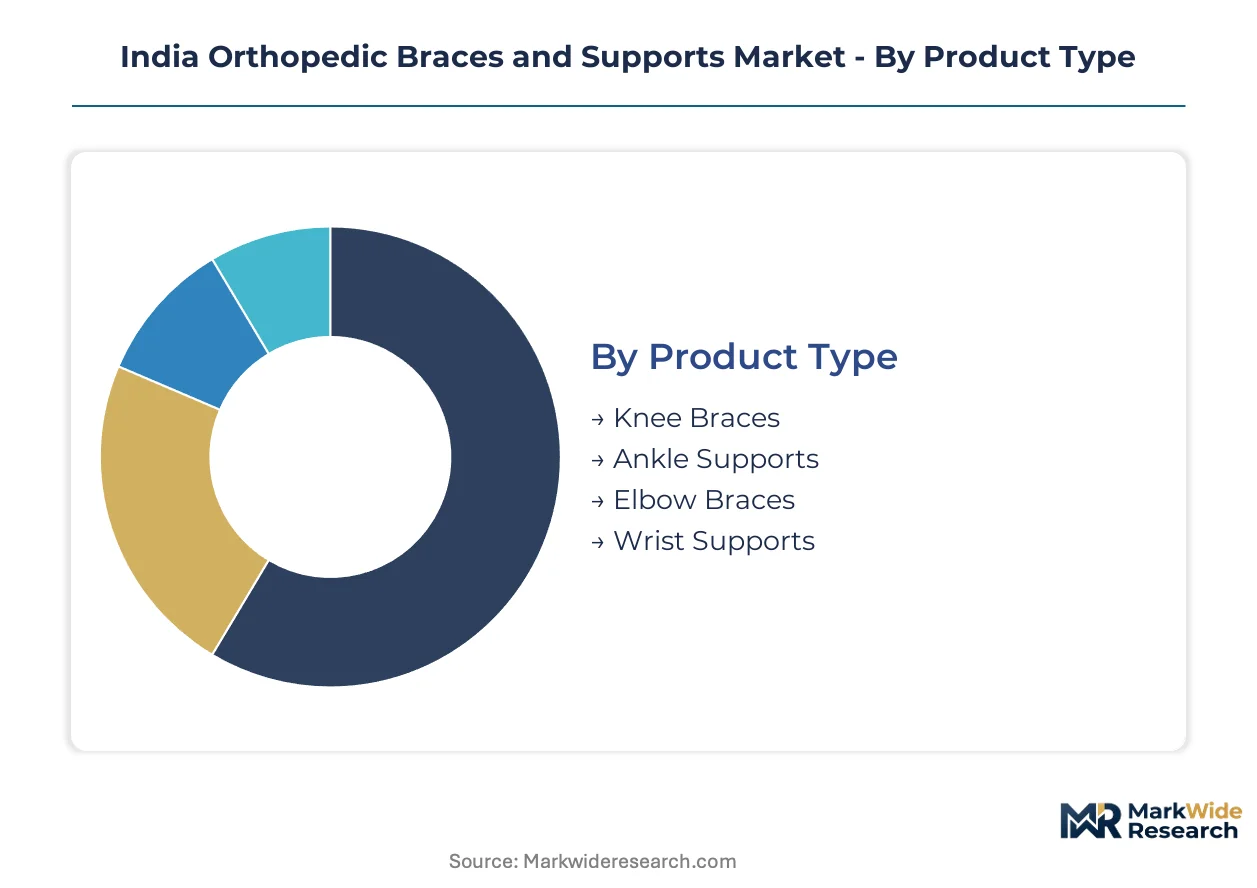
Orthopedic braces and supports in India fragment across four structural dimensions that determine pricing power, channel strategy, and regulatory exposure. Product type and end-user concentration in Maharashtra and Karnataka drive margin distribution, while material composition and distribution channel choices separate value-tier fabricators from premium-positioned specialists.
Product Type:
Margins pool disproportionately in post-surgical and sports-medicine categories where hinge engineering and customization commands price premiums.
- Knee Braces:Hinged and compression variants fabricated from neoprene blends and aluminum alloy frames address ligament reconstruction and osteoarthritis management. Mumbai-Pune corridor hospitals are consolidating procurement for post-ACL reconstruction protocols, with Apollo and Max networks driving volume concentration.
- Ankle Supports:Semi-rigid stirrup designs and lace-up fabric wraps dominate acute sprain management and chronic instability prevention. Tier-2 city cricket academies and football clubs are expanding institutional purchasing through Gujarat-based manufacturers supplying at sub-INR 800 price points.
- Elbow Braces:Counterforce straps and hinged immobilizers target tennis elbow and post-operative fixation.
- Wrist Supports:Cock-up splints and elastic compression sleeves address carpal tunnel syndrome and Colles fracture rehabilitation.
The dominant share belongs to Knee Braces, while Ankle Supports are gaining share fastest through sports medicine infrastructure expansion.
End User:
Procurement centralization patterns split volume between institutional tendering and direct patient cash-pay channels.
- Hospitals:Apollo, Max, and Fortis networks enforce centralized supply contracts with 90-120 day payment cycles, compressing supplier margins while demanding batch traceability and CDSCO documentation compliance.
- Clinics:Single-specialty orthopedic practices in Bengaluru and Hyderabad generate recurring demand for soft supports and prefabricated walking boots, with shorter procurement cycles than hospital chains.
- Home Care:Self-directed purchasers through Flipkart and Amazon health storefronts are migrating volume from medical stores, particularly for sub-INR 500 fabric supports.
- Rehabilitation Centers:Post-surgical facilities in Tamil Nadu and Karnataka are piloting sensor-embedded braces for remote monitoring, creating premium pricing tiers for data-enabled outcomes.
Hospitals retain volume leadership, though Home Care is expanding most quickly through e-commerce channel migration.
Material:
Cost tier stratification separates domestically moldable inputs from import-dependent aerospace-grade composites.
- Fabric:Neoprene blends and elastic textiles with compression gradient engineering dominate volume production through Gujarat textile-lamination clusters, with BIS certification timelines of 14-18 months constraining novel formulations.
- Plastic:Thermoformable polypropylene and polyethylene enable mass-customization of ankle-foot orthoses through repurposed dental technology equipment in Tamil Nadu manufacturing hubs.
- Metal:Lightweight aluminum alloys for hinge mechanisms and frame structures.
- Composite:Carbon-fiber and aerospace-grade laminates sourced from Germany and Japan for premium hinged braces, with currency volatility inflating landed costs and compressing margins for implant-grade specialists.
Fabric commands the largest volume share, yet Composite materials are climbing the fastest as post-surgical rehabilitation centers upgrade to lightweight rigid immobilization.
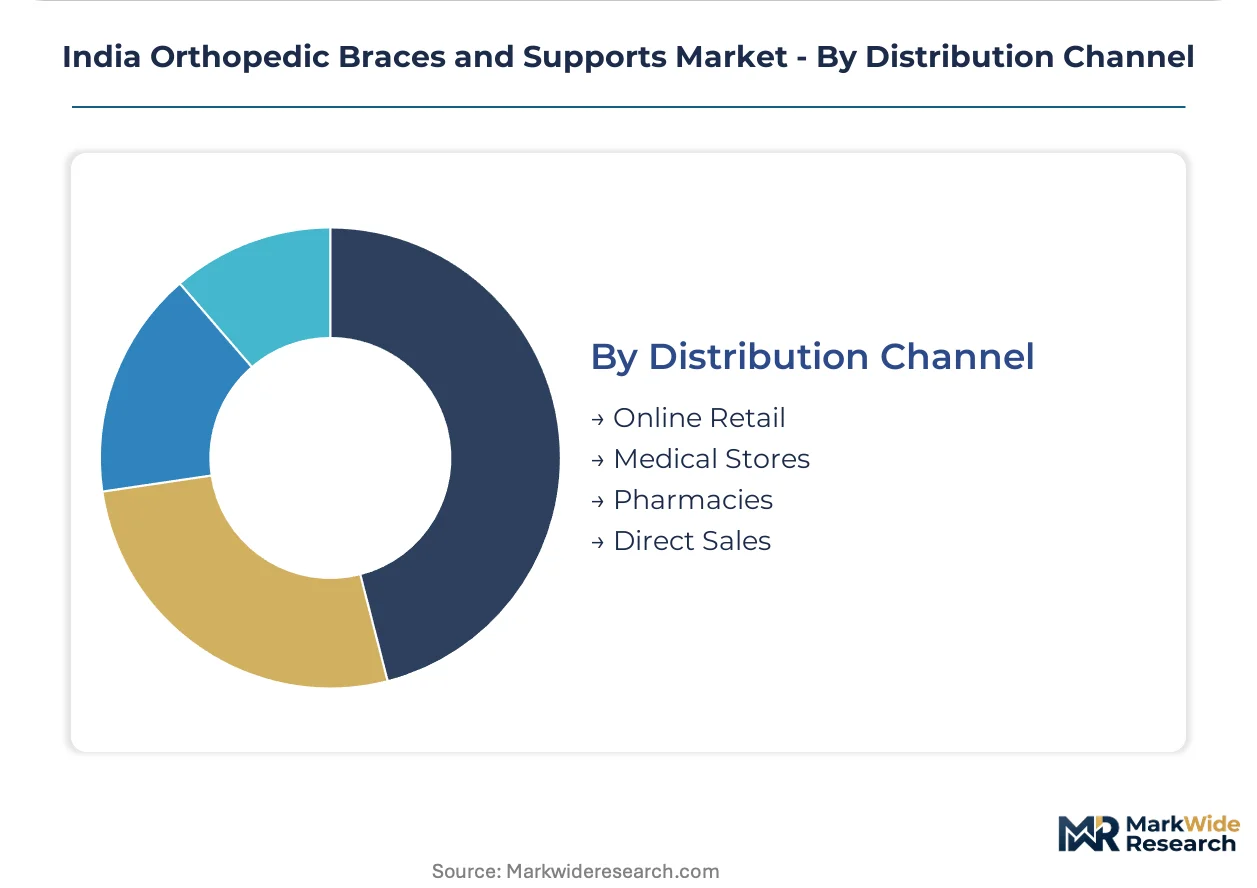
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition cost structures.
- Online Retail:Flipkart and Amazon dedicated orthopedic storefronts with virtual fitting tools and chatbot-guided sizing are capturing urban millennial demand, particularly in Maharashtra and Karnataka metropolitan markets where pharmacy retail density already exceeds national averages.
- Medical Stores:Traditional brick-and-mortar outlets retain dominance in tier-3 cities and rural districts where digital literacy and payment infrastructure constrain e-commerce penetration.
- Pharmacies:Chain pharmacy networks with in-store orthopedic sections.
- Direct Sales:Institutional procurement teams at Apollo and Max headquarters are consolidating supplier relationships and extending payment cycles, favoring capital-resilient manufacturers with INR 2 crore-plus quality infrastructure.
Medical Stores still hold the dominant position, though Online Retail is expanding most rapidly through platform investment in health category specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands premium pricing for carbon-composite hinged braces while Gujarat fabricators dominate sub-INR 500 neoprene volume tiers, creating a structural price-to-performance asymmetry across western India manufacturing corridors.
Maharashtra
Mumbai-Pune corridor hospitals drive demand for post-surgical rehabilitation braces through Apollo and Max network procurement centralization. CDSCO's tightened Class C device audits enforce 7-day adverse event reporting timelines for hinged knee systems. Thane-Aurangabad industrial zones host textile-lamination facilities upgrading BIS certification infrastructure to meet medical-grade standards.
Gujarat
Ahmedabad and Vadodara clusters manufacture fabric-based soft supports capturing tier-2 city volume through price-accessible positioning. PLI scheme incentives redirect capital toward domestic molding capabilities, compressing informal manufacturer participation. Surat textile engineering programs supply polymer chemistry talent for neoprene blend formulation to competing Gujarat fabricators.
Karnataka
Bengaluru sports medicine infrastructure and Hyderabad rehabilitation centers pilot sensor-embedded braces for remote patient monitoring. State disability program reimbursement tie-ins create sticky accounts in pediatric neuromuscular segments. Mysuru medical device parks attract thermoformable plastic equipment repurposed from dental technology clusters.
Tamil Nadu
Chennai and Coimbatore manufacturing hubs leverage existing precision engineering capabilities for ankle-foot orthosis mass-customization. CDSCO quality management system documentation demands exceed INR 2 crore for mid-tier fabricators, compressing working capital availability. Hosur industrial corridor hosts aluminum alloy frame production for hinge mechanism components.
Telangana
Hyderabad's expanding hospital chains consolidate supply contracts for post-ACL reconstruction protocols, extending payment cycles to 90-120 days. BIS certification bottlenecks of 14-18 months constrain novel textile-lamination combinations from domestic innovators. Genome Valley medical technology incubators support CAD-CAM integration for 3D-scanning orthotic customization.
India Orthopedic Braces and Supports Market Competitive Landscape
Concentration sits with domestic fabricators leveraging Gujarat manufacturing scale against multinational implant-grade specialists importing carbon-composite lines. The vendor base stratifies across three tiers: value-positioned neoprene blend producers, mid-market thermoplastic specialists, and premium aerospace-grade composite distributors. Two dominant competitive moves are reshaping positioning — hospital chain procurement centralization compressing supplier margins, and PLI scheme incentives accelerating domestic molding capacity expansion.
Among domestic fabricators, Tynor Orthotics exemplifies value-tier scale advantages through its Gujarat manufacturing footprint. DJO and Ottobock occupy premium positioning vectors, with the former representing multinational import-dependent archetypes and the latter anchoring pediatric neuromuscular specialization where state reimbursement programs create defensive account stickiness. These three players collectively illustrate the market's tripartite competitive structure.
| Leading Market Players |
|---|
| Tynor Orthotics |
| BSN Medical |
| Ascent Meditech Limited |
| Vision Meditech Pvt. Ltd. |
| Ottobock |
| Össur |
| DeRoyal Industries |
| Bauerfeind |
| DJO |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement centralization through 90-120 day payment cycles locks in supply access for Apollo and Max networks while compressing margin visibility for domestic fabricators competing against carbon-composite imports. This contract-structure pattern forces Gujarat-based manufacturers to absorb working capital strain or cede volume to multinational distributors with deeper balance sheets.
Pricing Analysis
Configured-to-order pricing for thermoformable ankle-foot orthoses commands 3-4x premiums over standard neoprene compression sleeves. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade composite hinged braces from aluminum-frame mid-market variants and sub-INR 500 fabric supports. Cost compression in the economy tier intensifies because BIS certification bottlenecks constrain novel textile-lamination entrants. Price sensitivity concentrates among tier-2 city cricket academies and football clubs sourcing institutional ankle supports, while post-surgical rehabilitation centers show lowest sensitivity for sensor-embedded monitoring devices.
Supply Chain Analysis
Germany and Japan anchor carbon-fiber and aerospace-grade laminate production for premium hinged brace components, while India and China dominate neoprene blend textile-lamination for volume-tier soft supports. Raw material dependencies include polymer chemistry feedstocks, aluminum alloy hinge mechanisms, and MEMS accelerometers for connected devices. Single-source vulnerability runs through aerospace-grade composite supply given currency volatility and concentrated German-Japanese exporter bases. Distribution runs through hospital chain procurement headquarters consolidating supplier relationships, alongside Flipkart and Amazon health storefronts capturing direct-to-consumer migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as PLI scheme incentives redirect capital toward domestic molding capabilities, compressing informal participation and elevating compliant manufacturer pricing power.
For Market Incumbents: Shield margin position by deepening backward integration into Gujarat textile-lamination clusters and securing BIS certification for novel compression gradient formulations before CDSCO audit timelines compress further. Hospital chain procurement centralization represents the core threat; channel control through exclusive Apollo and Max supply contracts offers defensive leverage. For New Entrants and Emerging Players: Lead with thermoformable plastic convergence in Tamil Nadu dental technology clusters, where repurposed CAD-CAM equipment enables mass-customization of ankle-foot orthoses at mid-market price points. Pediatric neuromuscular segments tied to state disability reimbursement programs offer the most penetrable white-space, with direct-to-clinic sales bypassing hospital tender complexity. For Investors and Strategic Acquirers: Capital is best deployed toward domestic fabricators with existing PLI scheme qualification and INR 2 crore-plus quality infrastructure capable of surviving CDSCO audit escalation. Long-term viability over a 5-10 year window favors operators with certified molding capabilities and sticky institutional accounts. The signal to watch is Ayushman Bharat procedure coverage expansion redistributing volume between public tenders and private cash-pay segments.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Quality Infrastructure Investment | BIS certification and pharmacovigilance documentation capabilities separate surviving fabricators from compressed informal competitors. |
| Hospital System Partnership | Apollo and Max network-level supply contracts lock in institutional volume despite extended 90-120 day payment cycles. |
| Reimbursement Strategy | State disability program tie-ins create multi-year replacement cycles with defensive account stickiness in pediatric neuromuscular segments. |
| Software Companion Development | Sensor-embedded braces with real-time gait analysis enable premium pricing tiers for data-enabled outcomes in Bengaluru rehabilitation centers. |
| Backward Integration into Textile-Lamination | Gujarat polymer chemistry capabilities and Surat engineering programs support captive neoprene blend formulation. |
Research Methodology
Desk research of CDSCO medical device registration databases, BIS certification records, and hospital procurement tender documents preceded structured interviews with biomedical engineers, orthopedic surgeons, GPO contracts managers, and Gujarat-based manufacturing operations heads. Primary fieldwork across Mumbai-Pune corridor hospitals and Ahmedabad-Vadodara industrial zones combined with secondary validation from PLI scheme disbursement records and state disability program reimbursement schedules. Bottom-up patient volume modeling and top-down healthcare expenditure triangulation anchored market size estimation.
Variance decomposition across product type, material composition, end-user concentration, and distribution channel dimensions shaped analytical framework construction throughout the forecast period. CAGRs derived from procedure volume elasticity to sports injury incidence, Ayushman Bharat coverage expansion trajectories, and import substitution rates for carbon-composite materials. Modeled inputs included hinge brace adoption in post-ACL reconstruction protocols and e-commerce penetration rates for self-application soft supports.
Forecasts assume regulatory continuity in CDSCO medical device classification and PLI scheme incentive structures; material policy shifts would require re-modeling. Specific risks include BIS certification timeline extensions beyond 18 months, abrupt currency volatility affecting German-Japanese composite landed costs, and physiotherapy protocol substitution shortening brace-wear duration. Recalibration cycles align with material shifts in hospital chain procurement centralization and state-level disability program reimbursement adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Physiotherapy Devices Market