
 Wrist Replacement Orthopedic Devices Market | 2026-2036
Wrist Replacement Orthopedic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wrist Replacement Orthopedic Devices Market Analysis
Patient-specific implant modeling is narrowing the gap between off-the-shelf designs and anatomical variation, forcing manufacturers to retool digital workflows. Stryker Corporation leverages its proprietary preoperative planning software to anchor premium positioning in robotic-assisted wrist arthroplasty. Integra LifeSciences competes through focused R&D intensity in pyrocarbon hemiarthroplasty systems, while Zimmer Biomet dominates North American hospital contracts through backward integration into cobalt-chrome casting.
Wrist replacement orthopedic devices encompass total and partial arthroplasty systems engineered to restore carpal kinematics, typically incorporating cobalt-chrome or titanium alloy radial components articulating against polyethylene or pyrocarbon carpal inserts manufactured via precision CNC machining and vacuum plasma spraying for osseointegration. These devices serve patients with post-traumatic arthritis, rheumatoid destruction, or scapholunate advanced collapse where salvage procedures fail. Fixed-bearing total wrist arthroplasty retains the largest installed base among product configurations, though adjustable modular systems capture expanding margin pools as revision rates drive demand for intraoperative customization. Minimally invasive surgical approaches represent the fastest-growing technology segment, compressing recovery windows and shifting eligible procedures toward outpatient facilities.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for CE marking access across European markets. ISO 5832 standards for metallic implant materials establish baseline biocompatibility thresholds that shape raw material supplier qualification and downstream testing costs. Stakeholders must monitor evolving CMS procedural reimbursement codes for outpatient total wrist arthroplasty, as site-of-service payment differentials will determine capital allocation between hospital and ambulatory surgical center channels.
Market Dynamics
The wrist replacement orthopedic devices market pivots on outpatient surgical migration, where CMS reimbursement differentials between hospital and ambulatory settings are compressing procedure economics and forcing manufacturers to reconfigure distribution channels.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined premarket notification framework accelerates commercialization timelines for metal-on-polymer implant systems, reducing regulatory friction for manufacturers entering the US market.
- Cobalt-Chrome Casting Integration:Backward integration into precision casting operations secures supply chain control over critical radial component materials, stabilizing input quality for tier-one manufacturers.
- Orthopedic Clinic Expansion:Rising patient volumes in specialized outpatient orthopedic facilities concentrate demand for minimally invasive wrist arthroplasty systems with compressed recovery protocols.
Market Restraints
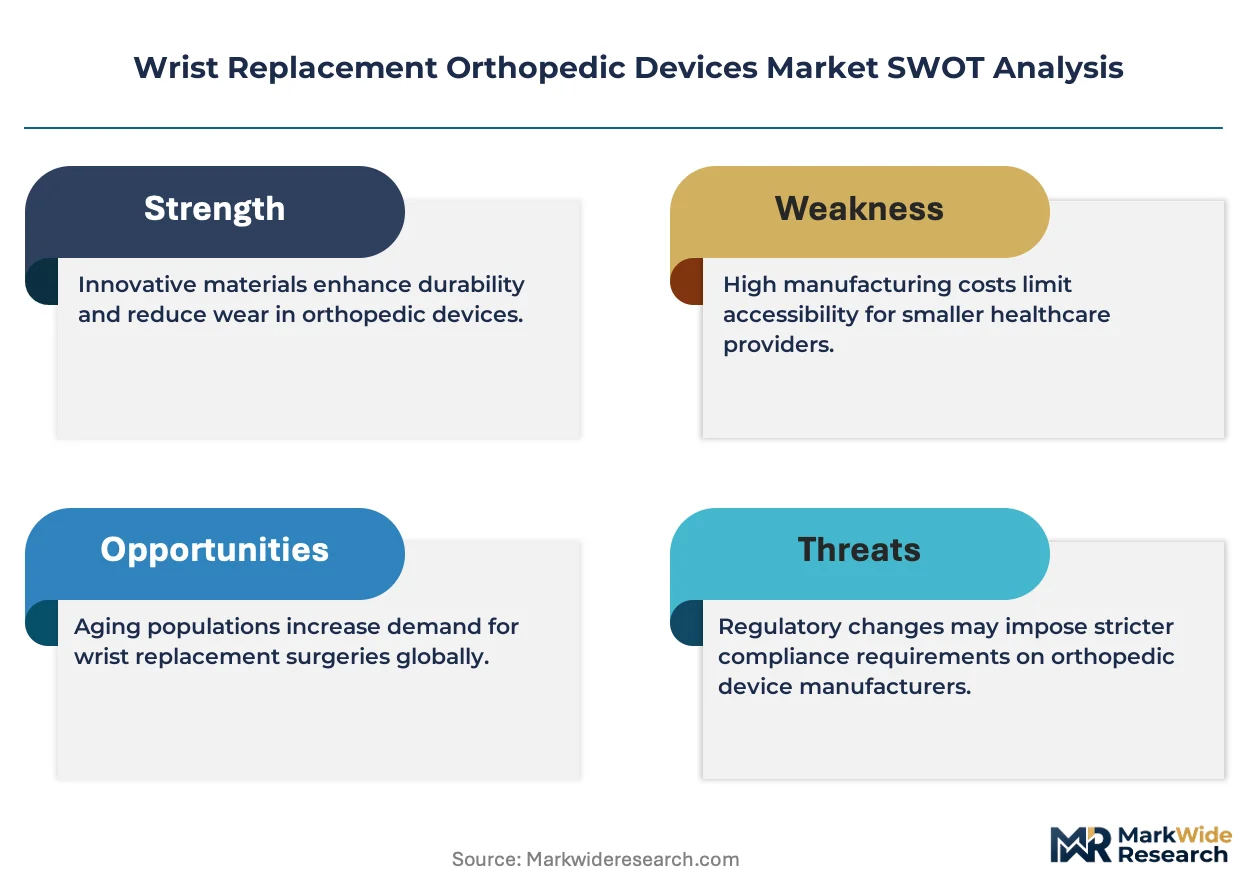
- Polyethylene Wear Debris:Long-term osteolysis risk from particulate generation in metal-on-polymer articulations limits implant longevity and drives revision procedure costs.
- EU MDR Clinical Evidence Burden:Strengthened post-market surveillance and clinical data requirements for CE marking extend time-to-market and inflate regulatory compliance expenditures for European access.
- Pyrocarbon Supply Concentration:Limited qualified suppliers of medical-grade pyrocarbon for hemiarthroplasty inserts create single-source vulnerability and price volatility for specialized carpal components.
Strategic Opportunities
- Ambulatory Surgical Center Channel:Site-of-service payment differentials under Medicare favor capital allocation toward outpatient-capable implant systems with simplified instrumentation.
- Patient-Specific Implant Modeling:Digital preoperative planning software converges with additive manufacturing workflows to enable anatomically matched radial components for complex revision cases.
- ISO 5832 Material Certification:Biocompatibility standardization creates competitive moats for manufacturers with validated titanium alloy and cobalt-chrome supply chains against unqualified entrants.
Industry Challenges
- Robotic-Assisted Surgical Training:The specialized skill set required for computer-navigated wrist arthroplasty exceeds current fellowship program output, constraining adoption velocity.
- Legacy Hospital Contract Lock-In:Incumbent manufacturers with multi-year purchasing agreements at integrated delivery networks block market access for modular system innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrist Replacement Orthopedic Devices Market |
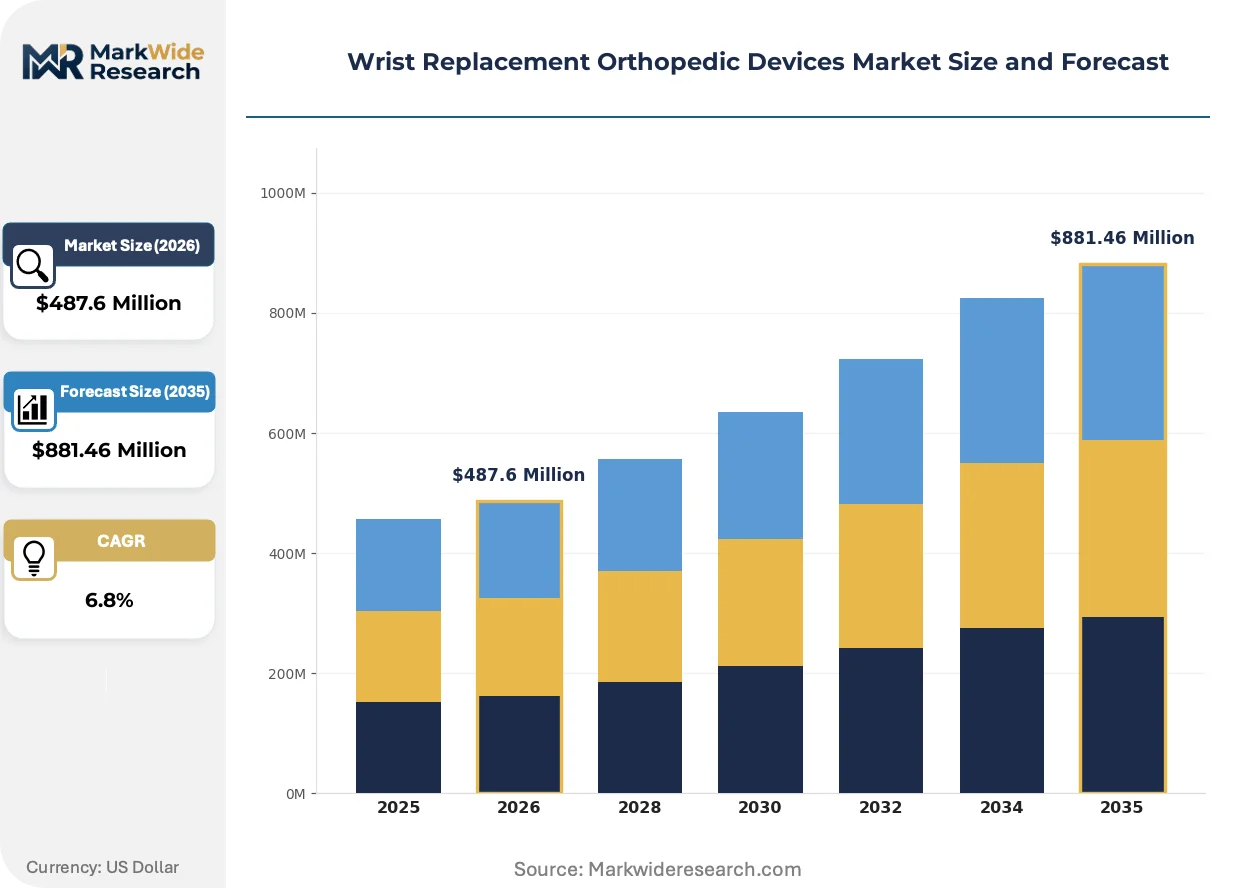
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Semi-Constrained, Constrained, Adjustable Material: Titanium, Stainless Steel, Polymer, Ceramic End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Outpatient Facilities Technology: Minimally Invasive Surgery, Robotic-Assisted Surgery, Conventional Surgical Techniques, Hybrid Approaches |
| Companies Covered | Smith & Nephew, CONMED Corporation, Stryker Corporation, Integra LifeSciences, DJO Global Inc., Johnson & Johnson, Aesculap Implant Systems LLC, Acumed LLC, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrist Replacement Orthopedic Devices Market Emerging Trajectories
Digital preoperative planning is collapsing traditional boundaries between implant design and surgical execution, forcing manufacturers to compete on software-integrated ecosystems rather than hardware alone.
Adjustable modular wrist arthroplasty systems with intraoperative customization capabilities are collapsing the distinction between primary and revision implant configurations. Academic medical centers with high-complexity caseloads adopt these platforms fastest, compressing the addressable market for fixed-bearing legacy designs and reallocating R&D budgets toward software-defined instrumentation.
The EU Medical Device Regulation's strengthened clinical evidence requirements for CE marking are compressing the competitive field to manufacturers with robust post-market surveillance infrastructure. Mid-tier suppliers lacking European notified body relationships face exclusion from the second-largest addressable market, consolidating procurement options for hospital systems.
Service-line unbundling at US health systems separates implant procurement from surgical facility fees, enabling direct manufacturer-to-ASC contracting that bypasses traditional hospital purchasing committees. This channel fragmentation concentrates volume in high-throughput outpatient facilities in Texas and Florida, where certificate-of-need restrictions are weakest.
Wrist Replacement Orthopedic Devices Market Segmentation
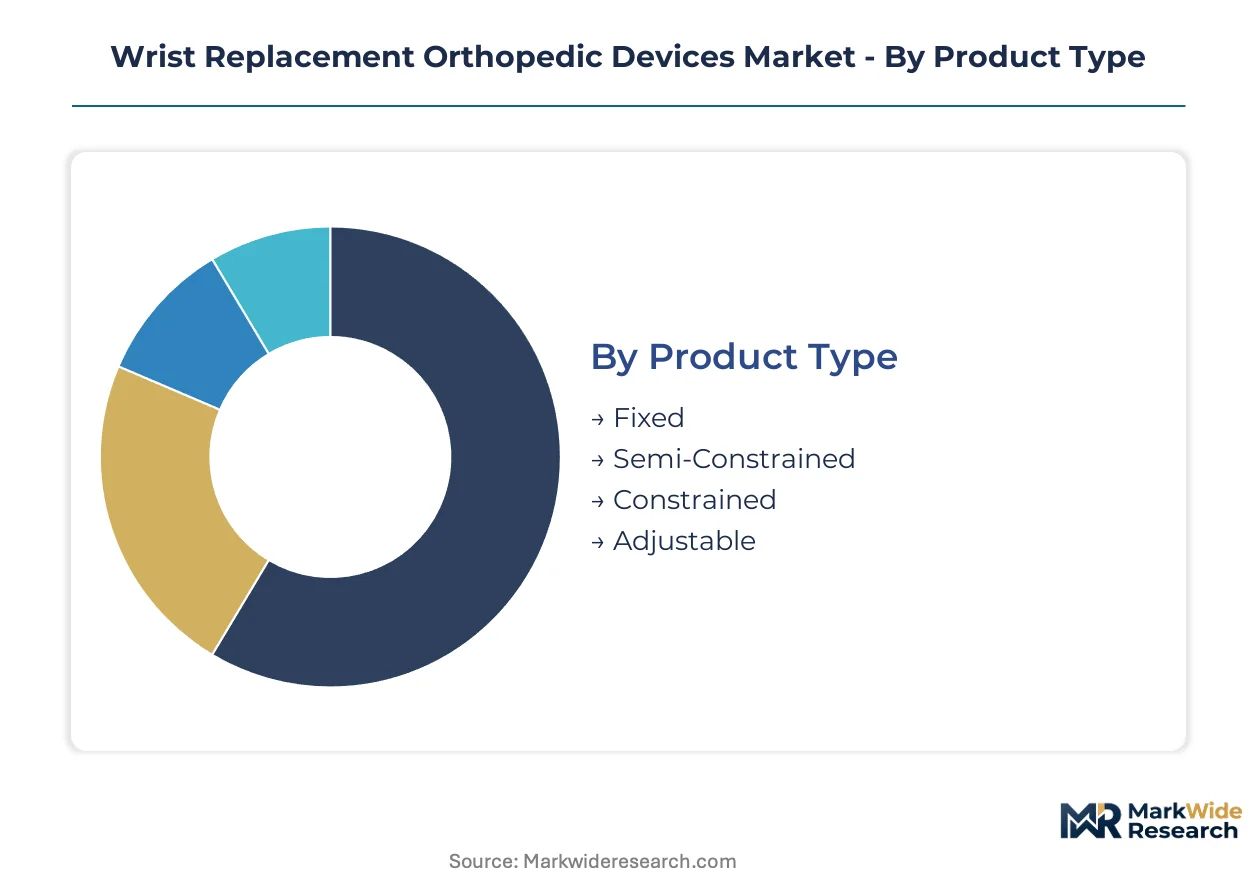
Wrist replacement orthopedic devices segment along four axes that determine procurement patterns and clinical utility. Product type and material selection drive revision economics, while end-user channel and surgical technology shape go-to-market configuration for manufacturers.
Product Type:
Fixed-bearing designs cycle through inventory slowly due to established surgeon familiarity, while adjustable systems turn faster as revision caseloads expand and customization protocols mature.
- Fixed:Non-modular radial and carpal components lock into predetermined alignment angles. Hospital systems in the United States favor these for primary arthroplasty volumes where surgical training emphasizes standardized technique over intraoperative flexibility.
- Adjustable:Modular radial stems and variable carpal plates permit real-time tension and alignment correction. Orthopedic clinics in Texas and Florida adopt these fastest where outpatient migration compresses recovery windows and revision preparedness matters.
- Semi-Constrained:Partially stabilized articulation permits limited motion arc with retained ligamentous support.
- Constrained:Rigid linkage between radial and carpal components sacrifices motion for stability in salvage cases.
Fixed configurations anchor the volume base while Adjustable gains share at the steepest rate.
Material:
Cost tiers separate segments sharply, with titanium alloys commanding premium positioning against commodity stainless steel and experimental ceramics.
- Titanium:Ti-6Al-4V ELI alloy delivers superior osseointegration through vacuum plasma-sprayed porous coatings. German and Swiss manufacturers source this grade exclusively from ISO 5832-3 qualified suppliers, locking in biocompatibility certification that blocks unqualified entrants.
- Polymer:Cross-linked polyethylene inserts articulate against metal radial heads in metal-on-polymer systems. FDA 510(k) clearance pathways favor these pairings, accelerating commercialization timelines for US-focused manufacturers against ceramic alternatives requiring PMA scrutiny.
- Stainless Steel:316LVM grade persists in cost-sensitive hemiarthroplasty components.
- Ceramic:Alumina and zirconia-toughened alumina reduce wear debris but fracture risk limits application.
Polymer-metal pairings dominate procedure counts while Titanium expands most quickly in premium revision segments.
End User:
Volume concentrates in hospital inpatient settings, though margin pools shift toward outpatient channels where site-of-service payment differentials restructure procurement economics.
- Hospitals:Integrated delivery networks negotiate multi-year purchasing agreements that lock in cobalt-chrome casting supply chains. Academic medical centers in Boston and Philadelphia anchor complex revision caseloads requiring explant analysis and custom component fabrication.
- Outpatient Facilities:Ambulatory surgical centers in certificate-of-need-free states concentrate minimally invasive wrist arthroplasty volume. Medicare reimbursement codes favor these settings, compressing implant pricing while expanding procedure accessibility.
- Orthopedic Clinics:Specialized hand surgery practices in suburban markets.
- Rehabilitation Centers:Post-acute facilities managing conservative therapy before surgical candidacy.
Hospitals retain the installed base while Outpatient Facilities climb the fastest as migration accelerates.
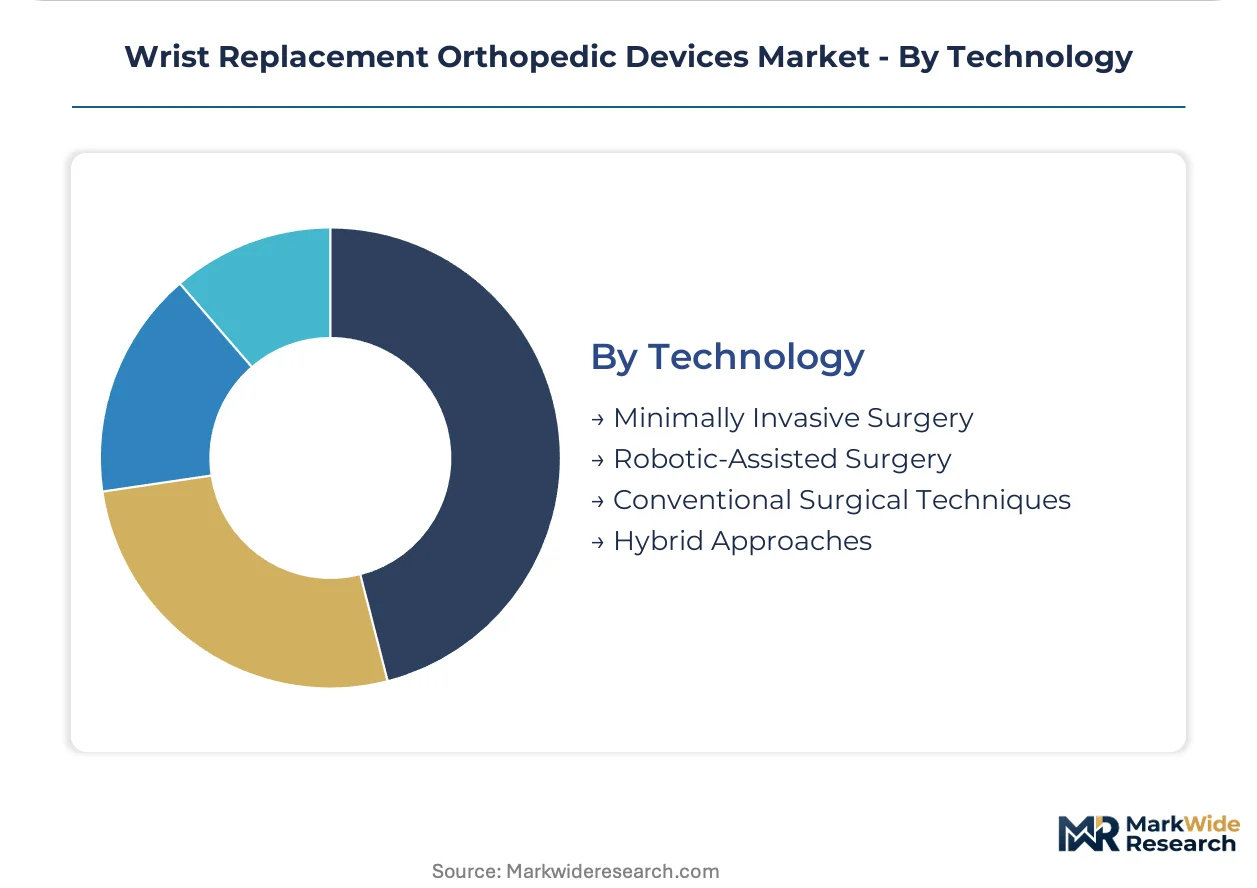
Technology:
Maturity curves diverge sharply, with conventional open approaches plateauing as robotic-assisted platforms absorb training investment and capital allocation.
- Minimally Invasive Surgery:Limited-incision approaches preserve extensor tendon integrity and compress rehabilitation timelines. Stryker Corporation anchors this segment through proprietary preoperative planning software that integrates with dorsal mini-incision instrumentation.
- Robotic-Assisted Surgery:Computer-navigated implant positioning targets sub-millimeter alignment accuracy. Fellowship programs in Baltimore and Cleveland produce insufficient trained surgeons, constraining adoption velocity despite capital equipment subsidies from manufacturers.
- Conventional Surgical Techniques:Open dorsal exposure with extensor tendon tenotomy persists in low-volume community settings.
- Hybrid Approaches:Mini-open exposure with computer-guided drilling templates.
Conventional techniques anchor the volume base while Robotic-Assisted Surgery gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in wrist replacement orthopedic devices tilt toward net-import positions in most advanced economies, with specialized component manufacturing concentrating in Germany and Switzerland while procedure volume concentrates in the United States and Japan. Currency-adjusted procurement costs are widening the arbitrage window for Asian contract manufacturers supplying cobalt-chrome castings to European OEMs.
United States
Medicare site-of-service payment differentials are compressing hospital inpatient margins and accelerating ambulatory surgical center migration in Texas and Florida. The FDA's 510(k) premarket notification framework maintains the fastest regulatory pathway for metal-on-polymer systems. Academic medical centers in Boston and Philadelphia anchor complex revision caseloads requiring explant analysis and custom fabrication protocols.
Germany
ISO 5832-3 qualified titanium alloy suppliers in Baden-Württemberg and Bavaria lock in biocompatibility certification that blocks unqualified third-country entrants. The EU Medical Device Regulation's strengthened clinical evidence requirements extend CE marking timelines and inflate compliance expenditures. Precision casting clusters around Stuttgart and Munich supply cobalt-chrome radial components to tier-one manufacturers across the continent.
Switzerland
Swissmedic oversight of pyrocarbon hemiarthroplasty systems maintains rigorous post-market surveillance that filters out mid-tier competitors. Medical-grade pyrocarbon supply concentrates around Solothurn and Neuchâtel, creating single-source vulnerability for carpal insert manufacturers. The country's bilateral MRA with the FDA accelerates parallel US-EU commercialization for domestic innovators.
Japan
PMDA reimbursement pricing reviews under the biennial Central Social Insurance Medical Council schedule compress implant margins while expanding procedure accessibility in Kanto and Kansai regions. Aging demographics in Tokyo and Osaka metropolitan areas drive rheumatoid arthritis caseloads toward salvage arthroplasty thresholds. Domestic manufacturers face METI pressure to localize cobalt-chrome supply chains away from European dependency.
United Kingdom
NHS England's MedTech Funding Mandate accelerates uptake of minimally invasive wrist arthroplasty systems with proven outpatient recovery protocols. MHRA post-Brexit regulatory divergence from EU MDR creates dual-track compliance costs for manufacturers serving both markets. Private orthopedic clinic chains in London and the Southeast concentrate demand for adjustable modular systems with premium positioning.
Wrist Replacement Orthopedic Devices Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified orthopedic conglomerates with captive casting operations, mid-scale specialists in pyrocarbon hemiarthroplasty, and regional contract manufacturers supplying precision-machined components. Strategic archetypes include backward-integrated material controllers, software-anchored robotic platforms, and pure-play hand surgery device specialists. Dominant competitive moves span M&A-driven portfolio diversification into adjacent upper-extremity segments and technology licensing partnerships for preoperative planning software integration.
Within the diversified conglomerate tier, Stryker Corporation and Zimmer Biomet represent contrasting geographic and integration strategies, with the former anchoring robotic-assisted positioning and the latter dominating North American hospital contract channels through in-house cobalt-chrome production. Integra LifeSciences occupies a specialist position in pyrocarbon hemiarthroplasty systems, exemplifying the R&D-intensive archetype focused on biomaterial differentiation rather than scale-driven procurement leverage.
| Leading Market Players |
|---|
| Smith & Nephew |
| CONMED Corporation |
| Stryker Corporation |
| Integra LifeSciences |
| DJO Global Inc. |
| Johnson & Johnson |
| Aesculap Implant Systems LLC |
| Acumed LLC |
| Zimmer Biomet |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors absorb titanium alloy shipments from Baden-Württemberg suppliers, with container rate volatility feeding directly into implant pricing spreads between European OEMs and US distributors. This logistics cost dynamic amplifies the margin pressure on mid-tier manufacturers lacking captive cobalt-chrome casting capacity, while tier-one players with backward-integrated supply chains preserve pricing power through input cost insulation.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) clearance tier and ISO 5832-3 material certification grade driving the sharpest price spreads. Cost compression in standard-grade metal-on-polymer systems is intensifying because Asian contract manufacturers are undercutting European casting quotes. Ambulatory surgical centers exhibit the highest price sensitivity due to Medicare reimbursement caps, while academic medical centers with revision caseloads show the least.
Supply Chain Analysis
Swiss and German precision foundries hold captive capacity for medical-grade pyrocarbon and cobalt-chrome radial components, with secondary machining clusters concentrated in Switzerland, Germany, and the United States. Raw material flows draw from ISO 5832-qualified titanium alloy suppliers, cross-linked polyethylene resin producers, and vacuum plasma spraying equipment manufacturers. Single-source vulnerability in pyrocarbon supply from Solothurn-Neuchâtel concentration creates structural risk. Distribution runs through GPO-negotiated hospital contracts and direct-to-ASC manufacturer agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wrist replacement orthopedic devices market represents high-growth disruption as robotic-assisted surgical platforms and patient-specific implant modeling converge to displace conventional open techniques. FDA 510(k) clearance acceleration for software-integrated systems serves as the primary regulatory inflection compressing commercialization timelines.
For Market Incumbents: Entrench cobalt-chrome casting control through upstream facility investment in Bavaria or Baden-Württemberg to neutralize Asian contract manufacturer price pressure. Lock multi-year GPO agreements with integrated delivery networks before modular system innovators penetrate hospital purchasing committees. Prioritize software companion development for robotic platforms to defend against pure-play digital surgery entrants.
For New Entrants and Emerging Players: Outpatient orthopedic clinics in Texas and Florida present the most penetrable white-space target, where certificate-of-need-free environments and Medicare site-of-service differentials concentrate minimally invasive procedure volume. Adjustable modular systems for revision preparedness offer the fastest adoption pathway. Pursue direct manufacturer-to-ASC contracting models that bypass legacy hospital purchasing lock-in.
For Investors and Strategic Acquirers: EU MDR strengthened clinical evidence requirements reshape the acquisition landscape by filtering out mid-tier suppliers lacking European notified body relationships. Five-to-ten-year viability favors targets with validated ISO 5832 supply chains and post-market surveillance infrastructure. Watch FDA 510(k) clearance velocity for software-integrated platforms as the signal indicating competitive consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence investment secures access to the second-largest addressable market. |
| Hospital System Partnership | Multi-year GPO agreements with integrated delivery networks block modular system innovators. |
| Software Companion Development | Preoperative planning integration anchors premium positioning in robotic-assisted wrist arthroplasty. |
| Backward Integration into Casting | Captive cobalt-chrome production stabilizes input quality against Asian contract manufacturer pricing. |
| Reimbursement Strategy | CMS outpatient procedure code optimization accelerates ambulatory surgical center channel migration. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up implant volume modeling and top-down market sizing triangulated demand estimates.
Forecast inputs span product type segmentation across fixed-bearing and adjustable modular configurations, material grade tiers from standard stainless steel to premium titanium alloy, end-user channel splits between hospital inpatient and ambulatory surgical center settings, and technology adoption curves for minimally invasive versus robotic-assisted approaches. CAGRs derive from procedure volume elasticity to demographic aging patterns and reimbursement policy shifts. Surgical training program output constraints and pyrocarbon supply concentration serve as industry-specific forecast modifiers.
Practitioners should monitor FDA 510(k) clearance velocity for software-integrated platforms, EU MDR notified body relationship stability, and CMS outpatient procedure code revisions for early signals of competitive inflection. Quarterly review of ambulatory surgical center certificate-of-need policy changes and pyrocarbon supplier qualification status is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market