
 Digital Shaker Market | 2026-2036
Digital Shaker Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Shaker Market Insights
Brushless DC motor assemblies are replacing brushed motor systems across mid-range and premium digital shakers, and this substitution is realigning maintenance schedules, energy consumption curves, and total cost of ownership calculations for procurement teams. Thermo Fisher Scientific leverages its service network density to sustain recurring revenue from installed-base upgrades. Eppendorf anchors its position through precision control firmware developed for cell culture workflows. IKA competes on modularity, offering interchangeable platform configurations that reduce capital redundancy.
A digital shaker is an electromechanical laboratory device that generates controlled orbital, reciprocal, or three-dimensional agitation for liquid samples, typically operating at programmable speeds between 50 and 500 rpm with temperature control ranges from ambient to 80 degrees Celsius. Its primary purpose is to ensure homogeneous mixing, aeration, or suspension in cell culture, microbial fermentation, and analytical chemistry protocols. Countertop units occupy the dominant revenue position due to their flexibility across academic and industrial settings, while touchscreen interfaces command margin premiums over analog controls. Bluetooth-enabled models represent the fastest-expanding technology segment as laboratories integrate equipment into electronic lab notebook ecosystems.
FDA 21 CFR Part 11 compliance requirements shape software architecture decisions for digital shaker manufacturers targeting pharmaceutical validation workflows, while EMA GMP Annex 15 guidelines influence qualification documentation and IQ/OQ/PQ protocol bundling in Europe. ISO 9001 quality management certification functions as a baseline market-access threshold for institutional procurement tenders. Stakeholders must monitor evolving cybersecurity standards for connected laboratory equipment as network-enabled shakers become standard in regulated environments.
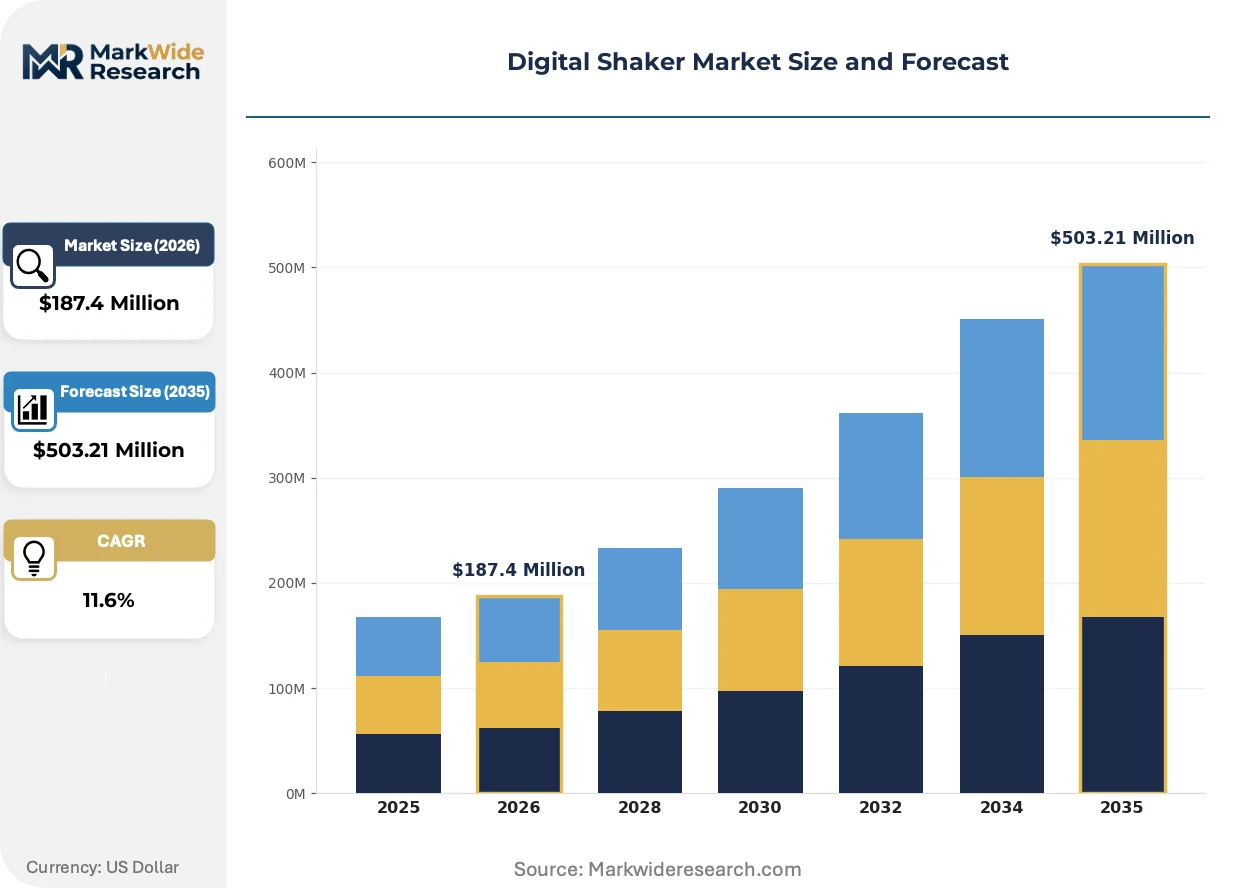
Market Dynamics
Brushless DC motor assemblies are displacing brushed systems across digital shaker portfolios, forcing procurement teams to recalculate total cost of ownership around energy curves and maintenance intervals rather than upfront capital expenditure alone.
Growth Catalysts
- FDA 21 CFR Part 11:Validation requirements for electronic records in pharmaceutical workflows drive replacement cycles for non-compliant legacy equipment.
- Cell culture automation:Biopharmaceutical laboratories in Germany and the United States expand orbital shaker fleets to support reproducible suspension protocols.
- Bluetooth-enabled connectivity:Electronic lab notebook integration mandates reshape R&D facility equipment specifications.
Market Restraints
- Premium motor magnet costs:Rare earth element price volatility compresses margins on brushless DC assemblies.
- Qualification documentation burden:EMA GMP Annex 15 IQ/OQ/PQ protocol bundling extends European sales cycles.
- Used equipment channels:Refurbished certified pre-owned shakers divert mid-budget academic purchases.
Strategic Opportunities
- India biopharma clusters:CDSCO-aligned contract manufacturing organizations build out analytical laboratories with import-substitution incentives.
- Cloud-based predictive maintenance:Sensor-embedded shakers enable subscription service models displacing break-fix contracts.
- Modular platform architectures:Interchangeable flask clamps and microplate adapters reduce capital redundancy across multi-protocol facilities.
Industry Challenges
- Cybersecurity certification gaps:Network-connected shakers lack harmonized IEC 62443 implementation timelines, delaying hospital and pharmaceutical deployments.
- Field service technician scarcity:Brushless motor diagnostics and firmware calibration require specialized training programs that OEMs must build from limited talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Shaker Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Countertop, Commercial, Industrial End User: Restaurants, Cafes, Catering Services, Home Users Application: Food & Beverage, Healthcare, Research, Education Technology: Touchscreen, Bluetooth, Wi-Fi, Analog |
| Companies Covered | Thermo Fisher Scientific, Eppendorf, Brüel & Kjær, IKA, Corning Incorporated, PCB Piezotronics, LDS Test and Measurement, Ohaus Corporation, IMV Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Shaker Market Trends and Innovations
Digital shaker architectures are fragmenting into three distinct innovation vectors: electromechanical component substitution, software compliance layering, and service model reinvention. Each vector carries divergent margin implications for incumbent suppliers.
Brushless DC motor technology is modularizing shaker design by decoupling drive systems from platform mechanics. Biopharmaceutical contract manufacturers in the United States and Germany are specifying these motors for 24/7 continuous culture protocols. This substitution is modularizing supplier relationships, allowing laboratories to source motors and control firmware from different vendors than mechanical platforms.
EMA GMP Annex 15 and FDA 21 CFR Part 11 are converging on equipment qualification documentation. Pharmaceutical validation teams now demand pre-written IQ/OQ/PQ protocols bundled with purchase orders. European academic consortia purchasing for shared core facilities are adopting these same documentation standards, compressing the price premium between research-grade and GMP-grade equipment.
After-sales service unbundling is accelerating as laboratories separate maintenance contracts from initial equipment procurement. North American contract research organizations now negotiate multi-vendor service agreements through third-party laboratory asset management firms. This pattern is most visible in Boston and San Diego biotech clusters, where specialized service providers aggregate calibration and preventive maintenance across competing shaker brands.
Digital Shaker Market Segmentation
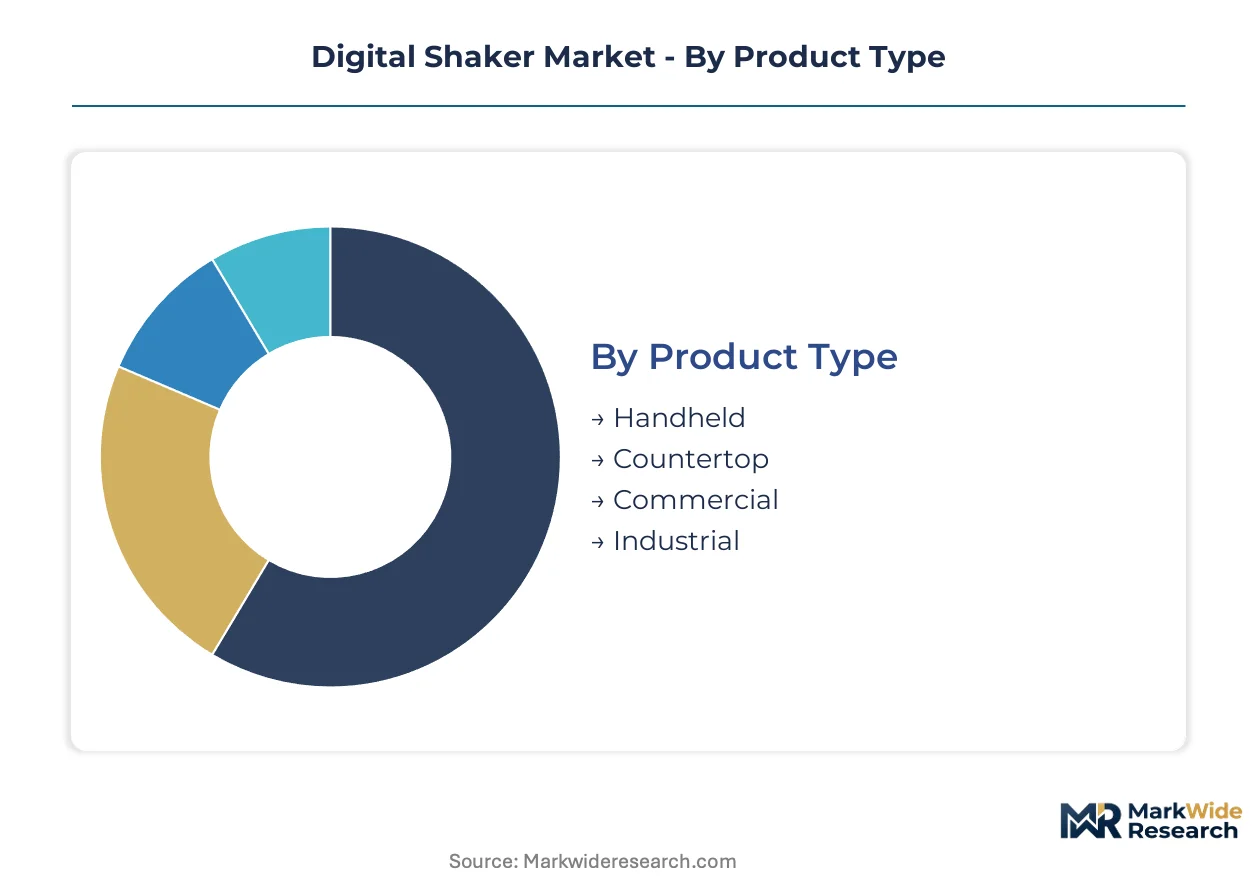
Digital shaker procurement decisions diverge sharply across laboratory settings. Academic core facilities prioritize modularity and capital efficiency, while pharmaceutical validation teams demand compliance architecture and documentation bundles.
Product Type:
Platform footprint and motor duty cycle define the specification axis for laboratory shakers.
- Countertop:Compact orbital platforms with brushless DC motors dominate biopharmaceutical contract manufacturing in Germany and the United States. These units balance 24/7 continuous culture protocols with flexible placement across multi-purpose laboratory benches.
- Industrial:Heavy-duty floor-standing systems integrate temperature control ranges up to 80 degrees Celsius for microbial fermentation scale-up. Demand concentrates in CDSCO-aligned contract manufacturing organizations across Indian biopharma clusters seeking import-substitution incentives.
- Handheld:Battery-operated portable units serve field sampling and point-of-care diagnostic workflows.
- Commercial:Mid-capacity systems bridge research-grade flexibility with production-scale throughput requirements.
Countertop units lead on scale; industrial systems lead on momentum.
End User:
Capital allocation patterns separate institutional procurement from individual purchasing authority.
- Research:University core facilities and national laboratories specify interchangeable platform configurations to reduce redundancy across cell culture, microbial fermentation, and analytical chemistry protocols. EMA GMP Annex 15 documentation standards now penetrate European academic consortia, compressing price premiums between research-grade and GMP-grade equipment.
- Healthcare:Hospital clinical laboratories demand FDA 21 CFR Part 11 compliance for electronic records in diagnostic workflows. Cybersecurity certification gaps under IEC 62443 delay network-connected deployments despite ELN integration mandates.
- Restaurants:Food and beverage preparation applications utilize basic orbital agitation for ingredient homogenization.
- Catering Services:Mobile food service operations require portable, durable shaker platforms for field deployment.
- Home Users:Consumer-grade units serve hobbyist fermentation and small-batch beverage production.
Research institutions anchor volume commitment; healthcare systems drive compliance premium capture.
Application:
Protocol specificity determines control firmware requirements and qualification documentation depth.
- Research:Cell culture automation demands programmable speeds between 50 and 500 rpm with precision orbital control. Biopharmaceutical laboratories in Boston and San Diego biotech clusters expand shaker fleets to support reproducible suspension protocols under tightening FDA validation requirements.
- Healthcare:Diagnostic sample preparation requires homogeneous mixing with full audit trail documentation. Cloud-based predictive maintenance through sensor-embedded shakers enables subscription service models displacing traditional break-fix contracts.
- Food & Beverage:Ingredient emulsification and flavor extraction protocols utilize temperature-controlled agitation.
- Education:Undergraduate teaching laboratories prioritize analog controls and capital cost minimization over connectivity features.
Research applications command the steepest expansion trajectory; healthcare applications concentrate margin extraction.
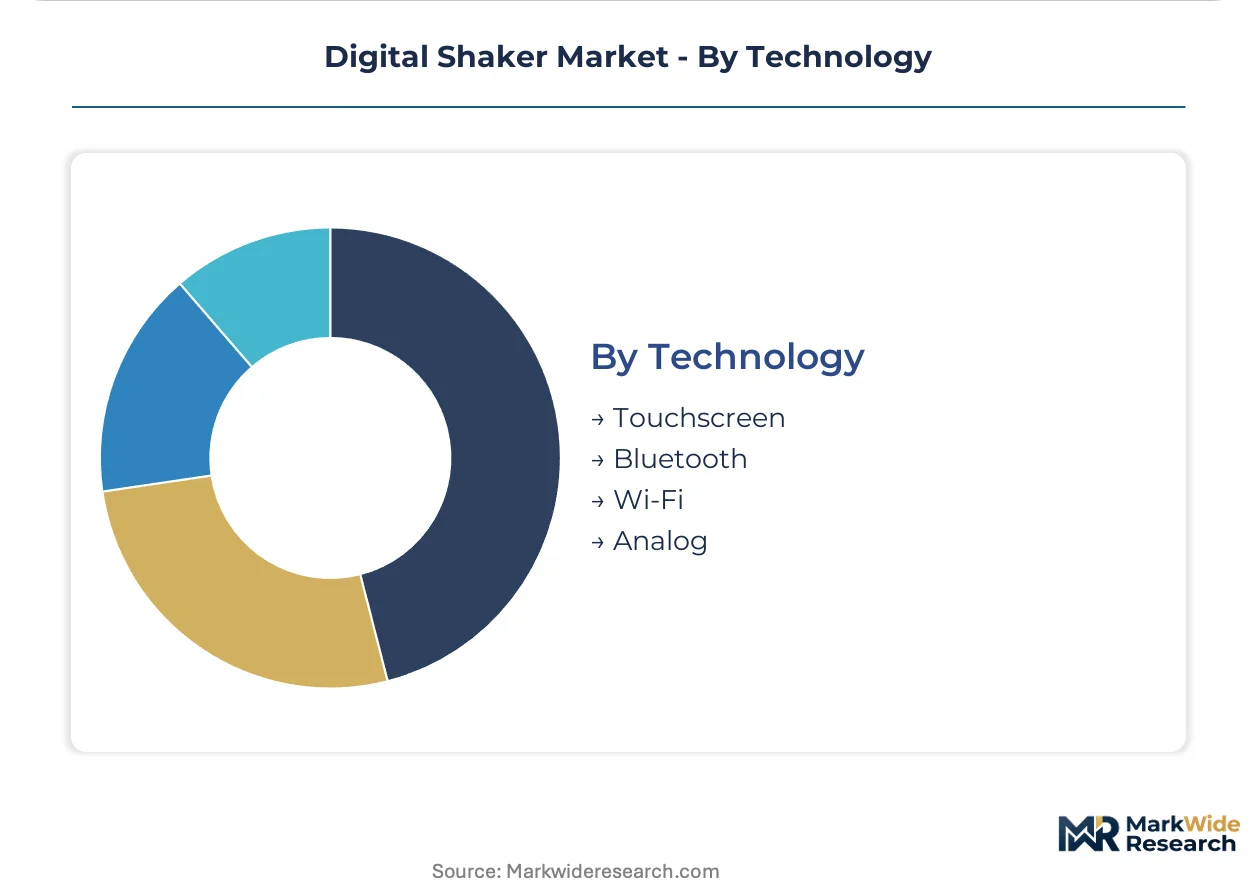
Technology:
Interface architecture and connectivity protocols segment pricing power and service attach rates.
- Bluetooth:Wireless-enabled models represent the fastest-expanding technology segment as laboratories integrate equipment into electronic lab notebook ecosystems. North American contract research organizations now negotiate multi-vendor service agreements through third-party asset management firms.
- Touchscreen:Programmable interfaces command margin premiums over analog controls through reduced operator error and protocol standardization. Thermo Fisher Scientific leverages service network density to sustain recurring revenue from installed-base touchscreen upgrades.
- Wi-Fi:Network-connected shakers face deployment delays due to harmonized IEC 62443 implementation timeline gaps in hospital and pharmaceutical environments.
- Analog:Basic dial controls persist in budget-constrained academic settings and developing market entry segments.
Touchscreen interfaces dominate current revenue; Bluetooth connectivity captures forward momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical contract manufacturing clusters in Germany and the United States drive digital shaker procurement volumes through tightening FDA and EMA validation requirements. Academic research consortia across European university systems now adopt GMP-grade documentation standards. CDSCO-aligned contract manufacturing organizations in India build analytical laboratory capacity under import-substitution incentives.
United States
Cell culture automation in Boston and San Diego biotech clusters expands orbital shaker fleets for reproducible suspension protocols. FDA 21 CFR Part 11 compliance mandates reshape electronic records architecture in pharmaceutical validation workflows. North American contract research organizations negotiate multi-vendor service agreements through third-party laboratory asset management firms.
Germany
Precision control firmware demand concentrates in Baden-Württemberg and Bavaria biopharmaceutical laboratories. EMA GMP Annex 15 qualification documentation requirements extend equipment sales cycles while compressing price premiums between research-grade and GMP-grade systems. Thermo Fisher Scientific leverages dense service networks across German industrial regions for recurring installed-base upgrade revenue.
India
CDSCO-aligned contract manufacturing organizations in Maharashtra and Telangana build out analytical laboratories with import-substitution incentives favoring domestic equipment sourcing. BIS certification requirements shape procurement specifications for institutional tenders. Hyderabad and Mumbai biopharma clusters drive demand for temperature-controlled orbital platforms in microbial fermentation scale-up.
China
NMPA regulatory harmonization with international standards accelerates replacement cycles for legacy equipment in Yangtze River Delta pharmaceutical manufacturing. GB standards compliance functions as baseline market-access threshold for laboratory equipment tenders. Shanghai and Suzhou biopharmaceutical hubs specify brushless DC motor systems for 24/7 continuous culture protocols.
Japan
PMDA quality management requirements drive documentation bundling for equipment qualification in Kanto region pharmaceutical R&D facilities. METI industrial policy supports precision manufacturing capabilities for laboratory instrumentation. Tokyo-Osaka corridor academic consortia adopt modular platform configurations to reduce capital redundancy across multi-protocol core facilities.
Digital Shaker Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent suppliers unbundle after-sales service from initial equipment procurement. The vendor base fragments across three strategic tiers: precision control firmware specialists, modular platform fabricators, and service-network aggregators. Thermo Fisher Scientific exemplifies the latter archetype through installed-base upgrade monetization. Eppendorf anchors the firmware-specialist position. IKA occupies the modularity vector. M&A activity and cloud-based predictive maintenance service models represent the two dominant competitive moves reshaping revenue architecture.
Among precision instrumentation specialists, Thermo Fisher Scientific, Eppendorf, and IKA exemplify divergent strategic positioning within the digital shaker segment. Thermo Fisher Scientific represents the service-network-aggregator archetype, leveraging geographic coverage density for recurring revenue extraction. Eppendorf occupies the firmware-specialist tier, with precision control systems developed for cell culture workflows. IKA exemplifies the modularity-focused competitor, offering interchangeable platform configurations that reduce capital redundancy. These three companies illustrate how electromechanical component substitution, software compliance layering, and service model reinvention fragment competitive positioning across the market.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf |
| Brüel & Kjær |
| IKA |
| Corning Incorporated |
| PCB Piezotronics |
| LDS Test and Measurement |
| Ohaus Corporation |
| IMV Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned precision instrumentation specialists in Germany and Switzerland anchor supply-side discipline through generational capital allocation patterns that resist short-term margin compression. Their ownership structures sustain pricing power for brushless DC motor assemblies and precision control firmware even as rare earth magnet costs fluctuate, while procurement teams at North American contract research organizations exploit this concentration through multi-year service bundling negotiations.
Pricing Analysis
Rare earth magnet price pass-through from neodymium suppliers in China directly compresses margins on premium brushless DC shaker assemblies. Three-tier pricing structure across GMP-validated, research-grade, and educational tiers separates FDA 21 CFR Part 11 documentation bundles from basic analog controls. Cost compression in mid-range touchscreen models is intensifying because EMA GMP Annex 15 qualification requirements extend European sales cycles without commensurate price premiums. Academic core facilities exhibit highest price sensitivity; pharmaceutical validation teams absorb compliance-driven premiums with minimal elasticity.
Supply Chain Analysis
Dual-sourcing mandates from FDA-inspected pharmaceutical manufacturers require qualification of at least two brushless DC motor suppliers, fragmenting procurement leverage. Manufacturing concentrates in Germany, China, and Switzerland for precision mechanical platforms; rare earth magnets draw from Chinese processing facilities with tariff exposure under Section 301 enforcement actions. Supply chain risk centers on single-source vulnerability for high-grade ferrite cores and Hall-effect sensors. Distribution runs through authorized dealer networks for GMP-grade equipment and direct OEM channels for research-tier sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German precision manufacturing costs and Indian import-substitution incentives under CDSCO alignment, where regulatory convergence lowers entry barriers faster than cost structures adjust.
For Market Incumbents: Lock in firmware upgrade recurring revenue through cloud-enabled predictive maintenance subscriptions that displace break-fix service contracts. Defend against modular platform disintermediation by IKA-type competitors through captive supply of interchangeable flask clamp ecosystems, while accelerating IEC 62443 cybersecurity certification to capture hospital laboratory ELN integration mandates before connectivity gaps close. For New Entrants and Emerging Players: Laboratory asset management firms represent the fastest channel to aggregate multi-brand service contracts without manufacturing capital intensity. White-space concentrates in CDSCO-aligned Indian contract manufacturing organizations building analytical capacity under domestic content incentives, and in cloud-based calibration subscription models for North American CROs. Go-to-market leverage rests on third-party qualification documentation bundling that matches EMA GMP Annex 15 standards without legacy protocol baggage. For Investors and Strategic Acquirers: Valuations sit cheapest among firmware-specialist mid-caps with precision control IP for cell culture workflows but underdeveloped service network density. Five-to-ten year viability favors acquisition targets combining brushless DC motor integration capabilities with existing FDA 21 CFR Part 11 software architecture. The signal to watch is CDSCO regulatory harmonization velocity with ICH guidelines, which would accelerate replacement demand in Indian biopharma clusters beyond current import-substitution pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Predictive Maintenance Launch | Sensor-embedded shakers enable subscription revenue displacement of break-fix contracts in Boston CROs. |
| IEC 62443 Cybersecurity Certification | Network-connected shaker deployments accelerate in FDA-inspected pharmaceutical laboratories. |
| Backward Integration into Brushless DC Motors | In-house motor production insulates margins from rare earth magnet price volatility. |
| CDSCO-Aligned Qualification Documentation | Pre-written IQ/OQ/PQ protocol bundling captures Indian contract manufacturing expansion. |
| Modular Platform Architecture Expansion | Interchangeable flask clamps reduce capital redundancy across European academic core facilities. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with laboratory equipment procurement managers, biopharmaceutical validation specialists, aftermarket service directors, and academic core facility directors with secondary validation. FDA 510(k) filings, EMA GMP inspection databases, CDSCO manufacturing licensing records, and SEC 10-K equipment revenue disclosures anchored supply-side triangulation against bottom-up demand modeling.
Granularity-level modeling distinguished countertop from industrial platform footprints, brushless versus brushed motor architectures, touchscreen versus analog interface tiers, and GMP-validated versus research-grade compliance bundles across the projection horizon. CAGRs derived from installed-base replacement cycle analysis, biopharmaceutical capacity expansion pipelines, and electronic lab notebook integration penetration curves. Forecast inputs incorporated rare earth magnet price elasticity coefficients and regulatory harmonization velocity between CDSCO and ICH standards.
Revisions become necessary when cybersecurity certification timelines for IEC 62443 accelerate or stall, when CDSCO domestic content mandates expand beyond analytical equipment, or when brushless DC motor supplier consolidation eliminates dual-sourcing options. Deviation in rare earth magnet export restrictions from Chinese processing facilities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Distillers Malt Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Japanese Whisky Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Canned Wine Market