
 North America Food Service Disposable Market | 2026-2036
North America Food Service Disposable Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Service Disposable Market Intelligence
U.S. molded fiber production capacity is shifting toward the Gulf Coast and Southeastern states, drawn by pulp supply proximity and lower energy costs. Pactiv LLC leverages its integrated thermoforming and fiber operations to serve national quick-service accounts with consistent lead times. Dart Container Corporation anchors the insulated cup segment through its proprietary foam and paperboard technologies, while Huhtamaki Oyj competes aggressively in the premium molded-fiber bowl category with European-designed, North American-manufactured lines.
North America food service disposables encompass single-use containers, serviceware, and packaging designed for one-time food contact, typically manufactured from paper pulp, petroleum-based polymers, expanded polystyrene, or certified compostable resins meeting ASTM D6400 or D6868 degradation standards. These items function primarily to enable safe, sanitary food transport and consumption away from permanent dishwashing infrastructure. The material dimension shows paper and biodegradable substrates gaining shelf space as foam faces legislative compression across multiple jurisdictions, while the product-type dimension reveals bowls outpacing plates in growth velocity due to grain-bowl and soup-centric menu expansion. The end-user dimension remains concentrated in fast-food and catering channels, where volume contracts and standardized specifications create margin pools distinct from fragmented independent restaurant procurement.
FDA food-contact notification requirements, EPA sustainable materials management guidelines, and municipal composting facility certifications in jurisdictions like Seattle, San Francisco, and Toronto collectively reshape permissible material inputs and end-of-life labeling claims. The patchwork of state-level extended producer responsibility proposals and local plastic-ordinance enforcement creates compliance complexity that favors suppliers with dedicated regulatory affairs functions and multi-material platform flexibility. Stakeholders must monitor pending federal procurement standards for compostable products and assess whether their manufacturing footprints align with emerging regional composting infrastructure gaps.
Market Dynamics
Off-premise dining expansion across quick-service chains is compressing order cycles and forcing container suppliers to synchronize production with real-time demand signals rather than quarterly forecasts.
Growth Catalysts
- ASTM D6400-certified compostable resins:Municipal procurement mandates in Seattle, San Francisco, and Toronto are creating pull-through demand for certified fiber bowls and clamshells.
- QSR off-premise infrastructure:Drive-thru optimization and ghost kitchen buildouts in Texas, Georgia, and Florida are lifting unit volumes for heat-retentive containers.
- Pulp supply proximity:Southeastern U.S. paper mill clusters are shortening raw material transit legs for molded-fiber producers serving Atlanta and Dallas distribution hubs.
Market Restraints
- Natural gas price volatility:Thermoforming and pulp-drying operations in the U.S. Gulf Coast face margin compression from feedstock energy cost swings.
- Composting infrastructure gaps:Certified compostable products require municipal facility access that remains concentrated in the Pacific Northwest and Northeast corridors.
- Expanded polystyrene substitution timeline:Foam-dependent operators in jurisdictions with phased bans face capital-intensive retooling before compliance deadlines.
Strategic Opportunities
- Canadian prairie provinces:Saskatchewan and Manitoba foodservice distribution remains underpenetrated by national fiber-container suppliers relative to Ontario and Quebec.
- Reusable container pooling systems:Third-party logistics platforms are emerging to serve corporate catering accounts with trackable, returnable serviceware.
- Extended producer responsibility frameworks:Pending state-level legislation in California and New York would shift end-of-life cost accountability toward manufacturers.
Industry Challenges
- Food-contact substance notification timelines:FDA review cycles for novel biopolymer coatings are extending product development schedules by twelve to eighteen months.
- Multi-material platform complexity:Suppliers maintaining parallel foam, paperboard, and fiber production lines face working capital intensity and SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Service Disposable Market |
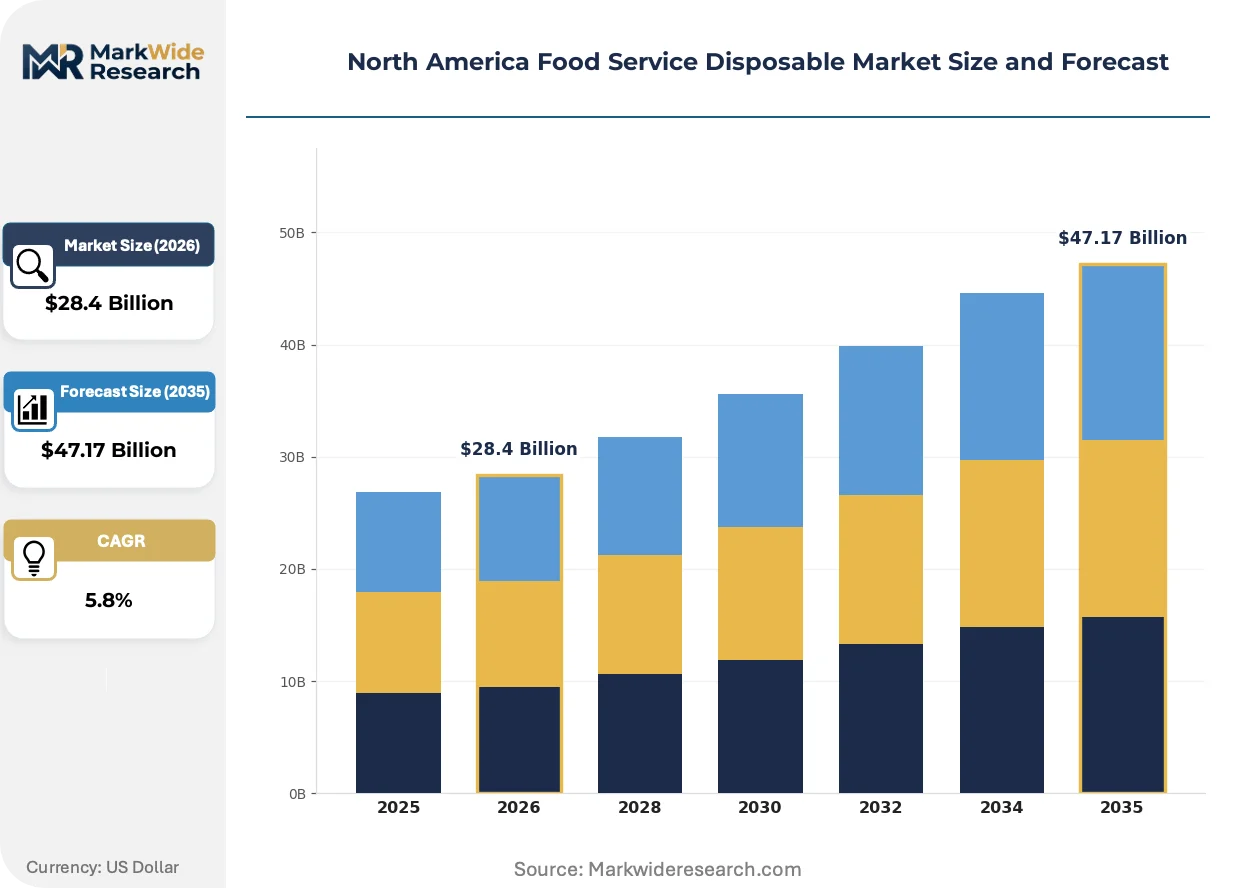
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Cups, Utensils, Bowls Material: Paper, Plastic, Biodegradable, Foam End User: Restaurants, Cafés, Catering, Fast Food Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Pactiv LLC, Sonoco Products Company, Dart Container Corporation, Sabert Corp., Huhtamaki Oyj, Berry Global Inc., Georgia-Pacific LLC, Genpak LLC, Graphic Packaging International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Service Disposable Market Strategic Shifts & Innovations
Material science advances and regulatory compression are converging to redefine performance specifications across disposable food-contact applications, with functionality and end-of-life accountability now weighted equally in procurement decisions.
Barrier-coated molded fiber is electrifying the premium takeout segment by matching grease resistance and structural integrity previously exclusive to plastic laminates. National fast-casual chains with grain-bowl and sauced-protein menus are specifying these containers for hot-fill applications above 180°F. The technology is electrifying supplier R&D allocation, drawing investment away from incremental foam improvements toward aqueous coating and PLA-lining development.
FDA food-contact notification requirements for new substances are tightening the evidentiary threshold for biopolymer and additive approvals, extending pre-market clearance timelines. Manufacturers are responding by consolidating formulation portfolios around previously cleared chemistries rather than pursuing novel material breakthroughs. The chilled and ambient food segments are absorbing the bulk of this conservatism, as hot-fill applications face higher migration-test scrutiny.
Direct procurement relationships between quick-service chains and container manufacturers are displacing traditional foodservice distributor intermediation for high-volume, specification-stable SKUs. Chains with franchisee consolidation in the U.S. Southeast are leveraging this channel compression to secure volume commitments and customize dimensions. The shift is most visible in Texas and Georgia, where distribution center proximity to manufacturing clusters enables just-in-time replenishment without distributor safety-stock buffers.
North America Food Service Disposable Market Segmentation
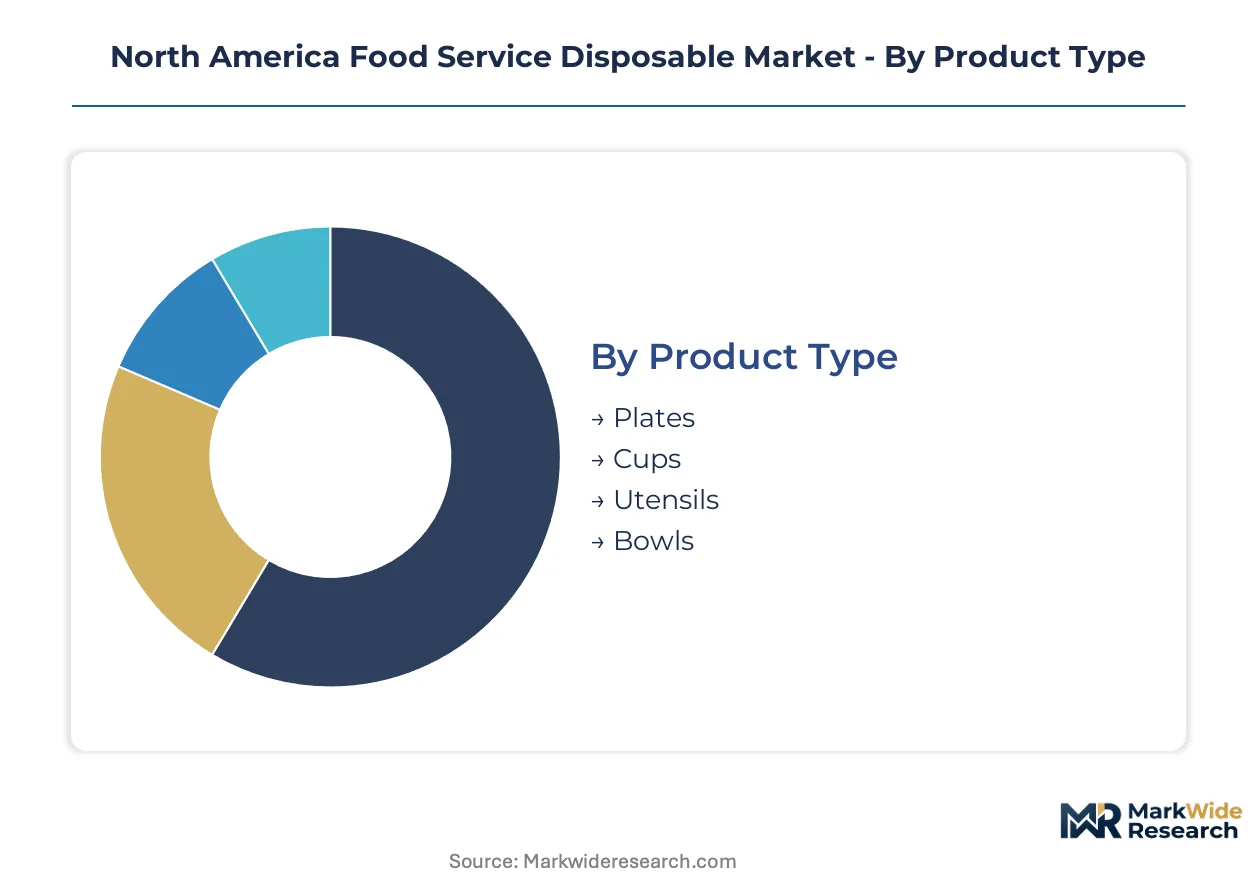
Disposable foodservice procurement in North America fragments across material chemistry, thermal performance requirements, and channel access economics. Suppliers configure production platforms around these divides to capture margin pools distinct from commodity segments.
Product Type:
Volume concentrates in handheld formats optimized for drive-thru velocity, while premium positioning clusters around structural integrity for sauced and hot-fill applications.
- Bowls:Molded-fiber and double-wall paperboard constructions with grease-resistant aqueous coatings serve grain-bowl and soup-centric menus across fast-casual chains. Texas and Georgia distribution hubs are absorbing the fastest capacity additions for heat-retentive bowl formats as QSR off-premise infrastructure expands.
- Cups:Insulated double-wall paperboard and foam technologies dominate hot-beverage applications, with proprietary lid-locking systems anchoring supplier differentiation. Seattle and San Francisco municipal procurement mandates are redirecting specification toward fiber-based alternatives with compostable lining systems.
- Plates:Laminated paperboard and pressed-pulp formats serve casual dining and catering channels where rigidity and cut-resistance outweigh thermal retention needs.
- Utensils:Polystyrene, polypropylene, and CPLA resin formulations compete on cost-per-piece and compostability certification tiers for quick-service and institutional accounts.
Today's leader: Cups. Tomorrow's challenger: Bowls.
Material:
Regulatory compression across U.S. and Canadian jurisdictions is forcing multi-material platform strategies, with compliance timelines varying by municipality.
- Paper:Unbleached kraft and bleached sulfate pulp grades form the substrate for plates, cups, and molded-fiber bowls, with barrier coatings determining end-use suitability. FDA food-contact substance notifications for novel aqueous coatings are extending product development cycles by twelve to eighteen months.
- Biodegradable:PLA, bagasse, and molded-fiber formulations certified to ASTM D6400 or D6868 standards capture municipal procurement mandates in Toronto, Seattle, and San Francisco. Composting infrastructure gaps in the U.S. Southeast and Canadian prairie provinces limit addressable market penetration despite specification pull-through.
- Plastic:Polypropylene and PET thermoformed containers retain cost advantages for chilled and ambient applications where heat tolerance requirements are minimal.
- Foam:Expanded polystyrene faces phased substitution timelines in Vancouver, Montreal, Los Angeles, and New York City, with capital-intensive retooling compressing margins for dependent operators.
Paper commands current volume. Biodegradable formats are climbing the fastest as municipal bans proliferate.
End User:
Procurement sophistication varies sharply between consolidated chain accounts and fragmented independent operators, dictating sales force deployment and specification engineering intensity.
- Fast Food:Drive-thru and delivery-optimized formats with standardized dimensions and national distribution requirements dominate volume contracts. Direct procurement relationships between chains and manufacturers are displacing distributor intermediation for high-SKU, specification-stable items in Texas and Georgia.
- Catering:Event-based demand with seasonal peaks and premium presentation requirements favors disposable formats with elevated aesthetic and structural performance.
- Restaurants:Full-service and casual dining segments prioritize plate and bowl formats with cut-resistance and sauce containment for dine-in and takeout hybrid models.
- Cafés:Beverage-centric procurement concentrates in cup and lid combinations with brand-customizable print surfaces and thermal comfort features.
Fast Food anchors volume scale. Catering offers the steepest expansion trajectory for premium compostable formats.
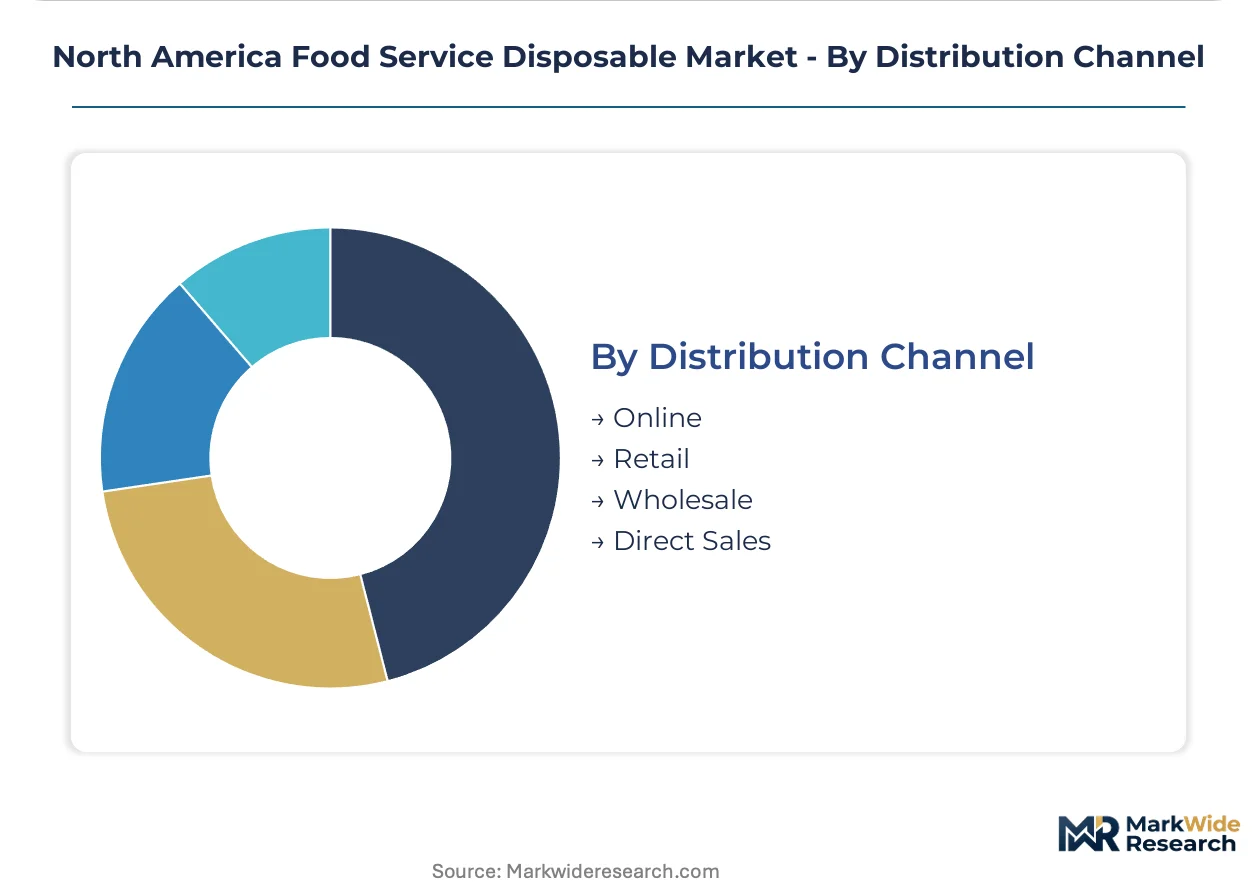
Distribution Channel:
Channel selection determines working capital intensity and customer intimacy, with direct models capturing specification stability and wholesale retaining fragmented access.
- Direct Sales:National quick-service accounts with franchisee consolidation in the U.S. Southeast leverage manufacturing proximity in Atlanta and Dallas for just-in-time replenishment without distributor safety-stock buffers.
- Wholesale:Broadline foodservice distributors serve independent restaurants and regional chains with consolidated procurement across equipment, ingredients, and disposables.
- Retail:Club stores and cash-and-carry formats capture small-operator and consumer segments with case-quantity flexibility and immediate availability.
- Online:E-procurement platforms are emerging for corporate catering accounts and multi-location operators seeking consolidated billing and specification compliance tracking.
Direct Sales commands margin concentration. Online channels are gaining share fastest among digitally native operator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity is migrating toward jurisdictions with lower energy costs and streamlined compliance pathways, creating a regulatory-arbitrage dynamic that concentrates molded-fiber manufacturing in the U.S. Southeast while Canadian operators face municipal plastic-ban acceleration.
United States
Quick-service restaurant chains are expanding drive-thru and ghost kitchen infrastructure across Texas, Georgia, and Florida, lifting container volumes for heat-retentive formats. FDA food-contact substance notifications govern novel aqueous coatings, extending product development timelines for suppliers pursuing premium bowl specifications. Atlanta and Dallas distribution hubs cluster near Gulf Coast pulp mills, shortening raw material transit legs for molded-fiber producers serving QSR accounts.
Canada
Municipal single-use plastic bans in Vancouver and Montreal are redirecting procurement toward ASTM D6400-certified fiber alternatives for foodservice operators. Health Canada regulations on food-contact materials align with FDA standards but move faster on certain additive restrictions, compressing formulation windows for cross-border suppliers. Ontario and Quebec absorb the majority of national fiber-container capacity, while Saskatchewan and Manitoba distribution channels remain underpenetrated by national suppliers.
Mexico
Cross-border manufacturing integration is expanding as U.S. brands nearshore thermoforming operations to leverage labor cost differentials and USMCA tariff preferences for plastic container exports. Mexico's federal environmental standards on single-use plastics lag municipal enforcement in Mexico City and Monterrey, creating a compliance gradient that favors regional production for domestic consumption. The Bajío Region and Northern Border States are absorbing thermoforming capacity additions serving quick-service accounts with U.S. distribution requirements.
North America Food Service Disposable Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue compostable certification and regional niche penetration. The market structure consolidates around integrated manufacturers with multi-material platform flexibility, while mid-scale specialists concentrate on single-format excellence. Three archetypes dominate: pulp-integrated giants with captive fiber supply, thermoforming specialists with petroleum-based polymer expertise, and biopolymer pure-plays chasing municipal procurement mandates. Competitive moves center on capacity relocation toward pulp-proximate geographies and strategic partnerships with quick-service chains for direct procurement relationships.
Among U.S.-based integrated manufacturers, Pactiv LLC and Dart Container Corporation exemplify the multi-material platform archetype, spanning foam, paperboard, and molded-fiber production lines. Finnish-domiciled Huhtamaki Oyj occupies a position representing European-designed, North American-manufactured premium fiber formats. Georgia-Pacific LLC anchors the pulp-integrated tier with captive supply advantages for kraft-based container substrates.
| Leading Market Players |
|---|
| Pactiv LLC |
| Sonoco Products Company |
| Dart Container Corporation |
| Sabert Corp. |
| Huhtamaki Oyj |
| Berry Global Inc. |
| Georgia-Pacific LLC |
| Genpak LLC |
| Graphic Packaging International LLC |
| Others |
Cost & Logistics Intelligence
Pulp fiber costs originating from Southeastern U.S. mill clusters cascade through three distinct pricing tiers before reaching end-user procurement desks, with captive supply integration separating premium bowl manufacturers from spot-market dependent competitors.
Pricing Analysis
Distributor margin layers compress most acutely in the wholesale channel serving fragmented independent restaurants, while direct-to-QSR contracts command volume-scaled discounts that erase intermediary markups entirely. Pricing stratifies across premium, standard, and economy tiers based on ASTM D6400 certification status and barrier-coating performance specifications. Cost compression in the fiber-bowl segment is intensifying because Gulf Coast energy volatility feeds into thermoforming and pulp-drying operations. National quick-service chains exhibit lowest price sensitivity due to specification-locked contracts, whereas cash-and-carry retail buyers demonstrate highest elasticity to per-unit fluctuations.
Supply Chain Analysis
Domestic-content procurement mandates in Canadian municipal contracts are redirecting sourcing toward North American fiber mills rather than Asian pulp imports. Manufacturing concentrates in the United States, Canada, and Mexico, with cross-border USMCA integration enabling tariff-advantaged plastic container flows from Bajío Region thermoformers. Raw material dependencies center on bleached kraft pulp, PLA resin feedstocks, and aqueous barrier coatings. Single-source vulnerability runs through Gulf Coast natural gas supply for energy-intensive molding operations. Distribution runs through Atlanta and Dallas hub-and-spoke networks serving QSR accounts with just-in-time replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
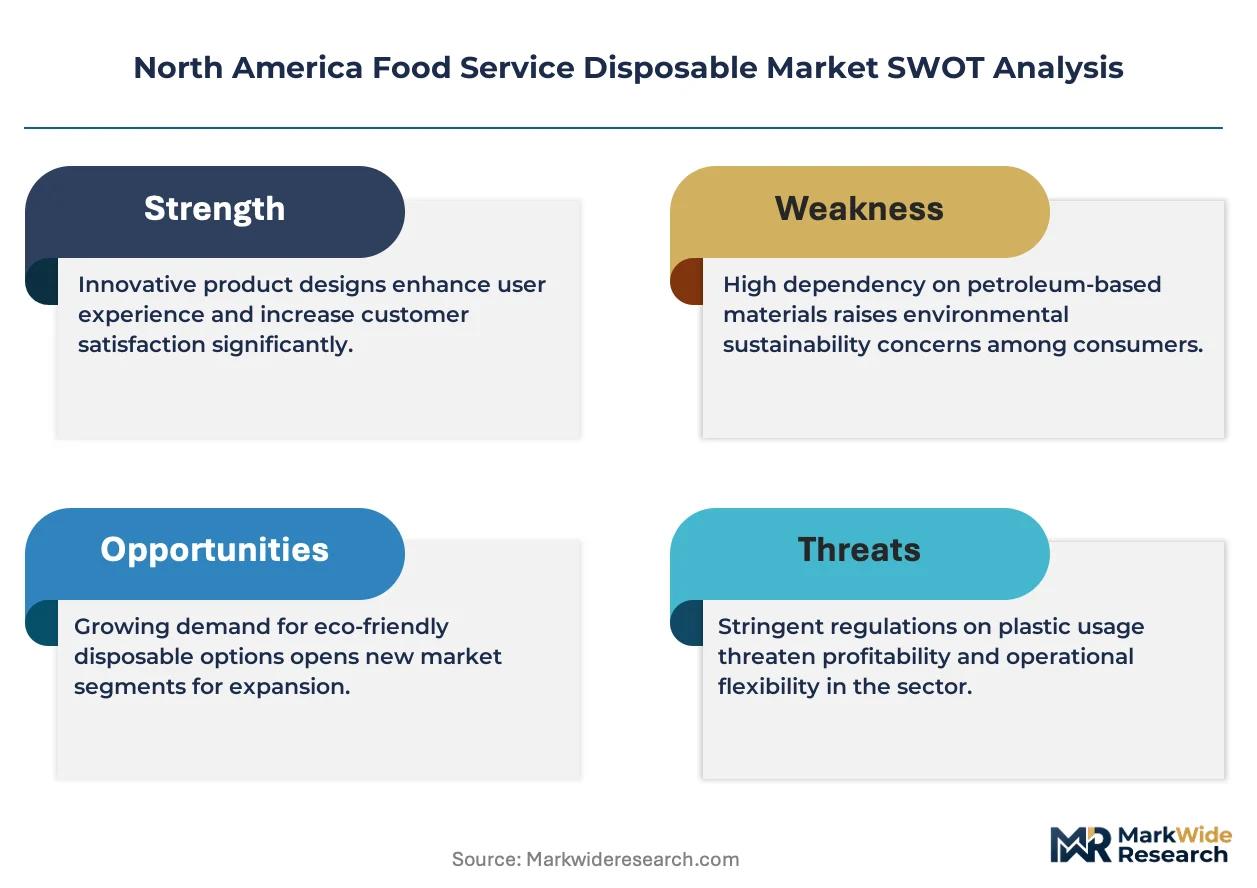
Margin expansion in this market rests on the shift from petroleum-based foam to premium fiber formats, where barrier-coated specifications command pricing premiums that outpace pulp input cost escalations.
For Market Incumbents: Deepen captive pulp supply integration through Southeastern mill partnerships to insulate against spot fiber volatility. Expand molded-fiber capacity in Georgia and Texas to exploit distribution hub proximity. Defend against biopolymer pure-plays by accelerating FDA-cleared aqueous coating R&D ahead of twelve-to-eighteen-month notification timelines. For New Entrants and Emerging Players: Broadline foodservice distributors represent the most accessible channel partner type for penetrating underexploited Canadian prairie provinces. Target Saskatchewan and Manitoba catering accounts with ASTM D6400-certified clamshell formats where national suppliers maintain thin coverage. Pursue white-label manufacturing arrangements with regional distribution cooperatives to bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-material platform complexity strains working capital for mid-scale operators lacking captive fiber supply. Long-term viability favors pulp-integrated manufacturers with regulatory affairs functions capable of navigating municipal ban patchworks. Acquisition target archetype: Southeastern U.S. molded-fiber specialists with QSR direct procurement relationships. Signal to watch: California and New York extended producer responsibility legislation advancing through state committees.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive kraft fiber access insulates margin compression from spot market volatility in Gulf Coast energy corridors. |
| Barrier-Coating R&D Expansion | FDA-cleared aqueous formulations unlock hot-fill applications above 180°F previously restricted to plastic laminates. |
| Direct Procurement Relationships | QSR chain partnerships displace distributor intermediation for specification-stable SKUs in Texas and Georgia. |
| Compostable Certification Investment | ASTM D6400 compliance opens municipal procurement mandates in Seattle, San Francisco, and Toronto. |
| Canadian Prairie Distribution Buildout | Saskatchewan and Manitoba channel penetration captures underserved catering and institutional accounts. |
Research Approach
Multiple input streams — executive interviews with QSR procurement directors, regulatory affairs specialists at container manufacturers, and foodservice distribution channel managers — were reconciled against secondary validation from FDA food-contact substance filings, EPA sustainable materials management guidelines, and municipal ordinance databases. Primary fieldwork incorporated perspectives from pulp mill operations heads, composting facility managers in Pacific Northwest corridors, and franchisee consortium representatives. Secondary sources included customs trade data on resin and pulp flows, SEC 10-K disclosures from integrated packaging manufacturers, and industry association capacity surveys. Bottom-up volume modeling triangulated against top-down market sizing derived from QSR unit expansion and per-location disposable consumption benchmarks.
Cross-referencing historical capacity addition patterns with panel input from manufacturing executives informed the analytical framework across the analysis window. Segmentation dimensions modeled encompassed material chemistry, product format, thermal performance tier, end-user channel sophistication, and regional regulatory cluster intensity. CAGRs were derived from elasticity-adjusted volume projections tied to QSR off-premise infrastructure buildouts and substitution timelines for foam-dependent operators. Industry-specific forecast inputs incorporated municipal ban phase-in schedules and composting facility penetration rates by metropolitan statistical area.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal procurement standard adoptions, natural gas price trajectories, and biopolymer coating approval timelines. Forecasts reflect documented assumptions regarding QSR franchisee consolidation rates and pulp mill capacity expansion commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Air Fryer Market
Food Service
Global Online Food Delivery Services Market
Food Service
Philippines Quick Service Restaurants Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Clear Ice Maker Market
Food Service
Popcorn Making Cart Market
Food Service
Global Dark Store Market
Food Service
Europe Food Away from Home Market
Food Service
Food Logistics Market
Food Service
Australia Foodservice Market
Food Service
Meal Voucher Market
Food Service
Germany Foodservice Market
Food Service
Ship Catering Service Market
Food Service
Full-Service Restaurants Market
Food Service
Cutting Boards Market
Food Service
Europe Smokeless Indoor Grills Market