
 Europe Inflight Catering Market | 2026-2036
Europe Inflight Catering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Inflight Catering Market Foresight
The buyer base for inflight catering is broadening as low-cost carriers expand route networks while legacy airlines diversify premium cabin tiers. Gategroup leverages centralized kitchen networks across multiple European hubs to sustain operational density. Newrest Group anchors its position through specialized catering contracts with charter and business aviation operators. DO & CO Aktiengesellschaft differentiates via chef-driven meal programs designed for premium cabin segments.
Europe inflight catering encompasses the industrial preparation, assembly, and logistics of food and beverage products consumed during commercial air travel, requiring compliance with HACCP protocols and altitude-adjusted flavor formulations to compensate for cabin pressure effects on taste perception. Meal Service and Beverage Service dominate revenue within the Service Type dimension, though Special Meal Service commands disproportionate margin contribution due to dietary customization complexity. The Customer Type dimension shows First Class and Business Class generating concentrated margin pools, while Economy Class sustains volume throughput across narrow-body European routes.
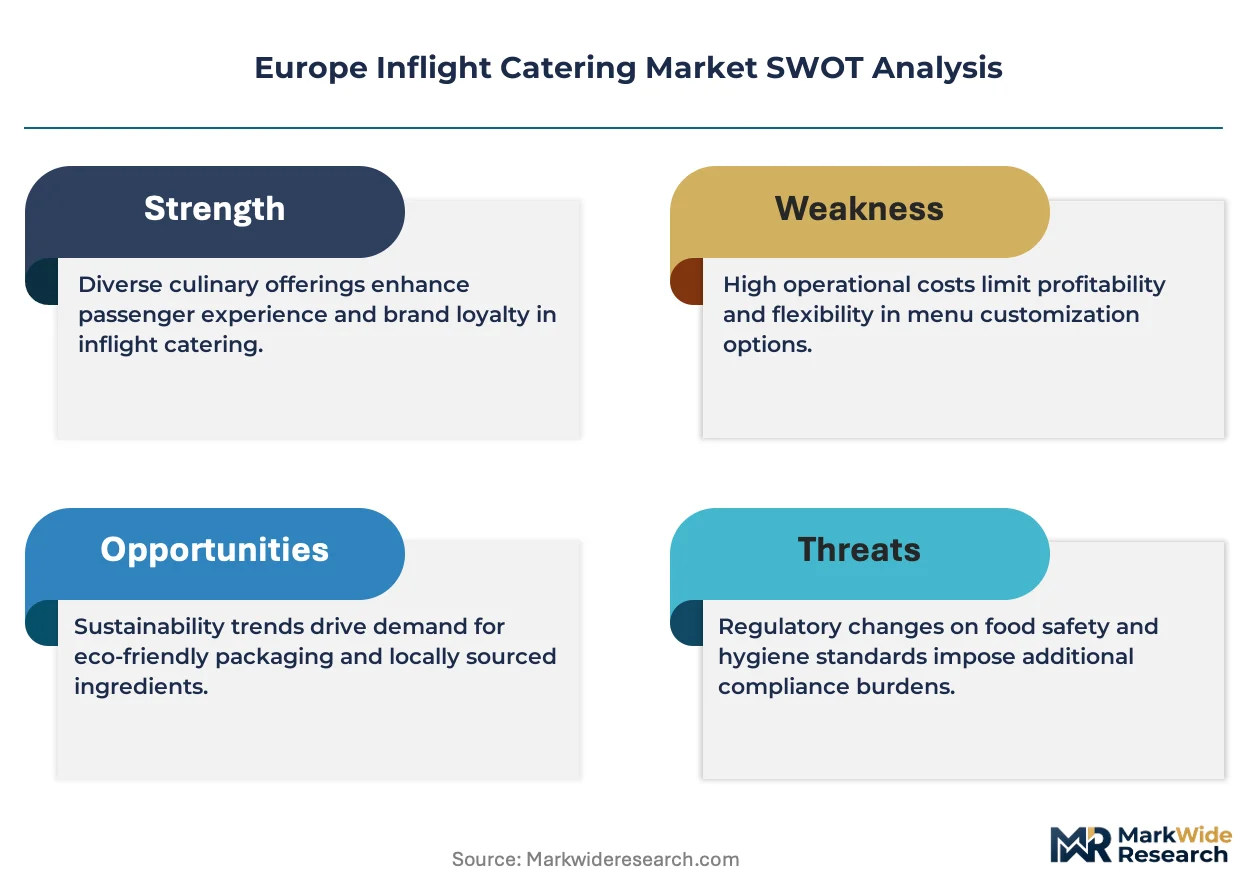
EMA food safety standards, EU Green Deal sustainability frameworks, and national aviation authority operational directives collectively shape ingredient sourcing, packaging material selection, and waste reporting obligations for caterers. REACH chemical regulations further constrain cleaning agents and food-contact materials used in galley operations. Stakeholders must monitor evolving carbon accounting rules for airport-adjacent logistics and the pace of electrified catering truck deployment mandates across major European hubs.
Market Dynamics
EU Green Deal food waste reduction mandates are compressing procurement cycles and forcing caterers to reconfigure sourcing networks across airport-adjacent logistics zones. Legacy carriers and low-cost operators alike face simultaneous pressure to expand premium cabin tiers while cutting per-passenger resource intensity.
Growth Catalysts
- Hub airport expansion:Capacity additions at Frankfurt, Amsterdam Schiphol, and Istanbul are generating concentrated demand for high-volume catering infrastructure.
- REACH packaging reforms:Biodegradable food-contact material mandates are accelerating supplier innovation in compostable tray and cutlery formats.
- Altitude-adjusted formulation science:Umami-enhanced recipes developed for cabin pressure effects are differentiating premium cabin offerings and commanding margin premiums.
Market Restraints
- Perishable input volatility:Fresh protein and dairy sourcing costs fluctuate with seasonal EU agricultural output and energy-intensive cold chain requirements.
- Galley equipment supplier concentration:Narrow-body retrofit approvals depend on a limited set of EASA-certified oven and refrigeration system manufacturers.
- HACCP compliance fragmentation:National aviation authorities in Germany, France, and the UK maintain divergent audit protocols that complicate cross-border kitchen operations.
Strategic Opportunities
- Eastern European route density:Underpenetrated charter and business aviation catering in Poland, Hungary, and Romania offers white-space expansion for specialized operators.
- Electrified ground support mandates:EU airport decarbonization timelines are creating first-mover advantage for caterers deploying battery-powered catering truck fleets.
- AI-driven demand forecasting:Machine learning integration with airline reservation systems is enabling dynamic meal loading that cuts waste and unlocks sustainability credentials.
Industry Challenges
- Certified cold chain technician scarcity:HACCP-qualified kitchen staff and drivers with dangerous goods endorsements face recruitment bottlenecks across major European hubs.
- Legacy galley system incompatibility:New lightweight packaging formats often fail to interface with existing oven racking and trolley configurations, forcing dual inventory maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Inflight Catering Market |
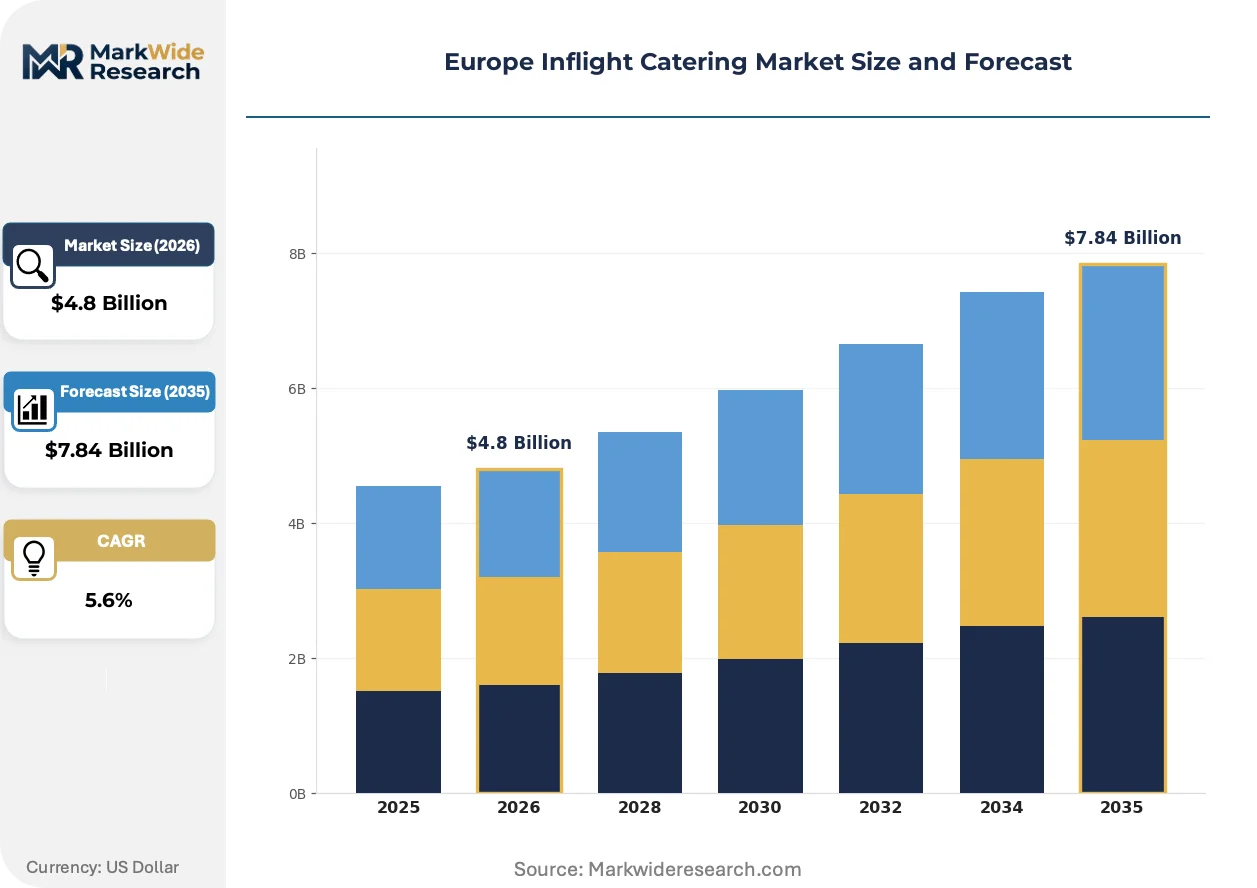
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Service, Snack Service, Beverage Service, Special Meal Service Product Type: Meals, Beverages, Snacks, Desserts Delivery Mode: Onboard Delivery, Pre-ordered Delivery, Home Delivery, In-flight Ordering Customer Type: First Class, Business Class, Economy Class, Charter Flights |
| Companies Covered | KLM Catering Services, Servair, Gategroup, Satys, Dnata Catering, Newrest Group, LSG Sky Chefs, Journey Group, DO & CO Aktiengesellschaft, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Inflight Catering Market Shifts & Advancements
Digital traceability and circular packaging are converging to reshape how caterers demonstrate compliance and differentiate bids. Operators now compete on waste verification transparency as much as culinary execution.
Blockchain-enabled ingredient provenance tracking is integrating with airline sustainability reporting platforms to provide immutable chain-of-custody documentation. Full-service carriers adopting these systems are compressing supplier audit cycles and reducing documentation overhead. The technology is integrating procurement, kitchen operations, and passenger-facing transparency into unified compliance architecture.
EU Green Deal food waste reduction frameworks are mandating granular reporting on unconsumed meal volumes and disposal pathways. Caterers must now install weighing systems and digital logging infrastructure to meet airport authority contractual requirements. Narrow-body operators on high-frequency European routes face the steepest compliance cost curves as they lack the scale to amortize tracking investments across large fleets.
Airline procurement departments are consolidating vendor relationships and demanding outcome-based contracts tied to waste reduction metrics rather than per-meal unit pricing. This model displaces traditional volume-commitment agreements and shifts risk to caterers for overproduction. Lufthansa Group and Air France-KLM have piloted these structures on intra-European routes, with Iberia and SAS evaluating adoption.
Europe Inflight Catering Market Segmentation
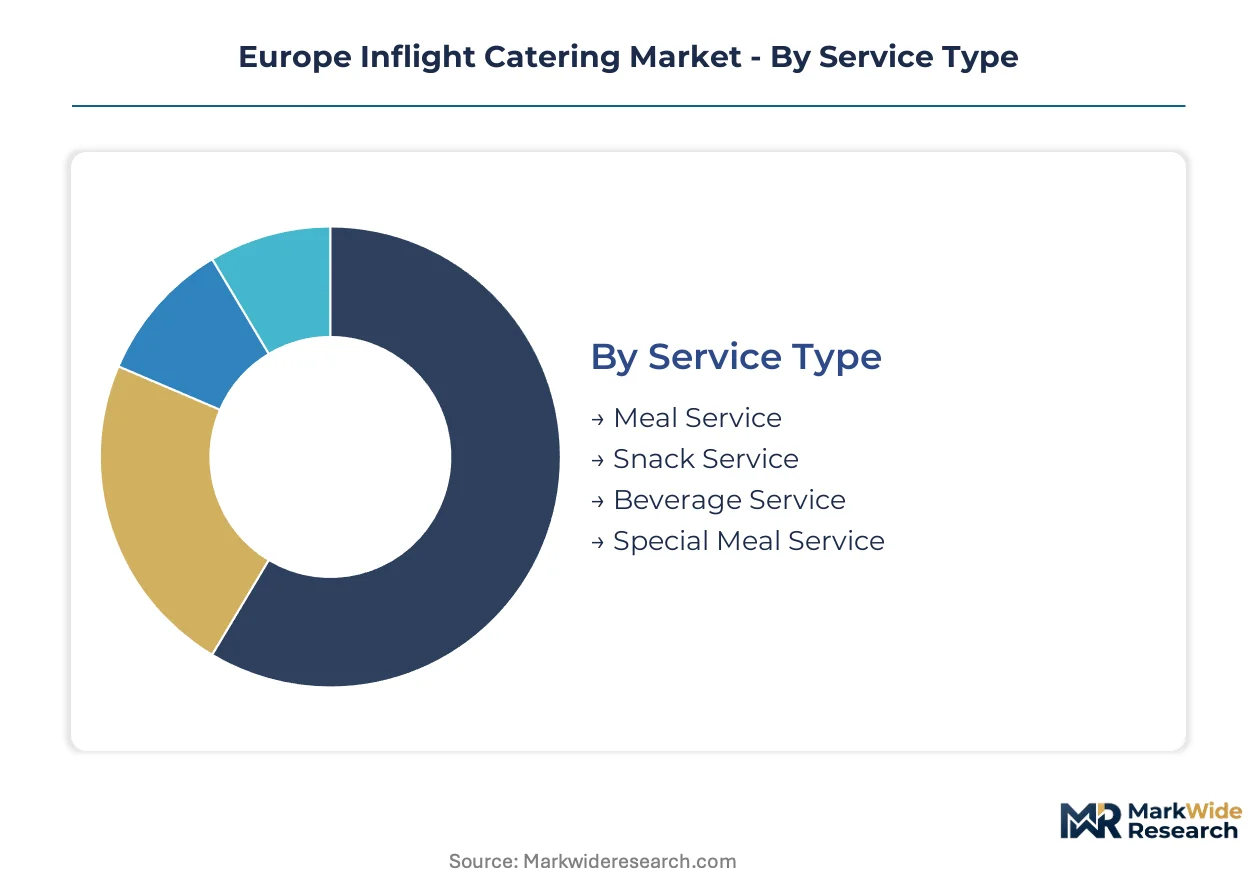
Segmentation in European inflight catering determines which HACCP certification tiers apply to kitchen operations and which altitude-adjusted formulation protocols govern recipe development. Each category channels procurement decisions toward distinct supplier capabilities and margin structures.
Service Type:
Full HACCP compliance and EASA galley safety certifications apply universally, though Special Meal Service demands additional allergen-management protocols and EFSA dietary claim verifications that extend audit cycles.
- Meal Service:Multi-course tray assemblies requiring thermal regeneration compatibility with narrow-body and wide-body oven specifications. Frankfurt and Amsterdam Schiphol hubs concentrate demand as Lufthansa Group and Air France-KLM expand premium cabin rotations on European trunk routes. REACH-compliant packaging mandates are accelerating compostable tray adoption.
- Beverage Service:Altitude-calibrated coffee extraction systems and wine service protocols designed for cabin pressure effects on olfactory perception. Business Class cabins on intra-European routes generate concentrated demand for sommelier-curated selections with provenance documentation.
- Snack Service:Shelf-stable items with extended ambient stability for high-frequency short-haul rotations.
- Special Meal Service:Religious, medical, and lifestyle dietary accommodations requiring segregated preparation lines and ingredient traceability systems.
Meal Service sits at the top of the volume ranking, with Special Meal Service climbing the fastest as dietary accommodation mandates tighten across EU carriers.
Product Type:
Margin concentration varies sharply across product categories, with perishables commanding cold chain premiums and shelf-stable items offering volume scale but compressed unit economics.
- Meals:Protein-centric main courses formulated with umami enhancement to compensate for cabin pressure-induced taste suppression. Central kitchen production at Frankfurt, Paris Charles de Gaulle, and London Heathrow anchors supply for full-service carrier networks.
- Beverages:Still and sparkling water, soft drinks, juices, and alcoholic categories governed by excise duty variations across EU member states.
- Snacks:Pre-packaged items with ambient stability requirements aligned with narrow-body galley storage constraints.
- Desserts:Chilled and frozen preparations requiring precise thawing protocols and EFSA-compliant dairy sourcing documentation.
Meals dominate absolute revenue contribution, while Desserts gain share fastest as premium cabin differentiation intensifies on competitive European routes.
Delivery Mode:
Operational complexity escalates from centralized onboard loading toward passenger-initiated channels that demand real-time inventory synchronization with reservation systems.
- Onboard Delivery:Traditional galley-loaded service coordinated with ground handling agents at hub airports. Istanbul Airport capacity expansion is driving infrastructure investment for high-volume loading operations.
- Pre-ordered Delivery:Passenger-selected meals loaded based on advance booking data, requiring integration with airline CRM platforms.
- Home Delivery:Post-flight meal kit distribution, currently limited to pilot programs by Air France-KLM and British Airways.
- In-flight Ordering:Real-time selection via seatback or personal device, demanding dynamic inventory visibility and galley restocking protocols.
Onboard Delivery retains volume leadership, though Pre-ordered Delivery is expanding most quickly as waste reduction mandates favor demand-certain loading models.
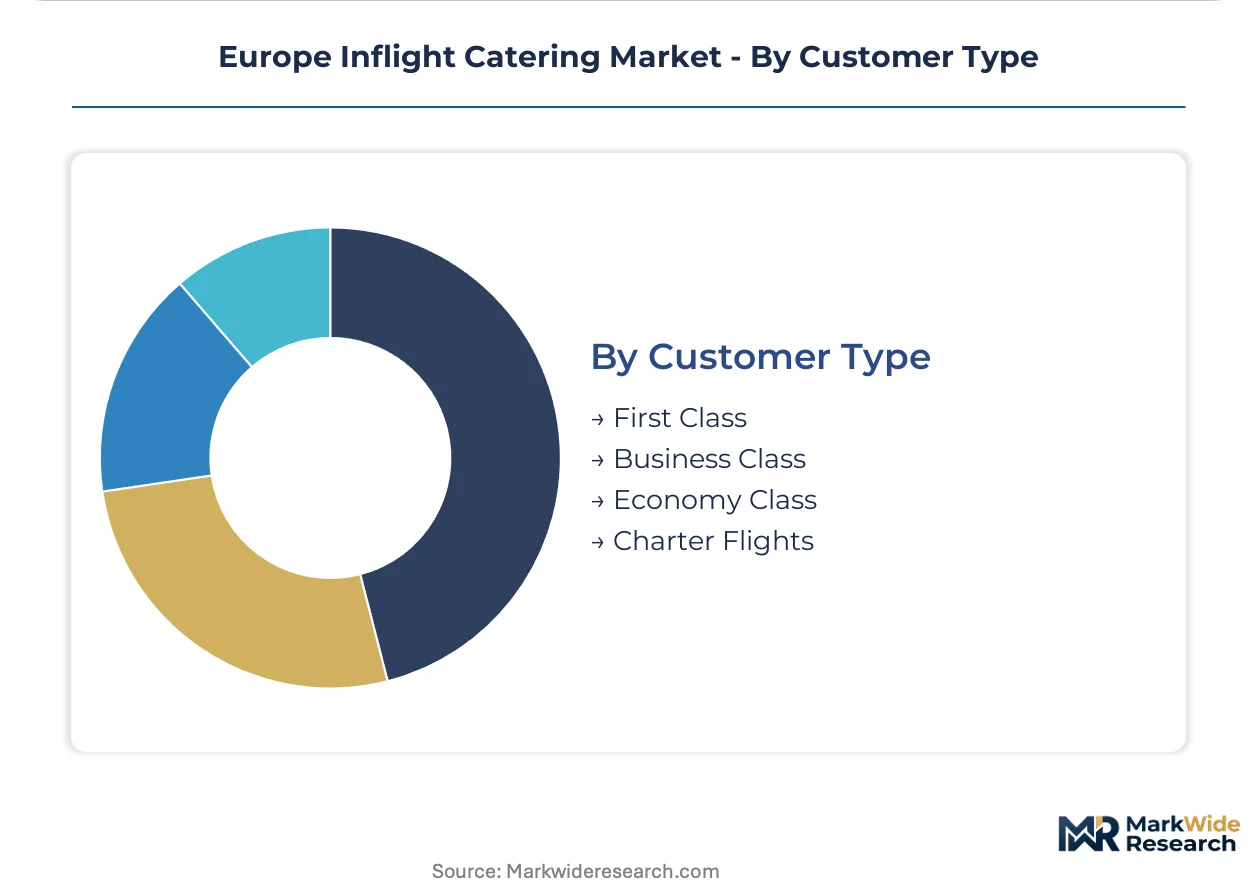
Customer Type:
Certification requirements intensify toward the premium tier, with First Class demanding chef-attended preparation and Business Class requiring sommelier-curated beverage programs that exceed Economy operational standards.
- First Class:Chef-on-call programs and bespoke menu development requiring DO & CO Aktiengesellschaft-style culinary partnerships. London Heathrow and Frankfurt maintain dedicated premium kitchens with EASA-certified live cooking capabilities.
- Business Class:Lie-flat seat dining protocols with multi-course sequencing and wine pairing documentation. Air France-KLM and Lufthansa Group procurement departments are consolidating supplier relationships around waste-linked outcome contracts.
- Economy Class:High-volume tray assembly with compressed preparation windows for narrow-body turnaround schedules.
- Charter Flights:Flexible provisioning for tour operators and business aviation with variable passenger manifests and ad-hoc scheduling.
Economy Class sustains the highest absolute loading volumes, while Charter Flights are gaining share fastest as Eastern European leisure routes expand beyond established hub networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hub airport density contrasts with Spain's resort-route specialization, illustrating how geography shapes catering infrastructure requirements across the continent. France and the United Kingdom occupy intermediate positions with mixed hub-and-spoke and point-to-point demand profiles. The EU Green Deal's waste reporting mandates apply uniformly, though national aviation authorities implement divergent audit protocols.
Germany
Lufthansa Group's premium cabin expansion at Frankfurt and Munich drives demand for chef-attended kitchen facilities. The Federal Ministry of Transport enforces EASA-aligned HACCP standards with additional BfR food-contact material testing. North Rhine-Westphalia hosts centralized production facilities serving Cologne-Bonn and Düsseldorf with high-frequency narrow-body turnaround capacity.
United Kingdom
British Airways' Club World refurbishment and Virgin Atlantic's Upper Class investments concentrate demand at London Heathrow. The Civil Aviation Authority maintains distinct audit schedules from continental regulators, complicating cross-border kitchen certification. Gatwick and Manchester serve as secondary hubs where low-cost carrier volume sustains tray-assembly operations with compressed preparation windows.
France
Air France-KLM's procurement consolidation and Transavia's seasonal capacity swings create volatile demand patterns at Paris Charles de Gaulle. ANSM oversees food safety compliance alongside EU Green Deal waste tracking requirements. Lyon and Nice maintain specialized catering for business aviation and charter operators serving Alpine and Mediterranean leisure corridors.
Netherlands
KLM's hub-and-spoke network at Amsterdam Schiphol generates concentrated demand for long-haul wide-body provisioning. The Dutch Food and Consumer Product Safety Authority integrates REACH packaging reforms with NVWA operational inspections. Rotterdam The Hague Airport supports secondary catering capacity for low-cost carrier point-to-point routes.
Turkey
Istanbul Airport's capacity expansion and Turkish Airlines' aggressive European network growth are driving infrastructure investment for high-volume loading operations. The General Directorate of Civil Aviation aligns with EASA standards while maintaining national sovereignty over kitchen licensing. Ankara and Izmir serve domestic trunk routes with scaled-down versions of Istanbul's centralized production model.
Europe Inflight Catering Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service segments. The vendor base clusters around three operational models: hub-centralized mass production, premium cabin culinary partnerships, and flexible charter provisioning. Consolidation pressure intensifies as airlines demand outcome-based contracts tied to waste metrics rather than per-meal pricing. Dominant competitive moves include strategic partnerships with airport authorities for exclusive ground-handling rights and portfolio diversification into rail and retail catering.
Within the hub-centralized tier, Gategroup and LSG Sky Chefs exemplify scale-driven operators with multi-airport kitchen networks. DO & CO Aktiengesellschaft occupies a distinct position as a chef-driven specialist serving premium cabin segments. Newrest Group anchors the flexible provisioning archetype through charter and business aviation contracts. These three company structures illustrate how competitive positioning fragments across operational specializations rather than geographic territories.
| Leading Market Players |
|---|
| KLM Catering Services |
| Servair |
| Gategroup |
| Satys |
| Dnata Catering |
| Newrest Group |
| LSG Sky Chefs |
| Journey Group |
| DO & CO Aktiengesellschaft |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists like Gategroup and LSG Sky Chefs anchor supply concentration across Frankfurt, Amsterdam Schiphol, and London Heathrow, compressing procurement cycles while enforcing volume-commitment pricing discipline that squeezes mid-tier caterers without hub scale.
Pricing Analysis
Capacity additions at Istanbul Airport are reshaping price floors across Eastern European routes as Turkish Airlines expands network density. Three-tier pricing structure across premium, standard, and economy levels separates chef-attended First Class programs from Business Class sommelier-curated tiers and high-volume Economy tray assemblies. Cost compression in narrow-body Economy provisioning is intensifying because EU Green Deal waste mandates force dual inventory maintenance for legacy galley compatibility. Charter operators exhibit highest price sensitivity due to variable manifests, while full-service carriers prioritize outcome-based contracts tied to waste reduction metrics over per-meal unit pricing.
Supply Chain Analysis
Logistics costs escalate sharply for airport-adjacent cold chain operations where HACCP-qualified technician scarcity drives wage premiums across Germany, France, and the United Kingdom. Fresh protein sourcing draws from seasonal EU agricultural output, while REACH-compliant biodegradable packaging materials hinge on specialized suppliers in the Netherlands and Belgium. Single-source vulnerability concentrates in EASA-certified galley equipment manufacturers for narrow-body retrofit approvals. Distribution runs through centralized kitchen networks serving hub airports with spoke-feed logistics zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Lufthansa Group and Air France-KLM procurement consolidation favors caterers with chef-driven premium capabilities over pure-scale operators.
For Market Incumbents: Anchor hub-centralized production density at Frankfurt, Amsterdam Schiphol, and London Heathrow through exclusive ground-handling rights with airport authorities. Consolidate supplier relationships around waste-linked outcome contracts to defend against AI-driven demand forecasting entrants. Certification investment in EASA live-cooking capabilities at premium kitchens protects margin pools as airlines compress vendor rosters. For New Entrants and Emerging Players: Launch via specialized charter and business aviation contracts in underpenetrated Poland, Hungary, and Romania where flexible provisioning meets Eastern European leisure route expansion. Target electrified ground support mandates at EU airports as first-mover advantage for battery-powered catering truck fleets. White-space opportunity concentrates in AI-integrated demand forecasting pilots with narrow-body operators lacking scale to amortize tracking investments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier tray-assembly operators without premium cabin culinary partnerships or hub scale. Long-term viability favors caterers with backward integration into altitude-adjusted formulation science and blockchain-enabled provenance tracking. The signal to watch is consolidation pace around outcome-based contracts as Lufthansa Group and Air France-KLM procurement templates diffuse across IAG and SAS networks.| Strategic Initiative | Industry Significance |
|---|---|
| Chef-Driven Premium Kitchen Investment | DO & CO Aktiengesellschaft-style partnerships command margin premiums as full-service carriers expand First Class offerings. |
| Blockchain Provenance Integration | Immutable chain-of-custody documentation compresses supplier audit cycles for EU Green Deal waste reporting compliance. |
| Electrified Ground Support Fleet Deployment | Battery-powered catering trucks capture first-mover advantage under EU airport decarbonization timelines at major hubs. |
| AI Demand Forecasting Pilot Programs | Machine learning integration with airline reservation systems enables dynamic meal loading that cuts waste and unlocks sustainability credentials. |
| Eastern European Charter Network Expansion | Specialized catering contracts in Poland, Hungary, and Romania access white-space growth beyond established hub infrastructure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airline procurement directors, catering operations executives, HACCP compliance officers, and airport authority ground-handling managers with secondary validation through EASA safety directives, EU Green Deal regulatory filings, REACH chemical registration databases, and airline sustainability reports. Bottom-up segment sizing triangulated against top-down market aggregation across service type, product type, delivery mode, and customer type dimensions.
Segment-weighted modeling applied differential growth assumptions across Meal Service, Beverage Service, and Special Meal Service categories with altitude-adjusted formulation adoption curves and waste reduction mandate compliance timelines as industry-specific forecast inputs. CAGRs derived from logistic curve fitting to historical loading data and projected passenger volume trajectories across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU agricultural subsidy shifts or EASA galley equipment certification backlogs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Switzerland Food Service Market
Food Service
India Foodservice Market
Food Service
Chinese Takeout Market
Food Service
Europe Cloud Kitchen Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Ice Cream Carts Market
Food Service
France Foodservice Market
Food Service
Food Service Gloves Market
Food Service
Tabletop Pizza Oven Market
Food Service
South America Free from Food Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Brazil Foodservice Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Singapore Food Service Market