
 Asia-Pacific Halal Food and Beverage Market | 2026-2036
Asia-Pacific Halal Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Halal Food and Beverage Market Outlook
Indonesia's BPJPH halal certification mandate is broadening the cost-of-entry calculus for exporters seeking access to the world's largest Muslim consumer base. Nestlé S.A. leverages its established certification infrastructure across multiple Asia-Pacific jurisdictions to sustain compliant production at scale. QL Foods Sdn Bhd anchors its position through deep specialization in processed meat and seafood segments with Malaysian JAKIM endorsement. Ramly Food Processing competes on brand recognition and channel control within domestic Malaysian retail and food service networks.
Halal food and beverage encompasses consumable products manufactured, processed, and handled in strict accordance with Islamic dietary law, requiring absence of pork derivatives, alcohol, and non-halal animal byproducts, with slaughter protocols mandating specific invocation and blood drainage. The primary commercial purpose centers on serving Muslim populations while increasingly attracting ethical and quality-conscious non-Muslim consumers seeking assured supply chain integrity. Meat and dairy segments occupy the dominant value share given their centrality to daily protein consumption and the technical complexity of maintaining halal integrity through processing. Online shoppers represent the fastest-growing end-user category as digital platforms reduce certification verification friction and expand access beyond traditional retail footprints.
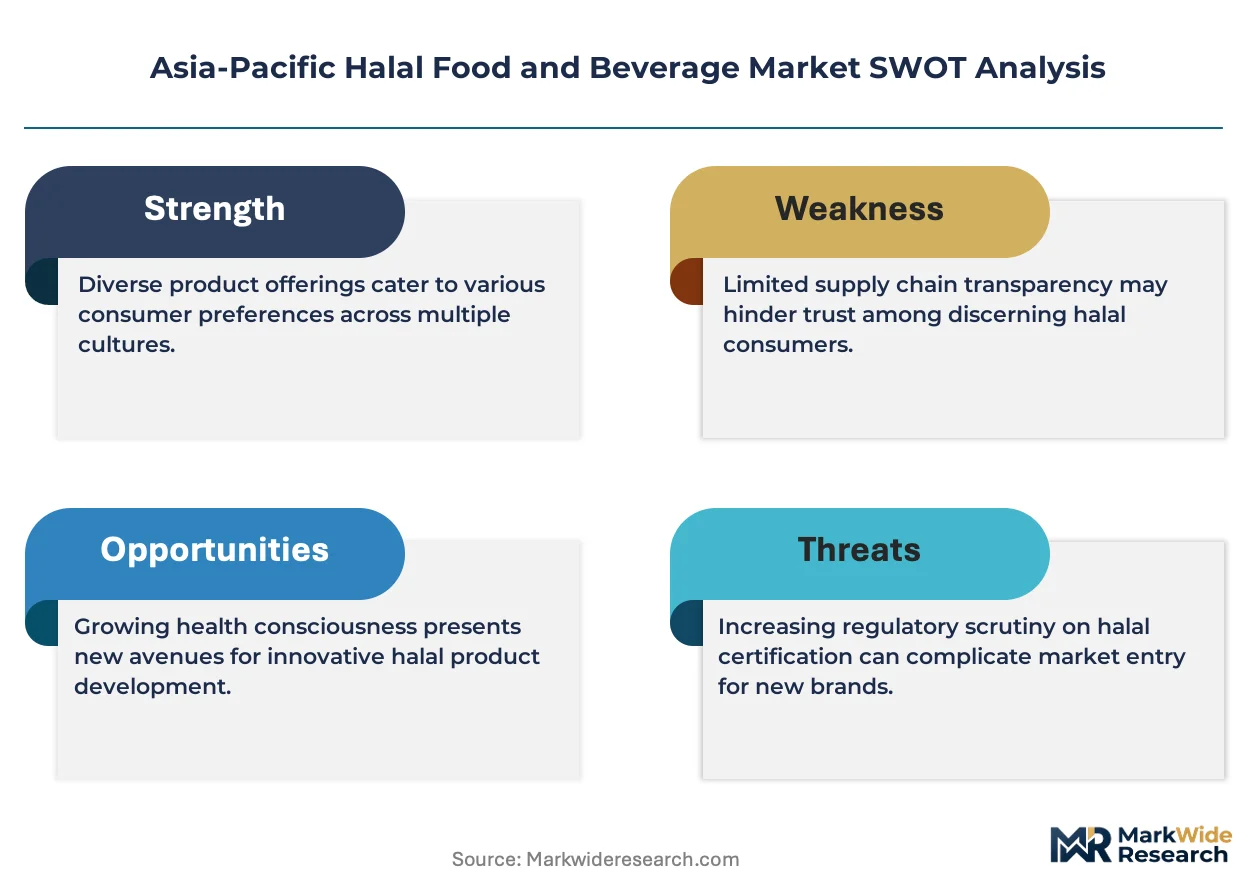
Malaysia's Department of Islamic Development (JAKIM), Indonesia's Halal Product Assurance Agency (BPJPH), and Australia's Islamic Coordinating Council each enforce distinct certification protocols that fragment compliance requirements across the region. These regulatory frameworks shape demand by elevating product standards and creating non-tariff barriers that favor suppliers with established multi-jurisdiction certification capabilities. Stakeholders must monitor divergence between national halal standards and the emerging push for mutual recognition agreements that could reshape competitive access across Southeast Asian markets.
Market Dynamics
Indonesia's BPJPH mandate is compressing certification timelines and forcing exporters to restructure supply chains around Jakarta's halal assurance infrastructure. This regulatory compression is redrawing competitive access across Southeast Asian markets.
Growth Catalysts
- Digital verification platforms:Blockchain-enabled halal traceability systems are collapsing certification friction for cross-border meat and dairy shipments. Exporters leveraging these tools secure faster market entry into Indonesia and Malaysia.
- Malaysia's JAKIM mutual recognition push:Bilateral agreements with Middle Eastern halal authorities are opening re-export corridors for Malaysian-certified products. Food manufacturers in Penang and Selangor are capturing transit trade value.
- Non-Muslim ethical consumption:Quality-assurance seekers in Australia, South Korea, and Japan are importing JAKIM-certified products as clean-label alternatives. This demand expansion is diversifying revenue streams beyond core Muslim demographics.
Market Restraints
- Livestock input cost volatility:Australian and New Zealand cattle and sheepmeat prices fluctuate with feed grain markets and climate shocks. Processors face margin compression when procurement costs spike without corresponding pricing power.
- Slaughterhouse concentration risk:Halal-compliant abattoir capacity clusters in specific Australian states and New Zealand regions. Supply disruptions from biosecurity incidents or labor shortages propagate rapidly through downstream value chains.
- Regulatory fragmentation:Divergent slaughter protocols between Indonesia's BPJPH and Malaysia's JAKIM create compliance duplication. Exporters serving both markets absorb redundant audit and facility segregation costs.
Strategic Opportunities
- Vietnam's underpenetrated Muslim corridor:The Cham Muslim population in central Vietnam and growing Middle Eastern tourism in Da Nang and Ho Chi Minh City create nascent demand pockets. Early movers can establish brand presence before regulatory frameworks mature.
- Plant-based halal convergence:Cellular agriculture and precision fermentation technologies are enabling slaughter-free protein production that satisfies Islamic dietary law. Singapore's food tech ecosystem is incubating ventures targeting this intersection.
- Quick-commerce channel expansion:Halal-certified dark kitchens and 15-minute grocery delivery platforms are penetrating Jakarta, Kuala Lumpur, and Bangkok suburbs. Specialized logistics providers are capturing last-mile value previously held by traditional retail.
Industry Challenges
- Halal auditor talent scarcity:Qualified sharia compliance officers with veterinary science backgrounds are concentrated in Malaysia and Indonesia. Exporters in Thailand and the Philippines struggle to staff in-house certification teams.
- Legacy ERP integration friction:Established food manufacturers operate on decades-old batch tracking systems. Retrofitting these platforms for real-time halal ingredient segregation requires substantial capital deployment and operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Halal Food and Beverage Market |
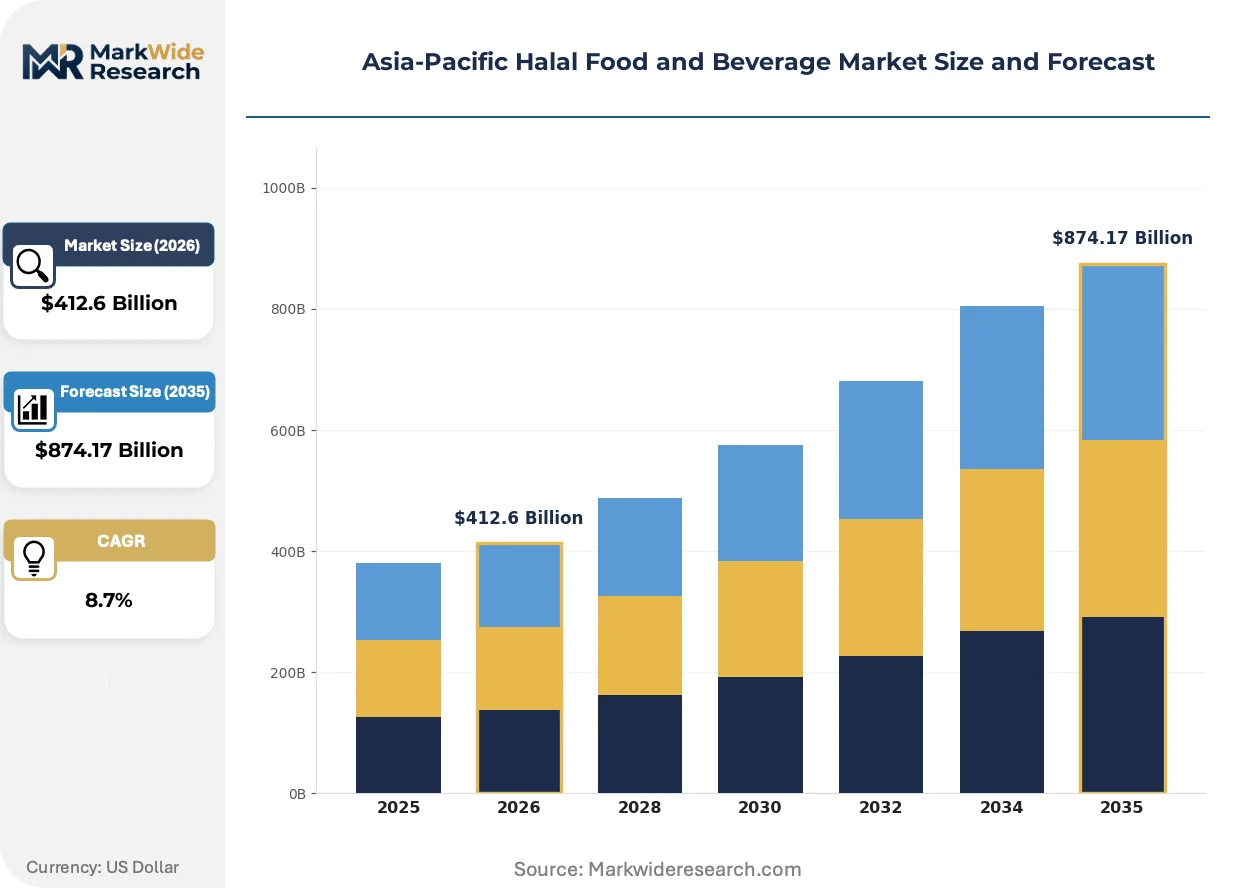
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $874.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Snacks, Beverages End User: Retail Customers, Food Service, Institutions, Online Shoppers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales Certification: Halal Certified, Local Certification, International Certification, Others |
| Companies Covered | Nestlé S.A., Unilever PLC, Cargill, Incorporated, BRF S.A., QL Foods Sdn Bhd, Kawan Foods Berhad, Prima Agri-Products, Ramly Food Processing, Al-Falah Halal Foods Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Halal Food and Beverage Market Strategic Shifts
Digital traceability infrastructure and alternative protein platforms are restructuring how halal integrity is verified and produced. These shifts are compressing traditional certification timelines while opening new technical pathways to compliance.
Blockchain-enabled supply chain tracking is absorbing verification workload previously handled by paper-based audit trails. Major Indonesian retailers and food service operators are mandating digital halal passports for upstream suppliers. This technology is absorbing documentation costs while accelerating customs clearance at Jakarta's Tanjung Priok port.
Indonesia's BPJPH regulatory overhaul is compelling foreign manufacturers to establish in-country halal inspection partnerships. The mandate requires on-site sharia auditors for production facilities exporting to Indonesian markets. Australian meat processors are responding by embedding BPJPH-accredited personnel within their quality assurance departments.
Ethical consumption patterns among non-Muslim urban populations in Seoul, Tokyo, and Sydney are redirecting procurement toward certified products. Retail buyers in these cities are prioritizing JAKIM and BPJPH endorsements as shorthand for supply chain transparency. This behavioral shift is most visible in premium supermarket channels where certification badges command shelf placement premiums.
Asia-Pacific Halal Food and Beverage Market Segmentation
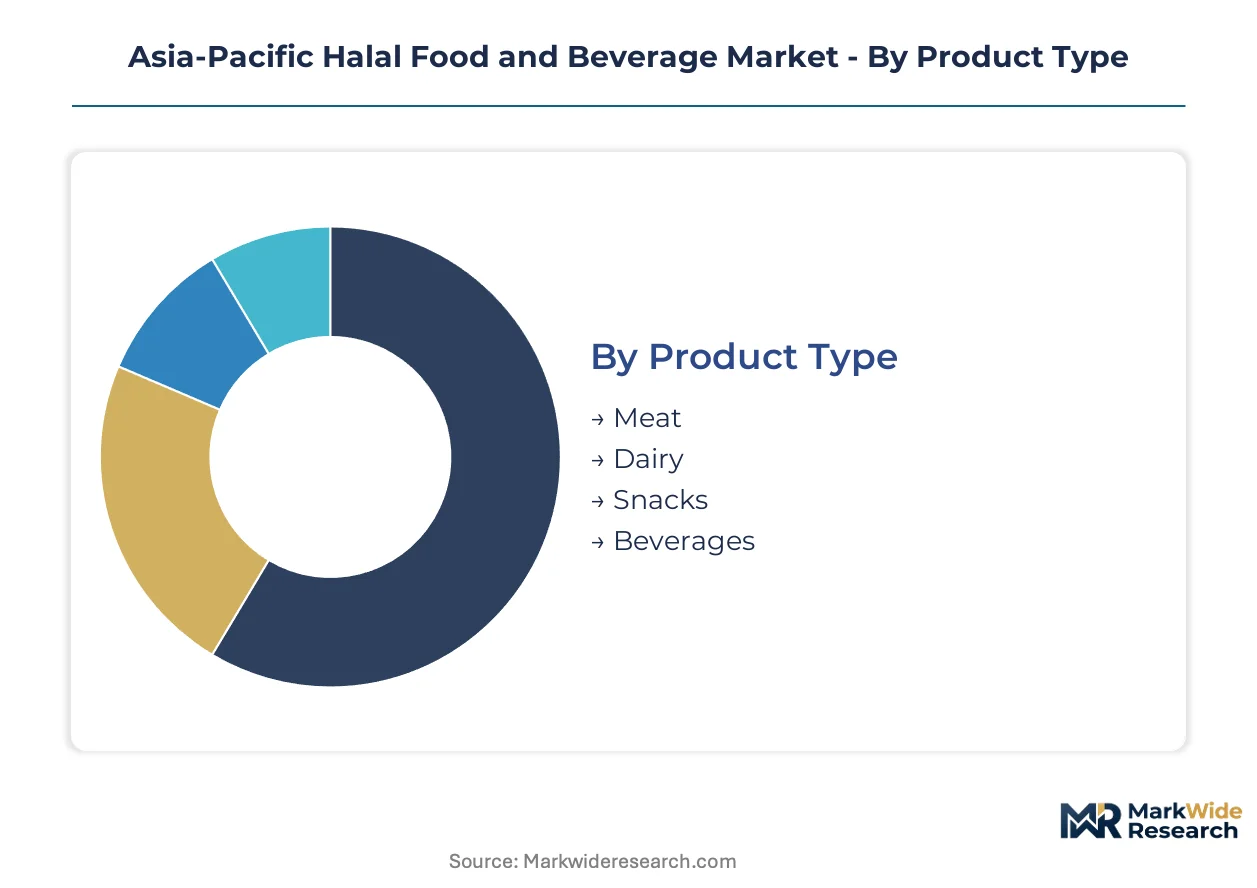
Halal food and beverage segmentation reveals how certification complexity, channel fragmentation, and end-user diversity create distinct competitive arenas. Suppliers must align product portfolios with specific compliance tiers and distribution economics to capture value across Muslim-majority and export-oriented markets.
Product Type:
Production assets for fresh proteins concentrate near slaughterhouse infrastructure in Australia, New Zealand, and Malaysia, while processed categories distribute manufacturing more broadly.
- Meat:Fresh and frozen beef, lamb, and poultry requiring JAKIM or BPJPH-compliant slaughter and segregation protocols. Australian processors in Queensland and Victoria dominate export supply to Indonesian importers facing compressed certification timelines.
- Dairy:Milk, cheese, and yogurt products where halal integrity hinges on enzyme sourcing and cross-contamination controls during co-packing. Malaysian UHT milk producers leverage integrated dairy farms to maintain chain-of-custody documentation for Middle Eastern re-export markets.
- Snacks:Processed savory and sweet items with halal gelatin and flavoring substitutions. Thai and Philippine manufacturers compete on cost for regional distribution within ASEAN trade corridors.
- Beverages:Non-alcoholic drinks including functional waters and juices where halal compliance centers on processing aids and packaging materials. Indonesian bottlers in Java command domestic volume through direct-store-delivery networks.
Meat absorbs the bulk of installed capacity; beverages are expanding most quickly.
End User:
Demand patterns diverge sharply between institutional procurement with long-term contract structures and fragmented retail purchasing where certification visibility drives selection.
- Retail Customers:Individual consumers purchasing through supermarkets and neighborhood provision shops. Urban Indonesian households in Jakarta and Surabaya prioritize BPJPH logo recognition when selecting packaged proteins.
- Food Service:Restaurants, hotels, and catering operations requiring bulk halal ingredients with consistent supply reliability. Malaysian hotel chains in Kuala Lumpur and Penang mandate JAKIM certification for all protein suppliers to serve Middle Eastern tourists.
- Institutions:Schools, hospitals, and government facilities with tender-based procurement and price-sensitive specifications. State education departments in Indonesia centralize halal meal contracts through designated distributors.
- Online Shoppers:Digital-native consumers purchasing through e-commerce platforms and quick-commerce apps. Singapore-based dark kitchen operators source certified ingredients through specialized B2B marketplaces with blockchain verification.
Food service captures the largest contract value; online shoppers are climbing the fastest.
Distribution Channel:
Channel economics vary with certification documentation burdens, cold chain requirements, and the need for halal segregation during last-mile handling.
- Supermarkets:Hypermarket and supermarket chains with dedicated halal sections and in-house certification verification. Indonesian retailers such as Transmart and Superindo require supplier digital halal passports for shelf placement.
- Online Retail:E-commerce platforms and grocery delivery apps collapsing geographic access constraints. Malaysian platforms like Lazada and Shopee have introduced halal verification badges to reduce consumer search friction.
- Specialty Stores:Independent halal butchers, ethnic grocers, and religious bookstores with curated assortments. These outlets concentrate in Sydney's Lakemba and Melbourne's Coburg for Australian Muslim communities.
- Direct Sales:Manufacturer-to-institution contracts and subscription-based meat box deliveries. New Zealand lamb exporters maintain direct relationships with Indonesian hotel groups to bypass distributor margins.
Supermarkets retain the deepest penetration; online retail is gaining share fastest.
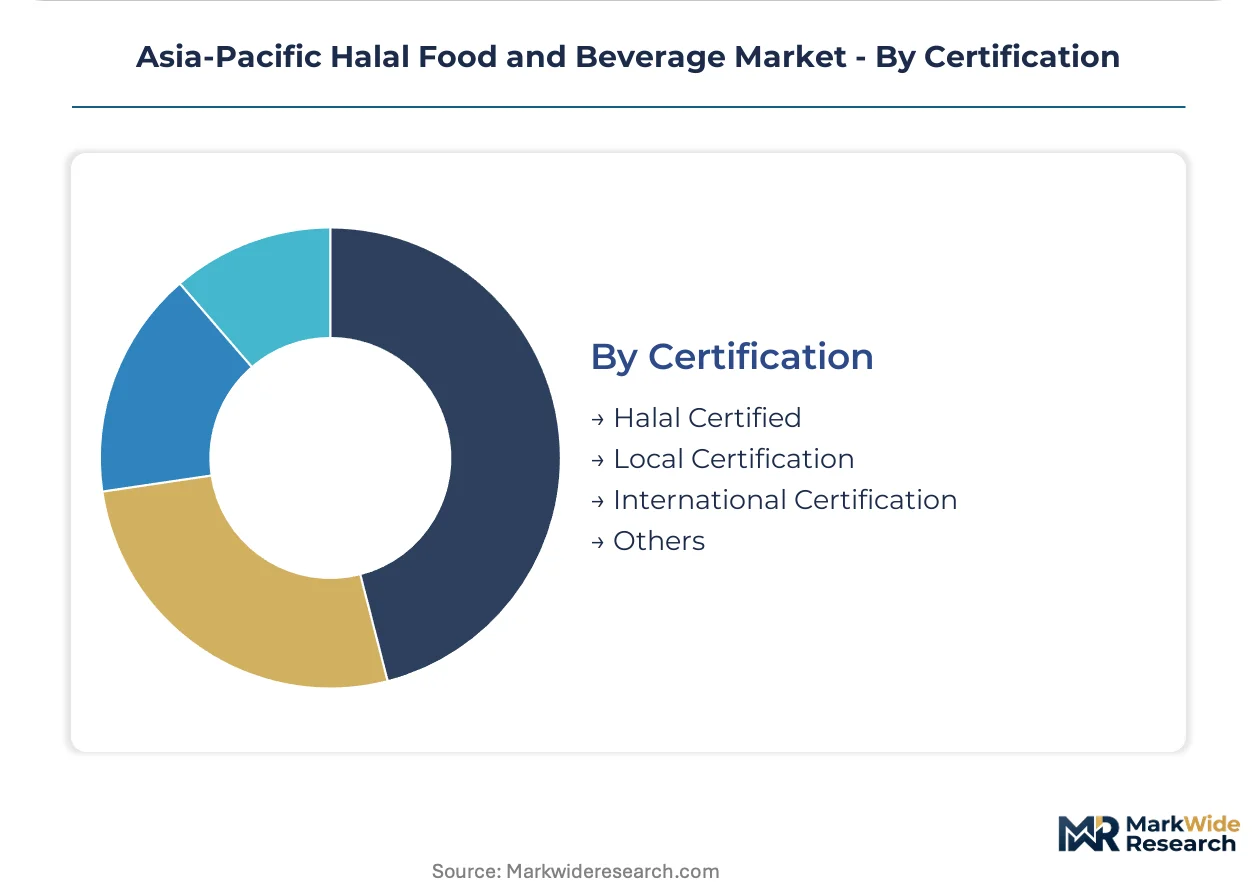
Certification:
Regulatory divergence between national halal authorities fragments compliance pathways and elevates costs for multi-market suppliers.
- Halal Certified:Products bearing recognized halal marks from JAKIM, BPJPH, or equivalent national bodies. This baseline tier satisfies domestic market entry requirements across Indonesia and Malaysia.
- Local Certification:Sub-national or single-jurisdiction approvals such as Australian state-level halal programs or Thai provincial Islamic council endorsements. Exporters using local certification face barriers when crossing into stricter neighboring markets.
- International Certification:Multi-jurisdiction approvals including GAC accreditation for Gulf Cooperation Council access or mutual recognition arrangements between JAKIM and Middle Eastern authorities. Malaysian manufacturers in Selangor exploit these pathways for re-export competitiveness.
- Others:Emerging blockchain-verified halal credentials and private assurance schemes from major retailers. Singaporean food tech ventures pilot slaughter-free protein certifications that sit outside traditional sharia board oversight.
Halal certified dominates current volume; international certification shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia commands the dominant demand position with the world's largest Muslim population driving sustained procurement of certified meat and dairy products. Malaysia anchors the regulatory innovation layer through JAKIM's mutual recognition diplomacy with Middle Eastern authorities. Australia and New Zealand supply the upstream protein infrastructure, while Vietnam and Thailand represent emerging demand corridors with nascent Muslim consumer bases and inbound Middle Eastern tourism.
Indonesia
Jakarta and Surabaya households drive packaged protein consumption through BPJPH logo recognition at point of purchase. BPJPH's halal certification mandate compresses exporter timelines and forces on-site sharia auditor placement in foreign production facilities. Java-based bottlers command domestic beverage volume through direct-store-delivery networks penetrating suburban Jakarta corridors.
Malaysia
Kuala Lumpur hotel chains mandate JAKIM certification for all protein suppliers serving Middle Eastern tourist segments. JAKIM bilateral agreements with Gulf Cooperation Council authorities open re-export corridors for Penang and Selangor manufacturers. Selangor food processors capture transit trade value through integrated certification infrastructure spanning production and packaging stages.
Australia
Queensland and Victoria processors dominate export supply to Indonesian importers facing compressed BPJPH certification timelines. The country's national food safety regulator maintains parallel halal compliance protocols alongside state-level Islamic council endorsements. Australian meat processors embed BPJPH-accredited personnel within quality assurance departments to satisfy Jakarta's on-site inspection requirements.
New Zealand
Lamb exporters maintain direct contractual relationships with Indonesian hotel groups to bypass distributor margin capture. Regional halal abattoir capacity concentrates in specific South Island and North Island zones vulnerable to biosecurity disruption propagation. Canterbury processors leverage integrated farm-to-fork documentation systems for Middle Eastern re-export market access.
Vietnam
The Cham Muslim population in central provinces and growing Middle Eastern tourism in Da Nang create nascent certified product demand pockets. Provincial Islamic council frameworks remain underdeveloped relative to JAKIM or BPJPH standards, creating first-mover positioning opportunities. Ho Chi Minh City quick-commerce platforms are piloting halal-verified dark kitchen concepts targeting expatriate and tourist segments.
Asia-Pacific Halal Food and Beverage Market Competitive Environment
Malaysian producers anchor one tier through JAKIM-endorsed manufacturing infrastructure; Australian and New Zealand processors hold upstream protein supply dominance. The vendor base stratifies across integrated multinational food conglomerates with multi-jurisdiction certification capabilities and domestic specialists with deep channel control in single markets. Three archetypes prevail: scale-driven certifiers with regional production footprints, category specialists in processed meat and seafood segments, and brand-recognized domestic operators with retail network penetration. Competitive dynamics center on certification infrastructure investment and strategic partnerships with sharia audit bodies.
Within the multinational certifier tier, Nestlé S.A. and Unilever PLC exemplify archetypes leveraging established multi-jurisdiction compliance infrastructure for sustained scale production. Among Southeast Asian specialists, QL Foods Sdn Bhd occupies a position representing deep segment focus with Malaysian JAKIM endorsement, while Ramly Food Processing anchors domestic brand recognition within Malaysian retail and food service channels. These named entities sit within broader competitive patterns where certification capability concentration determines market access velocity across Indonesia and Malaysia.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Unilever PLC |
| Cargill, Incorporated |
| BRF S.A. |
| QL Foods Sdn Bhd |
| Kawan Foods Berhad |
| Prima Agri-Products |
| Ramly Food Processing |
| Al-Falah Halal Foods Ltd |
| Others |
Value Chain & Pricing Dynamics
BPJPH's halal certification mandate gates both qualified supply and premium-tier pricing access across Indonesian import channels. Exporters absorbing on-site sharia auditor placement costs pass through margin requirements that stratify pricing across certification-ready and compliance-lagging supplier tiers.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement contracts, with premium multiples attaching to guaranteed short-delivery windows for fresh proteins and spot inventory clearing at discounted rates for frozen stock approaching shelf limits. Pricing stratifies across JAKIM-endorsed premium tiers, BPJPH-compliant standard tiers, and uncertified economy alternatives. Cost compression in Australian cattle procurement is intensifying because feed grain volatility and climate shocks transmit directly into processor margins. Institutional buyers in Indonesian state education tenders exhibit highest price sensitivity, while Kuala Lumpur hotel chains serving Middle Eastern tourists show lowest sensitivity to certification-premium pricing.
Supply Chain Analysis
Workforce availability constraints in Queensland and Victoria abattoirs, South Island processing zones, and Selangor manufacturing corridors limit scalable halal-compliant production expansion. Geographic supply concentrates in Australia, New Zealand, and Malaysia, with raw material dependencies centering on Australian and New Zealand livestock, Malaysian palm-derived processing aids, and Indonesian domestic dairy inputs. Single-source vulnerability propagates rapidly from biosecurity incidents or labor shortages at concentrated halal abattoir sites. Distribution runs through Jakarta's Tanjung Priok port clearance, Kuala Lumpur distributor hubs, and direct-store-delivery networks penetrating Indonesian suburban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is compressing margin structures and forcing weaker capitalized exporters toward exit or acquisition, positioning this market as a consolidation play for well-resourced operators.
For Market Incumbents: Acquire BPJPH-accredited sharia auditor talent pools to internalize compliance capabilities and reduce third-party audit dependency. Nestlé S.A.-scale operators should embed on-site inspection personnel within Australian and New Zealand quality assurance departments, mirroring established multi-jurisdiction certification infrastructure. Backward integration into captive livestock supply contracts with Queensland and Victoria producers defends against feed cost volatility and biosecurity disruption propagation.
For New Entrants and Emerging Players: The price-point gap between JAKIM-endorsed premium imports and uncertified domestic Indonesian alternatives creates white-space positioning for mid-tier certification investment. Target Vietnam's Cham Muslim corridor in central provinces and Da Nang tourism corridors before regulatory frameworks mature and incumbent brand presence solidifies. Launch through quick-commerce dark kitchen partnerships in Ho Chi Minh City to establish proof-of-concept with minimal fixed asset deployment.
For Investors and Strategic Acquirers: BPJPH mutual recognition agreement announcements with Gulf Cooperation Council authorities are the leading indicator that Malaysian re-export corridor value will concentrate among integrated certification holders. Five-to-ten year viability favors operators with multi-jurisdiction endorsement infrastructure spanning JAKIM, BPJPH, and GAC accreditation tiers. Monitor Indonesian retailer mandates for blockchain-enabled halal passports as the signal that digital verification capability gaps will separate acquirable targets from stranded assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | BPJPH-JAKIM-GAC triple endorsement unlocks Indonesian, Malaysian, and Gulf market access simultaneously. |
| Blockchain Halal Passport Deployment | Digital traceability infrastructure satisfies Transmart and Superindo supplier mandates while accelerating customs clearance. |
| Sharia Auditor Talent Acquisition | In-house BPJPH-accredited personnel eliminate third-party audit bottlenecks and compress certification timelines. |
| Quick-Commerce Channel Partnership | Dark kitchen integration in Jakarta and Kuala Lumpur suburbs captures last-mile value from platform expansion. |
| Plant-Based Halal Convergence R&D | Singapore food tech ecosystem partnerships position for slaughter-free protein regulatory recognition. |
Study Parameters
Indonesian customs records, Malaysian Department of Islamic Development certification registries, and Australian Bureau of Agricultural and Resource Economics trade statistics formed the secondary backbone of this analysis. Primary interviews with halal certification officers at JAKIM and BPJPH, procurement directors at Indonesian hotel chains, quality assurance leads at Queensland meat processors, and category buyers at Malaysian supermarket operators combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis of certified product trade flows, slaughterhouse capacity utilization patterns, and retail channel penetration rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and certification tier, with CAGRs derived from regression analysis against Muslim population growth, regulatory mandate implementation timelines, and digital platform adoption curves. Forecast inputs incorporated BPJPH inspector deployment schedules and JAKIM mutual recognition negotiation status.
Inputs from JAKIM certification databases and BPJPH foreign facility audit records were available through the study window; gaps in real-time blockchain halal passport adoption metrics introduce uncertainty bands around quick-commerce channel growth assumptions. Forecasts reflect documented assumptions regarding regulatory implementation pace and mutual recognition timeline achievement. Material deviation in BPJPH enforcement intensity or JAKIM-GCC agreement finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Pizza Oven Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Instant Noodle Vending Machine Market
Food Service
US Food Service Market
Food Service
Shaker Bottles Market
Food Service
Vietnam Food Service Market
Food Service
Smart Food Logistics Market
Food Service
Food Service Disposables Market
Food Service
Full-Service Restaurants Market
Food Service
Instant Grocery Market
Food Service
Workplace Service Market
Food Service
Commercial Ice Dispenser Market
Food Service
Peer-To-Peer Dining Market
Food Service
France Foodservice Market
Food Service
Global Waffle Maker Market
Food Service
Tabletop Pizza Oven Market