
 Snack Subscription Box Service Market | 2026-2036
Snack Subscription Box Service Market Size, Share, and Industry Trends Forecast 2026-2036
Snack Subscription Box Service Market Insights
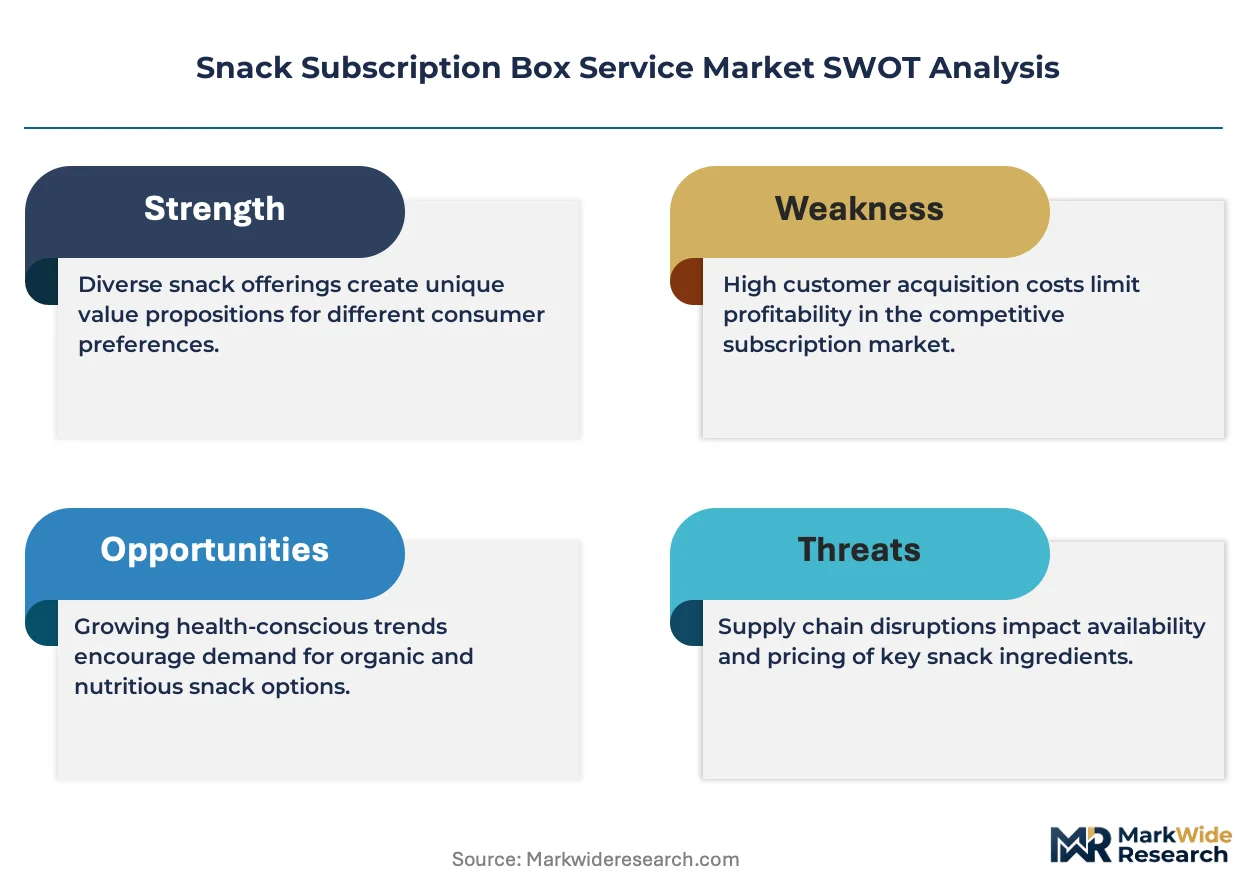
USDA Organic certification is unwinding competitive barriers as smaller curators enter the snack subscription box service space. UrthBox leverages its established supplier network to sustain organic SKU depth across monthly cycles. NatureBox anchors its position through health-focused curation that dominates the wellness-oriented subscriber base. MunchPak competes on international variety velocity, rotating country-themed assortments faster than regional rivals.
A snack subscription box service is a recurring-commerce platform that assembles curated edible assortments—typically shelf-stable items with moisture content below 0.6 water activity—into scheduled deliveries for consumer discovery and convenience. Monthly plans and customizable boxes lead subscription model revenue, while quarterly plans capture gift purchasers seeking lower-commitment entry points. Organic snacks and healthy options command premium positioning, whereas indulgent treats occupy higher-frequency reorder tiers among younger demographics.
FDA nutrition labeling requirements and state-level extended producer responsibility frameworks shape product selection and packaging specifications for operators across the United States. USDA Organic and Non-GMO Project standards gate supplier eligibility, raising procurement complexity for mid-tier curators. Stakeholders must monitor evolving state packaging mandates and certification costs to preserve margin structure as compliance thresholds tighten.
Market Dynamics
Curated discovery models are reshaping household purchasing patterns as Millennial and Gen Z consumers prioritize experiential consumption over transactional grocery buying. FDA nutrition labeling mandates and state-level extended producer responsibility laws are compressing supplier qualification timelines and forcing packaging redesign cycles.
Growth Catalysts
- USDA Organic Certification:Standardized eligibility criteria lower barriers for smaller curators to source certified inventory. Procurement networks expand as verification processes streamline.
- Extended Producer Responsibility Frameworks:California and New York packaging mandates accelerate compostable material adoption. Subscription operators redesign box formats to preempt compliance deadlines.
- Moisture-Control Packaging:Shelf-stable formulations with sub-0.6 water activity enable longer fulfillment cycles. Logistics providers extend regional reach without cold-chain dependency.
Market Restraints
- Input Cost Volatility:Organic nut and dried fruit commodity prices fluctuate with California agricultural yields. Margin pressure concentrates in premium SKU tiers.
- Supplier Concentration Risk:Domestic organic snack manufacturing clusters in the Pacific Northwest. Disruption events cascade through multiple subscription networks simultaneously.
- Substitution Threat:Direct-to-consumer brand websites bypass curation premiums. Loyalty program investments by individual snack manufacturers fragment subscriber retention.
Strategic Opportunities
- Underpenetrated Geography:Japanese metropolitan households show rising trial rates for Western snack assortments. Localization partnerships with domestic distributors reduce customs friction.
- Regulatory Tailwind:United Kingdom plastic packaging tax incentivizes fiber-based inserts. Early adopters capture sustainability-positioned subscriber segments.
- Channel Innovation:Employer wellness benefit integrations create B2B2C acquisition paths. Human resources platforms embed subscription allowances into flexible spending arrangements.
Industry Challenges
- Compliance Timeline Compression:Non-GMO Project verification cycles extend 14-18 weeks. Launch schedules slip when supplier documentation gaps emerge.
- Legacy System Integration:Warehouse management platforms built for single-SKU fulfillment struggle with high-variety kitting. Custom middleware development consumes technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snack Subscription Box Service Market |
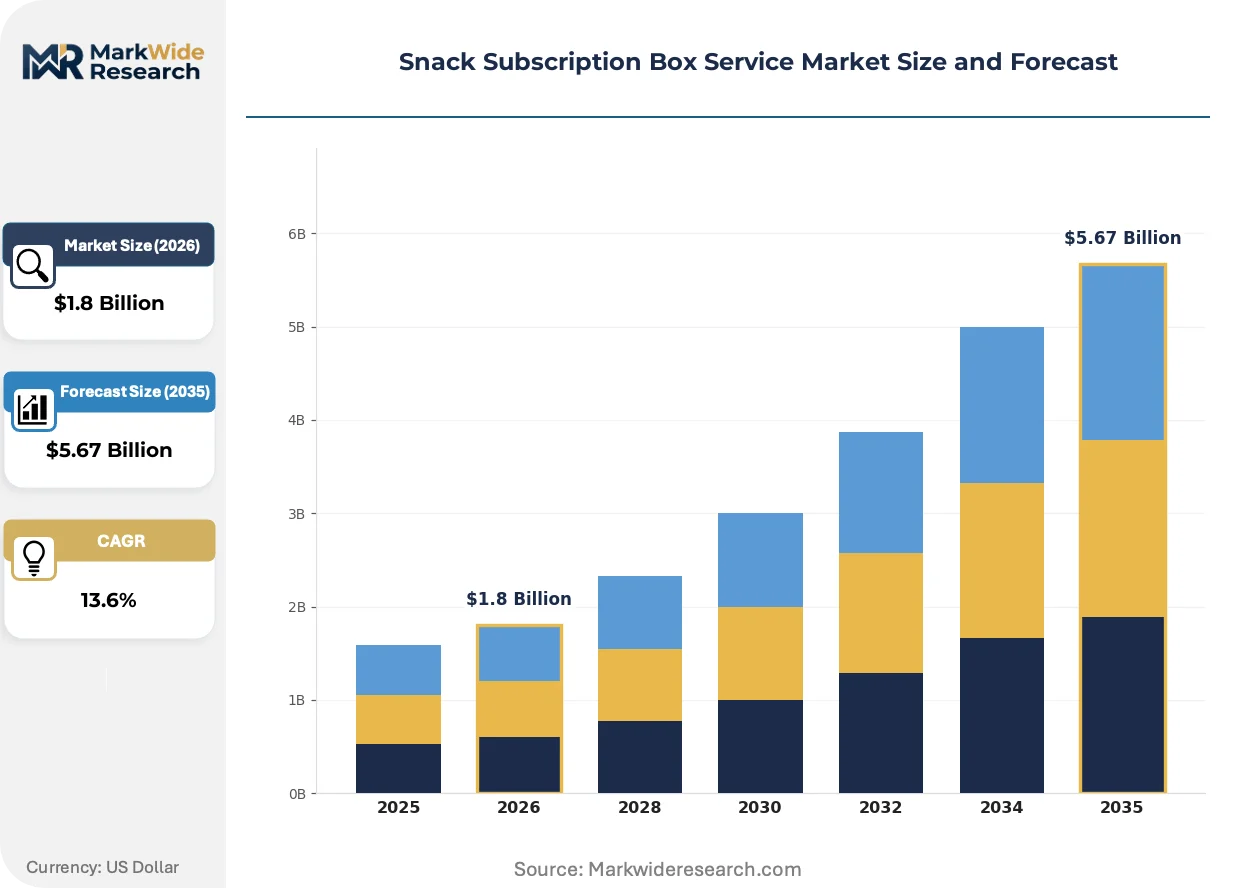
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.67 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Snacks, Healthy Options, Indulgent Treats, Savory Items Target Audience: Families, Students, Health Enthusiasts, Office Workers Subscription Model: Monthly Plans, Quarterly Plans, Customizable Boxes, Gift Subscriptions Packaging Type: Recyclable Boxes, Eco-Friendly Wrappers, Standard Packaging, Bulk Orders |
| Companies Covered | UrthBox, Japan Crate, NatureBox, SnackCrate, Universal Yums, Vegancuts Snack Box, MunchPak, Jerky Snob, Mantry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snack Subscription Box Service Market Trends and Innovations
Algorithmic curation and sustainable packaging chemistry are converging to redefine value propositions. Operators invest in predictive preference modeling and biodegradable barrier films simultaneously.
Machine learning recommendation engines analyze consumption velocity and rating patterns to personalize monthly assortments. Wellness-focused subscribers receive algorithm-weighted healthy options at higher frequencies. Predictive curation is displacing static category rotations in retention-sensitive segments.
California's extended producer responsibility law mandates 30% post-consumer recycled content in shipping containers by 2028. Operators accelerate fiber-based cushioning and soy-based ink transitions to avoid penalty structures. Small-to-mid-tier curators face disproportionate reformulation costs versus integrated competitors with captive packaging operations.
Subscription fatigue among urban households drives demand for pause-flexible plans and single-box trials. Gift purchasers favor quarterly commitments with explicit expiration dates over auto-renewing structures. United Kingdom consumers show highest sensitivity to cancellation friction, prompting operators to adopt one-click termination interfaces.
Snack Subscription Box Service Market Segmentation
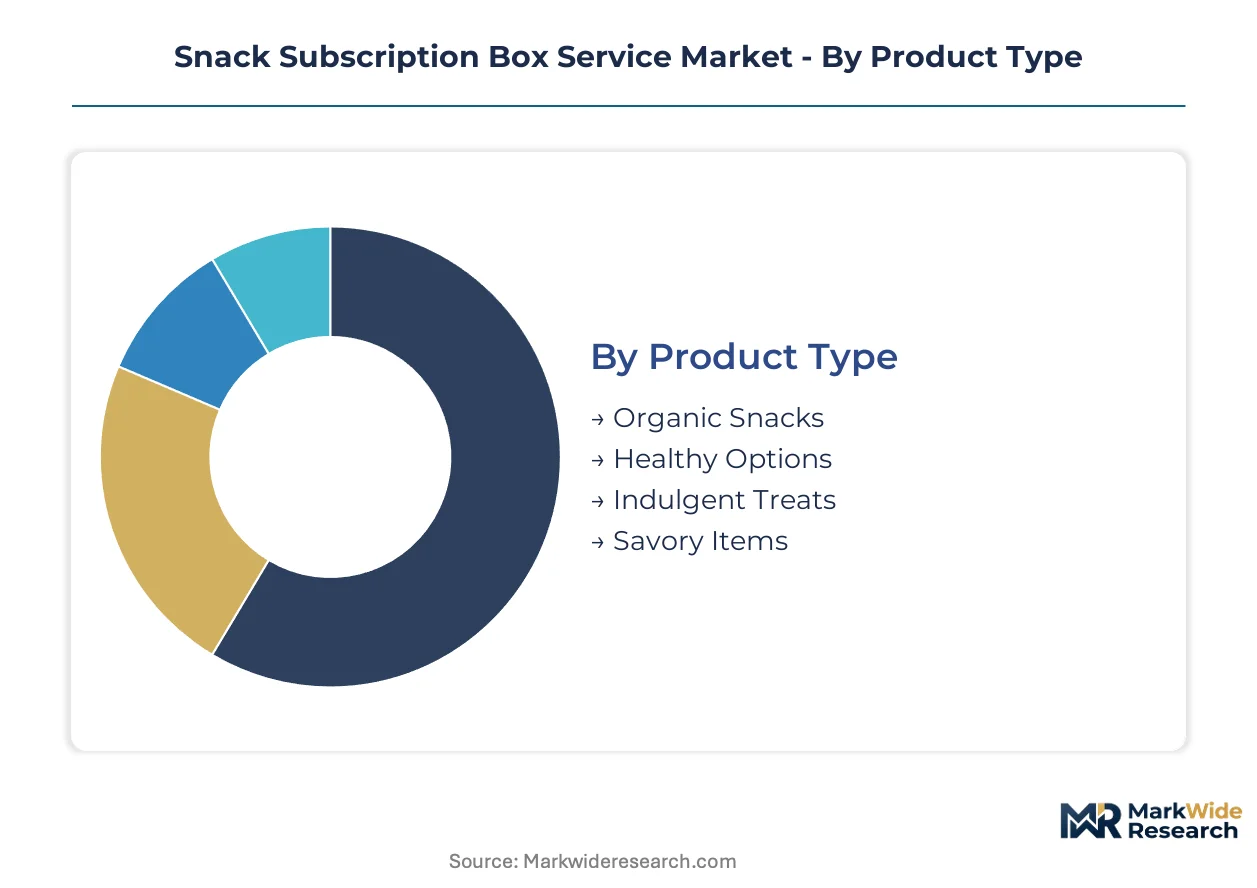
Segmentation in snack subscription services determines sourcing strategies, fulfillment economics, and regulatory exposure. Operators calibrate inventory depth and packaging specifications differently across each dimension, with USDA Organic certification and state EPR mandates creating divergent cost structures.
Product Type:
Domestic demand concentrates in health-positioned assortments, while export-led growth accelerates for indulgent and savory formats in Asian metropolitan markets.
- Organic Snacks:Products bearing USDA Organic certification require verified supplier networks with documented chain-of-custody. California and Pacific Northwest households drive premium-tier subscriptions, though FDA nutrition labeling compliance extends procurement timelines.
- Healthy Options:Formulations emphasizing reduced sodium, no added sugar, or functional ingredients like adaptogens. Health Enthusiasts in coastal US cities and London metropolitan areas anchor demand, with Non-GMO Project verification filtering supplier eligibility.
- Indulgent Treats:Higher-frequency reorder tiers among Gen Z subscribers.
- Savory Items:Japanese and South Korean trial rates climbing for Western flavor profiles.
Organic Snacks commands the established base. The steepest expansion runs through Indulgent Treats.
Target Audience:
Cost tier differentiation separates premium wellness positioning from mass-market convenience plays.
- Families:Bulk-format subscriptions with child-friendly portioning and allergen-controlled assortments. Suburban US households prioritize pause-flexible plans, while UK consumers show heightened cancellation friction sensitivity.
- Students:Compact box formats with dorm-friendly shipping dimensions and semester-aligned billing cycles. University towns in the Northeast US and Midwest generate concentrated demand, though price sensitivity compresses margin per box.
- Health Enthusiasts:Algorithm-weighted curation with predictive preference modeling.
- Office Workers:Employer wellness benefit integrations expanding B2B2C acquisition paths.
Families anchor volume throughput. Health Enthusiasts deliver the highest lifetime value per subscriber.
Subscription Model:
Application-driven segmentation separates discovery-oriented trial formats from committed replenishment structures.
- Monthly Plans:Core revenue engine with predictable inventory planning and supplier volume commitments. Auto-renewing structures dominate US subscriber bases, though UK operators increasingly adopt one-click termination to reduce churn friction.
- Quarterly Plans:Lower-commitment entry points capturing gift purchasers and seasonal trialists. Explicit expiration dates reduce subscriber service costs compared to cancellation-managed monthly formats.
- Customizable Boxes:Preference-engine curation displacing static rotations in retention-sensitive segments.
- Gift Subscriptions:Holiday-weighted revenue with minimal post-purchase engagement requirements.
Monthly Plans sustain the revenue base. Customizable Boxes are climbing the fastest as algorithmic curation matures.
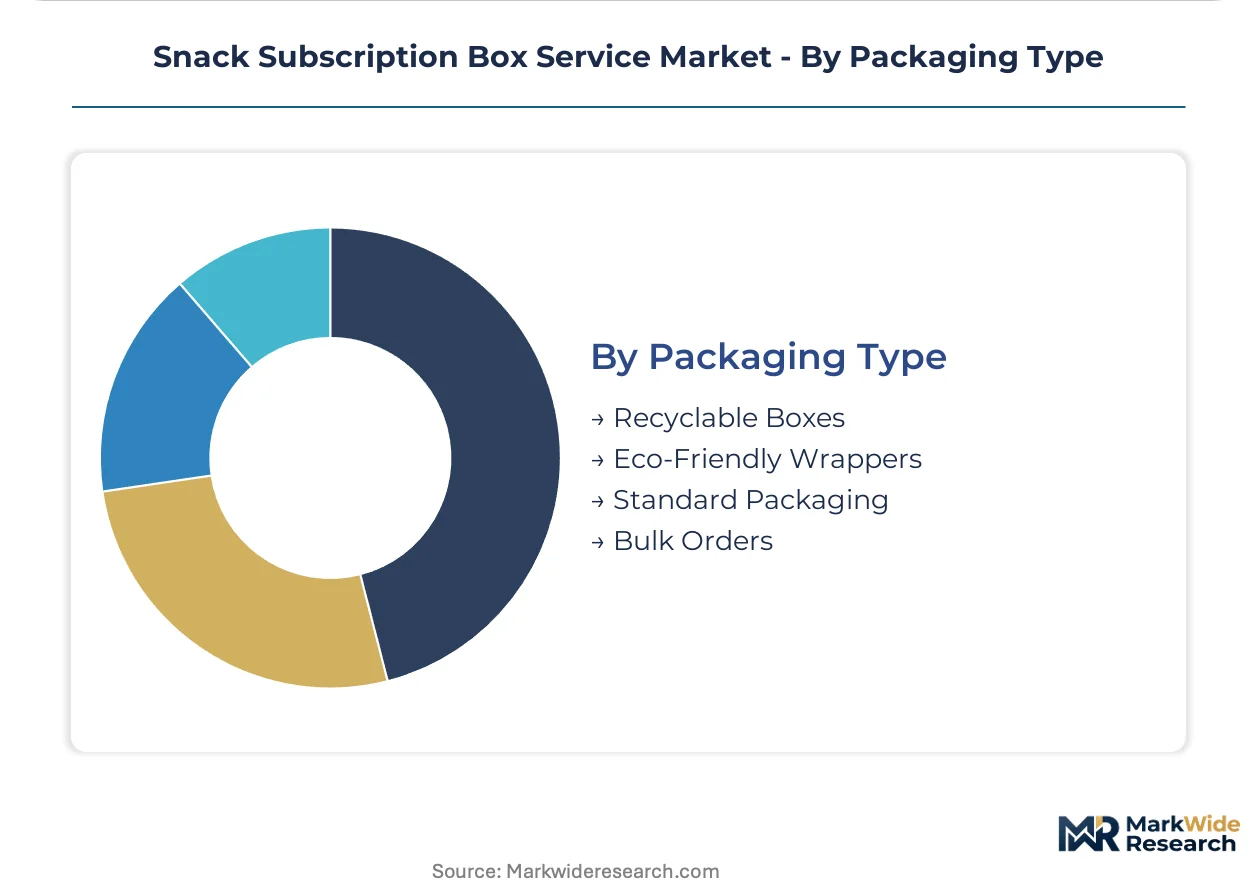
Packaging Type:
Margin pressure from regulatory compliance costs stratifies competitive position by operational scale.
- Recyclable Boxes:Post-consumer recycled content mandates in California and New York force material transitions. Integrated operators with captive packaging operations absorb reformulation costs more efficiently than mid-tier curators sourcing third-party.
- Eco-Friendly Wrappers:Compostable barrier films and soy-based inks addressing extended producer responsibility frameworks. Small-to-mid-tier curators face disproportionate per-unit compliance expenses versus scaled competitors.
- Standard Packaging:Legacy polypropylene and corrugated formats retaining cost advantage in price-sensitive segments.
- Bulk Orders:Reduced per-unit packaging intensity for high-volume B2B and family-tier subscribers.
Standard Packaging retains volume leadership. Eco-Friendly Wrappers show the steepest adoption trajectory as EPR deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z households concentrate in coastal metropolitan areas, with suburban family units driving volume in secondary markets. Regulatory fragmentation across jurisdictions creates divergent compliance cost structures for operators.
United States
Health Enthusiasts in California and Pacific Northwest metropolitan areas anchor premium-tier subscription demand. FDA nutrition labeling mandates compress supplier qualification timelines for organic SKU sourcing. Los Angeles and San Francisco Bay Area logistics clusters enable rapid fulfillment cycle optimization.
United Kingdom
London metropolitan households show highest sensitivity to cancellation friction, prompting one-click termination interface adoption. The UK plastic packaging tax accelerates fiber-based insert transitions among sustainability-positioned operators. Midlands distribution hubs handle cross-border European fulfillment for Western snack assortments.
Japan
Tokyo and Osaka metropolitan households drive rising trial rates for Western flavor profile assortments. METI circular economy guidelines shape packaging material specifications for imported snack subscriptions. Kanto region localization partnerships with domestic distributors reduce customs clearance friction.
Germany
Berlin and Munich urban clusters exhibit strong demand for algorithmic curation with explicit organic certification. ECHA REACH compliance requirements extend documentation burdens for non-EU snack suppliers. Bavaria-based organic food distributors expand procurement network capacity for subscription operators.
Canada
Toronto and Vancouver metropolitan areas concentrate health-focused subscriber acquisition with employer wellness benefit integrations. Health Canada nutrition labeling requirements parallel FDA frameworks, easing cross-border supplier qualification. Ontario distribution centers leverage moisture-control packaging for extended Prairie Provinces reach.
Snack Subscription Box Service Market Competitive Landscape
Player mix skews toward wellness-focused curators and international variety specialists competing on distinct value vectors. Market structure exhibits tiered consolidation with scaled operators absorbing disproportionate regulatory compliance costs. Strategic archetypes separate organic certification depth players from velocity-driven international rotation specialists. Dominant competitive moves center on supplier network exclusivity arrangements and predictive curation algorithm deployment.
Within the wellness-focused curation tier, NatureBox and UrthBox exemplify archetype positioning through certified organic SKU depth and established supplier verification networks. Japan Crate occupies a position representing international variety velocity with country-themed assortment rotation. MunchPak sits within the global discovery segment, anchoring competitive positioning through faster regional flavor profile turnover than domestic rivals.
| Leading Market Players |
|---|
| UrthBox |
| Japan Crate |
| NatureBox |
| SnackCrate |
| Universal Yums |
| Vegancuts Snack Box |
| MunchPak |
| Jerky Snob |
| Mantry |
| Others |
Pricing and Supply Chain Analysis
Compostable barrier films replacing conventional polypropylene linings simultaneously relocate packaging sourcing from Midwest converters to California fiber-specialist facilities and compress per-unit material economics for mid-tier curators. This substitution dynamic forces operators to absorb reformulation costs or pass through premiums to subscribers.
Pricing Analysis
Cost-plus contracts indexed to California almond and organic dried fruit commodity benchmarks dominate supplier agreements. Three-tier pricing structure across USDA Organic premium, Non-GMO Project verified standard, and conventional economy levels separates subscriber segments. Pricing pressure stems from Pacific Northwest supplier concentration and FDA nutrition labeling compliance extensions. Students exhibit highest price sensitivity, while Health Enthusiasts accept premium positioning for certified assortments.
Supply Chain Analysis
Port of Long Beach container clearance chokepoints constrain inbound specialty ingredient flows from Japan and South Korea. Domestic organic snack manufacturing clusters in California, Oregon, and Washington State. Raw material dependencies center on California tree nuts, Pacific Northwest dried fruits, and imported savory flavorings. Single-source vulnerability concentrates in organic certification bodies with 14-18 week verification cycles. Distribution runs through Los Angeles and San Francisco Bay Area logistics clusters for West Coast fulfillment, with Midwest distribution emerging for Prairie Provinces reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward subscriber cohorts as pause-flexible plans and one-click cancellation interfaces fragment retention economics. This fragmentation concentrates price sensitivity among urban Millennial households.
For Market Incumbents: Compound supplier network exclusivity arrangements around USDA Organic certified Pacific Northwest manufacturers to preempt emerging curator competition. Deepen backward integration into captive moisture-control packaging operations before California EPR mandates tighten. Lock in multi-year organic commodity offtake agreements to defend margin position against input cost volatility.
For New Entrants and Emerging Players: Lead with algorithmic curation capabilities targeting Japanese metropolitan households where Western snack trial rates are climbing fastest. Exploit localization partnership gaps in Tokyo and Osaka distribution networks. Position through employer wellness benefit integrations as the primary B2B2C acquisition channel.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scaled operators with captive compliance infrastructure over mid-tier curators facing disproportionate EPR reformulation costs. Long-term viability hinges on predictive curation algorithm ownership and fiber-based packaging transition completion. Target acquisition archetypes include wellness-focused curators with established Non-GMO Project verification networks. Monitor California post-consumer recycled content mandate enforcement as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Curation Deployment | Machine learning recommendation engines displace static rotations in retention-sensitive Health Enthusiast segments. |
| Fiber-Based Packaging Transition | California EPR compliance deadlines force soy-based ink and compostable barrier film adoption before penalty structures activate. |
| Employer Wellness Integration | Human resources platforms embedding subscription allowances create defensible B2B2C acquisition paths with lower churn. |
| Localization Partnership Expansion | Domestic distributor alliances in Japan reduce customs friction and accelerate Western snack assortment trial velocity. |
| Supplier Exclusivity Arrangements | Locked organic certification pipelines with Pacific Northwest manufacturers raise competitive barriers for emerging curators. |
Research Methodology
Initial hypotheses were tested against primary input from subscription operations executives, organic certification specialists, retail category buyers, and third-party logistics coordinators and refined through secondary validation. Primary fieldwork combined structured interviews with warehouse management platform vendors and procurement leads at fiber-based packaging converters. Secondary sources included FDA nutrition labeling guidance documents, California Department of Resources Recycling and Recovery packaging mandate filings, USDA Organic certification databases, and customs records for specialty ingredient imports. Bottom-up subscriber cohort modeling and top-down market sizing triangulated volume estimates.
Variance decomposition across product type, target audience, subscription model, and packaging format dimensions anchored the analytical framework. CAGRs were derived from segment-level growth trajectory analysis over the projection horizon. Forecast inputs incorporated organic commodity price index movements, EPR compliance timeline assumptions, and algorithmic curation adoption curves among Health Enthusiast subscribers.
Forecasts assume regulatory continuity in FDA nutrition labeling regimes and California extended producer responsibility frameworks; material policy shifts would require re-modeling. Specific risk factors include Pacific Northwest agricultural yield disruption, Non-GMO Project verification cycle extensions, and UK plastic packaging tax rate adjustments. Practitioners should keep alternative scenarios live as state-level packaging mandates and subscriber fatigue patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Oman Food Service Market
Food Service
Malaysia Food Service Market
Food Service
Commercial Pizza Oven Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Food Truck Services Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
United States Food Truck Market
Food Service
Charbroiler Market
Food Service
Switzerland Food Service Market
Food Service
Hospital Food Services Market
Food Service
Limited-Service Restaurants Market
Food Service
New Zealand Foodservice Market
Food Service
Food and Grocery Retail Market
Food Service
Portion Cups Market
Food Service
China Food Service Market
Food Service
India Foodservice Market